
 Electrophoresis Market | 2026-2036
Electrophoresis Market Size, Share, and Industry Trends Forecast 2026-2036
Electrophoresis Market Analysis
ISO 17025 laboratory accreditation is unwinding competitive access for electrophoresis equipment suppliers, particularly in clinical and pharmaceutical testing environments. Thermo Fisher Scientific leverages its vertical integration across reagents, instruments, and software to sustain pricing power in capillary electrophoresis systems. Bio-Rad Laboratories anchors its position through dense distribution networks in academic research channels. Danaher Corporation competes via operational discipline and recurring consumables revenue across its life sciences portfolio.
Electrophoresis separates charged macromolecules—DNA, RNA, proteins—through porous gel matrices or capillary channels under applied electric fields, with resolution thresholds reaching single-base-pair discrimination in sequencing workflows. Capillary electrophoresis leads instrument value pools due to automation demands in clinical diagnostics, while microfluidic platforms represent the fastest-expanding segment as point-of-care and lab-on-chip architectures displace manual gel workflows. Gel electrophoresis remains mature and cost-dominant in academic teaching laboratories, though margin compression limits supplier investment there.
FDA analytical method validation guidelines and EPA Good Laboratory Practice standards shape instrument procurement criteria, particularly for pharmaceutical quality control and environmental toxicology applications. ISO 13485 medical device quality management adds compliance overhead for manufacturers targeting in-vitro diagnostic integrations. Stakeholders must monitor how CRISPR-based quality control assays and mass spectrometry convergence alter the functional boundary of electrophoresis in nucleic acid analysis workflows.
Market Dynamics
Capillary electrophoresis automation is compressing manual gel workflows as pharmaceutical quality control demands tighten instrument validation protocols under FDA guidance updates. This technology shift concentrates procurement power among large biologics manufacturers while squeezing academic channel margins.
Growth Catalysts
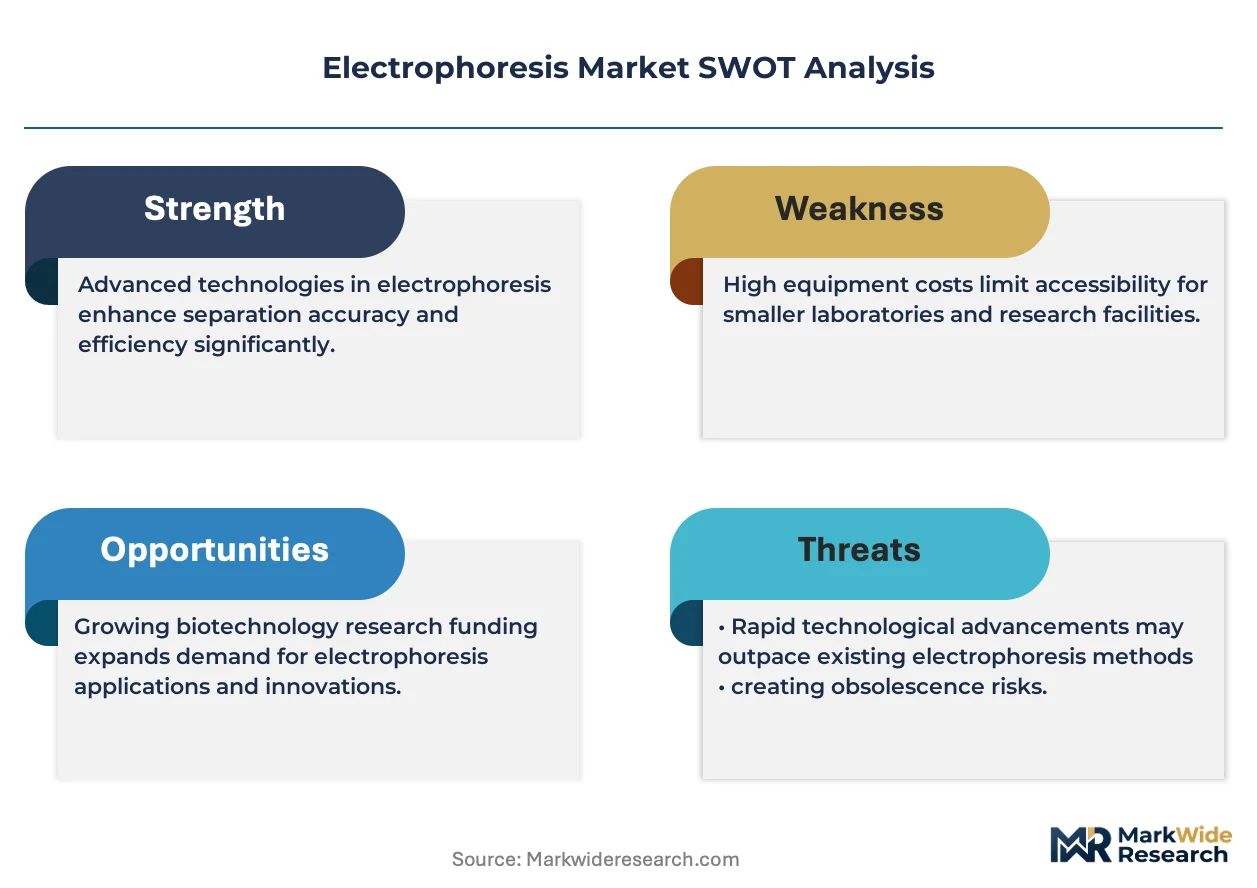
- Biologics QC expansion:FDA's updated analytical procedures guidance for biotech products mandates enhanced nucleic acid purity verification, forcing pharmaceutical manufacturers to upgrade electrophoresis infrastructure.
- ISO 17025 accreditation wave:Clinical and pharmaceutical testing laboratories across Germany, the United States, and Japan pursue formal accreditation, filtering equipment procurement toward validated system suppliers.
- CRISPR quality control integration:Gene editing workflows require single-base-pair resolution for guide RNA validation, pulling high-sensitivity capillary systems into synthetic biology manufacturing.
Market Restraints
- Helium supply volatility:Capillary electrophoresis systems depend on helium as a carrier gas, with price spikes and allocation disruptions from Qatar and Algeria constraining operational continuity.
- Mass spectrometry substitution:Proteomics laboratories in the United States and Switzerland increasingly bypass electrophoretic separation for direct mass-based protein characterization, eroding addressable demand in high-value segments.
- ISO 13485 compliance overhead:Medical device quality management certification adds 18-24 month validation timelines for manufacturers targeting in-vitro diagnostic integrations, delaying revenue recognition.
Strategic Opportunities
- Point-of-care microfluidics:Lab-on-chip architectures for infectious disease testing at decentralized clinics in India and Brazil bypass infrastructure constraints of central laboratory models.
- EU Green Deal solvent restrictions:REACH-regulated reduction in hazardous gel reagents creates demand for aqueous buffer systems and closed-loop capillary platforms with lower environmental liability.
- AI-assisted pattern recognition:Machine learning integration with electrophoretic output analysis automates band calling and anomaly detection, opening service revenue streams for instrument vendors.
Industry Challenges
- Electrophoresis-mass spectrometry interface standardization:Lack of unified data formats between separation output and downstream mass detection complicates workflow integration for proteomics service providers.
- Capillary coating reproducibility:Batch-to-batch variation in fused silica surface chemistry degrades migration time precision, requiring extensive in-house validation that strains quality assurance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrophoresis Market |
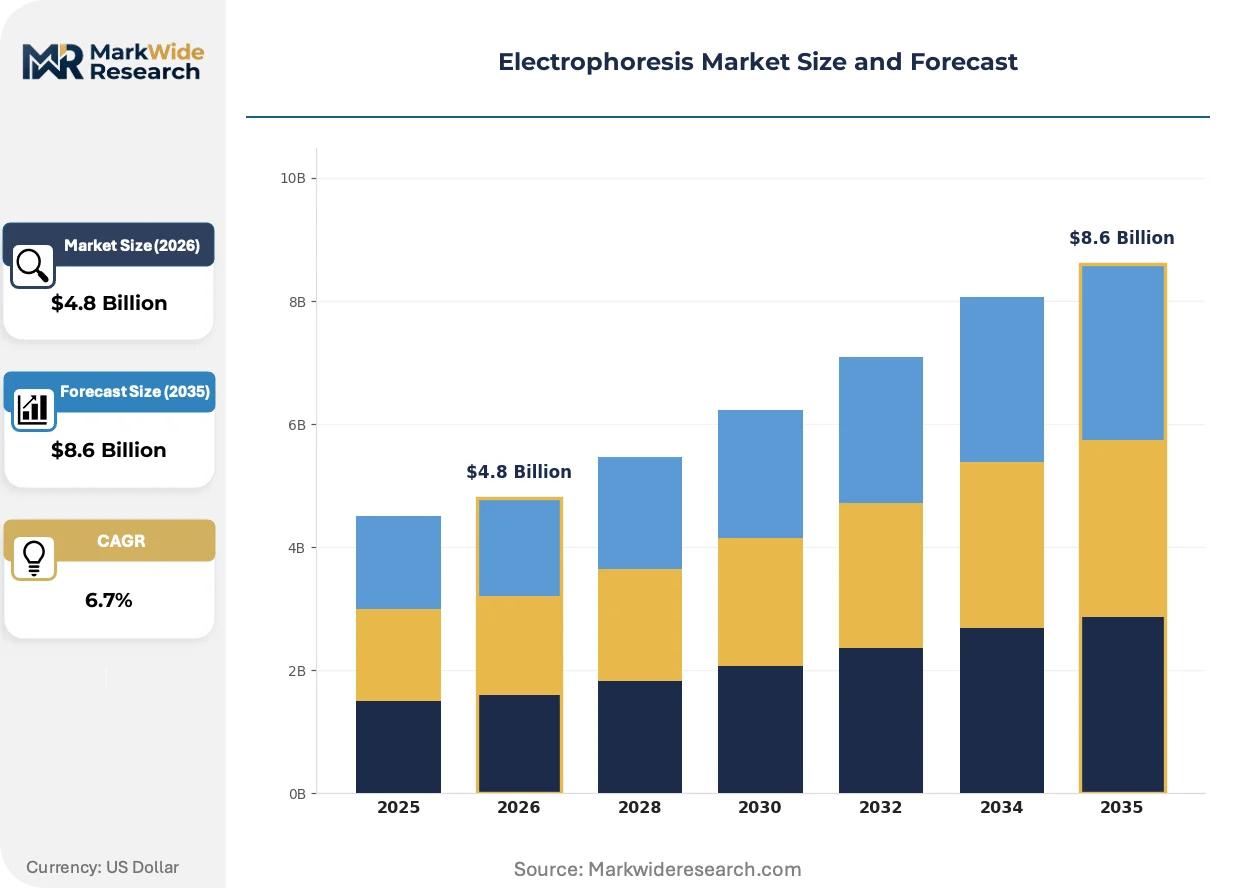
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Capillary, Microfluidic Technology: Gel Electrophoresis, Capillary Electrophoresis, Pulse Field Electrophoresis, Free Flow Electrophoresis End User: Pharmaceuticals, Academic Research, Clinical Laboratories, Biotechnology Application: DNA Analysis, Protein Analysis, RNA Analysis, Quality Control |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., Danaher Corporation, Agilent Technologies, Inc., Merck KGaA, GE HealthCare Technologies Inc., PerkinElmer, Inc., QIAGEN N.V., Lonza Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrophoresis Market Emerging Trajectories
Microfluidic electrophoresis platforms are fragmenting the traditional instrument-reagent bundling model as point-of-care deployment demands disposable cartridge architectures. This shift reconfigures supplier economics toward consumables volume and away from capital equipment margins.
Lab-on-chip electrophoresis is displacing manual gel workflows in clinical diagnostics as hospital laboratories automate nucleic acid fragment analysis for pharmacogenomic testing. Mid-sized health systems in the United States and Germany accelerate adoption to reduce technician hands-on time and standardize result reporting. The displacement compresses reagent revenue for traditional gel suppliers while redirecting procurement budgets toward integrated cartridge platforms with locked-in consumables.
EPA Good Laboratory Practice standards for environmental toxicology are tightening documentation requirements for electrophoretic separation data in agrochemical safety studies. Contract research organizations must implement 21 CFR Part 11-compliant electronic records systems, raising competitive barriers for smaller testing facilities. Environmental testing laboratories in California and the Netherlands respond by consolidating instrument vendors to simplify validation protocols and audit trails.
Pharmaceutical quality control teams increasingly unbundle after-sales service contracts from initial instrument purchases, preferring third-party maintenance providers or in-house bioengineer staffing. Large molecule manufacturers in Massachusetts and Basel negotiate multi-year service agreements separately from capital procurement, pressuring OEM service margins. This behavioral shift is most pronounced among biologics producers with internal metrology groups capable of independent calibration and troubleshooting.
Electrophoresis Market Segmentation
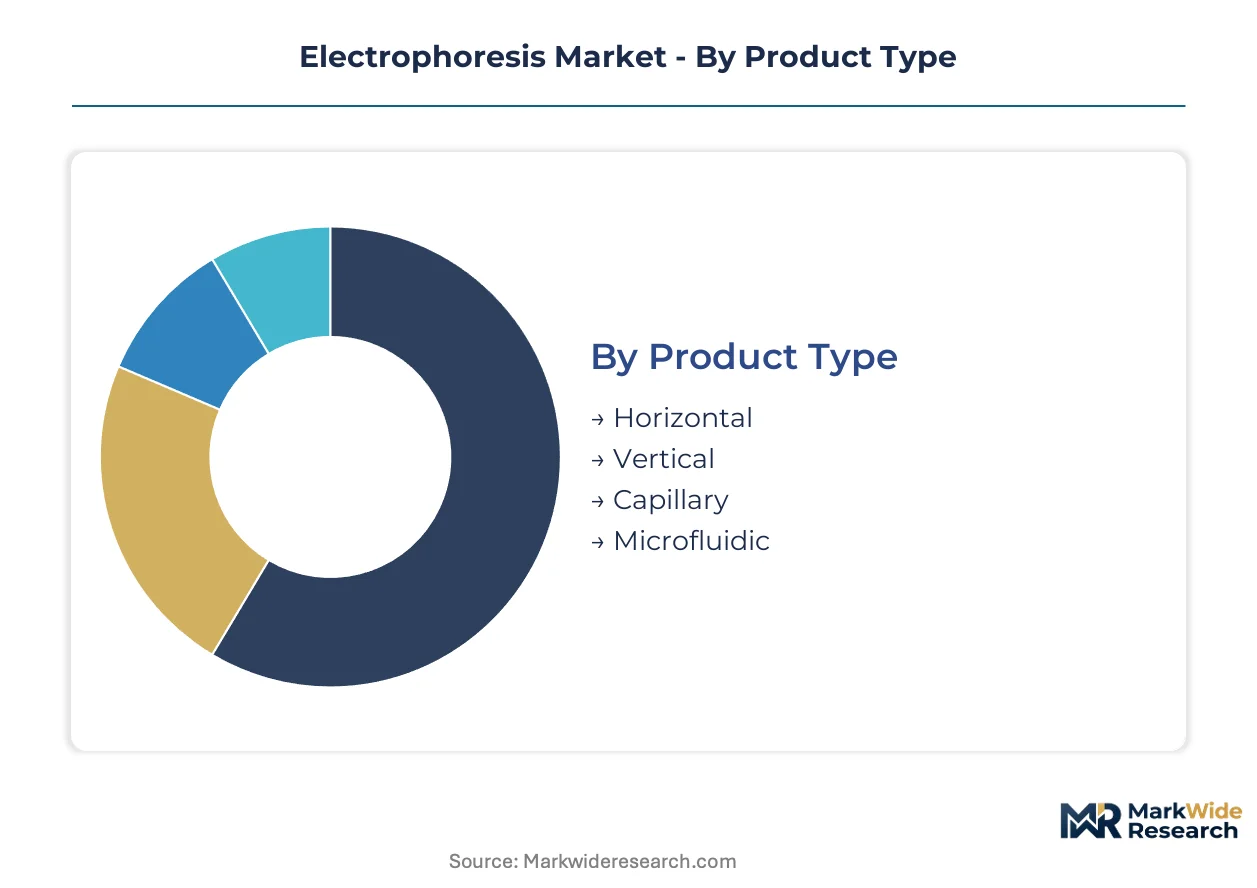
Electrophoresis market segmentation reveals divergent vulnerability to mass spectrometry substitution and microfluidic displacement across product architectures. Understanding these pressure gradients helps suppliers allocate R&D resources and defend pricing power in threatened versus resilient categories.
Product Type:
Substitution pressure intensifies from manual gel systems toward automated capillary and microfluidic platforms as pharmaceutical quality control demands tighten validation protocols under FDA guidance updates.
- Capillary:Automated separation through narrow fused silica columns delivers single-base-pair resolution for nucleic acid fragment sizing. Large biologics manufacturers in Massachusetts and Basel concentrate procurement here to meet FDA analytical method validation requirements for biotech product release.
- Microfluidic:Lab-on-chip architectures integrate sample preparation, separation, and detection into disposable cartridge formats. Point-of-care deployment in decentralized Indian and Brazilian clinics drives steepest expansion as these systems bypass central laboratory infrastructure constraints.
- Horizontal:Submarine gel configurations dominate academic teaching laboratories for routine DNA fragment separation.
- Vertical:Slab gel systems with discontinuous buffer chambers serve protein separation workflows in research settings.
Capillary systems anchor the volume base while microfluidic platforms gain share at the steepest rate.
Technology:
Cost tier stratification separates mature gel methods from premium automated alternatives, with capital intensity and consumables bundling determining customer access patterns.
- Capillary Electrophoresis:Electric field-driven separation through solution-filled capillaries replaces gel matrices with liquid-phase buffers. Clinical diagnostics laboratories in the United States and Germany prioritize this technology to reduce technician hands-on time and standardize pharmacogenomic test reporting.
- Gel Electrophoresis:Porous matrix separation remains cost-dominant in academic channels despite margin compression. Research universities across Japan and the United Kingdom maintain installed bases for undergraduate training and low-throughput screening.
- Pulse Field Electrophoresis:Alternating orthogonal electric fields enable large DNA molecule separation for microbial genotyping.
- Free Flow Electrophoresis:Continuous buffer stream separation supports preparative protein fractionation in proteomics workflows.
Gel electrophoresis retains the broadest installed base while capillary electrophoresis expands most quickly in regulated pharmaceutical environments.
End User:
Customer type determines procurement authority concentration, with centralized biologics manufacturers wielding greater negotiating leverage than fragmented academic purchasers.
- Pharmaceuticals:Quality control teams at large molecule manufacturers enforce stringent instrument validation under FDA and EMA guidelines. These buyers unbundle service contracts from capital purchases, pressuring OEM maintenance margins through third-party provider preferences.
- Academic Research:University laboratories and government research institutes prioritize capital cost minimization over throughput. Funding constraints from NIH and NSF grant cycles in the United States delay instrument refresh rates compared to commercial sectors.
- Clinical Laboratories:Hospital-based testing facilities pursue ISO 17025 accreditation to standardize nucleic acid analysis workflows.
- Biotechnology:Synthetic biology startups and CRISPR service providers demand high-sensitivity systems for guide RNA validation.
Pharmaceutical end users dominate revenue concentration while biotechnology segments climb the fastest on gene therapy manufacturing expansion.
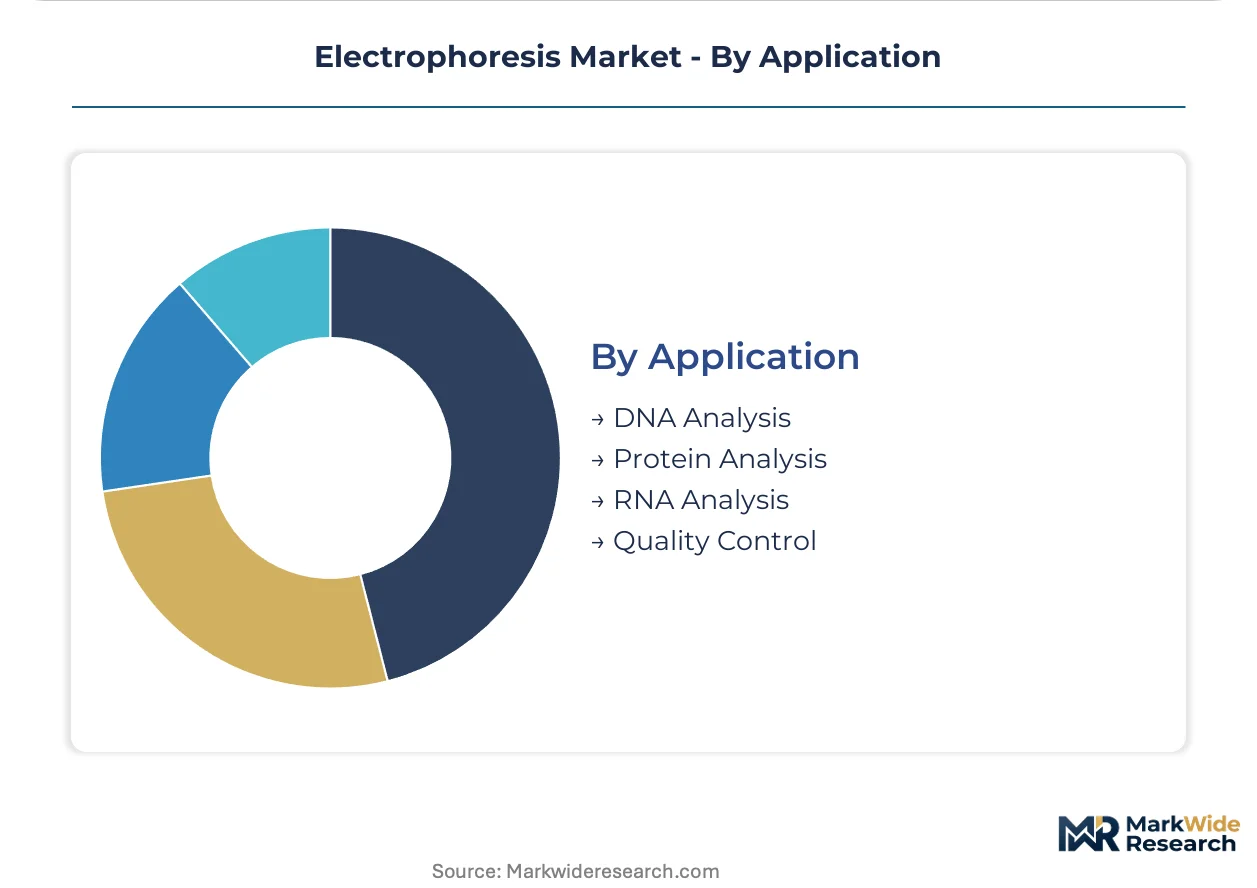
Application:
Application maturity varies by analytical target, with protein analysis facing strongest mass spectrometry substitution while nucleic acid applications retain electrophoresis dominance.
- DNA Analysis:Fragment sizing, genotyping, and sequencing quality control constitute the largest addressable use case. Sanger sequencing validation and CRISPR guide RNA characterization in synthetic biology manufacturing sustain instrument demand despite next-generation sequencing displacement of some preparatory workflows.
- Quality Control:Biologics release testing for nucleic acid contamination and purity verification commands premium pricing. FDA updated guidance on analytical procedures for biotech products mandates enhanced verification protocols, forcing infrastructure upgrades among contract manufacturers.
- Protein Analysis:SDS-PAGE and native gel methods face erosion from direct mass spectrometry characterization in proteomics service laboratories.
- RNA Analysis:Northern blotting and fragment analysis supports gene expression studies and mRNA therapeutic quality assessment.
DNA analysis anchors the volume base while quality control applications gain share at the steepest rate on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Boston's life sciences logistics corridor underwrites Massachusetts' dominance in biologics manufacturing infrastructure. Precision medicine clusters in Basel and Singapore rely on temperature-controlled supply chains anchored at EuroAirport and Changi Airport respectively.
United States
Massachusetts and California concentrate biologics quality control demand from gene therapy manufacturers. FDA updated guidance on analytical procedures for biotech products mandates enhanced nucleic acid purity verification protocols. Greater Boston hosts contract manufacturers upgrading capillary electrophoresis infrastructure to meet release testing standards for mRNA therapeutics.
Germany
Pharmaceutical testing laboratories in Baden-Württemberg and Bavaria pursue ISO 17025 accreditation for nucleic acid analysis workflows. REACH-regulated reduction in hazardous gel reagents accelerates aqueous buffer system adoption. The Rhine-Main cluster around Frankfurt consolidates procurement toward validated capillary platforms with simplified audit trails.
Japan
PMDA quality standards for regenerative medicine products drive instrument validation requirements at Osaka and Tokyo manufacturing sites. METI funding for precision medicine infrastructure supports academic-industrial collaboration on automated separation systems. The Kansai biocluster expands capillary electrophoresis deployment for cell therapy quality control.
Switzerland
Roche and Novartis manufacturing operations in Basel anchor European demand for high-sensitivity separation systems. Swissmedic guidance on biologics characterization tightens migration time precision requirements. The Basel-based precision medicine corridor concentrates procurement power among large molecule manufacturers negotiating unbundled service contracts.
India
CDSCO regulations for biosimilar approval create quality control infrastructure demand at Hyderabad and Bangalore manufacturing parks. PLI scheme incentives for pharmaceutical production attract contract research organizations building analytical capabilities. The Genome Valley cluster expands electrophoresis capacity for oligonucleotide therapeutic manufacturing.
Electrophoresis Market Vendor Landscape
Listed leaders compete with private specialists across instrument-reagent bundling strategies. The market exhibits moderate consolidation with three dominant platform suppliers controlling premium capillary segments while regional distributors fragment gel system sales. Strategic archetypes include full-stack integrators spanning reagents through software, consumables-dependent platform vendors, and precision component specialists. M&A activity concentrates on microfluidic cartridge technology acquisitions and third-party service provider roll-ups.
Among US-based life sciences conglomerates, Thermo Fisher Scientific Inc. exemplifies the full-stack archetype through captive supply of separation chemistries. Bio-Rad Laboratories, Inc. anchors academic channel positioning with dense distribution networks. Danaher Corporation occupies the operational excellence tier with recurring consumables revenue models across its life sciences portfolio.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| Danaher Corporation |
| Agilent Technologies, Inc. |
| Merck KGaA |
| GE HealthCare Technologies Inc. |
| PerkinElmer, Inc. |
| QIAGEN N.V. |
| Lonza Group Ltd. |
| Others |
Supply Flow & Price Mechanics
Helium-to-hydrogen carrier gas substitution in capillary electrophoresis systems simultaneously redraws supply geography toward hydrogen electrolysis hubs in Germany and Japan while compressing operating economics for laboratories locked into legacy helium contracts. This input transition concentrates procurement leverage among instrument vendors with modular gas compatibility while stranding buyers with inflexible installed bases.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical manufacturers purchasing multi-system contracts from academic laboratories buying single units. Pricing stratifies across premium capillary platforms with FDA validation documentation, standard benchtop systems for clinical ISO 17025 laboratories, and economy gel configurations for teaching environments. Cost compression in the economy tier intensifies as microfluidic disposables erode reagent revenue from traditional gel suppliers. Academic purchasers exhibit highest price sensitivity due to NIH and NSF funding volatility, while biologics manufacturers prioritize validation certainty over unit cost.
Supply Chain Analysis
Inventory lead times for fused silica capillaries and specialized gel chemistries stretch from six to fourteen weeks depending on coating complexity and batch validation requirements. Manufacturing concentrates in Germany, the United States, and Japan for precision capillary fabrication, while China dominates basic gel matrix production. Raw material dependencies include high-purity quartz sand, acrylamide monomers, and helium or hydrogen carrier gases. Single-source vulnerability sits with helium suppliers from Qatar and Algeria. Distribution runs through authorized distributors for academic channels and direct OEM relationships for pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care microfluidic expansion represents early-cycle penetration as decentralized clinics in India and Brazil bypass central laboratory infrastructure constraints. This tailwind sustains instrument demand even as mature markets approach saturation in academic gel workflows.
For Market Incumbents: Fortify consumables lock-in through cartridge-based microfluidic architectures that embed proprietary reagent chemistries. Deepen backward integration into high-purity fused silica manufacturing to secure capillary supply against coating reproducibility batch failures. Defend against mass spectrometry substitution in proteomics by emphasizing electrophoresis-mass spectrometry interface standardization investments.
For New Entrants and Emerging Players: Anchor in the CRISPR quality control segment where synthetic biology manufacturers demand single-base-pair resolution for guide RNA validation. Target service unbundling opportunities as large biologics manufacturers in Massachusetts and Basel prefer third-party maintenance over OEM contracts. Pursue AI-assisted pattern recognition software licensing as a lower-capital entry path than hardware manufacturing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed microfluidic cartridge specialists seeking scale partnerships or strategic exits. Five-to-ten year viability hinges on point-of-care infectious disease testing penetration in emerging markets. Monitor helium supply stabilization and hydrogen retrofit adoption rates as inflection indicators for capillary system competitive dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Cartridge Platform Launch | Disposable architectures capture recurring revenue from decentralized clinics in India and Brazil. |
| ISO 17025 Validation Documentation Investment | Pre-qualification packages accelerate procurement decisions at German and Japanese clinical laboratories. |
| Helium-to-Hydrogen Retrofit Program | Gas flexibility insulates pharmaceutical customers from Qatar supply allocation disruptions. |
| AI Pattern Recognition Software Licensing | Machine learning band calling opens service revenue streams without capital equipment manufacturing. |
| Third-Party Service Provider Acquisition | Roll-up strategies capture margin pools as biologics manufacturers unbundle OEM maintenance contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical quality control directors, clinical laboratory managers, academic research principal investigators, and electrophoresis instrument product managers. Secondary validation drew from FDA analytical procedure guidance documents, EPA Good Laboratory Practice standards, ISO 17025 accreditation registries, and EMA biologics characterization guidelines. Bottom-up triangulation across installed base estimates and consumables throughput combined with top-down cross-checks against pharmaceutical capital expenditure disclosures.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product architecture, technology tier, end-user concentration, and application maturity. Segmentation dimensions included capillary versus microfluidic versus gel platform types, pharmaceutical versus academic versus clinical customer channels, and DNA analysis versus protein analysis versus quality control use cases. CAGRs were derived from regression analysis of historical procurement patterns and regulatory-driven infrastructure replacement cycles. Industry-specific inputs encompassed helium price volatility indices, ISO 13485 certification timelines, and CRISPR manufacturing facility buildout announcements.
Material uncertainties — helium supply disruptions, mass spectrometry substitution acceleration, and REACH-regulated gel reagent phase-outs — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and biologics manufacturing expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Biobank Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Global Qpcr Reagents Market