
 Non-Animal Alternative Testing Market | 2026-2036
Non-Animal Alternative Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Animal Alternative Testing Market Analysis
Project finance partnerships between biotech tool developers and contract research organizations is reconfiguring capital deployment across the competitive landscape. Thermo Fisher Scientific leverages its reagent manufacturing scale to anchor supply agreements with multinational pharmaceutical clients. Lonza Group specializes in custom assay development, sustaining premium positioning through deep integration with academic research networks. MIMETAS competes in organ-on-a-chip applications, occupying a defensible niche in microfluidic platform design for toxicology screening.
Non-animal alternative testing encompasses in vitro cell-based assays, engineered tissue models, and computational toxicology platforms that replicate human physiological responses without vertebrate subjects. These systems typically employ primary human cells, induced pluripotent stem cell derivatives, or organoid structures maintained under perfusion conditions to assess compound safety, efficacy, or mechanistic pathways. In Vitro Testing and 3D Cell Cultures command the largest current revenue share, reflecting mature protocols and broad regulatory acceptance across cosmetics and pharmaceutical applications. Microfluidics represents the fastest-expanding technology segment, as integrated organ-on-chip architectures enable multi-organ interaction modeling that static well-plate formats cannot replicate. Pharmaceutical Firms and Contract Research Organizations concentrate the steepest procurement growth, driven by pipeline pressure to de-risk candidate molecules before costly clinical phases.
EMA's ban on animal testing for cosmetics ingredients, REACH registration requirements, and FDA's Modernization Act 2.0 provisions collectively reshape validation standards and market access conditions for assay providers. These frameworks compel technology developers to generate human-relevant data packages that satisfy multiple jurisdictional review pathways. ISO 10993 biocompatibility standards and OECD Test Guidelines further harmonize acceptance criteria, reducing fragmentation in cross-border product registration. Stakeholders must monitor evolving regulatory equivalence determinations between organ-chip readouts and legacy animal study endpoints to anticipate which platforms achieve formal substitution status.
Market Dynamics
Microfluidic organ-on-chip platforms are compressing validation timelines for pharmaceutical toxicology, forcing legacy assay providers to retool manufacturing footprints or surrender contract volumes to integrated platform specialists.
Growth Catalysts
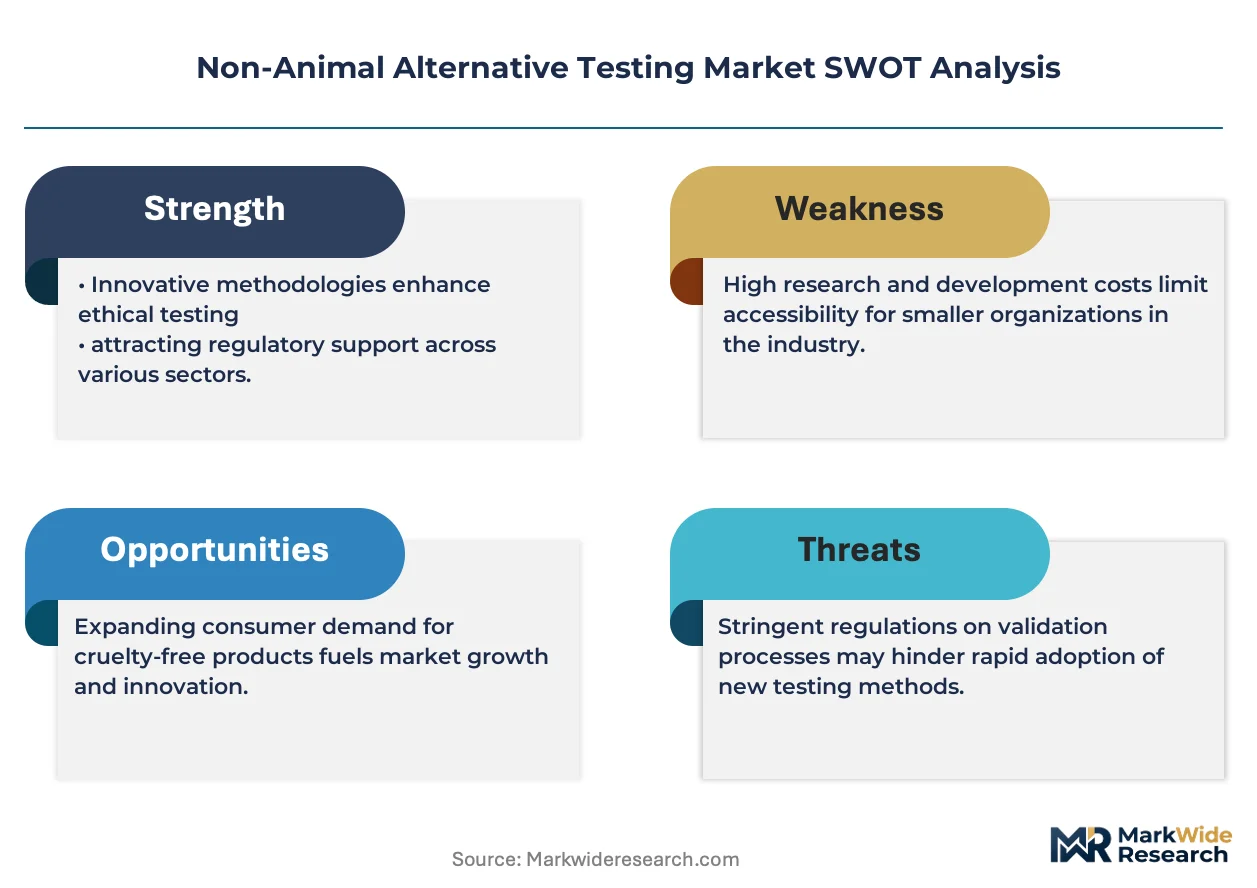
- REACH registration mandates:ECHA's tiered data requirements for chemical safety assessments channel industrial chemical producers toward validated in vitro methods for skin sensitization and eye irritation endpoints.
- Induced pluripotent stem cell maturation:Protocol refinements enabling hepatocyte-like functionality from patient-derived iPS lines expand disease-modeling applications for rare genetic disorders.
- Cosmetics formulators:Clean beauty positioning in North American and European retail channels accelerates demand for cruelty-free certification packages that exclude vertebrate testing.
Market Restraints
- Primary human tissue scarcity:Donor variability and cold-chain logistics inflate input costs for physiologically relevant hepatocyte and cardiomyocyte assays.
- Reagent supply concentration:Specialized growth factor and extracellular matrix production clusters in Switzerland and Germany create vulnerability to export licensing delays.
- Cross-platform standardization gaps:Absence of harmonized reference materials between microfluidic chip architectures complicates multi-site validation studies.
Strategic Opportunities
- India's pharmaceutical export sector:CDSCO alignment with ICH M3(R2) guidelines creates openings for Western assay providers to support ANDA submissions with non-animal pharmacokinetic data.
- Bioprinted tumoroid co-cultures:Immuno-oncology pipeline expansion drives demand for patient-matched stromal-immune-tumor models that static spheroids cannot replicate.
- FDA Modernization Act 2.0 implementation:Formal acceptance pathways for organ-chip submissions incentivize platform developers to build regulatory affairs capabilities ahead of guideline finalization.
Industry Challenges
- Microfabrication engineering talent:Scarcity of cross-trained professionals fluent in both cell biology and soft-lithography process development constrains platform scaling.
- Good Laboratory Practice certification timelines:OECD-compliant study audits for novel organ-chip endpoints extend 18-24 months, delaying revenue recognition for validated assay launches.
- Legacy LIMS integration:Data architecture mismatches between microfluidic sensor outputs and established pharmaceutical electronic data capture systems impede enterprise adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Animal Alternative Testing Market |
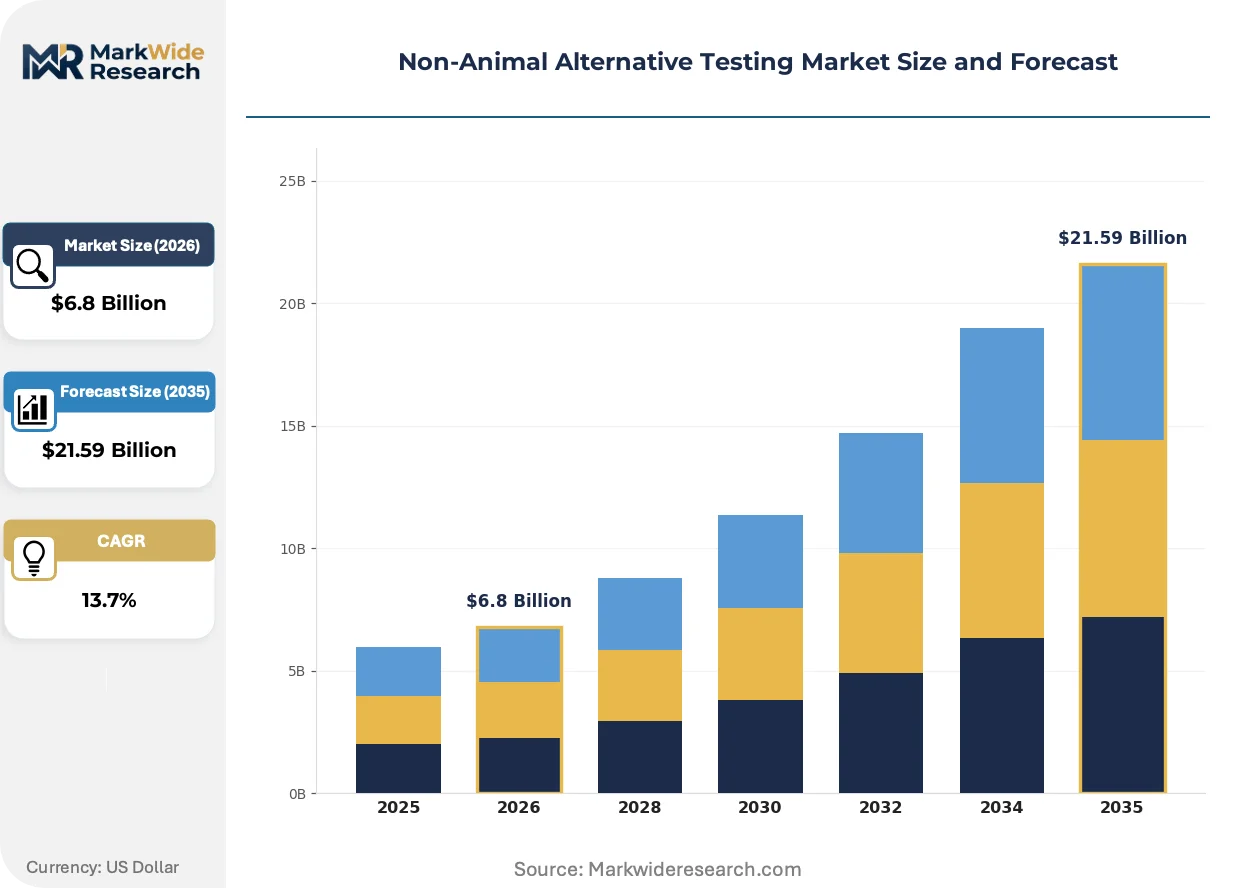
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: In Vitro Testing, Biomarkers, 3D Cell Cultures, Microfluidics Application: Cosmetics, Pharmaceuticals, Toxicology, Environmental Testing End User: Academic Institutions, Contract Research Organizations, Biotech Companies, Pharmaceutical Firms Product Type: Reagents, Assay Kits, Instruments, Software |
| Companies Covered | Emulate, VITROCELL Systems, TissUse, Thermo Fisher Scientific, Lonza Group, Merck, InSphero, MIMETAS, Evotec SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Animal Alternative Testing Market Emerging Trajectories
Computational-augmented biological modeling is collapsing the boundary between empirical observation and predictive simulation, redefining what constitutes acceptable evidence for regulatory decision-making across toxicology and efficacy assessment.
Artificial intelligence-driven toxicity prediction engines are digitizing the compound screening workflow. Pharmaceutical discovery groups deploy deep learning models trained on organ-chip transcriptomic outputs to flag mitochondrial dysfunction liabilities before physical synthesis. This compression of the design-test-learn cycle threatens fee-for-service contract research organizations dependent on wet-lab throughput.
EMA's 2023 qualification opinion for a kidney proximal tubule-on-chip model establishes precedent for organ-specific microphysiological systems achieving formal regulatory substitution status. Biotech tool developers now prioritize EMA parallel scientific advice pathways alongside FDA pre-submission meetings to accelerate dual-jurisdiction acceptance. European pharmaceutical sponsors lead in incorporating these qualified models into integrated nonclinical development plans.
Biopharmaceutical procurement teams unbundle after-sales technical support from reagent supply contracts, treating organ-chip platform training as a separate professional services category. This disintermediation pressures integrated vendors to demonstrate standalone educational value or cede implementation revenue to third-party consultancies. The pattern concentrates among mid-cap sponsors in the United States lacking internal microfluidics expertise.
Non-Animal Alternative Testing Market Segmentation
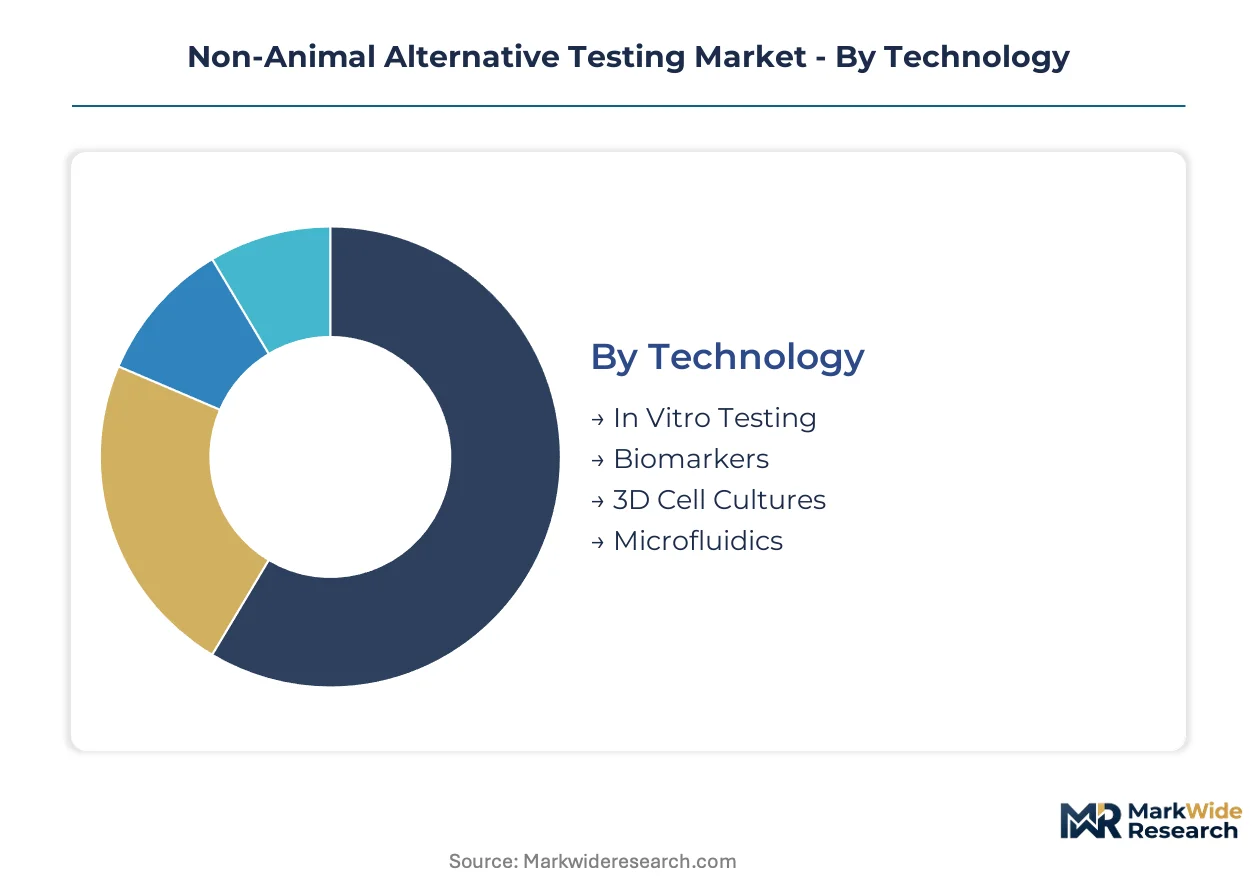
Technology platforms in non-animal testing serve distinct validation requirements across regulatory pathways. Application contexts determine which methods achieve formal substitution status versus supplementary data generation.
Technology:
Platform selection maps to the physiological complexity required for each safety endpoint.
- In Vitro Testing:Static well-plate assays using primary human cells or immortalized lines remain the workhorse for cytotoxicity and genotoxicity screening. Pharmaceutical toxicology groups in the United States deploy these methods for early candidate triage under FDA guidance on New Alternative Methodologies.
- 3D Cell Cultures:Spheroid and organoid architectures replicate tissue-level architecture absent in monolayer formats. European cosmetics formulators rely on reconstructed human epidermis models for skin sensitization assessments under ECHA REACH mandates.
- Microfluidics:Organ-on-chip systems enable perfusion and multi-organ interaction modeling. Contract research organizations in Germany and Switzerland are procuring these platforms fastest for integrated pharmacokinetic studies.
- Biomarkers:Protein and transcriptomic signatures quantify compound-induced stress responses. Toxicology screening programs incorporate these readouts for mechanistic liability classification.
The dominant share belongs to In Vitro Testing, while Microfluidics is expanding most quickly.
Application:
Regulatory pressure intensity varies sharply across end-use sectors.
- Pharmaceuticals:IND-enabling safety packages now integrate organ-chip data alongside legacy methods. FDA Modernization Act 2.0 provisions accelerate sponsor investment in qualified microphysiological systems for repeat-dose toxicity.
- Cosmetics:EMA's ban on animal testing for ingredients compels formulators to submit exclusively non-animal safety dossiers. Clean beauty positioning in French and German retail channels intensifies demand for cruelty-free certification.
- Toxicology:Industrial chemical producers face tiered data requirements under REACH registration timelines. Skin corrosion and serious eye damage endpoints now default to validated in vitro methods.
- Environmental Testing:Aquatic ecotoxicity assessments increasingly deploy fish embryo assays and computational models. Regulatory agencies in Japan and Canada are evaluating these approaches for pesticide registration.
Pharmaceuticals command the largest procurement volume, though Cosmetics exhibits the steepest regulatory-driven conversion rate.
End User:
Customer sophistication determines platform adoption sequencing.
- Pharmaceutical Firms:Internal discovery groups build dedicated microfluidics capabilities to de-risk candidates before CRO handoff. Pipeline pressure to compress timelines drives direct technology acquisition.
- Contract Research Organizations:Fee-for-service providers retool manufacturing footprints to capture organ-chip validation contracts. GLP certification for novel endpoints extends competitive moats.
- Academic Institutions:University labs generate qualification data packages supporting regulatory acceptance. NIH and EU Horizon funding concentrates on disease-modeling applications.
- Biotech Companies:Venture-backed developers outsource toxicology screening to specialized assay providers. Capital constraints favor modular reagent purchases over integrated platform investment.
Pharmaceutical Firms anchor demand, while Contract Research Organizations are gaining share fastest through technical specialization.
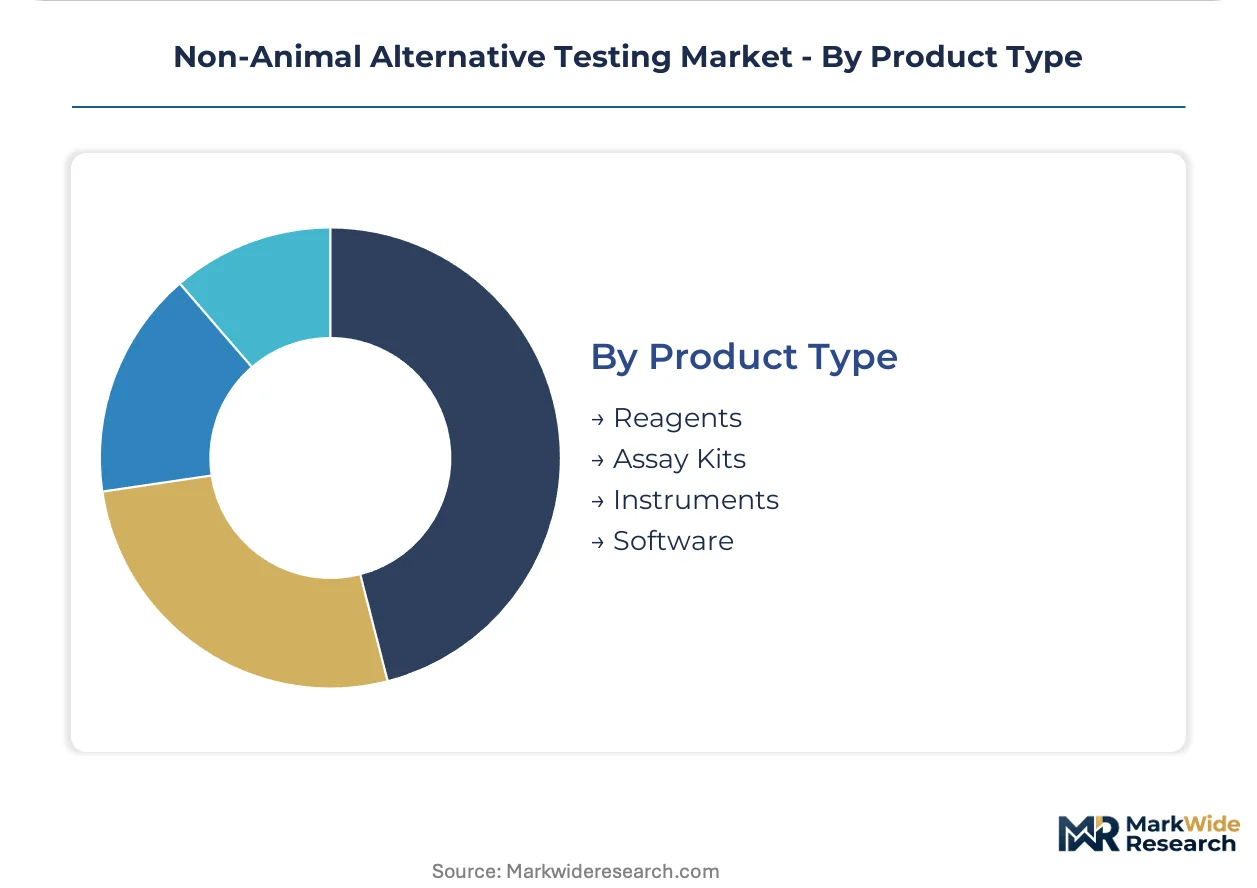
Product Type:
Supply chain configuration shapes vendor competitive dynamics.
- Reagents:Specialized growth factors, extracellular matrices, and cell culture media constitute recurring revenue streams. Swiss and German manufacturing clusters dominate high-grade input supply.
- Assay Kits:Pre-validated protocol bundles reduce implementation friction for mid-cap sponsors. Cytotoxicity and apoptosis detection kits see broadest cross-sector deployment.
- Instruments:Microfluidic pumps, imaging systems, and biosensors require capital investment and technical training. Biopharmaceutical procurement teams increasingly unbundle hardware from support services.
- Software:Data analysis platforms integrate sensor outputs with electronic laboratory notebooks. Legacy LIMS integration challenges impede enterprise adoption.
Reagents generate the steadiest revenue base, while Instruments show the most volatile demand cyclicality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented pharmaceutical hubs in Germany and Switzerland supply organ-chip platforms to contract research organizations across North America and Asia, while import-dependent biotech clusters in India and China accelerate local validation capacity to reduce procurement lead times.
United States
FDA Modernization Act 2.0 provisions drive pharmaceutical sponsors to integrate microphysiological systems into IND-enabling packages. The agency's qualification pathway for New Alternative Methodologies compresses validation timelines for hepatotoxicity screening. Greater Boston anchors concentrated demand, with venture-backed biotechs procuring organ-on-chip platforms for preclinical de-risking.
Germany
REACH registration mandates under ECHA channel industrial chemical producers toward validated in vitro methods for skin sensitization endpoints. The country's federal environment agency actively promotes OECD Test Guideline adoption for eye irritation assessments. Frankfurt-Rhine-Main clusters specialized reagent manufacturing, with Swiss and German supply chains dominating high-grade extracellular matrix production.
Switzerland
Swissmedic alignment with EMA qualification opinions accelerates local adoption of kidney proximal tubule-on-chip models for repeat-dose toxicity. The country's precision manufacturing base supports microfluidic component fabrication for export to European contract research organizations. Basel-Land canton concentrates toxicology service providers retooling for GLP-certified organ-chip studies.
India
CDSCO harmonization with ICH M3(R2) guidelines creates procurement openings for Western assay providers supporting ANDA submissions with non-animal pharmacokinetic data. The country's pharmaceutical export sector faces mounting pressure from European buyers to demonstrate cruelty-free certification. Hyderabad and Bangalore clusters build internal microfluidics capabilities to reduce dependency on imported platforms.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EMA bans on cosmetics animal testing while exploring accelerated acceptance for organ-chip submissions. London-Oxford-Cambridge corridor concentrates academic research networks generating qualification data packages. British contract research organizations specialize in custom assay development for multinational pharmaceutical clients.
Non-Animal Alternative Testing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and microfabrication supply. The vendor base stratifies across three functional layers: diversified life science conglomerates with reagent manufacturing scale, mid-cap platform developers with regulatory affairs capabilities, and niche microfluidic design houses. Consolidation pressure concentrates at the platform tier, where GLP certification timelines extend competitive moats. Strategic moves center on backward integration into specialized cell sourcing and technology licensing partnerships with academic medical centers.
Among diversified conglomerates, Thermo Fisher Scientific and Merck occupy positions anchored by recurring revenue streams in cell culture media and growth factor supply. Lonza Group exemplifies the custom assay development archetype, with premium positioning sustained through deep integration with European academic networks. MIMETAS sits within the specialized platform tier, representing microfluidic design capabilities focused on toxicology screening applications.
| Leading Market Players |
|---|
| Emulate |
| VITROCELL Systems |
| TissUse |
| Thermo Fisher Scientific |
| Lonza Group |
| Merck |
| InSphero |
| MIMETAS |
| Evotec SE |
| Others |
Supply Flow & Price Mechanics
Basel-Land canton in Switzerland concentrates microfluidic component fabrication capacity, with precision manufacturing clusters feeding European contract research organizations and anchoring premium pricing power for organ-chip platforms. This geographic concentration of specialized extracellular matrix and growth factor production creates asymmetric leverage over downstream assay providers competing on validation timelines.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the non-animal testing market. Price differentiation rests on GLP certification status and volume commitment scale, with pharmaceutical sponsors paying premiums for qualified microphysiological systems while mid-cap biotechs negotiate modular reagent bundles. Cost compression in standard-tier assay kits is intensifying because Swiss and German supply chain bottlenecks inflate input costs for primary human tissue. Contract research organizations exhibit the highest price sensitivity due to thin margins on fee-for-service toxicology screening, whereas integrated pharmaceutical discovery groups prioritize regulatory acceptance over unit economics.
Supply Chain Analysis
Tariff exposure between Switzerland and Germany dominates supply chain risk planning for specialized reagent procurement. Manufacturing concentrates in Switzerland, Germany, and the United States, with microfluidic chip fabrication drawing from photoresist polymers, soft-lithography masters, and precision pump components. Single-source vulnerability characterizes high-grade extracellular matrix supply, where Swiss producers control proprietary formulation IP. Distribution runs through direct vendor relationships with multinational pharmaceutical clients and specialized distributors serving contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-animal alternative testing market is entering a cyclical recovery phase driven by FDA Modernization Act 2.0 implementation accelerating regulatory acceptance timelines for organ-chip submissions.
For Market Incumbents: Harden defensive moats by accelerating GLP certification for novel organ-chip endpoints before guideline finalization locks in substitution status. Backward integration into induced pluripotent stem cell sourcing reduces donor variability risk that threatens hepatocyte assay margins. Incumbent platform developers must also consolidate technical training capabilities as biopharmaceutical procurement teams unbundle after-sales support from hardware contracts. For New Entrants and Emerging Players: India's pharmaceutical export sector represents the most penetrable entry point, with CDSCO alignment to ICH M3(R2) guidelines creating demand for Western assay providers supporting ANDA submissions. Bioprinted tumoroid co-cultures for immuno-oncology applications offer a second white-space target where static spheroid incumbents cannot replicate patient-matched stromal-immune-tumor complexity. A regulatory affairs-first go-to-market angle accelerates platform acceptance ahead of technical differentiation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory infrastructure play because EMA and FDA qualification pathways for microphysiological systems are hardening into durable competitive barriers. Acquisition targets should display dual-jurisdiction regulatory affairs capabilities and existing academic medical center licensing partnerships. The signal to watch is EMA parallel scientific advice meeting volume as a leading indicator of which platforms achieve formal substitution status.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Certification Investment | Extends competitive moats for organ-chip endpoints under OECD-compliant study audits. |
| Academic Medical Center Partnership | Generates qualification data packages supporting EMA and FDA substitution opinions. |
| Backward Integration into iPSC Sourcing | Reduces donor variability costs for hepatocyte-like functionality assays. |
| Regulatory Affairs Capability Buildout | Accelerates dual-jurisdiction acceptance ahead of FDA Modernization Act 2.0 finalization. |
| Professional Services Unbundling | Captures standalone educational value as biopharmaceutical procurement separates training from hardware. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with toxicology screening directors, regulatory affairs leads at pharmaceutical sponsors, contract research organization procurement officers, and microfluidics platform engineers; and secondary validation against FDA New Alternative Methodology guidance documents, EMA qualification opinions, OECD Test Guidelines, ISO 10993 biocompatibility standards, and REACH registration databases. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocation patterns.
Forecast inputs incorporated technology platform adoption curves, regulatory substitution timeline assumptions, and procurement budget shifts across the projection horizon. Segmentation dimensions modeled include technology platform type, application sector, end-user sophistication tier, and regional regulatory cluster alignment. CAGRs were derived from fitted diffusion curves calibrated to historical validation acceptance rates and pipeline pressure indicators in pharmaceutical discovery.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical venture funding availability or EU Green Deal implementation pace would shift the trajectory. Forecasts reflect documented assumptions about regulatory equivalence determinations and platform qualification timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Papain Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Colostrum Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Salmon Polynucleotide (PN) Market