
 Global DNA Test Kit Market | 2026-2036
Global DNA Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Global DNA Test Kit Market Foresight
Saliva-based biosample collection is consolidating as the dominant material format, displacing blood-draw protocols across consumer-facing product lines. AncestryDNA leverages proprietary reference databases to anchor its genealogical matching accuracy. 23andMe sustains dual-track positioning across ancestry and health risk verticals. Nebula Genomics differentiates through whole-genome sequencing depth rather than SNP-array breadth.
DNA test kits are self-administered sampling systems that extract and stabilize nucleic acid from buccal swabs or saliva for downstream genotyping, sequencing, or targeted mutation analysis, with most consumer kits employing SNP arrays interrogating hundreds of thousands to millions of genetic variants. The primary commercial purpose spans genealogical relationship inference, inherited disease carrier status determination, pharmacogenomic guidance, and polygenic risk scoring for common conditions. Ancestry testing kits occupy the largest revenue pool due to cultural curiosity and media-driven consumer awareness, while health risk assessment kits represent the fastest-expanding category as clinical validation frameworks mature. Nutrigenomic kits command premium positioning despite narrower evidence bases, attracting wellness-focused subscribers through personalized dietary recommendations.
FDA oversight in the United States classifies genetic health risk tests as Class II medical devices requiring 510(k) premarket notification, directly constraining which conditions manufacturers may report to consumers. EMA and national EU regulators under the In Vitro Diagnostic Regulation are harmonizing clinical evidence requirements for direct-to-consumer genetic testing, reshaping market access timelines across member states. China's NMPA has accelerated review pathways for domestic genomics platforms while maintaining strict data localization mandates for genetic information. Stakeholders must monitor evolving reimbursement decisions by Germany's Federal Joint Committee and France's ANSM regarding clinical-grade predictive genetic testing, as these will determine whether health-risk kits transition from discretionary purchases toward partially covered preventive services.
Market Dynamics
Saliva-based biosample collection is displacing blood-draw protocols as the dominant material format, while FDA 510(k) clearance pathways for genetic health risk assessments tighten approval timelines and reshape competitive positioning in the United States.
Growth Catalysts
- Genealogical hobbyist communities:Direct-to-consumer ancestry testing expands through social media-driven discovery and documentary media coverage. Germany and the United Kingdom concentrate European demand.
- IVDR harmonization:EMA and national EU regulators under the In Vitro Diagnostic Regulation are standardizing clinical evidence requirements, accelerating cross-border market access for compliant kits.
- Pharmacogenomic guidance adoption:Healthcare systems integrate genetic testing into medication selection protocols, creating institutional procurement channels beyond discretionary consumer purchases.
Market Restraints
- Reference database concentration:Proprietary genealogical matching accuracy depends on population-scale genomic datasets controlled by a limited set of commercial repositories.
- FDA Class II medical device classification:510(k) premarket notification requirements directly constrain which health conditions manufacturers may report to consumers, limiting product differentiation.
- Whole-genome sequencing cost premium:SNP-array breadth maintains price advantages over sequencing depth for mass-market consumer penetration.
Strategic Opportunities
- Preventive service reimbursement:Germany's Federal Joint Committee and France's ANSM reimbursement decisions could shift health-risk kits from discretionary purchases toward partially covered services.
- Polygenic risk scoring maturation:Clinical validation frameworks for common conditions expand addressable use cases beyond single-gene carrier status.
- China's NMPA accelerated pathways:Domestic genomics platforms benefit from streamlined review while strict genetic data localization mandates create captive market conditions.
Industry Challenges
- Bioinformatician talent scarcity:Interpretation of whole-genome sequencing outputs requires specialized computational biology expertise that outpaces educational pipeline production.
- Cross-border genetic data transfer restrictions:GDPR in Europe and China's data localization mandates fragment cloud-based analysis infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DNA Test Kit Market |
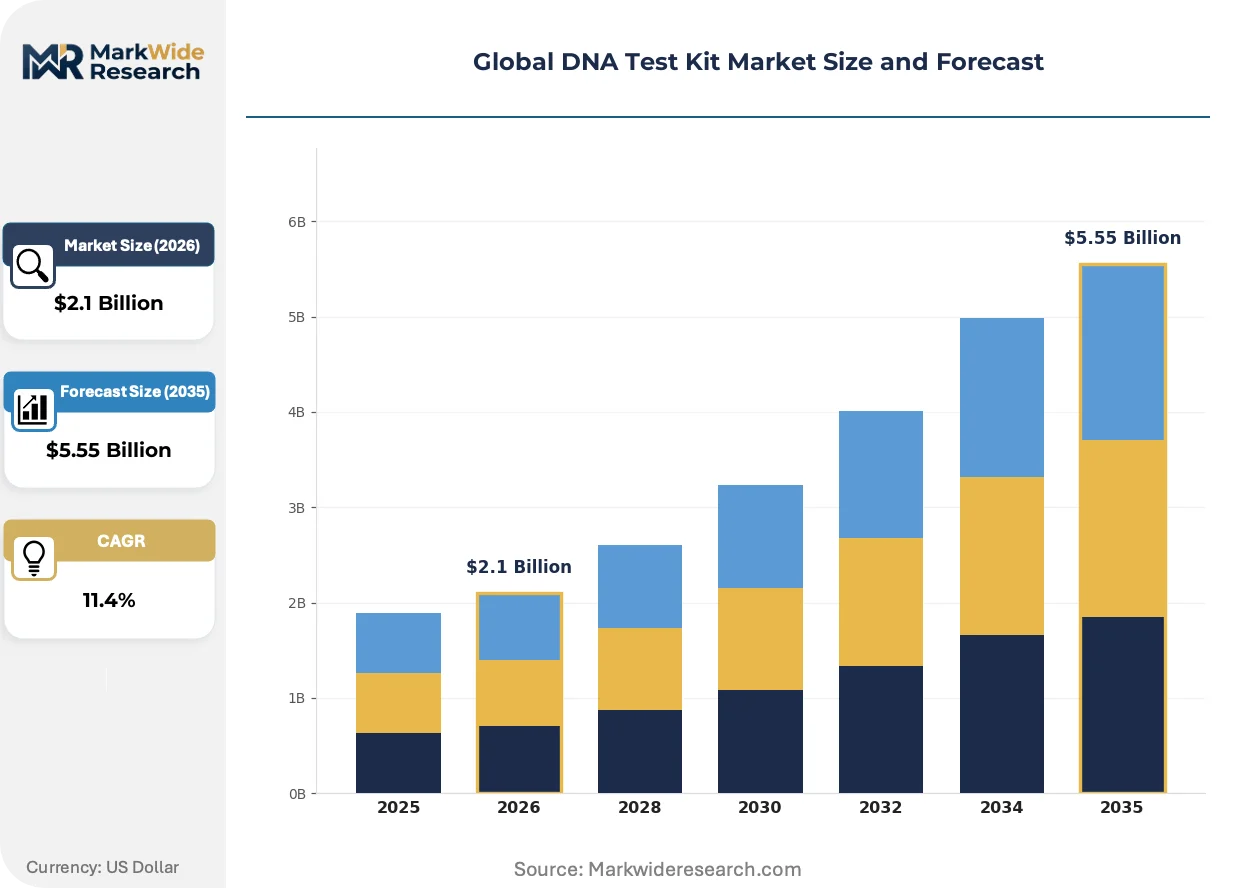
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: paternity Testing Kits, Ancestry Testing Kits, Health Risk Assessment Kits, Carrier Screening Kits, Nutrigenomic Kits Application: Forensic Analysis, Genetic Disorder Screening, Trait Prediction, Wellness Optimization, Personalized Diet Planning End User: Research Institutions, Genetic Counselors, Biotech Companies, Direct-to-Consumer, Academic Laboratories Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Healthcare Providers, Subscription Services |
| Companies Covered | FamilyTreeDNA, Living DNA, AncestryDNA, Everlywell, SelfDecode, 23andMe, Nebula Genomics, 24Genetics, MyHeritage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DNA Test Kit Market Shifts & Advancements
Technological convergence between sequencing chemistry and artificial intelligence interpretation tools is compressing turnaround times while regulatory divergence across major economies fragments standardization efforts.
CRISPR-based enrichment protocols are electrifying targeted mutation analysis workflows by reducing reagent costs and simplifying library preparation. Clinical laboratories in oncology and rare disease diagnostics adopt these methods at accelerating pace. This electrification enables point-of-care genetic screening applications previously confined to centralized facilities.
The EU AI Act classification of certain genomic interpretation algorithms as high-risk AI systems imposes conformity assessment obligations on software-as-a-service genetic analysis platforms. Manufacturers must document training data provenance and algorithmic transparency. Health risk assessment kits with automated reporting functions face the steepest compliance burden.
Subscription-based nutrigenomic services unbundle one-time test purchases into recurring dietary recommendation programs. Wellness-focused consumers in North America and Western Europe drive this model's expansion. Direct-to-consumer brands capture lifetime value through continuous content delivery rather than discrete transaction economics.
Global DNA Test Kit Market Segmentation
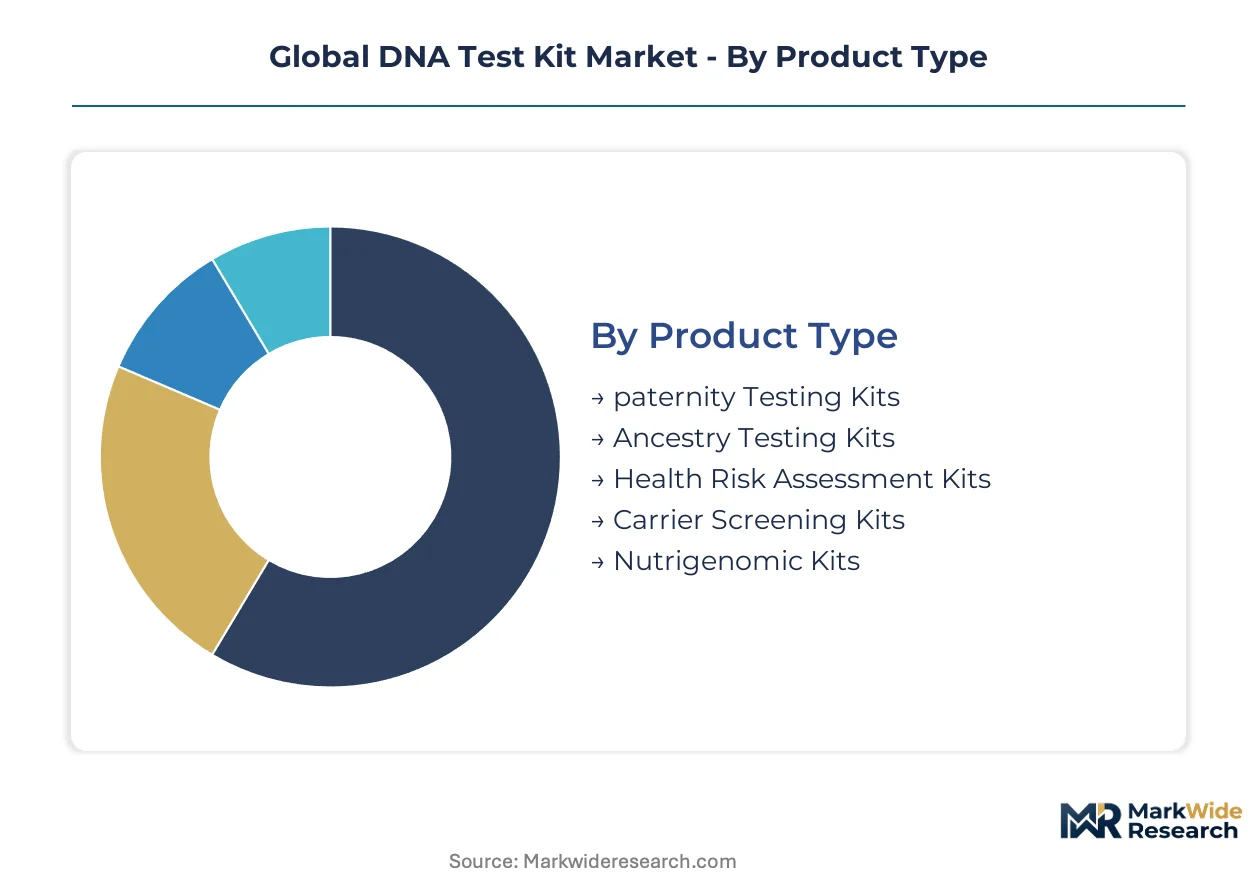
DNA test kit segmentation reveals how supply-side specialization fragments across divergent technical requirements, regulatory pathways, and customer acquisition economics. Manufacturers optimize production lines for either high-volume SNP-array ancestry products or clinically validated health risk platforms, rarely bridging both profitably.
Product Type:
Supply concentrates in saliva-based SNP-array manufacturing facilities that serve multiple product categories through shared biosample processing infrastructure.
- Ancestry Testing Kits:SNP-array platforms interrogate 700,000+ genetic variants against proprietary reference databases for genealogical matching. Demand clusters in Germany and the United Kingdom among documentary-media-influenced consumers.
- Health Risk Assessment Kits:FDA 510(k) clearance requirements constrain reportable conditions to clinically validated gene-disease associations. United States consumers drive volume despite regulatory narrowing of permissible risk disclosures.
- Paternity Testing Kits:STR analysis delivers rapid relationship confirmation with lower bioinformatics overhead.
- Carrier Screening Kits:Targeted mutation panels identify recessive disease risk for family planning decisions.
- Nutrigenomic Kits:Polygenic scoring for metabolic traits supports personalized dietary recommendations despite narrower clinical evidence bases.
Ancestry Testing Kits absorb the bulk of installed capacity; Health Risk Assessment Kits are expanding most quickly.
Application:
Application segmentation tracks how clinical validation maturity determines whether kits penetrate institutional procurement or remain discretionary consumer purchases.
- Genetic Disorder Screening:Single-gene and polygenic risk assessment for Mendelian conditions requires CAP/CLIA laboratory certification. Healthcare systems in France and Germany evaluate reimbursement eligibility through national health technology assessment processes.
- Wellness Optimization:Lifestyle-oriented genetic interpretation bypasses medical device classification in most jurisdictions. Direct-to-consumer marketing channels dominate distribution.
- Forensic Analysis:CODIS-compatible STR profiling serves law enforcement and legal paternity proceedings.
- Trait Prediction:Polygenic scores for non-medical characteristics occupy regulatory gray zones.
- Personalized Diet Planning:Nutrigenomic algorithms translate metabolic variants into meal recommendations.
Genetic Disorder Screening commands premium pricing tiers; Wellness Optimization is gaining share fastest.
End User:
End user segmentation reflects divergent purchasing authority between institutional procurement committees and individual discretionary spending.
- Direct-to-Consumer:Self-administered saliva collection with smartphone-activated result portals eliminates clinical intermediary costs. Marketing spend concentrates on social media platforms targeting genealogical hobbyist communities.
- Research Institutions:Bulk biosample procurement for population genomics studies requires IRB approval and informed consent infrastructure.
- Genetic Counselors:Clinical interpretation services integrate test results into patient risk communication protocols.
- Biotech Companies:Drug development programs license aggregated genomic datasets for target identification.
- Academic Laboratories:Grant-funded research applications prioritize whole-genome sequencing depth over SNP-array breadth.
Direct-to-Consumer channels move the highest unit volumes; Research Institutions generate the steepest revenue per kit.
Distribution Channel:
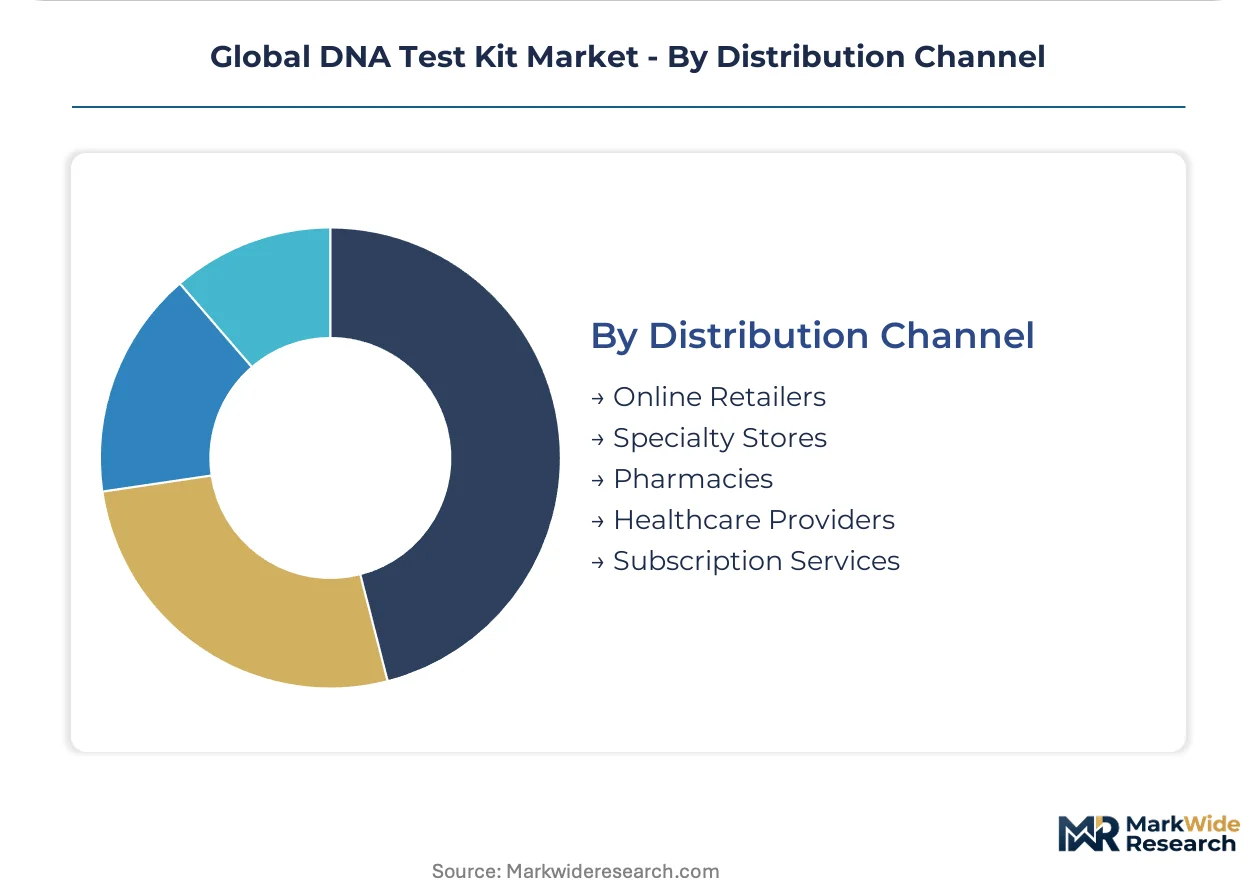
Channel segmentation tracks how customer acquisition costs vary between digital-native discovery and physical retail presence.
- Online Retailers:Amazon and direct brand websites capture majority volume through algorithmic recommendation engines and documentary-media-driven search demand.
- Subscription Services:Recurring nutrigenomic content delivery unbundles one-time test economics into lifetime value models.
- Pharmacies:CVS and Walgreens shelf placement targets health-conscious shoppers with impulse purchase accessibility.
- Healthcare Providers:Clinical integration requires laboratory certification and physician ordering workflows.
- Specialty Stores:Limited presence in wellness-focused retail environments.
Online Retailers dominate transaction volume; Subscription Services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Genealogical hobbyist communities in Germany and the United Kingdom concentrate European demand for direct-to-consumer ancestry testing. FDA clearance pathways in the United States constrain health risk assessment kit expansion. China's NMPA accelerates domestic platform approvals while enforcing strict genetic data localization.
United States
Direct-to-consumer marketing through social media platforms drives unit volumes among documentary-media-influenced consumers. FDA Class II medical device classification under 510(k) premarket notification requirements limits reportable health conditions to clinically validated gene-disease associations. The San Francisco Bay Area and Boston metropolitan region host the densest concentration of genomics platform developers and bioinformatics talent pools.
Germany
Federal Joint Committee reimbursement evaluations for predictive genetic testing determine whether health-risk kits transition from discretionary purchases toward partially covered preventive services. The In Vitro Diagnostic Regulation harmonizes clinical evidence requirements across EU member states, accelerating compliant kit market access. Munich and Berlin anchor the country's consumer genomics distribution infrastructure and genealogical research community hubs.
China
NMPA accelerated review pathways benefit domestic genomics platforms seeking competitive positioning against international entrants. Strict genetic data localization mandates under national cybersecurity frameworks create captive market conditions for indigenous service providers. Beijing and Shenzhen concentrate sequencing instrument manufacturing capacity and cloud-based genetic analysis infrastructure development.
United Kingdom
Media-driven consumer awareness from documentary programming sustains ancestry testing demand among genealogical hobbyist communities. GDPR compliance requirements and post-Brexit regulatory divergence reshape cross-border genetic data transfer protocols for analysis platforms. London and Cambridge host the primary research institution procurement channels and academic genomics laboratory networks.
France
ANSM reimbursement decisions for clinical-grade predictive genetic testing influence health-risk kit adoption patterns among preventive care consumers. CNIL oversight of genetic data processing imposes stringent consent and retention requirements on direct-to-consumer platforms. The Paris-Saclay cluster concentrates biotech company licensing activity and pharmacogenomic research institution partnerships.
Global DNA Test Kit Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with dual-track ancestry-health positioning commanding premium economics against single-vertical specialists. The vendor base organizes around three strategic archetypes: SNP-array platform operators leveraging proprietary reference databases, whole-genome sequencing depth providers targeting research-adjacent consumers, and wellness-oriented nutrigenomic subscription services. Competitive moves concentrate on M&A for database expansion and strategic partnerships for clinical validation pathway acceleration.
Within the dual-track positioning tier, AncestryDNA and 23andMe occupy positions that exemplify the ancestry-health convergence strategy, while Nebula Genomics represents the sequencing-depth archetype for research-oriented consumers. MyHeritage anchors the European-originated specialist segment with genealogical platform integration. These three named entities demonstrate how geographic origin and technical positioning stratify competitive differentiation without overlapping segment coverage.
| Leading Market Players |
|---|
| FamilyTreeDNA |
| Living DNA |
| AncestryDNA |
| Everlywell |
| SelfDecode |
| 23andMe |
| Nebula Genomics |
| 24Genetics |
| MyHeritage |
| Others |
Supply & Pricing Matrix
Bioinformatician talent scarcity in the San Francisco Bay Area and Boston metropolitan region drives labor-cost differentials that widen pricing-tier spreads between SNP-array ancestry products and whole-genome sequencing platforms. Manufacturers pass specialized computational biology expertise premiums through to consumers, stratifying accessible mass-market kits from research-grade offerings.
Pricing Analysis
Volume concentrates in ancestry testing kits while margins concentrate in health risk assessment platforms. Three-tier pricing structure across premium whole-genome sequencing, standard SNP-array health kits, and economy ancestry products reflects FDA 510(k) certification investment differentials. Pricing pressure stems from SNP-array commoditization as reference database scale becomes the primary switching cost. Direct-to-consumer channels exhibit highest price sensitivity; institutional procurement through healthcare systems demonstrates lowest.
Supply Chain Analysis
Direct-to-consumer channels handle hyperscale buyer demand through Amazon and brand-direct websites, while clinical integration flows through CAP/CLIA certified laboratories. Manufacturing concentrates in China for sequencing instrument production, the United States for SNP-array fabrication, and Germany for precision optical components. Raw material dependencies include Illumina flowcell chemistry, specialized polymerases for library preparation, and stabilized saliva collection buffers. Single-source vulnerability in sequencing instrument supply creates structural risk. Distribution runs through digital-native discovery platforms with limited physical retail presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through bioinformatician talent bottlenecks that prop pricing for interpretation-heavy whole-genome platforms. Specialized computational biology expertise scarcity limits expansion velocity for sequencing-depth providers.
For Market Incumbents: To counter emerging whole-genome sequencing depth providers, AncestryDNA and 23andMe should deepen proprietary reference database moats through genealogical platform integration investments. FDA 510(k) clearance pathway acceleration for additional health risk conditions represents a second defensive lever against SNP-array commoditization. For New Entrants and Emerging Players: Pharmacogenomic guidance adoption by healthcare systems offers the most penetrable white-space target, bypassing discretionary consumer purchase volatility. Germany and France reimbursement evaluation timelines create institutional procurement entry points. Direct hospital system partnerships outperform mass-market advertising for this segment. For Investors and Strategic Acquirers: Re-rating potential sits with dual-track ancestry-health positioning archetypes given FDA clearance expansion catalysts. Five-to-ten year viability favors platforms with proprietary database assets rather than sequencing-commodity providers. The signal to watch is Germany's Federal Joint Committee reimbursement decisions for predictive genetic testing.| Strategic Initiative | Industry Significance |
|---|---|
| Reference Database Expansion | Proprietary genealogical matching accuracy depends on population-scale genomic dataset accumulation against AncestryDNA and 23andMe repositories. |
| FDA 510(k) Pathway Acceleration | Additional health risk condition clearances differentiate compliant kits from direct-to-consumer wellness products facing regulatory narrowing. |
| Pharmacogenomic Hospital Partnerships | Healthcare system integration creates institutional procurement channels beyond discretionary consumer purchase volatility. |
| Whole-Genome Sequencing Cost Reduction | Library preparation automation and CRISPR-based enrichment protocols compress reagent costs for research-adjacent consumer segments. |
| EU IVDR Compliance Investment | EMA harmonization of clinical evidence requirements accelerates cross-border market access for compliant kit manufacturers. |
Research Methodology
Multi-period observation of FDA 510(k) clearance volumes, NMPA approval timelines, and EU IVDR conformity assessment completions anchored the trend analysis, supplemented by interviews with genomics platform executives, CAP/CLIA laboratory directors, genetic counselors, and hospital procurement managers. Secondary validation drew from FDA 510(k) databases, EMA IVDR guidance documents, ClinicalTrials.gov pharmacogenomic study registrations, and CMS Medicare reimbursement coding updates. Bottom-up kit shipment estimates triangulated against top-down market value reconstructions.
Input-output matrices modeled volume and value across product type, application, end user, and distribution channel dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included SNP-array manufacturing capacity utilization rates, whole-genome sequencing cost curves, and regulatory pathway timeline probability distributions.
Several conditions sit outside the modeled scope, including CRISPR therapeutic applications, forensic DNA database expansion policies, and direct-to-consumer raw data interpretation services. Forecasts reflect assumptions regarding reimbursement decision timelines and regulatory clearance velocity that periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
Point of Care Blood Testing Devices Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market