
 Europe Breath Analyzer Market | 2026-2036
Europe Breath Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Breath Analyzer Market Intelligence
Buyer concentration among European law enforcement agencies is decoupling from traditional national procurement frameworks as regional police consortia and private occupational health providers fragment purchasing across smaller, specialized contracts. Drägerwerk AG & Co. KGaA leverages its established calibration service networks to sustain long-term institutional relationships. BACtrack competes aggressively on portable unit portability and consumer-adjacent branding that spills into corporate wellness channels. Lion Laboratories Limited anchors its position through UK-specific Home Office approvals that constrain foreign rivals in British policing markets.
A breath analyzer measures ethanol and volatile organic compound concentrations in exhaled breath through electrochemical or spectroscopic detection, typically achieving blood alcohol content correlation within plus-or-minus 0.005 percentage points for evidential-grade devices. Fuel cell sensors dominate law enforcement applications due to their specificity against acetone and other interferents, while infrared sensors occupy premium medical diagnosis segments where multi-substance panels matter. Portable analyzers lead volume shipments across European police forces, yet disposable devices represent the fastest-expanding margin pool as employers adopt single-use occupational health protocols to eliminate cross-contamination liability.
CE marking under the EU Medical Device Regulation and the General Product Safety Directive govern market access, with notified bodies in Germany and the Netherlands conducting conformity assessments that delay entry for non-European manufacturers. The European Medicines Agency coordinates reference standards for breath biomarker validation that shape R&D priorities for clinical diagnostic applications. Stakeholders must monitor divergence between national metrology institute calibration requirements and emerging EU-wide digital health data interoperability rules that will determine whether connected breath analyzer data gains admissibility in occupational litigation and insurance underwriting.
Market Dynamics
EU Medical Device Regulation recalibration deadlines are forcing breath analyzer manufacturers to abandon legacy electrochemical platforms and accelerate semiconductor sensor certification timelines.
Growth Catalysts
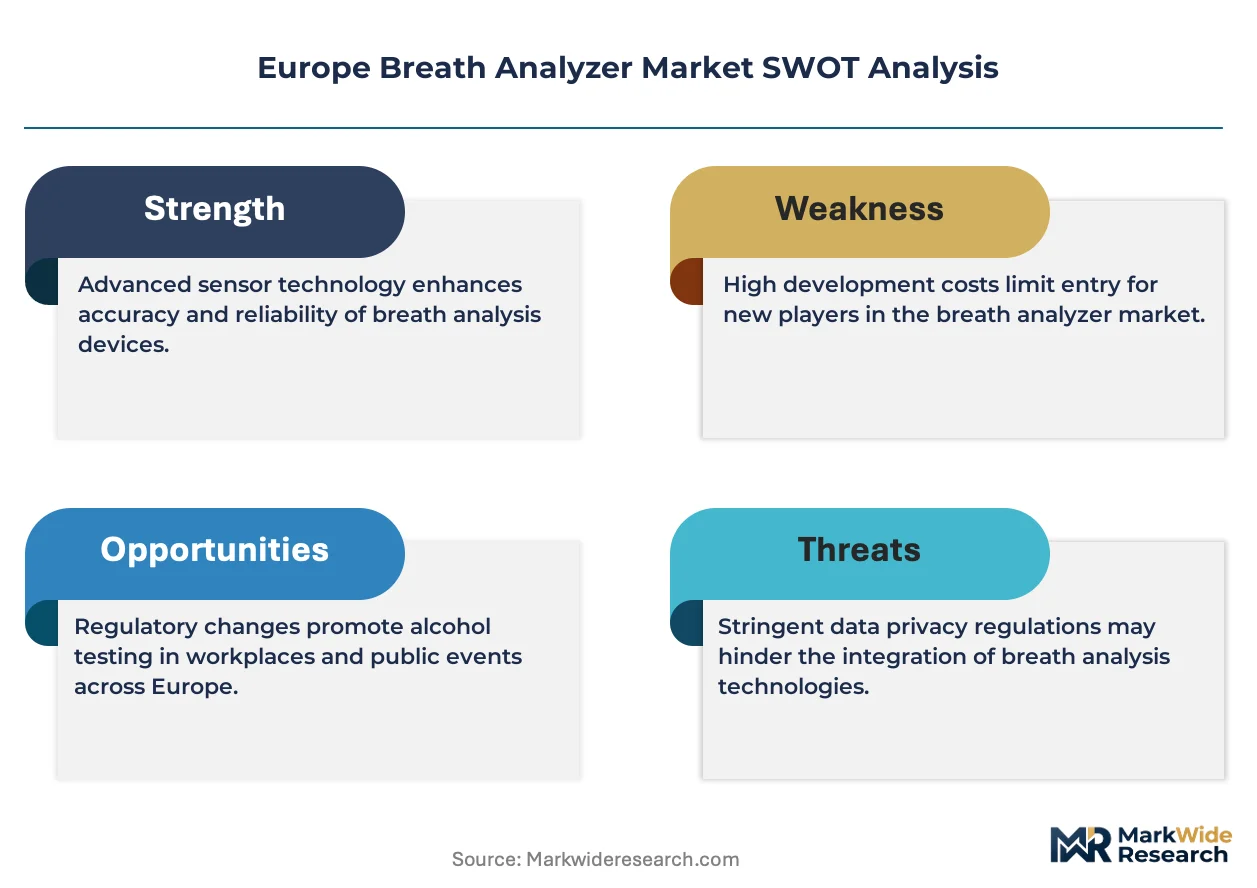
- Fuel cell specificity advantages:German federal traffic safety mandates now require acetone-resistant detection for roadside evidential units, locking in fuel cell architecture procurement across state police forces.
- Workplace testing protocols:France's occupational health directives are expanding mandatory alcohol screening to construction and logistics sectors, creating institutional demand clusters outside traditional law enforcement channels.
- CE marking convergence:Netherlands-based notified bodies are streamlining conformity assessments for multi-biomarker devices, reducing market access friction for clinical diagnostic entrants.
Market Restraints
- Calibration infrastructure concentration:Metrology-grade reference gas supply chains cluster in southern Germany, exposing peripheral European markets to service delays and transport cost volatility.
- Sensor material input costs:Platinum catalyst procurement for fuel cell electrodes faces price pressure from automotive hydrogen economy demand, compressing hardware margins for portable unit manufacturers.
- Infrared platform size constraints:Miniaturized spectroscopic modules remain incompatible with pocket-form factor requirements, limiting medical segment penetration into consumer-adjacent wellness channels.
Strategic Opportunities
- Eastern European enforcement modernization:Polish and Romanian national police forces are replacing Soviet-era screening equipment, opening tender windows for EU-certified portable systems with local language interfaces.
- Digital health data interoperability:Emerging EU-wide rules on occupational health record portability will determine whether connected breath analyzer outputs gain admissibility in insurance underwriting and litigation discovery.
- Single-use occupational protocols:Nordic corporate wellness providers are piloting disposable mouthpiece-integrated sensors to eliminate cross-contamination liability in high-frequency testing environments.
Industry Challenges
- Sensor fusion engineering talent scarcity:Electrochemical-semiconductor hybrid design expertise concentrates in Munich and Eindhoven R&D clusters, constraining product development velocity for peripheral competitors.
- MDR technical documentation burden:Clinical performance validation requirements for multi-substance panels are extending certification timelines, delaying revenue recognition for next-generation diagnostic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Breath Analyzer Market |
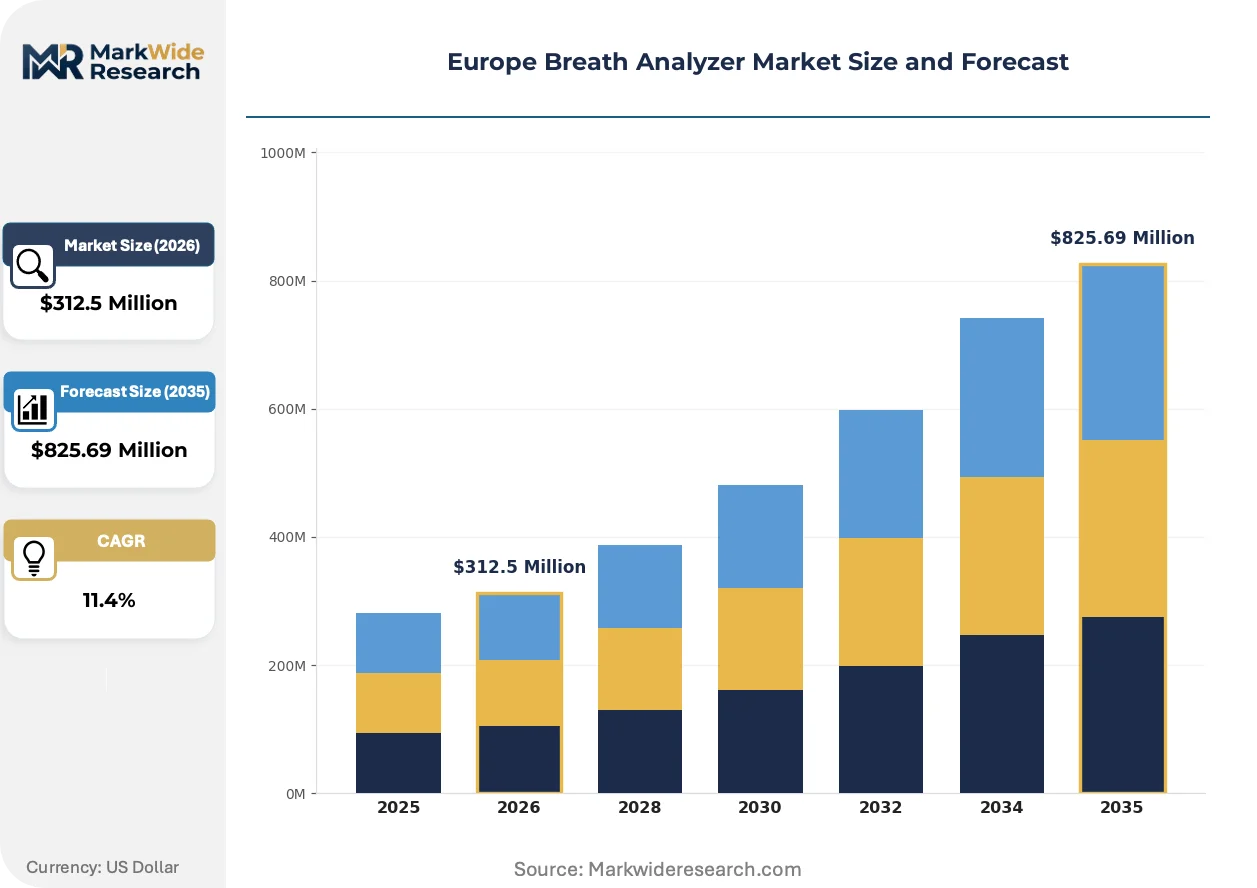
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Handheld Analyzers, Bench-Top Analyzers, Disposable Devices Technology: Fuel Cell Sensors, Semiconductor Sensors, Infrared Sensors, Photoionization Detectors End User: Hospitals, Clinics, Law Enforcement, Research Laboratories Application: Alcohol Testing, Drug Detection, Medical Diagnosis, Occupational Health |
| Companies Covered | Lifeloc Technologies, Inc., BACtrack, Drägerwerk AG & Co. KGaA, Andatech Private Limited, Quest Products, Inc., Lion Laboratories Limited, AlcoSense Laboratories Ltd., C4 Development Ltd., Intoximeters Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Breath Analyzer Market Strategic Shifts & Innovations
Sensor miniaturization and regulatory data interoperability are converging to redefine competitive positioning across law enforcement, occupational health, and clinical diagnostic deployment channels.
Semiconductor-based metal oxide sensors are expanding into portable law enforcement applications by delivering comparable ethanol specificity to fuel cells at reduced unit weight and power draw. Dutch and Belgian police procurement agencies are piloting these platforms for motorcycle-mounted officer kits. The technology is expanding into roadside screening by enabling continuous monitoring modes that fuel cell architectures cannot sustain.
EU General Product Safety Directive amendments are tightening accuracy tolerance bands for consumer-grade breath analyzers, compressing the performance gap between professional and personal use devices. Manufacturers must now submit to third-party laboratory validation previously reserved for medical device categories. German consumer protection authorities are enforcing these standards most aggressively, triggering product withdrawals from retail channels.
Regional police consortia in the United Kingdom are consolidating calibration service contracts under multi-force framework agreements, displacing manufacturer-direct maintenance relationships. This procurement model shift transfers aftermarket revenue to third-party metrology providers and compresses long-term hardware margins. The pattern is most visible in England and Wales, where Police Scotland's centralized approach is being replicated.
Europe Breath Analyzer Market Segmentation
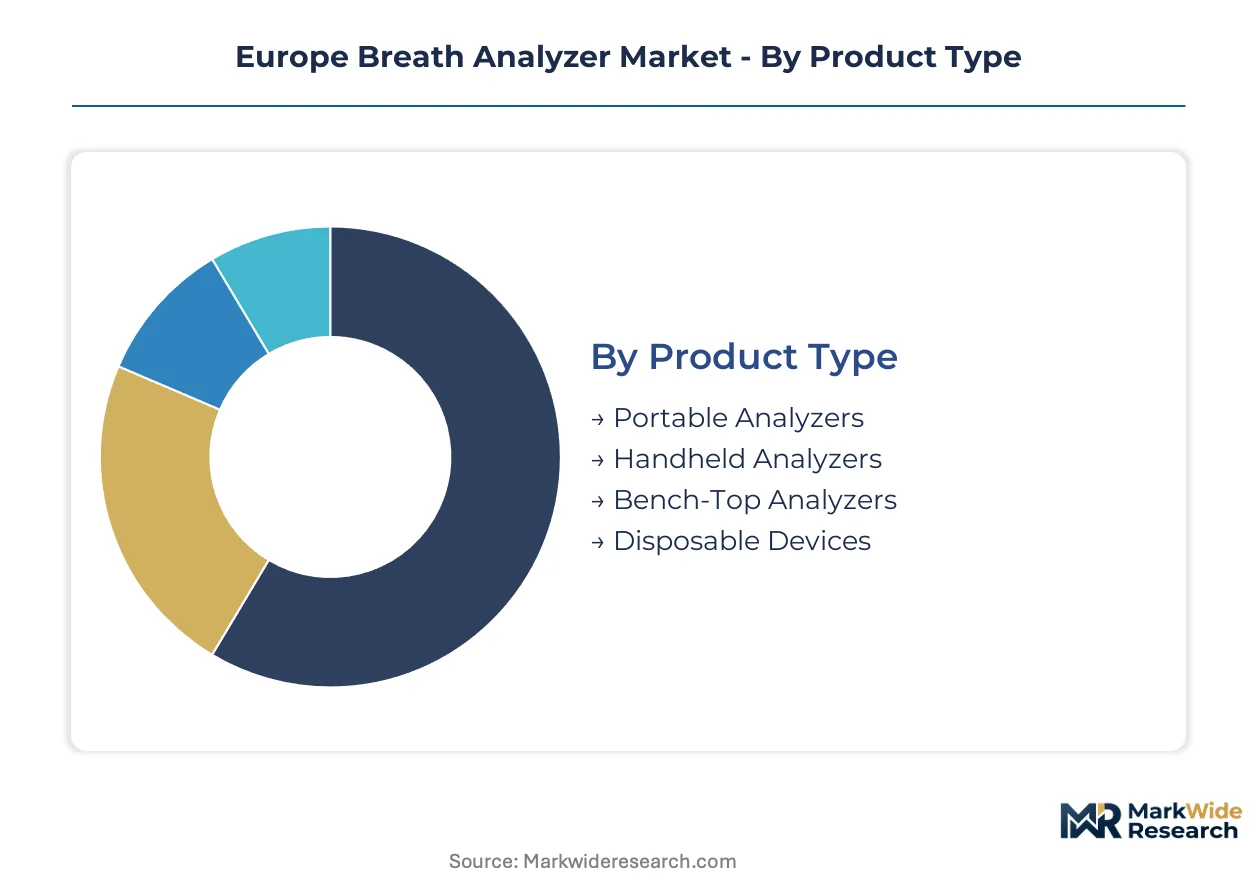
Equipment replacement cycles across European police forces and healthcare systems are fragmenting procurement patterns by performance tier and compliance vintage. Vendors must map sensor technology roadmaps against divergent national recertification timelines to capture upgrade revenue.
Product Type:
Replacement urgency concentrates in roadside enforcement fleets, where German and French state police are retiring electrochemical units ahead of MDR recalibration deadlines.
- Portable Analyzers:Battery-powered fuel cell systems with acetone-resistant detection architectures dominate German federal traffic safety procurement. State police forces in Bavaria and North Rhine-Westphalia are consolidating multi-year framework agreements for these units.
- Handheld Analyzers:Compact semiconductor-based devices deliver reduced power draw for motorcycle-mounted officer kits. Dutch and Belgian police agencies are piloting these platforms for continuous monitoring applications that fuel cell architectures cannot sustain.
- Bench-Top Analyzers:Laboratory-grade infrared systems serve forensic reference standards in UK Home Office-approved facilities.
- Disposable Devices:Single-use mouthpiece-integrated sensors eliminate cross-contamination liability in Nordic corporate wellness screening protocols.
Portable analyzers sit at the top of the volume ranking, with disposable devices climbing the fastest.
Technology:
Cost tier stratification is accelerating as platinum catalyst price pressure compresses fuel cell margins while semiconductor platforms achieve ethanol specificity parity.
- Fuel Cell Sensors:Platinum-catalyzed electrochemical detection delivers evidential-grade accuracy within plus-or-minus 0.005 percentage points. German federal mandates now require acetone-resistant specifications, locking in this architecture for roadside screening.
- Semiconductor Sensors:Metal oxide platforms achieve comparable ethanol specificity at reduced unit weight and manufacturing cost. Netherlands-based notified bodies are streamlining CE marking pathways for these devices.
- Infrared Sensors:Spectroscopic detection enables multi-substance panels for clinical diagnostic applications in European hospital networks.
- Photoionization Detectors:VOC-sensitive architectures serve occupational health screening for solvent exposure in French construction sector protocols.
Fuel cell sensors retain the largest installed base, though semiconductor platforms are gaining share fastest in portable law enforcement applications.
End User:
Customer type concentration is shifting as workplace testing mandates expand institutional demand beyond traditional policing channels.
- Law Enforcement:Regional police consortia in England and Wales are consolidating calibration contracts under multi-force framework agreements, displacing manufacturer-direct relationships.
- Hospitals:Clinical diagnostic applications require MDR-compliant multi-biomarker validation coordinated through the European Medicines Agency reference standards.
- Clinics:Point-of-care alcohol screening drives demand for connected devices capable of EU-wide digital health data interoperability.
- Research Laboratories:Metrology-grade reference gas supply chains in southern Germany serve calibration validation for academic and forensic institutions.
Law enforcement commands the largest procurement volumes, with hospitals expanding most quickly as clinical diagnostic applications multiply.
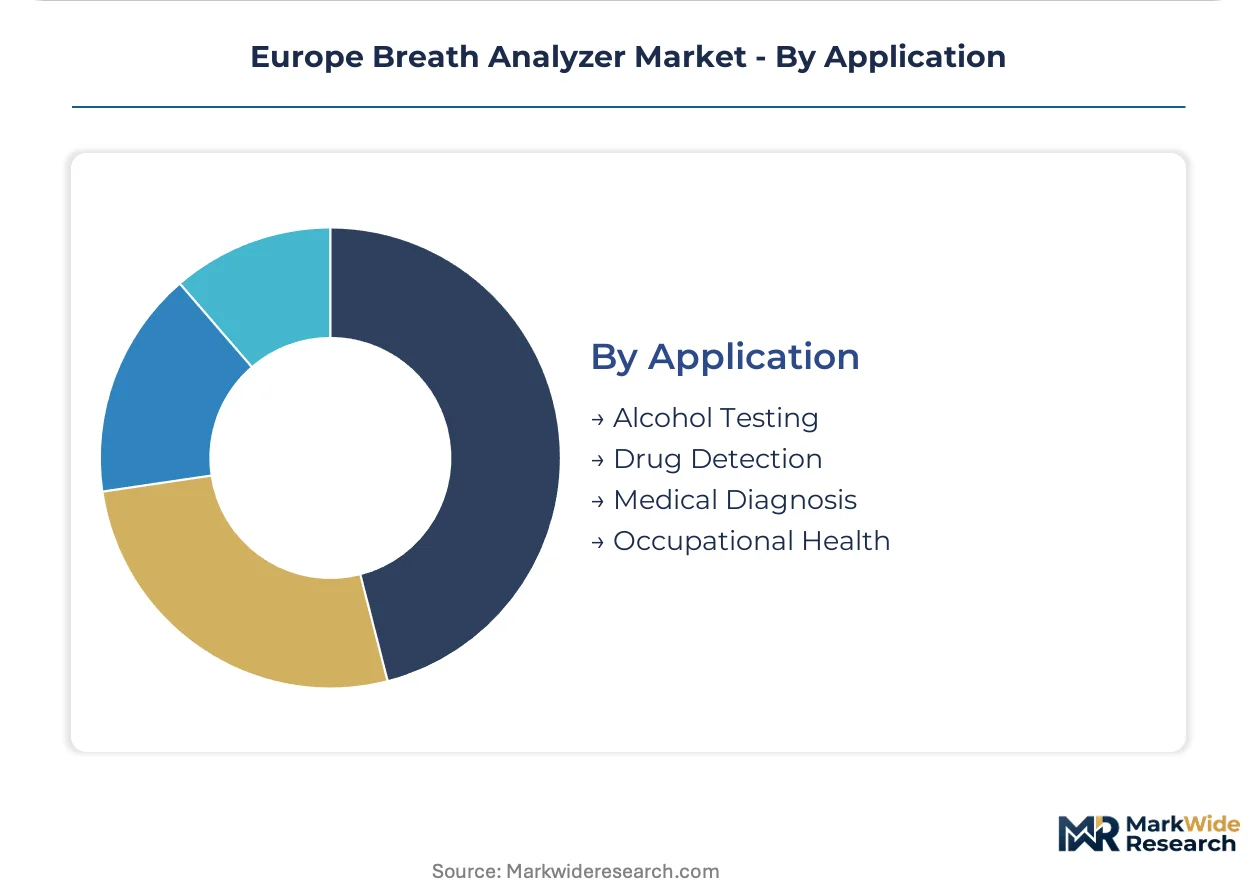
Application:
Application maturity varies sharply, with alcohol testing approaching saturation in enforcement markets while occupational health protocols drive greenfield deployment.
- Alcohol Testing:Roadside evidential screening and workplace compliance monitoring constitute the dominant revenue pool. French occupational health directives are expanding mandatory screening to logistics and construction sectors.
- Occupational Health:Employer-mandated alcohol and solvent exposure screening creates institutional demand clusters outside traditional channels. Nordic corporate wellness providers are piloting disposable protocols to eliminate cross-contamination liability.
- Drug Detection:Multi-substance breath panels remain in clinical validation phases under EMA coordination.
- Medical Diagnosis:Biomarker validation for disease state detection is extending MDR certification timelines for next-generation diagnostic platforms.
Alcohol testing maintains the deepest market penetration, with occupational health applications showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest procurement volumes while France accelerates workplace testing mandates fastest. National regulatory divergence across the region fragments certification timelines and shapes vendor entry strategies. Metropolitan R&D clusters in Munich, Eindhoven, and Cambridge anchor sensor technology advancement.
Germany
Federal traffic safety mandates and state police framework agreements sustain Europe's largest national deployment base. The KBA enforces acetone-resistant fuel cell specifications for roadside evidential units. Bavaria and North Rhine-Westphalia concentrate multi-year procurement contracts with metrology-grade calibration services clustering in southern German industrial zones.
United Kingdom
Regional police consortia in England and Wales consolidate calibration contracts under multi-force framework agreements. Home Office type approval requirements constrain foreign rivals in British policing markets. London and the Midlands host forensic reference facilities serving UK-wide evidential testing standards.
France
Occupational health directives expand mandatory alcohol screening to construction and logistics sectors outside traditional enforcement channels. ANSM coordinates clinical performance validation for multi-biomarker diagnostic platforms. The Île-de-France region anchors employer-mandated testing protocol development for corporate wellness providers.
Netherlands
Notified bodies streamline CE marking pathways for semiconductor-based portable devices, reducing market access friction. Dutch police agencies pilot motorcycle-mounted officer kits with continuous monitoring capabilities. The Eindhoven R&D cluster concentrates electrochemical-semiconductor hybrid design expertise.
Poland
National police forces replace Soviet-era screening equipment with EU-certified portable systems requiring local language interfaces. The country's national pharmaceutical regulator aligns device certification with MDR transitional provisions. Warsaw and Krakow concentrate tender administration for Eastern European enforcement modernization programs.
Europe Breath Analyzer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across technology tiers and end-use channels. Market structure tilts toward consolidated procurement relationships with regional police consortia and fragmented occupational health contracts. Three archetypes dominate: established calibration service integrators, portable unit portability specialists, and UK-specific approval holders. Competitive moves center on multi-force framework agreement capture and semiconductor sensor certification acceleration.
Within the established service integrator tier, Drägerwerk AG & Co. KGaA exemplifies long-term institutional relationship maintenance through calibration network density. BACtrack occupies a position emphasizing portable unit portability and consumer-adjacent branding that extends into corporate wellness channels. Lion Laboratories Limited anchors the UK-specific approval holder archetype through Home Office certification constraints that limit foreign competitor access.
| Leading Market Players |
|---|
| Lifeloc Technologies, Inc. |
| BACtrack |
| Drägerwerk AG & Co. KGaA |
| Andatech Private Limited |
| Quest Products, Inc. |
| Lion Laboratories Limited |
| AlcoSense Laboratories Ltd. |
| C4 Development Ltd. |
| Intoximeters Inc. |
| Others |
Cost & Logistics Intelligence
Platinum price volatility on the London Metal Exchange cascades through fuel cell electrode manufacturing into three-tier pricing stratification across premium evidential-grade, standard occupational-health, and economy consumer-tier breath analyzer units.
Pricing Analysis
Capacity additions in semiconductor sensor fabrication across the Netherlands and Belgium are reshaping price floors for portable law enforcement units. Pricing stratifies across premium evidential-grade, standard occupational-health, and economy consumer-tier levels based on CE marking tier and calibration service bundling. Cost compression in standard-tier portable units is intensifying because platinum catalyst procurement faces automotive hydrogen economy demand pressure. Occupational health providers show highest price sensitivity due to high-frequency disposable device procurement volumes, while forensic reference laboratories demonstrate lowest sensitivity given regulatory compliance mandates.
Supply Chain Analysis
Platinum catalyst supply rests on South African mining operations and Russian refining capacity, with semiconductor sensor substrates drawing from Taiwanese foundries and German specialty chemical producers. Metrology-grade reference gas production concentrates in southern Germany, while fuel cell membrane assemblies source from Japanese and US specialty materials suppliers. Single-source vulnerability persists in platinum group metal refining. Distribution runs through manufacturer-direct calibration service networks for law enforcement consortia and third-party occupational health distributors for workplace screening protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between German metrology-grade calibration infrastructure costs and Eastern European enforcement modernization tenders, where MDR transitional provisions delay full compliance expenses.
For Market Incumbents: Lock in multi-force framework agreements with UK regional police consortia before calibration service contracts consolidate under third-party metrology providers. Accelerate semiconductor sensor certification through Netherlands-based notified bodies to offset platinum cost pressure in fuel cell architectures. Defensive patent filings around electrochemical-semiconductor hybrid designs protect against Dutch and Belgian R&D cluster entrants. For New Entrants and Emerging Players: MDR recalibration deadlines in Germany and France open a window for semiconductor-based portable units to penetrate state police procurement ahead of fuel cell incumbent refresh cycles. Target Polish and Romanian national police tenders requiring local language interfaces as the most penetrable geography. Pursue white-label partnerships with Nordic corporate wellness providers piloting disposable mouthpiece-integrated sensors. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor sensor specialists holding CE marking pathways through Netherlands notified bodies and pilot contracts with Dutch motorcycle-mounted officer kit programs. Five-to-ten year viability favors platforms capable of digital health data interoperability as EU-wide occupational health record portability rules crystallize. Watch for EMA coordination signals on multi-biomarker breath panel validation as inflection indicator for clinical diagnostic segment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Sensor Certification Acceleration | Netherlands notified bodies streamline CE marking pathways for metal oxide platforms entering law enforcement channels. |
| Multi-Force Calibration Framework Capture | UK regional police consortia consolidate service contracts, transferring aftermarket revenue to third-party metrology providers. |
| Disposable Device Protocol Development | Nordic corporate wellness providers pilot single-use sensors to eliminate cross-contamination liability in high-frequency testing. |
| Eastern European Tender Localization | Polish and Romanian police modernization programs require EU-certified systems with native language interface capabilities. |
| Digital Health Data Interoperability Investment | Connected breath analyzer outputs gain admissibility in occupational litigation as EU-wide record portability rules emerge. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with law enforcement procurement officers, occupational health program directors, biomedical engineers at notified bodies, and calibration service technicians with secondary validation against EMA reference standard documents, KBA type approval filings, SEC disclosures from listed device manufacturers, and Dutch and Belgian police pilot program tender records. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Historical reference periods anchored volume and value trajectories across the analysis window, with segmentation modeling across sensor technology tier, product form factor, end-user channel, and national regulatory compliance vintage. CAGRs derived from fitted growth curves incorporating platinum price index movements, MDR implementation phase transitions, and enforcement fleet replacement cycle schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt platinum supply disruption or accelerated EMA multi-biomarker validation timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Thrombus Precursor Protein Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Electrochemical Biosensors Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Non-Invasive Biosensors Market