
 Amniotic Fluid Detection Market | 2026-2036
Amniotic Fluid Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Amniotic Fluid Detection Market Outlook
Asset-light leasing models for point-of-care diagnostic equipment is narrowing the competitive field to firms with strong balance sheets and service networks. Medtronic leverages its hospital contracting infrastructure to place amniotic fluid detection systems under multi-year service agreements. QIAGEN sustains competitive position through R&D intensity in molecular diagnostic platforms. CooperSurgical anchors its presence in obstetric suites through specialized channel relationships with women's health clinics.
Amniotic fluid detection encompasses biochemical and biophysical methods for identifying ruptured membranes or assessing fetal wellbeing through analysis of vaginal fluid samples, typically measuring pH, insulin-like growth factor binding protein-1, or placental alpha microglobulin-1 concentrations with sensitivity thresholds above 90%. These technologies serve primarily to prevent preterm birth complications and guide clinical intervention timing in labor and delivery settings. Diagnostic kits command the largest revenue share due to standardized workflows and reimbursement alignment, while fluorescence-based platforms represent the fastest-expanding technology segment as laboratories automate high-throughput screening. Hospitals dominate end-user demand, though home care channels are gaining traction where remote maternal monitoring programs expand.
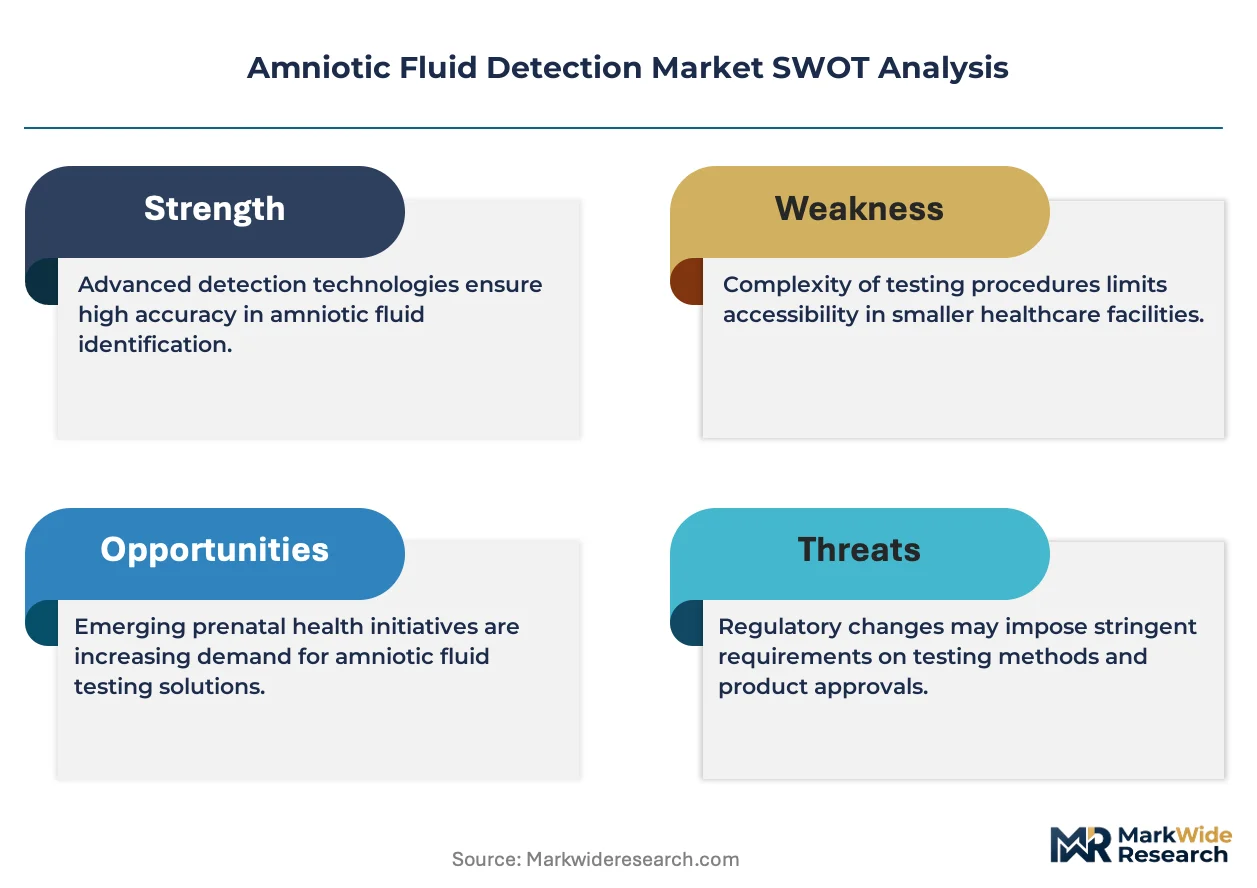
The FDA's 510(k) clearance pathway and Clinical Laboratory Improvement Amendments govern market entry for amniotic fluid detection products in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on manufacturers seeking CE marking for European distribution. These frameworks elevate barriers for new entrants but reward firms with established quality management systems and regulatory affairs capabilities. Stakeholders must weigh investment in multiplex assay development against the pace of payer acceptance for novel biomarker panels.
Market Dynamics
Hospital maternity wards are consolidating procurement around integrated diagnostic platforms, compressing vendor selection to firms capable of delivering bundled assay-instrument-service contracts rather than standalone test kits.
Growth Catalysts
- Point-of-care automation:Fluorescence-based detection systems are reducing turnaround times in labor and delivery units, enabling real-time clinical decision-making during active labor.
- CLIA-waived test expansion:The FDA's Clinical Laboratory Improvement Amendments pathway is broadening test deployment to satellite clinics and birth centers without full laboratory infrastructure.
- Preterm birth prevention protocols:Maternal-fetal medicine specialists in the United States are embedding amniotic fluid detection into standardized rupture-of-membranes triage workflows.
Market Restraints
- Reimbursement compression:CMS coding revisions for biochemical assays are narrowing margins on routine pH and protein marker tests.
- Supply concentration:Optical sensor components for fluorescence platforms depend on a limited base of German and Japanese precision optics manufacturers.
- Cross-reactivity limitations:Blood-contaminated vaginal samples generate false-positive readings for placental alpha microglobulin-1 assays, restricting test reliability in antepartum hemorrhage cases.
Strategic Opportunities
- Home-based monitoring programs:Remote maternal health initiatives in the United Kingdom are creating demand for patient-administered specimen collection devices paired with telemedicine interpretation.
- Multiplex assay development:Convergence of nucleic acid amplification with protein biomarker detection is enabling single-sample fetal lung maturity and infection screening.
- EU MDR transition window:Stricter clinical evidence requirements under the Medical Device Regulation are advantaging firms with established notified body relationships and quality management systems.
Industry Challenges
- Regulatory affairs specialization:Firms lack personnel capable of navigating simultaneous 510(k) premarket notifications and EU MDR technical documentation.
- Instrument-software integration:Legacy laboratory information systems require costly middleware development to interface with automated fluorescence readers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amniotic Fluid Detection Market |
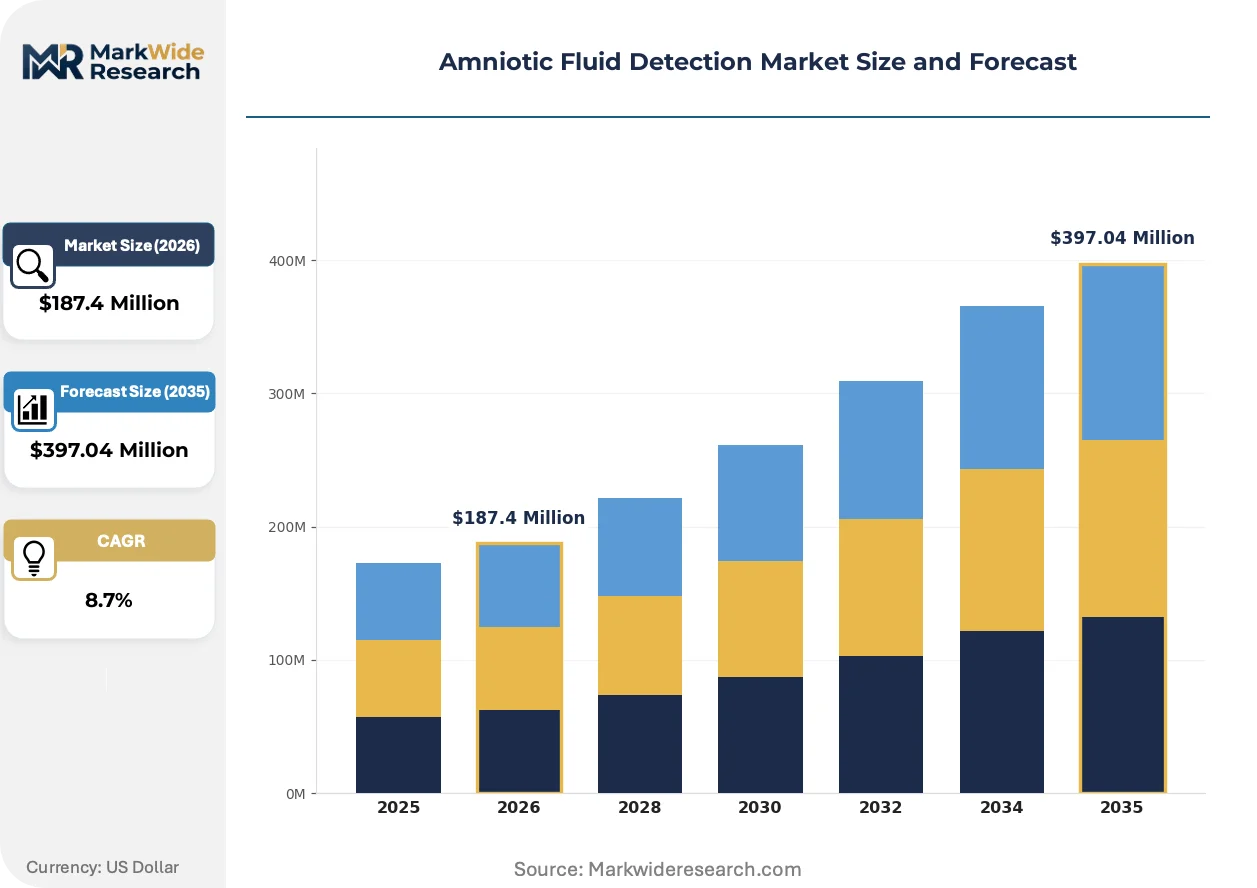
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Strips, Diagnostic Kits, Sensors, Reagents Technology: Colorimetry, Fluorescence, Spectroscopy, Enzyme Immunoassay End User: Hospitals, Diagnostic Labs, Clinics, Home Care Application: Pregnancy Diagnosis, Fetal Monitoring, Labor Assessment, Research Studies |
| Companies Covered | Medtronic, QIAGEN, Becton, Dickinson and Company, Integra Lifesciences, ELITechGroup, Cook Group, Thermo Fisher Scientific, CooperSurgical, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amniotic Fluid Detection Market Strategic Shifts
Digital connectivity and assay miniaturization are restructuring how amniotic fluid detection reaches clinical endpoints, with implications for capital deployment and service delivery models.
Artificial intelligence-enabled image analysis is virtualizing the interpretation of fluorescence signal patterns in point-of-care devices. Community hospitals and freestanding birth centers are adopting these systems to reduce dependence on specialized laboratory personnel. The technology is virtualizing expertise distribution, allowing centralized pathology oversight of geographically dispersed testing sites without on-site cytology training.
The FDA's 510(k) premarket notification pathway is tightening evidentiary standards for substantial equivalence claims in biochemical pregnancy tests. Manufacturers must now submit larger comparator studies and more robust analytical validation data. In vitro diagnostic firms with mature clinical affairs departments are accelerating clearance timelines while smaller entrants face extended development cycles.
Leasing arrangements for diagnostic platforms are displacing capital purchase models in hospital systems under margin pressure. Third-party equipment finance firms are inserting themselves between manufacturers and end-users, unbundling instrument placement from reagent supply contracts. This shift is most visible in United States health systems consolidating maternity services across multiple facility licenses.
Amniotic Fluid Detection Market Segmentation
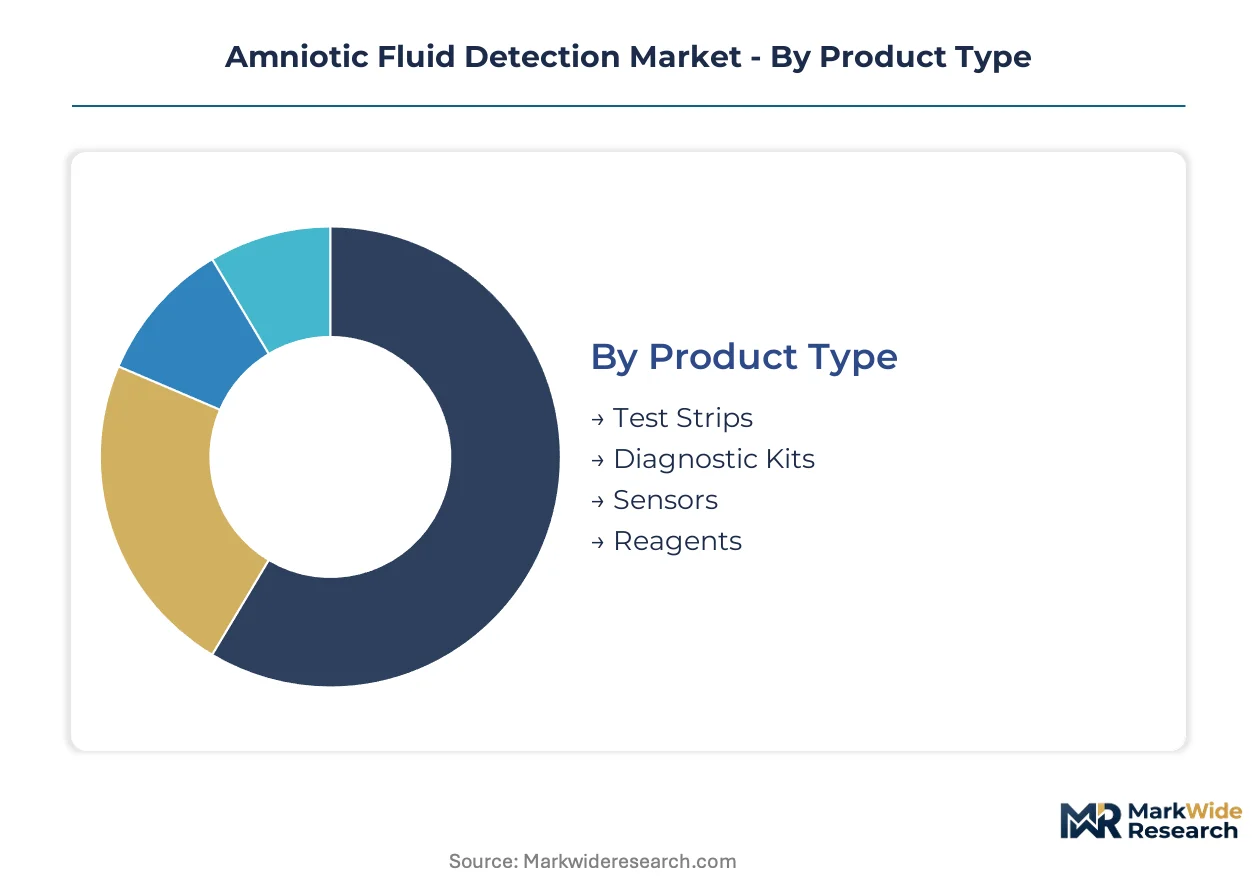
Amniotic fluid detection technologies serve distinct clinical workflows ranging from emergency labor triage to longitudinal fetal surveillance. Segmentation reveals how product form factors, detection chemistry, and care settings shape procurement patterns and reimbursement pathways across maternal-fetal medicine.
Product Type:
Use-case spectrum spans rapid qualitative screening in active labor through quantitative laboratory assays for complex cases.
- Diagnostic Kits:Integrated cassette-based systems combine sample collection with stabilized reagent chemistry for CLIA-waived deployment. Hospital maternity wards concentrate procurement around these standardized workflows due to alignment with CMS reimbursement codes for biochemical membrane rupture testing.
- Test Strips:Single-use nitrocellulose substrates impregnated with pH-sensitive dyes or antibody conjugates enable immediate visual interpretation. Demand clusters in birth centers and triage units where capital equipment placement is impractical and turnaround time governs clinical decisions.
- Sensors:Electrochemical and optical transducers provide continuous or sequential measurement capabilities for integrated diagnostic platforms.
- Reagents:Bulk antibody preparations, buffer systems, and calibration materials support laboratory-developed tests and research applications.
Established volume favors diagnostic kits; emerging adoption favors test strips.
Technology:
Detection chemistry maturity correlates with regulatory clearance breadth and automation compatibility.
- Fluorescence:Time-resolved fluorometry and Förster resonance energy transfer architectures achieve picomolar sensitivity for placental alpha microglobulin-1 and insulin-like growth factor binding protein-1 quantification. United States health systems with centralized laboratory infrastructure are expanding fluorescence platform placement under multi-year reagent rental agreements.
- Colorimetry:pH indicator and chromogenic substrate reactions deliver immediate visual results without instrumental readout. Cost-sensitive clinics and international markets with limited maintenance capabilities favor these low-complexity methods despite narrower analytical range.
- Enzyme Immunoassay:Horseradish peroxidase and alkaline phosphatase conjugate systems provide intermediate sensitivity for mid-volume laboratories.
- Spectroscopy:UV-Vis and infrared absorption methods support research-scale fetal lung maturity assessment and fluid composition profiling.
Fluorescence platforms are climbing the fastest as laboratories automate high-throughput screening; colorimetry retains dominant installed base in point-of-care settings.
End User:
Care setting determines regulatory pathway, staffing requirements, and reimbursement rate.
- Hospitals:Integrated labor and delivery units with 24-hour laboratory coverage perform the majority of membrane rupture confirmations using FDA-cleared platforms. These facilities negotiate enterprise contracts bundling instruments, assays, and service across multiple maternity licenses.
- Diagnostic Labs:Independent reference laboratories and hospital outreach programs process specimens from geographically dispersed obstetric practices. CLIA-certified high-complexity laboratories concentrate fluorescence-based testing for quantitative biomarker reporting.
- Clinics:Outpatient obstetric and maternal-fetal medicine practices perform initial screening under CLIA-waived certificates of waiver.
- Home Care:Remote maternal monitoring programs in the United Kingdom and select United States Medicaid managed care plans are piloting patient-collected specimens with telemedicine interpretation.
Hospital systems command procurement scale; home care channels are gaining share fastest through remote monitoring program expansion.
Application:
Clinical indication dictates sensitivity requirements, sample type, and frequency of testing.
- Pregnancy Diagnosis:Early gestation confirmation through biochemical markers in vaginal fluid samples supports prenatal care initiation. United States community health centers embed these tests into standardized intake protocols for uninsured patient populations.
- Fetal Monitoring:Serial amniotic fluid index assessment and biophysical profile components guide antepartum surveillance decisions. Maternal-fetal medicine specialists in academic medical centers concentrate demand for integrated ultrasound-biochemical assessment platforms.
- Labor Assessment:Rupture of membranes confirmation represents the highest-volume acute indication with immediate intervention implications.
- Research Studies:Biobanking and longitudinal cohort investigations require standardized collection devices and validated assay protocols.
Labor assessment generates procedure volume; fetal monitoring applications are expanding most quickly through risk-stratified surveillance protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification requirements and CLIA-waived test expansion policies are accelerating deployment patterns across maternal-fetal medicine infrastructure. Germany's notified body relationships under EU MDR are advantaging firms with established quality management systems. Japan's PMDA is tightening analytical validation standards for biochemical pregnancy diagnostics.
United States
Hospital maternity wards concentrate procurement around bundled assay-instrument-service contracts. CMS coding revisions for biochemical assays are compressing margins on routine pH and protein marker tests. The Research Triangle Park corridor in North Carolina anchors fluorescence platform R&D for high-throughput screening automation.
Germany
Precision optics manufacturers in Jena and Oberkochen supply optical sensor components for fluorescence-based detection systems. The EU Medical Device Regulation imposes stricter clinical evidence requirements on manufacturers seeking CE marking for European distribution. Bavaria's medical technology cluster around Munich hosts notified body relationships accelerating MDR transition timelines.
Japan
METI funding for point-of-care diagnostic automation is reducing turnaround times in labor and delivery units. PMDA is requiring larger comparator studies for substantial equivalence claims in biochemical pregnancy tests. The Kansai region around Osaka concentrates electrochemical sensor manufacturing for integrated diagnostic platforms.
United Kingdom
Remote maternal health initiatives are creating demand for patient-administered specimen collection devices paired with telemedicine interpretation. NHS England procurement frameworks favor CLIA-waived deployment to satellite clinics and birth centers. London's maternal-fetal medicine specialists are embedding amniotic fluid detection into standardized rupture-of-membranes triage workflows.
China
NMPA streamlined review pathways for in vitro diagnostic devices are shortening market entry timelines for fluorescence-based platforms. Provincial health commissions in Guangdong and Jiangsu are consolidating maternity service procurement across multiple facility licenses. The Yangtze River Delta around Shanghai anchors manufacturing scale for diagnostic kit production.
Amniotic Fluid Detection Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement environments. Hospital systems favor enterprise contracts bundling instruments, assays, and service, while birth centers prioritize low-complexity consumables. Three archetypes dominate: diversified medical technology conglomerates with hospital contracting infrastructure, molecular diagnostic specialists with R&D intensity in fluorescence platforms, and obstetric-focused firms with specialized women's health channel relationships. Competitive moves concentrate on multi-year service agreement placement and regulatory affairs capability accumulation.
Within the diversified medical technology tier, Medtronic and Thermo Fisher Scientific occupy positions anchored by broad hospital system relationships. QIAGEN exemplifies the molecular diagnostic specialist archetype through its emphasis on fluorescence platform development. CooperSurgical represents the obstetric-focused category with concentrated presence in specialized women's health channels. These three firms illustrate how regulatory affairs scale and service network density separate sustainable competitors from marginal participants in CLIA-waived and high-complexity laboratory segments.
| Leading Market Players |
|---|
| Medtronic |
| QIAGEN |
| Becton, Dickinson and Company |
| Integra Lifesciences |
| ELITechGroup |
| Cook Group |
| Thermo Fisher Scientific |
| CooperSurgical |
| Medline Industries |
| Others |
Value Chain & Pricing Dynamics
Freight corridors connecting German precision optics manufacturers to United States hospital systems impose cost volatility that amplifies price spreads between FDA-cleared fluorescence platforms and CLIA-waived test kits. This logistics tension concentrates pricing power with vendors who have secured multi-year reagent rental agreements, while forcing cost-sensitive birth centers toward lower-complexity colorimetry alternatives.
Pricing Analysis
Certification level creates the primary spread, with FDA 510(k)-cleared fluorescence systems commanding premium positioning against CE-marked alternatives. Three-tier pricing structure separates enterprise bundled contracts from standalone instrument placements and consumable-only procurement. Pricing pressure stems from CMS coding revisions compressing reimbursement for routine pH and protein marker tests. Birth centers and community clinics exhibit highest price sensitivity, while academic medical centers prioritize analytical sensitivity over unit cost.
Supply Chain Analysis
Optical sensor feedstocks draw from concentrated German and Japanese precision manufacturing clusters, with Jena and Oberkochen supplying time-resolved fluorometry components. Antibody conjugates and nitrocellulose substrates source from United States and Chinese bioprocessing facilities. Single-source vulnerability in specialized optical transducers creates procurement risk for fluorescence platform manufacturers. Distribution runs through third-party equipment finance firms that unbundle instrument placement from reagent supply, inserting intermediaries between manufacturers and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from remote maternal monitoring program expansion, which splinters demand across home care channels, satellite clinics, and traditional hospital laboratories that incumbent bundled contracts fail to capture.
For Market Incumbents: Build regulatory affairs scale as the primary moat by accumulating simultaneous 510(k) and EU MDR submission capabilities that smaller entrants cannot replicate. Deepen hospital contracting infrastructure to defend against molecular diagnostic specialists encroaching on fluorescence platform placement. Accumulate notified body relationships in Germany and Bavaria to accelerate MDR transition timelines before smaller competitors can adapt. For New Entrants and Emerging Players: Build out CLIA-waived test strip portfolios targeting United Kingdom remote maternal health initiatives and United States birth center networks where capital equipment placement is impractical. Penetrate home care channels through patient-administered specimen collection devices paired with telemedicine interpretation services. Pursue GPO contracts with community health centers serving uninsured populations as the fastest-access procurement pathway. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core obstetric diagnostics amid portfolio rationalization. Long-term viability hinges on regulatory affairs specialization and fluorescence platform R&D intensity rather than standalone kit manufacturing. Watch FDA evidentiary standard tightening for substantial equivalence claims as the signal indicating which smaller entrants will face extended development cycles and distressed positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Service Agreement Placement | Medtronic leverages hospital contracting infrastructure to lock in fluorescence platform adoption across maternity service consolidations. |
| CLIA-Waived Test Expansion | QIAGEN accelerates deployment to satellite clinics and birth centers without full laboratory infrastructure under FDA pathway. |
| EU MDR Transition Acceleration | Firms with Bavarian notified body relationships compress technical documentation timelines ahead of smaller competitors. |
| Home Care Channel Development | CooperSurgical pilots patient-collected specimens with telemedicine interpretation through United Kingdom NHS frameworks. |
| Multiplex Assay R&D Investment | Convergence of nucleic acid amplification with protein biomarker detection enables single-sample fetal lung maturity screening. |
Study Parameters
Initial hypotheses were tested against primary input from maternal-fetal medicine specialists, hospital procurement managers, biomedical engineers, and GPO contracts managers and refined through secondary validation. FDA 510(k) premarket notification databases, CMS Medicare reimbursement schedules, hospital procurement records, and EU MDR technical documentation filings anchored quantitative calibration. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down health system expenditure aggregation.
Demand-supply balance across the analysis window calibrated procedure volume forecasts against fluorescence platform manufacturing capacity and antibody conjugate production constraints. Segmentation dimensions modeled include product form factor, detection chemistry maturity, care setting regulatory pathway, and clinical indication urgency. CAGRs derived from weighted average of historical reimbursement trend extrapolation and technology substitution curve analysis, with fluorescence automation adoption and remote monitoring program expansion as primary industry-specific inputs.
Sensitivities concentrate around FDA evidentiary standard revisions, CMS coding updates for biochemical assays, and EU MDR implementation pace variations. Forecasts reflect documented assumptions regarding CLIA-waived test expansion timelines and hospital maternity ward consolidation patterns. Material shifts in fluorescence platform automation economics or telemedicine reimbursement policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Dual Energy X-Ray Absorptiometry Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
MRI Compatible Biopsy Devices Market