
 US Point of Care Diagnostics Market | 2026-2036
US Point of Care Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US Point of Care Diagnostics Market Insights
Urgent care centers are restructuring the traditional lab-hospital referral chain by embedding molecular diagnostics and immunoassay platforms directly into patient intake workflows. Abbott Laboratories dominates the glucose monitoring segment through retail pharmacy partnerships that extend its channel control beyond clinical settings. Roche Diagnostics anchors its position through R&D intensity in biosensor miniaturization that differentiates its instrument footprint from conventional lab equipment. Siemens Healthineers competes on manufacturing scale, sustaining geographic dominance across integrated delivery networks in the Midwest and Southeast.
Point of care diagnostics encompass portable analytical systems designed to deliver clinical-grade results at or near the patient location, typically operating with sample volumes below 500 microliters and turnaround times under 30 minutes for critical analytes. These devices serve the primary commercial purpose of decentralizing laboratory functions to accelerate clinical decision-making and reduce care escalation costs. Glucose monitors occupy the most mature margin pool, while infectious disease testing represents the fastest-expanding segment driven by respiratory panel adoption in urgent care centers. Microfluidics technology leads in innovation velocity, though immunoassay platforms still capture the largest installed base across clinics and home care settings.
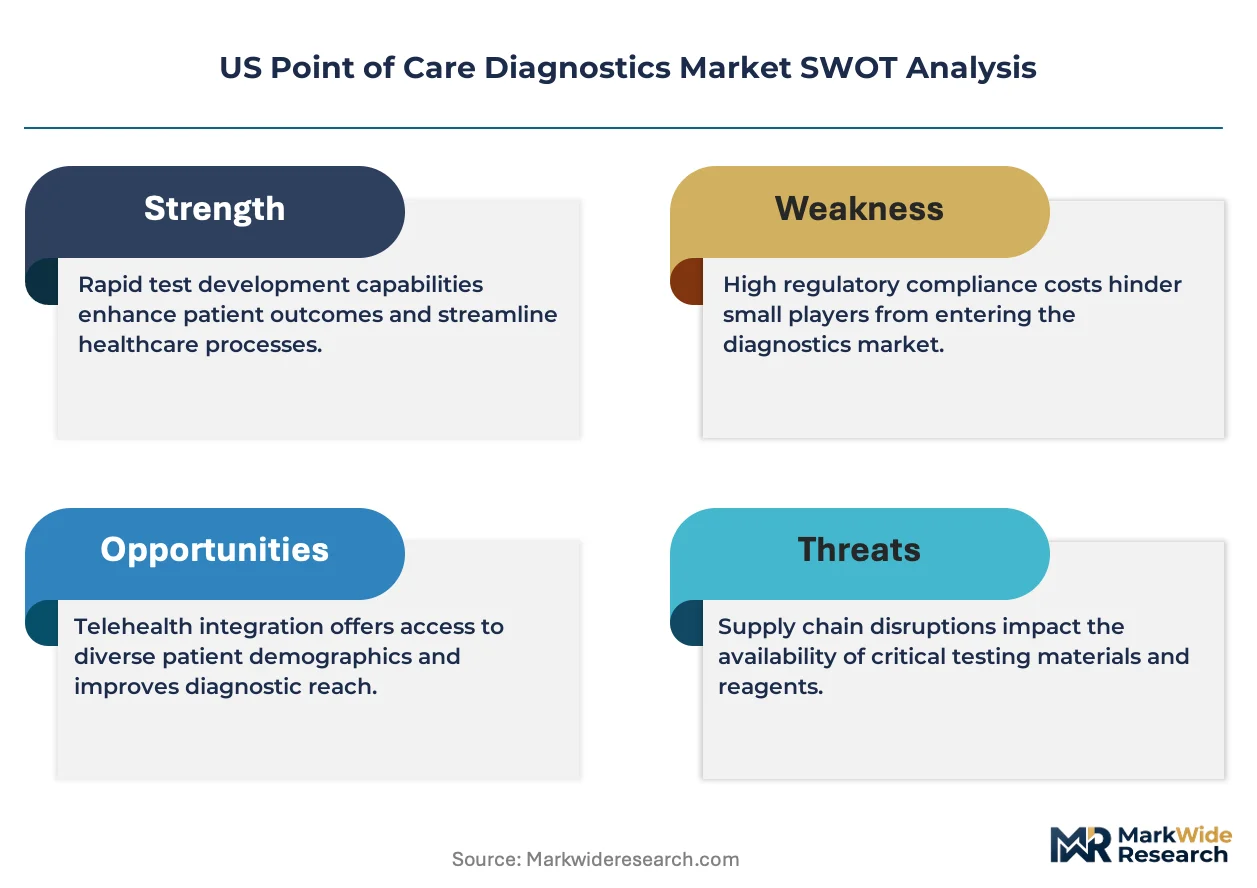
FDA oversight through the CLIA waiver program and 510(k) clearance pathways directly shapes product design priorities, pushing manufacturers toward simplified operator interfaces that qualify for waived complexity status. The Centers for Medicare & Medicaid Services reimbursement codes determine site-of-care economics, influencing whether health systems deploy devices in hospitals or push testing outward to affiliated clinics and home care settings. Stakeholders must monitor how evolving FDA guidance on artificial intelligence-enabled result interpretation reshapes the competitive boundary between automated and operator-dependent platforms.
Market Dynamics
Hospital emergency departments are compressing turnaround times through CLIA-waived molecular platforms, forcing manufacturers to prioritize simplified operator interfaces over laboratory-grade analytical performance. This operational imperative is reshaping R&D allocation across the competitive landscape.
Growth Catalysts
- CLIA Waiver Expansion:FDA's streamlined 510(k) pathways for waived complexity devices compress development-to-deployment cycles. Manufacturers now design for bedside operators rather than laboratory technicians.
- Health System Consolidation:Large integrated delivery networks in Texas and Florida are centralizing procurement across dozens of affiliated clinics, creating volume commitments that justify platform investments.
- Microfluidics Miniaturization:Biosensor advances enable sample volumes below 500 microliters, opening pediatric and geriatric applications where venipuncture is contraindicated.
Market Restraints
- Reimbursement Compression:CMS site-of-care coding distinctions create economic friction, pushing health systems to limit POCT deployment to settings with favorable technical payment rates.
- Supply Concentration Risk:Critical biosensor components concentrate among specialty contract manufacturers in Southeast Asia, exposing device makers to single-source vulnerabilities.
- Analytical Performance Ceiling:waived complexity instruments sacrifice sensitivity and specificity compared to central laboratory methods, restricting clinical utility for certain diagnostic applications.
Strategic Opportunities
- Home Care Penetration:Remote patient monitoring programs in California are expanding glucose and coagulation testing beyond clinical settings into Medicare Advantage home benefit structures.
- AI-Enabled Interpretation:Machine learning algorithms for result validation are integrating into portable platforms, potentially qualifying for new CPT codes that capture cognitive work.
- Respiratory Panel Expansion:Urgent care centers in the Midwest are adopting multiplex infectious disease assays that consolidate flu, RSV, and COVID detection into single cartridge workflows.
Industry Challenges
- Regulatory Talent Scarcity:The specialized expertise required for FDA 510(k) and CLIA waiver submissions commands premium compensation, constraining mid-tier manufacturers.
- Legacy System Interoperability:Hospital IT departments struggle to integrate POCT data streams into existing electronic health record architectures without custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Point of Care Diagnostics Market |
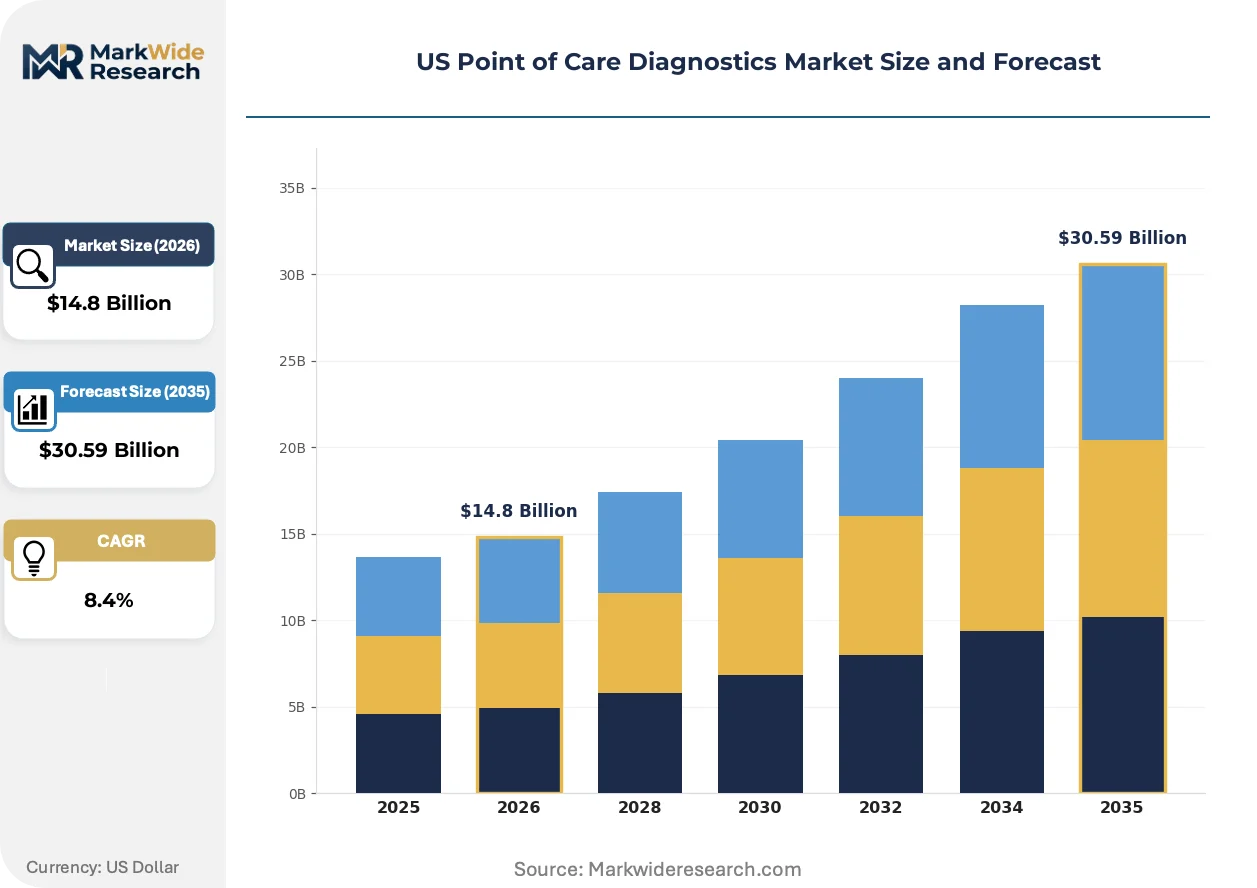
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Monitors, Rapid Tests, Infectious Disease Testing, Hemoglobin A1c Test Delivery Mode: Self-Testing, Laboratory Services, Telehealth Solutions, Mobile Testing Units End User: Clinics, Hospitals, Home Care Settings, Urgent Care Centers Technology: Immunoassay, Microfluidics, Molecular Diagnostics, Biosensors |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Danaher Corporation, BD, Thermo Fisher Scientific, bioMérieux, Quidel Corporation, QIAGEN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Point of Care Diagnostics Market Trends and Innovations
Portable analytical systems are converging with digital health infrastructure, creating new value capture mechanisms beyond device sales. This convergence is altering how manufacturers structure commercial relationships with health systems.
Microfluidics technology is integrating electrochemical and optical detection modalities into single-chip architectures. Urgent care chains and retail health clinics are adopting these platforms at accelerating pace. The technology is integrating previously separate sample preparation and analysis steps, compressing total assay time and reducing operator training burdens.
FDA guidance on artificial intelligence-enabled medical devices is clarifying validation requirements for algorithm-assisted result interpretation. Manufacturers must now submit clinical performance data specifically addressing software components. POCT developers with respiratory and cardiac assay portfolios are restructuring quality management systems to accommodate predetermined change control plans.
Health system procurement committees are consolidating vendor relationships around enterprise-wide platform agreements. Independent urgent care operators and physician-owned clinics face exclusion from these contracting vehicles. This concentration is most visible in Texas and Florida, where three large systems control the majority of outpatient diagnostic spending.
US Point of Care Diagnostics Market Segmentation
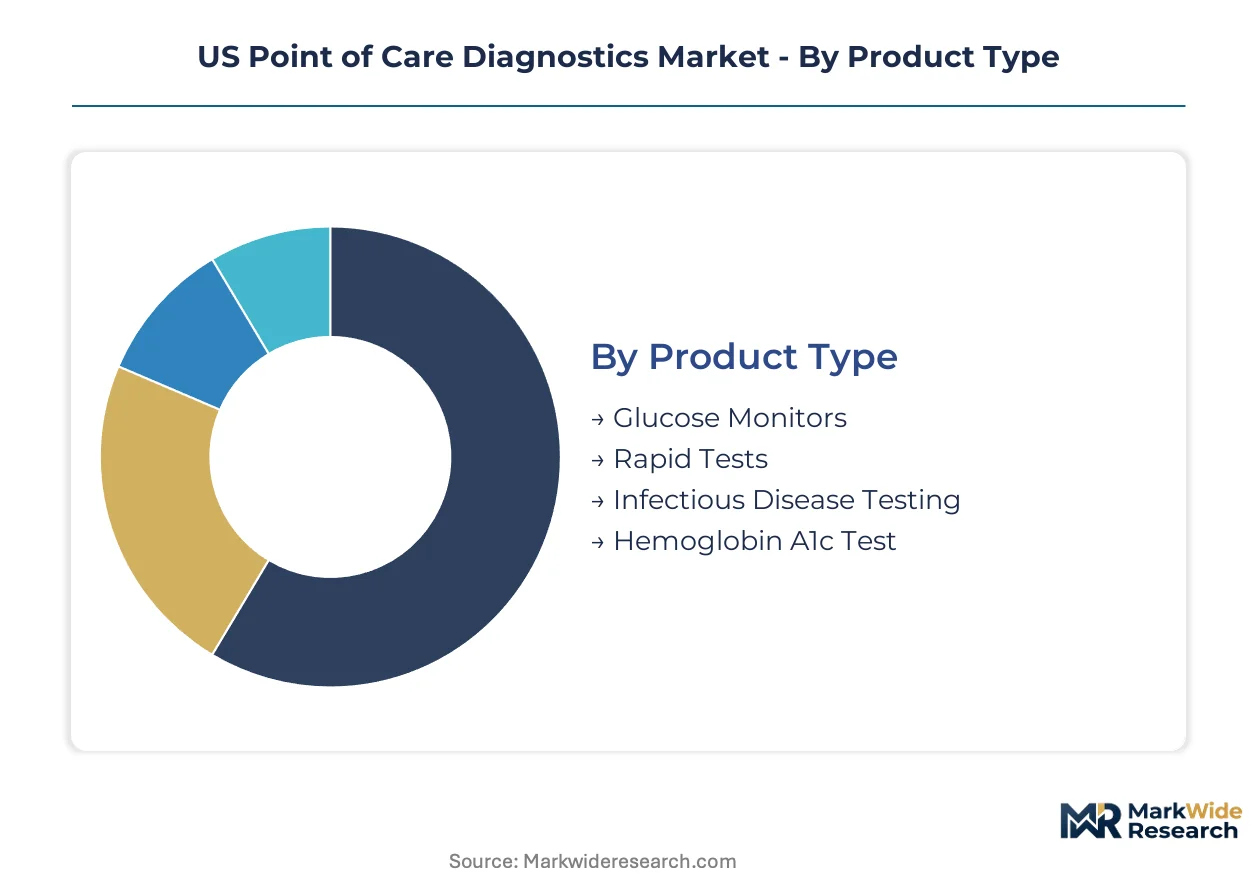
Point of care diagnostics segment along four intersecting dimensions that determine capital deployment, regulatory pathway, and reimbursement economics. Product type and technology choices lock in manufacturing scale requirements, while delivery mode and end-user targeting shape channel strategy and margin structure.
Product Type:
Capital intensity varies sharply across product categories, with molecular cartridge platforms requiring the highest upfront investment in precision molding and reagent stabilization infrastructure.
- Glucose Monitors:Electrochemical strip-based systems dominate retail pharmacy and home care channels. Texas and California health systems consolidate procurement of connected meter ecosystems across Medicare Advantage populations.
- Infectious Disease Testing:Multiplex respiratory panels integrate sample preparation and nucleic acid amplification into single-use cartridges. Urgent care centers in Florida deploy these platforms to reduce emergency department referrals during respiratory season.
- Rapid Tests:Lateral flow immunoassays serve screening applications with minimal operator training.
- Hemoglobin A1c Test:Benchtop analyzers support diabetes management in Federally Qualified Health Centers.
Most installed capacity flows through Glucose Monitors. Expansion is steepest in Infectious Disease Testing.
Delivery Mode:
Channel configuration determines regulatory burden and reimbursement tier, with laboratory-mediated services commanding distinct CPT coding from direct-to-patient models.
- Self-Testing:Home-use devices carry FDA 510(k) clearance with over-the-counter labeling. California's remote patient monitoring programs expand glucose and coagulation testing into Medicare Advantage home benefit structures.
- Laboratory Services:CLIA-waived platforms operated by non-laboratorians in physician offices. Texas integrated delivery networks centralize procurement across dozens of affiliated clinics.
- Telehealth Solutions:Cloud-connected devices enable asynchronous clinician review of patient-generated data.
- Mobile Testing Units:Deployable platforms serve rural and underserved geographies with limited fixed infrastructure.
Laboratory Services capture the dominant share of billable volume. Telehealth Solutions are gaining share fastest among new deployments.
End User:
Site-of-care selection drives FDA complexity classification and CMS reimbursement rate, creating divergent margin profiles across settings.
- Hospitals:Emergency departments compress turnaround times through CLIA-waived molecular platforms. Florida health systems prioritize bedside deployment to reduce admission bottlenecks.
- Urgent Care Centers:Retail health locations embed diagnostics directly into patient intake workflows. Midwest chains adopt multiplex infectious disease assays consolidating flu, RSV, and COVID detection.
- Clinics:Physician offices operate waived complexity devices with minimal regulatory overhead.
- Home Care Settings:Remote monitoring programs extend testing beyond clinical facilities.
Hospitals maintain the largest cumulative installed base. Urgent Care Centers show the steepest expansion trajectory.
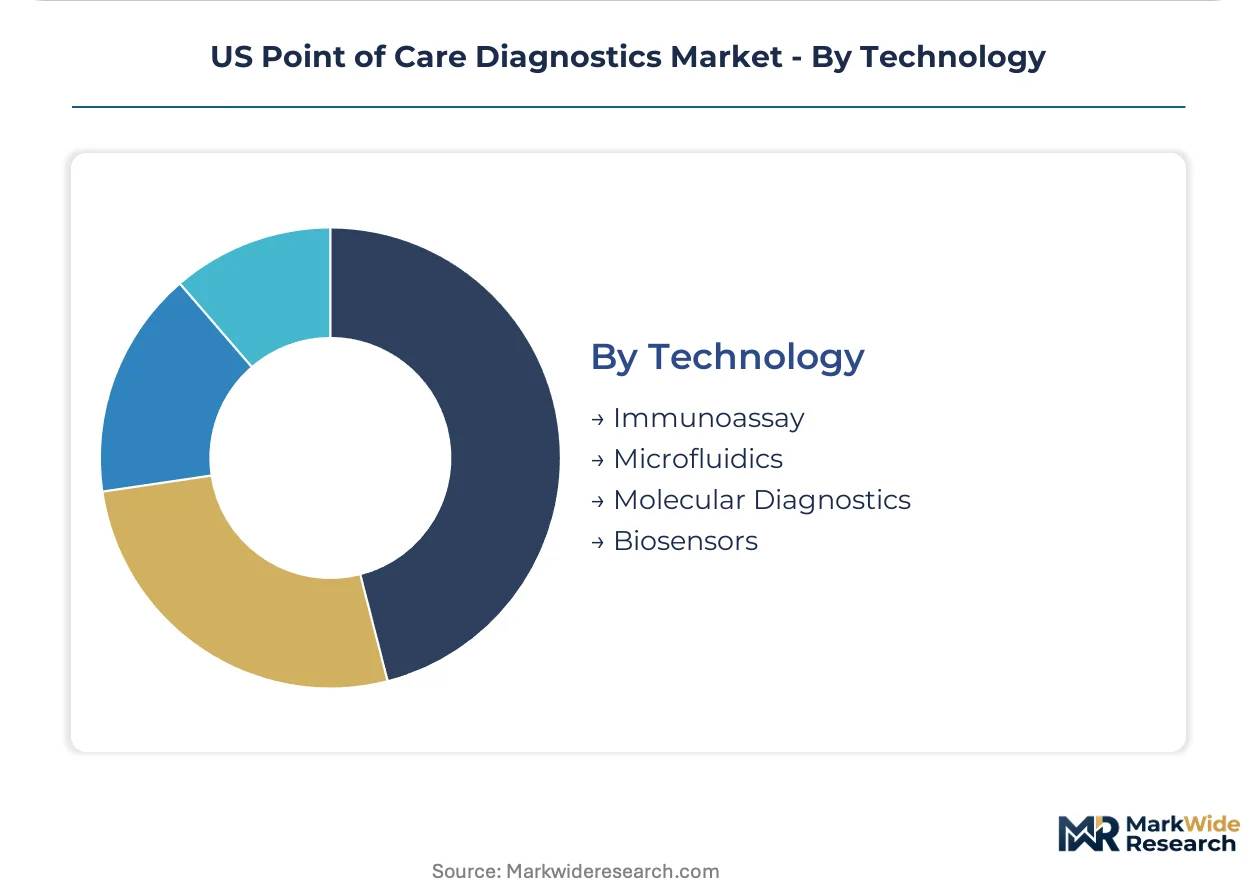
Technology:
Technology platform selection determines analytical performance ceiling, manufacturing partner ecosystem, and R&D amortization timeline.
- Microfluidics:Single-chip architectures integrate electrochemical and optical detection with sample volumes below 500 microliters. Urgent care chains adopt these platforms for pediatric and geriatric applications where venipuncture is contraindicated.
- Immunoassay:Antibody-based detection dominates the installed base across clinics and home care settings. Established supply chains and operator familiarity sustain platform persistence.
- Molecular Diagnostics:Nucleic acid amplification enables pathogen identification at low analyte concentrations.
- Biosensors:Miniaturized transducers support continuous monitoring applications.
Immunoassay platforms carry the largest legacy installed base. Microfluidics is climbing the fastest among new technology commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage drives device manufacturing toward states with streamlined FDA interaction pathways and concentrated regulatory expertise. Production clusters form where CLIA waiver consulting density lowers time-to-market for new platforms.
Texas
Integrated delivery networks in Dallas and Houston centralize procurement across dozens of affiliated clinics, creating volume commitments that justify molecular platform investments. State Medicaid reimbursement policies favor site-of-care testing over laboratory referrals. The Texas Medical Center anchors biosensor R&D partnerships with device manufacturers seeking clinical validation sites.
California
Medicare Advantage remote patient monitoring programs expand glucose and coagulation testing into home benefit structures, creating demand for connected meter ecosystems. FDA's Oakland district office shapes pre-submission strategies for AI-enabled interpretation features. The San Francisco Bay Area concentrates microfluidics startups targeting pediatric sample volumes below 500 microliters.
Florida
Health systems in Miami and Tampa prioritize bedside deployment to reduce emergency department admission bottlenecks during respiratory season. State licensure requirements for waived complexity devices align with federal CLIA standards, reducing compliance friction. The Orlando medical corridor hosts urgent care chains adopting multiplex infectious disease assays.
Midwest
Integrated delivery networks in Illinois and Ohio sustain geographic dominance through manufacturing scale advantages in instrument production. CMS regional payment determinations influence whether health systems deploy devices in hospitals or push testing outward to affiliated clinics. The Minneapolis medical device cluster supplies precision molding infrastructure for cartridge-based platforms.
Southeast
Urgent care expansion in Georgia and North Carolina embeds diagnostics directly into patient intake workflows, displacing traditional lab-hospital referral chains. State-level scope-of-practice regulations enable non-physician operators to run waived complexity devices. The Research Triangle Park anchors contract manufacturing for biosensor components.
US Point of Care Diagnostics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostics conglomerates controlling glucose monitoring while emerging players capture infectious disease testing growth. The market structure concentrates around three to five full-line suppliers with CLIA-waived portfolios spanning multiple analyte classes. Strategic archetypes include retail pharmacy channel masters, biosensor miniaturization specialists, and manufacturing scale leaders. Dominant competitive moves involve health system enterprise contracting and R&D partnerships for microfluidics integration.
Among diversified diagnostics conglomerates, Abbott Laboratories, Roche Diagnostics, and Siemens Healthineers occupy positions that exemplify distinct competitive vectors. Abbott represents retail pharmacy channel control extending beyond clinical settings. Roche anchors biosensor miniaturization differentiation from conventional lab equipment footprints. Siemens exemplifies manufacturing scale sustaining geographic dominance across integrated delivery networks. These three structures illustrate how device makers align capability investment with procurement committee consolidation trends in Texas and Florida health systems.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Danaher Corporation |
| BD |
| Thermo Fisher Scientific |
| bioMérieux |
| Quidel Corporation |
| QIAGEN |
| Others |
Pricing and Supply Chain Analysis
Microfluidics miniaturization is compressing per-unit manufacturing costs while concentrating precision molding expertise among Southeast Asian contract manufacturers, simultaneously lowering device price floors and amplifying single-source supply vulnerabilities for US-based OEMs.
Pricing Analysis
Distributor margins on CLIA-waived molecular platforms typically absorb 15-25 points before reaching hospital procurement committees. Pricing stratifies across premium, standard, and economy tiers based on analytical performance ceiling and after-sales service bundling. Cost compression in the standard tier is intensifying as Texas and Florida health systems consolidate enterprise contracts. Federally Qualified Health Centers exhibit the highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over per-test pricing.
Supply Chain Analysis
FDA 510(k) clearance and CLIA waiver qualification requirements gate entry for biosensor component suppliers, limiting approved vendor pools. Precision molding capacity concentrates in China, Taiwan, and South Korea. Reagent stabilization chemistries draw from specialty polymer suppliers in Germany and Japan. Tariff exposure on Chinese-sourced microfluidic substrates threatens margin stability. Distribution runs through regional medical device distributors with GPO contracting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US point of care diagnostics rests on microfluidics-driven cost-down trajectories and the premium-tier shift toward AI-enabled interpretation features.
For Market Incumbents: Cement platform stickiness through backward integration into cartridge manufacturing and exclusive GPO contracting with Texas and Florida health systems. Defend against emerging microfluidics specialists by accelerating FDA submissions for multiplex respiratory panels. Prioritize R&D investment in algorithm-assisted result validation to capture new CPT code economics. For New Entrants and Emerging Players: Independent urgent care operators in Georgia and North Carolina face exclusion from enterprise contracting vehicles and present a penetrable buyer archetype. Target Federally Qualified Health Centers with simplified operator interfaces requiring minimal training. Pursue telehealth-integrated distribution partnerships to bypass incumbent channel control. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier CLIA waiver consulting firms with specialized FDA submission expertise. Long-term viability favors platforms with respiratory and cardiac assay portfolios positioned for AI-enabled device guidance. Watch FDA predetermined change control plan adoption rates as an inflection indicator for algorithm-assisted platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA CLIA Waiver Submission | Accelerates bedside deployment timelines for molecular platforms in Florida emergency departments. |
| Hospital System Partnership | Secures volume commitments across dozens of affiliated clinics in consolidating Texas networks. |
| Software Companion Development | Enables AI-enabled result interpretation qualifying for new Medicare reimbursement codes. |
| Backward Integration into Cartridge Manufacturing | Reduces single-source dependency on Southeast Asian precision molding suppliers. |
| Reimbursement Strategy | Aligns platform deployment with CMS site-of-care coding favorable to urgent care settings. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and CLIA waiver regulatory consultants grounded the qualitative framework. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, hospital procurement records, and GPO contract disclosures. Bottom-up and top-down triangulation reconciled device shipment estimates with health system capital expenditure patterns.
Bottom-up modeling aggregated individual product category growth trajectories across the projection horizon. Segmentation dimensions included product type, technology platform, delivery mode, and end-user setting. CAGRs derived from historical volume trends and penetration rate assumptions specific to CLIA waiver expansion and health system consolidation dynamics. Forecast inputs incorporated respiratory panel adoption curves and remote patient monitoring program enrollment data.
Underlying measurement precision varies by segment; glucose monitoring carries tighter precision than emerging infectious disease testing categories. Forecasts reflect assumptions regarding FDA guidance evolution and CMS reimbursement stability. A model refresh is warranted upon material change in CLIA waiver approval timelines or health system enterprise contracting concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
US Breath Analyzers Market
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
United States Biopsy Devices Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Immunology-Oncology ELISA Kits Market
Diagnostic Devices
Lung Biopsy Systems Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market