
 Video Dermatoscope Market | 2026-2036
Video Dermatoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Video Dermatoscope Market Analysis
Aftermarket service revenue is tilting toward software maintenance and AI algorithm updates as hardware margins compress across the installed base. Canfield Scientific leverages its imaging platform dominance to sustain recurring revenue from dermatology networks. HEINE Optotechnik anchors its position through specialized optics manufacturing that competes on diagnostic precision in European clinics.
A video dermatoscope combines high-resolution digital imaging with polarized or non-polarized light sources to capture magnified skin surface and subsurface structures for clinical evaluation, typically achieving magnifications from 10x to 100x with integrated dermoscopy software for lesion documentation and tracking. Portable units lead volume sales due to flexibility across outpatient settings, while AI integration represents the fastest-expanding technology segment as vendors embed automated lesion classification algorithms. Optical coherence tomography occupies a premium niche in research institutions where subsurface imaging depth justifies higher capital expenditure.
FDA 510(k) clearance requirements and the EU MDR framework shape product development timelines and clinical validation burdens for manufacturers seeking market access. ISO 13485 quality management standards further constrain supply chain qualification for optical and sensor components. Stakeholders must monitor how reimbursement policies for teledermatology services evolve, as these will determine whether AI-enhanced video dermatoscopy achieves routine clinical financing or remains concentrated in self-pay aesthetic and screening programs.
Market Dynamics
AI algorithm integration is compressing diagnostic timelines and forcing hardware vendors to restructure R&D budgets toward software validation. The shift from standalone imaging devices to connected diagnostic platforms is redistributing value capture across the supply chain.
Growth Catalysts
- FDA 510(k) digital pathology pathway:Streamlined clearance for AI-enhanced devices accelerates commercialization timelines for manufacturers targeting teledermatology networks.
- Polarized light dermoscopy:Enhanced subsurface visualization capabilities expand clinical utility beyond pigmented lesion assessment into inflammatory and vascular conditions.
- Germany skin cancer screening mandate:Statutory early-detection programs drive systematic procurement of video dermatoscopy systems across dermatology clinics and primary care networks.
Market Restraints
- CMOS sensor supply concentration:Reliance on East Asian semiconductor foundries creates vulnerability to export control disruptions and capacity allocation constraints.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations extend validation timelines and inflate regulatory compliance costs for CE marking.
- Smartphone dermoscopy attachments:Low-cost consumer-grade alternatives threaten price positioning at the primary care entry segment.
Strategic Opportunities
- Japan rural teledermatology expansion:Government-funded connectivity infrastructure programs create addressable demand in underserved prefectures lacking specialist access.
- Optical coherence tomography-AI fusion:Convergence of volumetric imaging with automated segmentation algorithms opens premium research and referral center segments.
- Subscription-based software licensing:Recurring revenue models for algorithm updates and cloud storage displace capital-intensive hardware refresh cycles.
Industry Challenges
- Computational pathology skill scarcity:Shortage of trained dermoscopists capable of validating AI outputs limits deployment velocity in community health settings.
- ISO 13485 supplier qualification:Optical component vendors face extended audit timelines, constraining production scaling for qualified device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Dermatoscope Market |
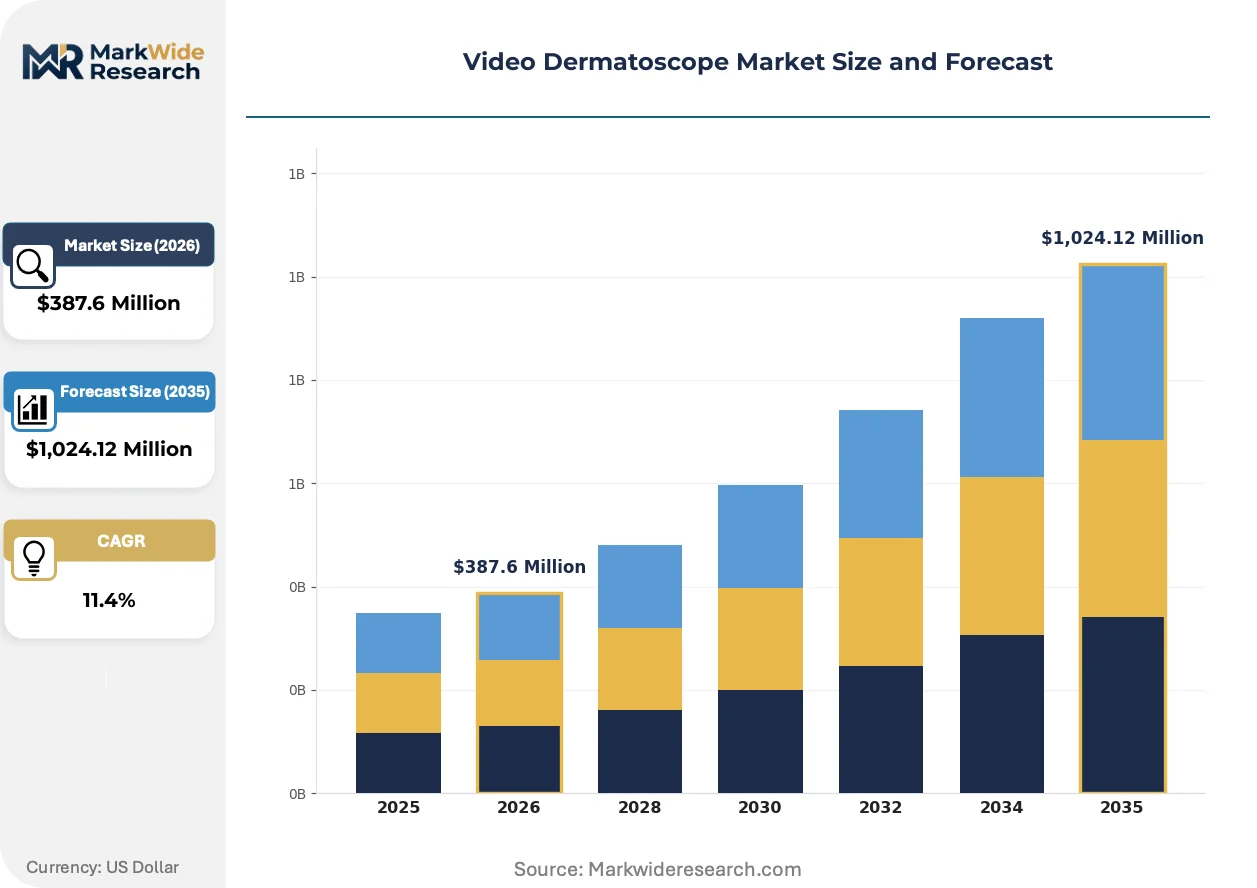
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Digital Cameras, Software Solutions, Fixed Systems Technology: LED Illumination, Optical Coherence Tomography, Image Capture Techniques, AI Integration End User: Dermatology Clinics, Research Institutions, Hospitals, Aesthetic Centers Application: Skin Cancer Screening, Cosmetic Procedures, Dermatological Research, Teledermatology |
| Companies Covered | Canfield Scientific, Inc., Dynamify GmbH, Caliber Imaging & Diagnostics, NIDEK CO., LTD., Firefly Global, FotoFinder Systems, Inc., DermoScan GmbH, Optomed Plc., HEINE Optotechnik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Dermatoscope Market Emerging Trajectories
Deep learning architectures are displacing rule-based image analysis and forcing restructuring of clinical workflow software. Vendors now compete on algorithm training data scale and regulatory clearance breadth rather than hardware specifications alone.
Convolutional neural networks for lesion classification are digitizing diagnostic decision support in dermatology clinics. Academic medical centers in the United States and Germany are deploying these systems for triage prioritization. The technology is digitizing documentation workflows and compressing specialist consultation queues.
The EU MDR framework is tightening clinical performance validation requirements for digital pathology devices. Manufacturers must generate prospective clinical evidence rather than relying on equivalence predicates. Class IIa device reclassifications are delaying market access for AI-integrated systems.
Hospital procurement departments are consolidating vendor relationships around integrated imaging platforms. Standalone device suppliers face displacement by enterprise software contracts bundling hardware, algorithms, and cloud storage. This concentration is most visible in United States integrated delivery networks and German hospital chains.
Video Dermatoscope Market Segmentation
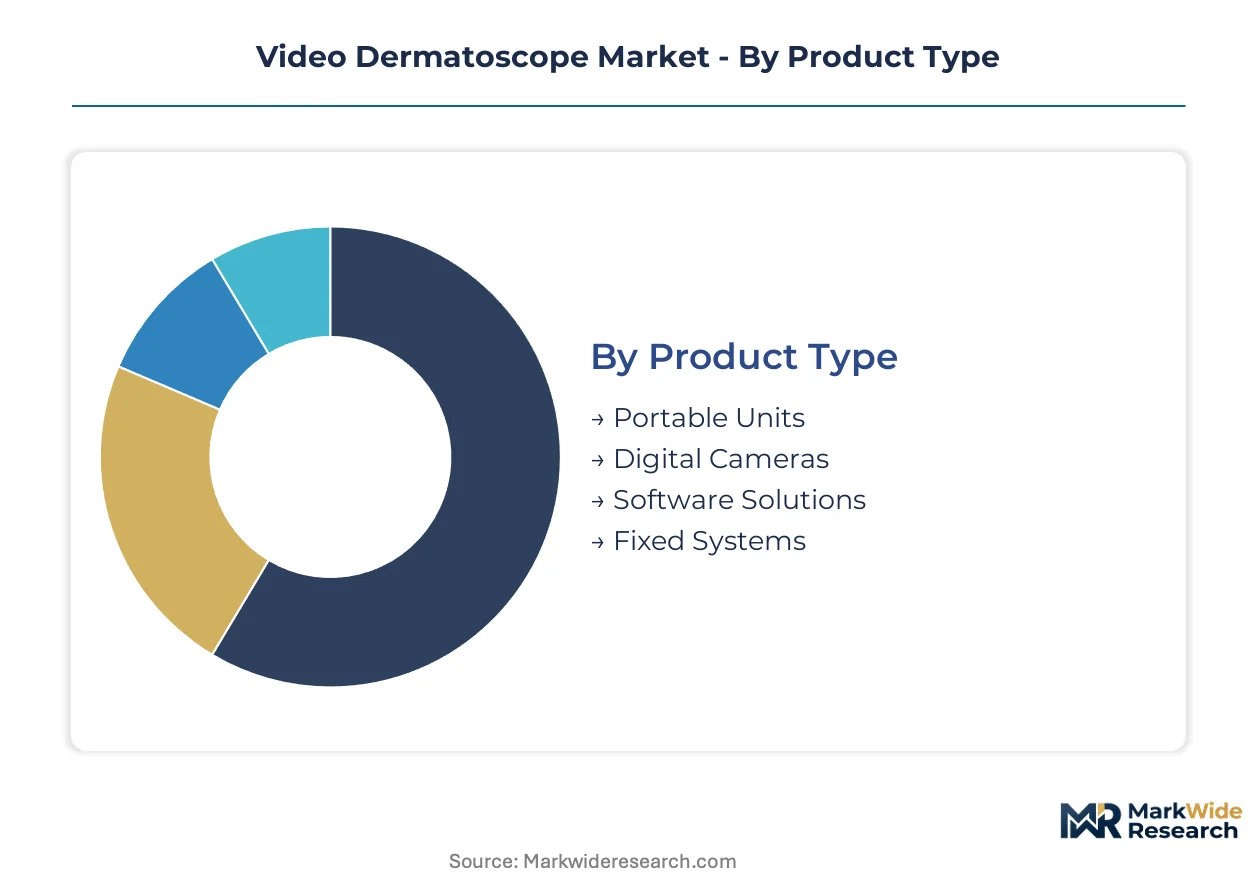
Segmentation in video dermatoscopy reveals how hardware commoditization, AI value migration, and care setting diversification are restructuring vendor priorities. Understanding these divides clarifies where R&D budgets concentrate and which customer relationships yield recurring revenue.
Product Type:
Mature hardware formats dominate installed base volumes while software monetization models reshape emerging revenue streams.
- Portable Units:Handheld devices with rechargeable power and wireless connectivity serve outpatient workflows across dermatology clinics and primary care networks. Demand concentrates in Germany and Japan where statutory screening programs require point-of-care deployment flexibility. Battery life and image stabilization specifications determine competitive positioning in this segment.
- Digital Cameras:Dedicated imaging modules with CMOS sensors and polarized light sources attach to standard dermatoscope optics for high-resolution capture. Dermatology clinics in the United States prioritize these for lesion documentation compliance under teledermatology reimbursement protocols.
- Software Solutions:Cloud-based lesion management platforms with AI classification algorithms and longitudinal tracking databases.
- Fixed Systems:Permanent installation units with integrated examination chairs and networked storage for high-throughput hospital departments.
Portable units retain volume leadership; software solutions hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium imaging modalities from scalable illumination and algorithmic components.
- LED Illumination:Solid-state light engines with tunable wavelength outputs enable polarized and non-polarized dermoscopy without thermal degradation. This technology anchors mid-market device economics across European and North American manufacturing.
- Optical Coherence Tomography:Volumetric subsurface imaging using interferometric detection achieves cellular-level resolution for research applications. Academic medical centers in Germany and Japan justify capital expenditure through grant-funded dermatological research programs.
- Image Capture Techniques:Standardized photography protocols including contact and non-contact methods for lesion documentation.
- AI Integration:Deep learning inference engines for automated lesion classification and malignancy risk scoring.
LED illumination retains volume leadership; AI integration commands the steepest expansion trajectory.
End User:
Customer type concentration determines whether procurement follows hospital capital budgets, clinic operating expenditures, or research grant cycles.
- Dermatology Clinics:Specialist practices with high lesion throughput and established teledermatology workflows drive replacement demand for connected diagnostic platforms. United States integrated delivery networks and German clinic chains consolidate vendor relationships around bundled hardware-software contracts.
- Hospitals:Multi-department health systems with pathology integration requirements and enterprise IT governance standards.
- Research Institutions:Academic centers with NIH, DFG, or AMED funding for dermatological imaging validation studies.
- Aesthetic Centers:Cosmetic medicine practices with self-pay screening and mole mapping services.
Dermatology clinics retain volume leadership; aesthetic centers are climbing the fastest.
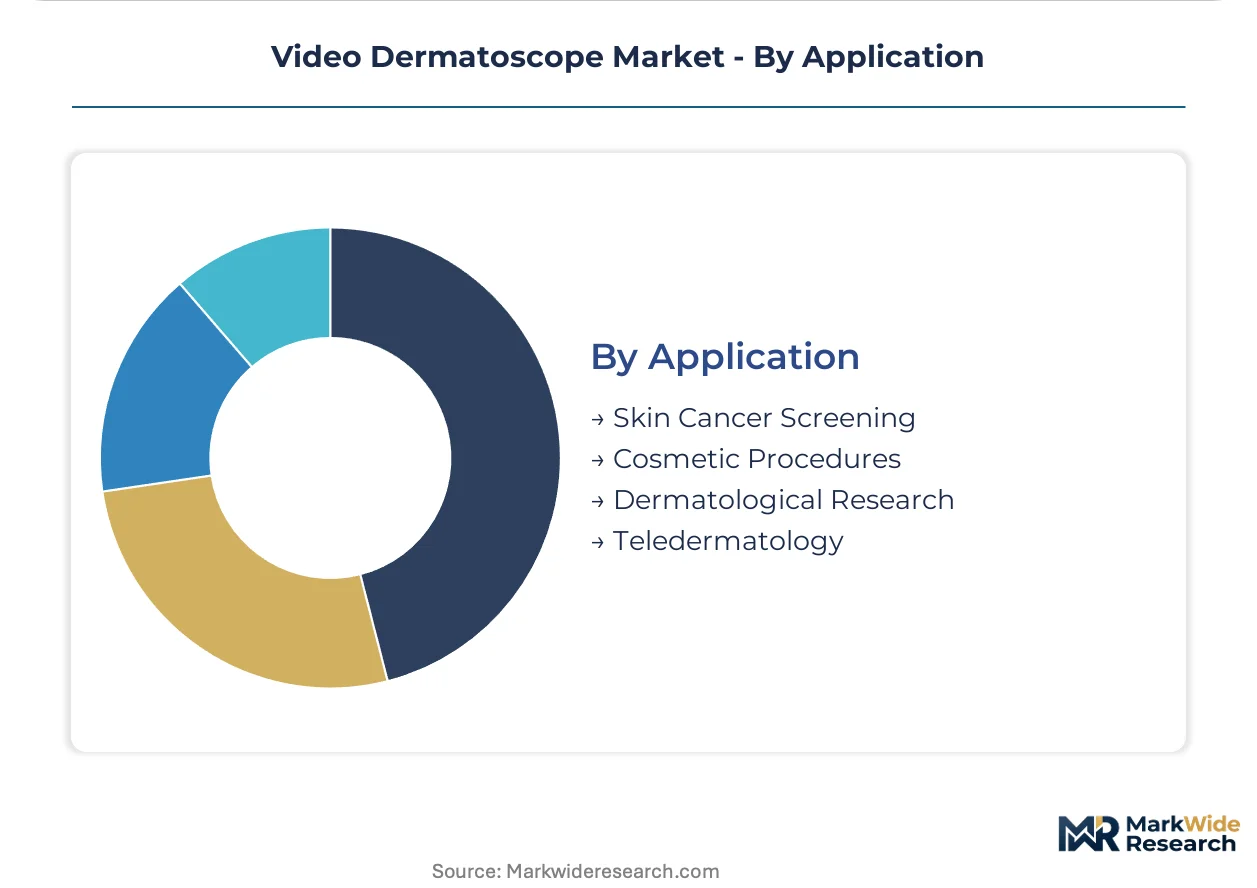
Application:
Geography-specific reimbursement policies segment demand between publicly financed screening programs and private aesthetic services.
- Skin Cancer Screening:Systematic early-detection workflows for melanoma and non-melanoma lesions in insured populations. Germany's statutory skin cancer screening mandate creates concentrated procurement demand across primary care and specialist networks.
- Teledermatology:Remote diagnostic workflows combining image capture, AI triage, and specialist consultation for underserved regions. Japan's rural connectivity infrastructure programs expand addressable demand in prefectures lacking dermatologist density.
- Dermatological Research:Longitudinal lesion tracking and algorithm training data collection for clinical validation studies.
- Cosmetic Procedures:Pre-treatment assessment and post-procedure monitoring in aesthetic medicine practices.
Skin cancer screening retains volume leadership; teledermatology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary care networks in Germany demonstrate the lowest price elasticity as statutory screening mandates guarantee reimbursement, while aesthetic centers in the United States exhibit the highest sensitivity to capital expenditure cycles. Japan's rural prefectures occupy an intermediate position where government connectivity subsidies offset hardware costs but algorithm licensing fees remain contested.
United States
Integrated delivery networks in Texas and Florida are consolidating vendor contracts around bundled teledermatology platforms that combine hardware, AI algorithms, and cloud storage. FDA 510(k) clearance timelines for AI-enhanced devices have compressed from 18 months to 9 months for predicate-established submissions. The Boston-Cambridge corridor anchors validation studies for convolutional neural networks at academic medical centers with NIH funding.
Germany
Statutory skin cancer screening mandates under the G-BA framework drive systematic procurement across Bavarian and North Rhine-Westphalian clinic chains. EU MDR clinical evidence requirements have extended CE marking timelines for AI-integrated systems to 24 months. The Heidelberg-Mannheim medical technology cluster concentrates optical engineering talent for polarized light dermatoscope manufacturing.
Japan
METI-funded rural connectivity infrastructure programs expand addressable demand in Hokkaido and Tohoku prefectures lacking dermatologist density. PMDA consultation pathways for SaMD-classified lesion classification algorithms are stabilizing after 2023 regulatory guidance revisions. The Osaka-Kobe corridor hosts manufacturing partnerships between precision optics suppliers and device assemblers targeting domestic hospital procurement.
United Kingdom
NHS England teledermatology tariff reforms are shifting procurement from capital budgets to per-consultation operating expenditures in Greater Manchester and West Midlands networks. MHRA recognition of FDA 510(k) clearances accelerates parallel market entry for US-validated AI devices. The Cambridge-London corridor concentrates digital pathology research institutions generating training data for algorithm developers.
Australia
Medicare reimbursement for store-and-forward teledermatology is expanding addressable demand in Queensland and Western Australia where specialist access gaps persist. TGA inclusion of international standards for software as a medical device reduces duplication of validation studies for EU-cleared systems. The Sydney-Melbourne corridor anchors melanoma research programs that supply longitudinal lesion databases for algorithm training.
Video Dermatoscope Market Vendor Landscape
Capability concentration sits with specialized optics manufacturers; scale advantage sits with imaging platform consolidators. The market structure bifurcates between precision-engineering specialists commanding premium pricing in European clinics and software-integrated platform vendors capturing recurring revenue through algorithm subscriptions. Three archetypes dominate: optical component specialists, AI-integrated platform providers, and teledermatology workflow bundlers. Competitive moves center on strategic partnerships between hardware OEMs and cloud infrastructure providers, plus portfolio diversification into adjacent aesthetic imaging modalities.
Within the precision-optics tier, HEINE Optotechnik GmbH & Co. KG and NIDEK CO., LTD. exemplify manufacturing depth that anchors diagnostic credibility in hospital procurement evaluations. Canfield Scientific, Inc. occupies a position representing the platform-consolidation archetype where software recurring revenue displaces hardware margin dependence. These three entities collectively illustrate how vendor positioning stratifies between component excellence and ecosystem control.
| Leading Market Players |
|---|
| Canfield Scientific, Inc. |
| Dynamify GmbH |
| Caliber Imaging & Diagnostics |
| NIDEK CO., LTD. |
| Firefly Global |
| FotoFinder Systems, Inc. |
| DermoScan GmbH |
| Optomed Plc. |
| HEINE Optotechnik GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
CMOS sensor supply concentration in East Asian foundries exposes video dermatoscope manufacturers to dual-use export control disruptions that simultaneously widen pricing spreads between qualified and unqualified supply tiers and force device assemblers toward multi-source qualification programs.
Pricing Analysis
Software maintenance and AI algorithm update contracts now drive lifetime customer value as hardware margins compress across installed bases. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-integrated platforms from CE-marked clinical devices and unregulated smartphone attachments. Pricing pressure stems from low-cost consumer dermoscopy alternatives entering primary care segments. Aesthetic centers in the United States exhibit the highest price sensitivity, while German dermatology clinics under statutory screening mandates show the least.
Supply Chain Analysis
Precision optical components and CMOS image sensors feed from concentrated manufacturing bases in Germany, Japan, and Taiwan. German optics suppliers anchor polarized light engine production, Japanese sensor fabricators dominate high-resolution CMOS output, and Taiwanese foundries handle semiconductor packaging. Single-source vulnerability in specialized dermatoscope-grade lenses constrains scaling velocity. Distribution runs through authorized medical device distributors with ISO 13485 certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Video dermatoscope demand cycles track government-funded screening program procurement waves and teledermatology reimbursement policy adjustments.
For Market Incumbents: Pre-empt smartphone attachment erosion by bundling cloud-based AI triage services with hardware contracts at price points that consumer alternatives cannot match. Deepen backward integration into CMOS sensor qualification pipelines to secure allocation priority during semiconductor capacity crunches. Anchor hospital system relationships through enterprise IT integration capabilities that standalone device vendors cannot replicate. For New Entrants and Emerging Players: Rural Japanese prefectures lacking dermatologist density represent the most penetrable entry point for connected diagnostic platforms leveraging government connectivity subsidies. AI-native software vendors without hardware heritage should pursue white-label partnerships with established optics manufacturers to bypass ISO 13485 supplier audit timelines. Target subscription-based algorithm licensing to German clinic chains seeking operational expenditure flexibility under EU MDR compliance pressures. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform consolidators with recurring software revenue over pure-play hardware manufacturers. Long-term viability over the next decade hinges on regulatory clearance breadth across FDA, CE marking, and PMDA jurisdictions. Monitor PMDA SaMD guidance evolution as the signal indicating whether AI-integrated systems achieve routine reimbursement or remain concentrated in self-pay segments.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Regulatory Clearance | FDA 510(k) and CE marking for lesion classification algorithms unlocks hospital procurement and teledermatology reimbursement. |
| Cloud Platform Integration | Enterprise IT contracts with United States integrated delivery networks displace standalone device vendors through bundled workflow solutions. |
| Optical Component Backward Integration | In-house polarized light engine production insulates margins from German and Japanese supplier qualification bottlenecks. |
| Teledermatology Reimbursement Strategy | Medicare and G-BA tariff alignment determines whether AI-enhanced screening achieves routine clinical financing. |
| Research Institution Partnership | NIH, DFG, and AMED grant-funded validation studies generate training data and clinical evidence for algorithm development. |
Methodological Framework
Operator-level perspectives from dermatology clinic directors, hospital biomedical engineers, GPO contracts managers, and regulatory affairs specialists anchored the qualitative base. Secondary validation drew from FDA 510(k) clearances, EU MDR technical documentation, PMDA SaMD guidance, and hospital procurement databases. Bottom-up unit economics and top-down epidemiological modeling were triangulated to reconcile volume estimates.
Scenario-bracketing across regulatory clearance timelines, reimbursement policy trajectories, and semiconductor supply availability framed the projection horizon. Segmentation dimensions modeled include product format, illumination technology, AI integration depth, end-user setting, and application type. CAGRs were derived from fitted growth curves calibrated to historical procurement data and forward policy commitments. Algorithm training data scale and clinical validation study completion rates served as industry-specific forecast inputs.
Stress conditions across CMOS export control escalation, EU MDR reclassification delays, and teledermatology tariff reversals were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about screening program expansion and AI reimbursement integration. Cross-checking against national health expenditure accounts and medical device import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Body Contouring Devices Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Neuromodulation Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Patellar Implant Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
Global Abutment Implants Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Active Wheelchair Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Microdebrider Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
North America Intraocular Lens Market