
 Calprotectin Serum Immunoassay Market | 2026-2036
Calprotectin Serum Immunoassay Market Size, Share, and Industry Trends Forecast 2026-2036
Calprotectin Serum Immunoassay Market Analytics
The EU In Vitro Diagnostic Regulation is repositioning procurement criteria across European hospital networks, favoring assays with documented clinical validation and traceable calibrator chains. BÜHLMANN Laboratories leverages its Swiss manufacturing base to sustain supply continuity for high-complexity immunoassay platforms. Thermo Fisher Scientific dominates distribution infrastructure across North American reference laboratories. DiaSorin anchors its competitive position through chemiluminescent assay integration with automated analyzer ecosystems.
Calprotectin serum immunoassay quantifies the S100A8/A9 heterodimer protein complex in blood specimens, typically measured in nanograms per milliliter with functional sensitivity thresholds around 20 ng/mL, serving as a non-invasive biomarker for systemic inflammation and neutrophil activation in clinical and research settings. ELISA Kits retain the largest installed base among product formats due to established protocol familiarity and lower capital requirements, while CLIA Kits capture the fastest expansion as laboratories seek higher throughput and reduced manual intervention. Automated Analyzers within the technology dimension concentrate margin pools through reagent rental agreements and long-term service contracts that lock in consumable volumes.
FDA 510(k) clearance pathways and the EU IVDR conformity assessment framework shape product development timelines and market access costs for manufacturers seeking dual-territory commercialization. Germany's national reimbursement authority, the G-BA, evaluates diagnostic utility evidence for serum calprotectin in differentiated inflammatory bowel disease monitoring protocols. Stakeholders must monitor evolving payer evidence requirements and automated platform compatibility standards as determinants of competitive viability in this assay category.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing commercialization timelines for serum calprotectin assays, forcing manufacturers to front-load clinical validation investments before CE-IVD certification becomes mandatory for European market access.
Growth Catalysts
- IVDR Conformity Pressure:The EU IVDR framework is accelerating hospital procurement of CE-IVD certified assays, as laboratories face 2028 deadlines for transitioning legacy diagnostic products.
- IBD Monitoring Protocols:German and US clinical guidelines are incorporating serum calprotectin as a non-invasive alternative to endoscopic surveillance, expanding test volumes in hospital-based laboratories.
- Automation Migration:High-throughput chemiluminescent platforms are displacing manual ELISA workflows, creating replacement demand among reference laboratories seeking labor cost reduction.
Market Restraints
- Reagent Rental Lock-in:Automated analyzer ecosystems enforce long-term consumable contracts that raise switching costs for laboratories considering alternative assay suppliers.
- Calibrator Traceability Costs:IVDR-mandated metrological traceability chains require expensive reference material sourcing, compressing margins for lower-volume assay manufacturers.
- Fecal Calprotectin Substitution:Established stool-based testing retains reimbursement advantages in primary IBD screening, limiting serum assay penetration in initial diagnostic workups.
Strategic Opportunities
- US Reference Laboratory Expansion:Unpenetrated regional hospital networks in the American Midwest and Mountain West present whitespace for automated platform placement.
- Sepsis Biomarker Positioning:Emerging critical-care applications for neutrophil activation monitoring could extend serum calprotectin beyond gastroenterology into emergency medicine protocols.
- Swissmedic Fast-Track Pathways:Switzerland's streamlined certification for innovative diagnostics offers early revenue generation while EU IVDR assessments proceed.
Industry Challenges
- Clinical Laboratory Scientist Shortages:Automated platform complexity demands specialized training that outpaces workforce pipeline output in US and German markets.
- Dual-Territory Validation Burden:Synchronous FDA 510(k) and EU IVDR submissions require parallel clinical studies, straining R&D budgets and extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calprotectin Serum Immunoassay Market |
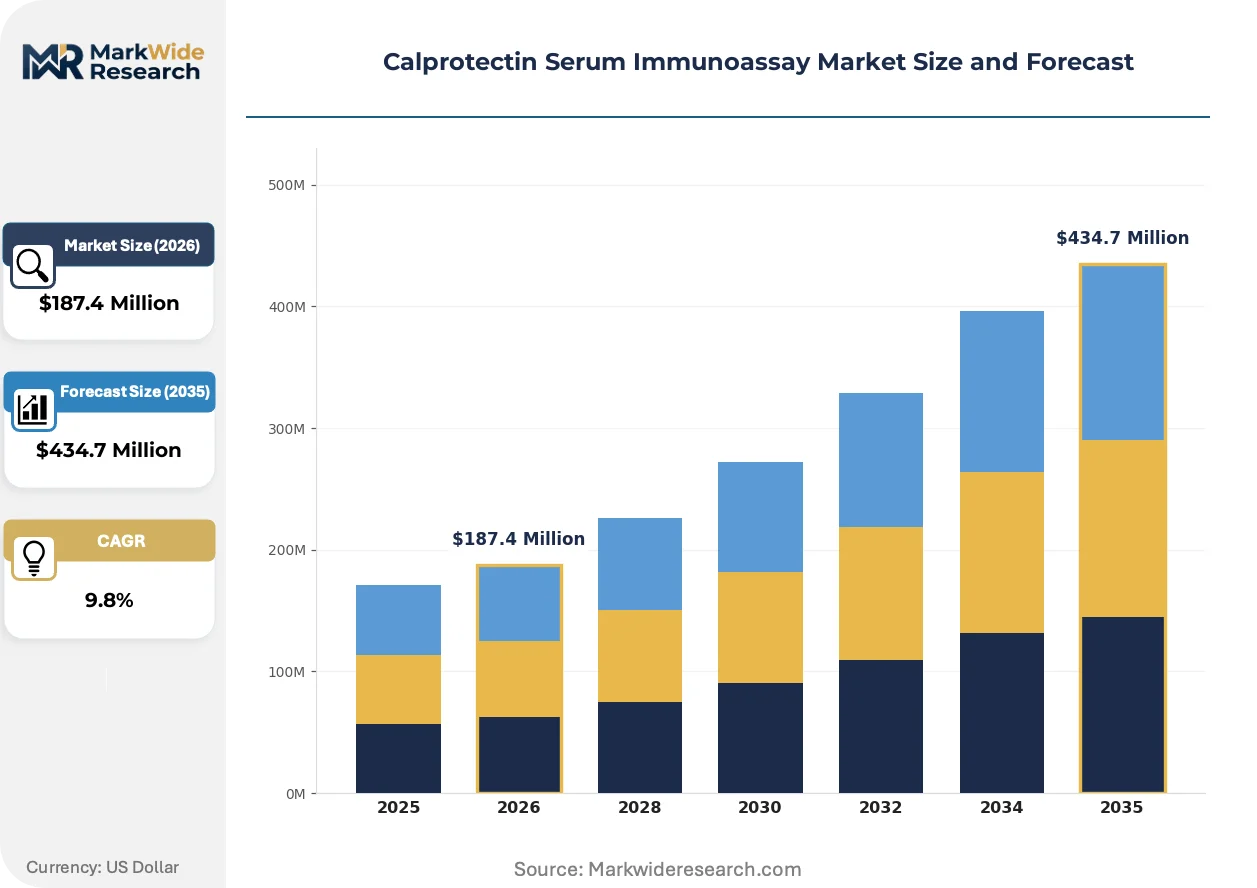
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA Kits, Lateral Flow Assays, CLIA Kits, Immunoturbidimetric Assays End User: Hospitals, Diagnostics Laboratories, Academic Research Institutions, Home Care Settings Technology: Fluorescent Immunoassay, Colorimetric Assay, Chemiluminescent Assay, Automated Analyzers Application: Diagnosis of Inflammatory Bowel Disease, Monitoring Treatment Response, Detection of Infections, Research Applications |
| Companies Covered | BÜHLMANN Laboratories, Thermo Fisher Scientific, DiaSorin, Gentian Diagnostics, ALPCO, Eagle Biosciences, Epitope Diagnostics, BioVendor, Hycult Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calprotectin Serum Immunoassay Market Evolving Landscape
Serum calprotectin testing is undergoing platform-level transformation as regulatory frameworks and automation economics reshape how laboratories procure and deploy inflammatory biomarker assays.
Chemiluminescent immunoassay technology is overtaking traditional ELISA formats in high-volume reference laboratories. This detection chemistry enables 10-minute sample-to-result turnaround on random-access analyzers. Major US hospital networks are prioritizing CLIA-based platforms for their STAT testing menus. The structural consequence is margin compression for standalone ELISA kit suppliers as reagent rental models capture long-term consumable streams.
REACH-aligned substance restrictions are forcing reformulation of assay buffer components containing flagged chemical intermediates. Manufacturers must validate alternative stabilizers without compromising S100A8/A9 binding kinetics. German IVD producers face the steepest compliance curves given their integrated European supply chains and proximity to ECHA enforcement.
Consolidated purchasing through group procurement organizations is displacing direct manufacturer relationships in US health systems. Banner Health and Kaiser Permanente-style networks now centralize immunoassay contracting across dozens of member laboratories. This concentration is most visible in California and Texas, where super-regional IDNs command price transparency and dedicated field service commitments from assay vendors.
Calprotectin Serum Immunoassay Market Segmentation
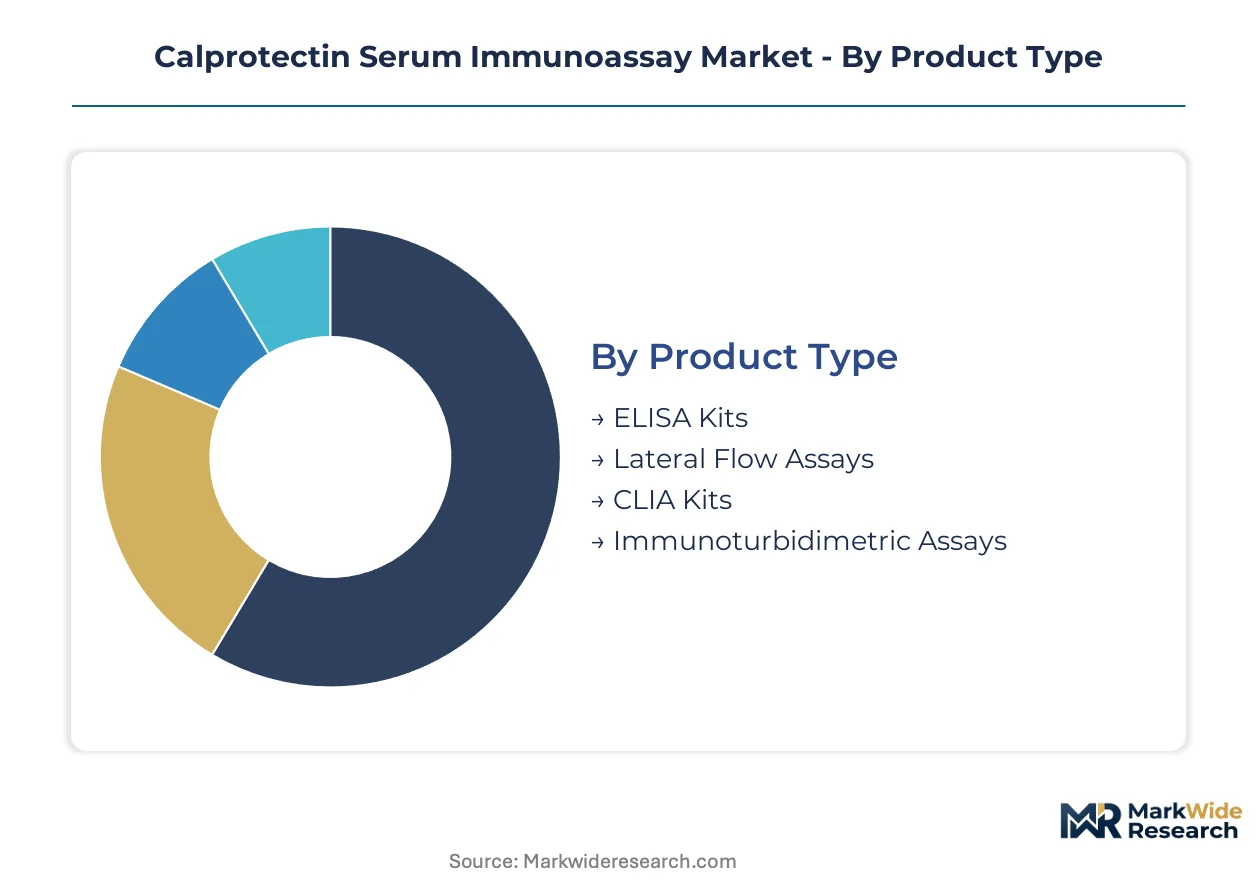
Segmentation in the calprotectin serum immunoassay market reveals how procurement decisions split between capital-intensive automation and flexible manual workflows. Laboratories weigh throughput requirements against existing platform investments when selecting across product formats and detection technologies.
Product Type:
Standalone kit formats dominate low-throughput settings while integrated reagent systems capture high-volume hospital laboratories.
- ELISA Kits:Enzyme-linked immunosorbent assay protocols quantify S100A8/A9 heterodimer through colorimetric detection with microplate readers. Demand clusters in German university hospital research divisions where protocol familiarity reduces training overhead. The format's lower capital barrier sustains placement in mid-tier diagnostics laboratories facing IVDR transition costs.
- CLIA Kits:Chemiluminescent immunoassay kits deliver enhanced sensitivity through acridinium ester or alkaline phosphatase signal amplification chemistry. US reference laboratories in California and Texas prioritize these for STAT inflammatory marker panels. Migration toward random-access automation is displacing batch-processed alternatives in high-complexity settings.
- Lateral Flow Assays:Point-of-care cartridges enable qualitative calprotectin detection without laboratory infrastructure.
- Immunoturbidimetric Assays:Turbidimetric detection suits high-throughput clinical chemistry analyzers with existing protein assay menus.
Volume placements concentrate in ELISA Kits; the faster expansion belongs to CLIA Kits.
End User:
Customer type determines pricing tolerance and service intensity, with consolidated health systems extracting distinct contract terms from standalone laboratories.
- Diagnostics Laboratories:Independent and hospital-affiliated testing facilities process calprotectin as part of expanded inflammation panels. Quest Diagnostics-scale operations in the American Midwest negotiate reagent rental agreements with dedicated field service. These customers prioritize assay interoperability across autoimmune and infectious disease test menus.
- Hospitals:Acute-care institutions integrate serum calprotectin into emergency department sepsis protocols and gastroenterology admission workups. German university medical centers in Berlin and Munich drive protocol standardization for IBD monitoring. Inpatient demand fluctuates with seasonal respiratory infection peaks that trigger neutrophil activation surveillance.
- Academic Research Institutions:University laboratories employ calprotectin assays for mechanistic studies of neutrophil biology.
- Home Care Settings:Remote patient monitoring applications remain nascent given regulatory complexity of blood-based self-testing.
Procurement authority is consolidating through Diagnostics Laboratories; Hospitals show the steepest test volume trajectory.
Technology:
Detection chemistry selection tracks laboratory automation maturity and regulatory certification availability across major markets.
- Chemiluminescent Assay:Signal amplification through luminol or acridinium derivatives achieves picogram-level sensitivity for low-abundance inflammatory states. Automated platforms from Roche and Abbott embed these assays within broader immunochemistry menus. US health systems prioritize this technology for labor cost reduction and result standardization.
- Automated Analyzers:Random-access instruments process calprotectin alongside CRP, procalcitonin, and cytokine panels without batch reconfiguration. German hospital networks favor these for 24/7 STAT testing coverage with minimal technologist intervention. Analyzer placement contracts typically span five to seven years with locked consumable pricing.
- Fluorescent Immunoassay:Time-resolved fluorescence detection offers alternative signal stability for research applications.
- Colorimetric Assay:Visible-spectrum absorbance measurement persists in resource-constrained settings and educational laboratories.
Installed base tilts toward Chemiluminescent Assay; Automated Analyzers are climbing the fastest as health systems consolidate testing infrastructure.
Application:
Use case segmentation separates reimbursed clinical diagnostics from investigational applications with distinct evidence requirements and pricing structures.
- Diagnosis of Inflammatory Bowel Disease:Serum calprotectin distinguishes active mucosal inflammation from functional gastrointestinal disorders. German G-BA reimbursement evaluations focus on this application for Crohn's disease and ulcerative colitis differentiation. Fecal testing retains first-line screening position, limiting serum assay penetration to monitoring intervals.
- Monitoring Treatment Response:Serial measurement tracks biologic therapy efficacy and predicts relapse risk in maintenance-phase patients. US gastroenterology practices in academic medical centers incorporate these assays into value-based care contracts. The application commands premium pricing due to documented impact on endoscopy avoidance.
- Detection of Infections:Neutrophil activation markers supplement traditional microbiology in sepsis risk stratification.
- Research Applications:Preclinical and clinical studies employ calprotectin as a pharmacodynamic endpoint in anti-inflammatory drug development.
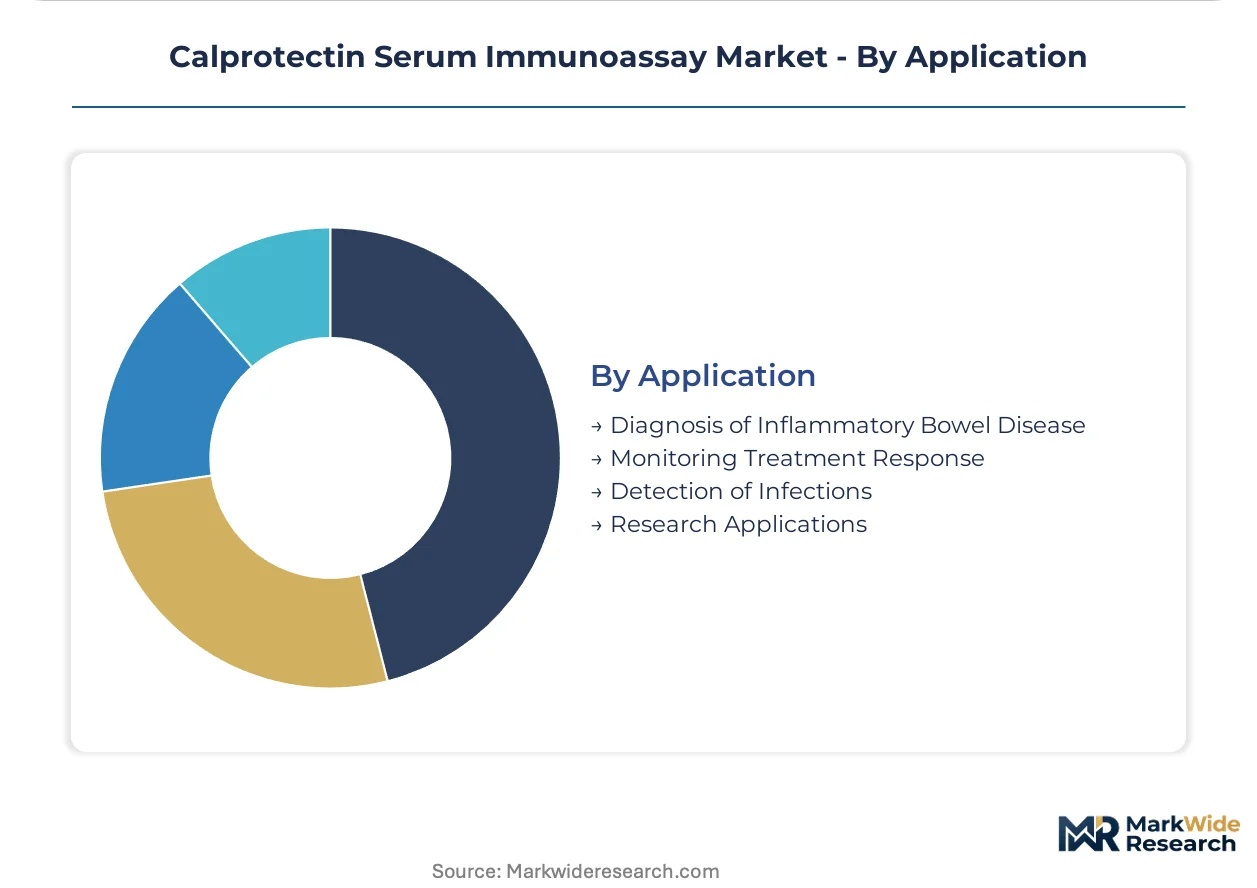
Test volume concentrates in Diagnosis of Inflammatory Bowel Disease; Monitoring Treatment Response is gaining share fastest through protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Berlin anchor European serum calprotectin testing volumes through university hospital networks that standardize IBD monitoring protocols across German-speaking regions.
United States
Quest Diagnostics-scale reference laboratories in the American Midwest negotiate reagent rental agreements for automated chemiluminescent platforms. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting dual-territory commercialization. California and Texas health systems centralize immunoassay contracting through super-regional IDNs.
Germany
The G-BA evaluates diagnostic utility evidence for serum calprotectin in differentiated inflammatory bowel disease monitoring protocols. EU IVDR conformity assessment compresses commercialization timelines, forcing front-loaded clinical validation investments. Berlin and Munich university medical centers drive protocol standardization for IBD monitoring.
Switzerland
Swissmedic fast-track pathways offer early revenue generation while EU IVDR assessments proceed. BÜHLMANN Laboratories leverages its Swiss manufacturing base to sustain supply continuity for high-complexity immunoassay platforms. Basel and Zurich clusters concentrate precision diagnostics manufacturing.
United Kingdom
NHS England procurement frameworks favor assays with documented clinical validation and traceable calibrator chains. MHRA post-Brexit regulatory alignment creates parallel conformity requirements for IVD market access. London and Cambridge academic medical centers incorporate serum calprotectin into value-based gastroenterology contracts.
Italy
Lombardy hospital networks expand adoption of serum calprotectin testing for inflammatory bowel disease management. EMA guidance on biomarker qualification influences national reimbursement evaluations for novel diagnostics. Milan and Bologna clinical research organizations conduct multicenter validation studies.
Calprotectin Serum Immunoassay Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with automated platform ecosystems. Three tiers separate high-throughput analyzer-integrated suppliers, specialized immunoassay kit manufacturers, and regional diagnostics distributors. Consolidated purchasing through group procurement organizations displaces direct manufacturer relationships. Strategic moves concentrate on reagent rental lock-in and IVDR certification acceleration.
Within the specialized diagnostics tier, BÜHLMANN Laboratories and DiaSorin exemplify contrasting geographic anchoring strategies—Swiss precision manufacturing versus Italian-American chemiluminescent platform integration. Thermo Fisher Scientific occupies a position representing North American distribution infrastructure dominance. These three entities represent the archetype spectrum from regional manufacturing specialists to global platform-integrated conglomerates.
| Leading Market Players |
|---|
| BÜHLMANN Laboratories |
| Thermo Fisher Scientific |
| DiaSorin |
| Gentian Diagnostics |
| ALPCO |
| Eagle Biosciences |
| Epitope Diagnostics |
| BioVendor |
| Hycult Biotech |
| Others |
Value Network & Pricing Analysis
Specialized immunoassay technologists in Basel and Munich command wage premiums that compress margins on economy-tier ELISA kits while widening spreads between automated analyzer contracts and manual workflows. Labor-cost differentials between Swiss precision manufacturing clusters and mid-tier German diagnostics hubs directly shape three-tier pricing structures across premium CE-IVD certified systems, standard hospital-laboratory bundles, and research-grade consumables.
Pricing Analysis
Value-based pricing anchored to endoscopy-avoidance outcomes dominates US gastroenterology contracts, with reimbursement tied to documented reductions in invasive surveillance procedures. Price differentiation separates IVDR-certified automated platforms from legacy ELISA formats through after-sales service bundling and locked consumable streams. Pricing pressure stems from GPO consolidation in California and Texas health systems extracting transparency commitments. Reference laboratories show lowest price sensitivity; independent diagnostics facilities face acute margin compression.
Supply Chain Analysis
EU IVDR local-content requirements for calibrator traceability chains are forcing manufacturers to source reference materials from accredited European metrology institutes rather than legacy Asian suppliers. Acridinium ester chemiluminescent substrates and S100A8/A9 recombinant proteins draw from Swiss and German specialty chemical producers. Single-source vulnerability concentrates in high-purity antibody supply for S100A8/A9 capture. Distribution runs through consolidated group procurement organizations displacing direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as assay manufacturers pursue captive control over calibrator reference material production to secure IVDR traceability compliance and margin defense.
For Market Incumbents: Deploy reagent rental lock-in mechanisms to defend installed base against CLIA kit displacement. Deepen backward integration into S100A8/A9 recombinant protein production to reduce dependency on third-party antibody suppliers. Consolidate field service density in the American Midwest where Quest Diagnostics-scale reference laboratories negotiate multi-year platform contracts. Counter the fecal calprotectin substitution threat by embedding serum assays into sepsis monitoring protocols beyond gastroenterology. For New Entrants and Emerging Players: Capture whitespace in Swissmedic fast-track pathways for early revenue generation while EU IVDR assessments proceed. Target underpenetrated regional hospital networks in the Mountain West where automated platform density remains lowest. Exploit clinical laboratory scientist shortages by offering simplified workflow training bundles that reduce implementation friction. Position through point-of-care lateral flow formats for emergency department triage applications. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier immunoassay specialists possessing CE-IVD certification progress and analyzer-agnostic kit formats given IVDR transition deadlines compressing valuation multiples. Long-term viability over the next decade hinges on regulatory navigation capability rather than raw R&D scale. Watch for G-BA reimbursement decisions on serum calprotectin in differentiated IBD monitoring as the critical inflection signal for German market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Certification Acceleration | EU IVDR conformity assessment deadlines force front-loaded clinical validation investments before market access. |
| Analyzer-Agnostic Kit Development | Platform interoperability reduces reagent rental lock-in vulnerability and expands addressable laboratory base. |
| Calibrator Traceability Integration | In-house reference material production secures margin defense against third-party supplier price volatility. |
| Sepsis Protocol Expansion | Emergency medicine positioning extends serum calprotectin beyond gastroenterology into critical-care biomarker panels. |
| GPO Contract Consolidation | Banner Health and Kaiser Permanente-style networks centralize purchasing across dozens of member laboratories. |
Research Methodology
Multi-period observation of IVDR certification timelines, G-BA reimbursement evaluations, and automated analyzer placement rates anchored the trend analysis, supplemented by interviews with clinical laboratory directors, IVD regulatory affairs specialists, hospital procurement managers, and gastroenterology practice administrators. Secondary validation drew from FDA 510(k) filings, EU IVDR notified body documentation, CMS Medicare reimbursement databases, and GPO contract disclosures. Bottom-up test volume modeling triangulated against top-down market sizing across product format and technology segments.
Segment-weighting applied differential growth assumptions to chemiluminescent platforms versus ELISA workflows, with technology migration curves calibrated to laboratory automation investment cycles. End-user segmentation incorporated pricing tolerance variations between consolidated health systems and standalone diagnostics facilities. CAGRs derived from compounded annual test volume expansion adjusted for reimbursement policy shifts and regulatory access barriers. Forecast inputs included IVDR transition deadlines and Swissmedic fast-track utilization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to G-BA reimbursement decisions, fecal calprotectin protocol persistence, and clinical laboratory workforce pipeline constraints. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Point of Care Diagnostics Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
PCR and Real-Time PCR Molecular Diagnostics Market