
 Hearing Screening Diagnostic Devices Market | 2026-2036
Hearing Screening Diagnostic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Screening Diagnostic Devices Market Outlook
Modular platform bundling is rebalancing how audiology departments evaluate capital purchases, with buyers favoring configurations that combine otoacoustic emissions and ABR testing in single units. Sonova Holding AG leverages its cochlear implant and diagnostic portfolio to sustain integrated workflow sales across European and North American hospital networks. Natus Medical Incorporated anchors its position through dominance in newborn screening protocols, while Interacoustics AS differentiates via specialized middle ear analyzer modules that occupy premium clinical segments.
Hearing screening diagnostic devices are electroacoustic instruments that generate calibrated puretone stimuli across frequencies from 125 Hz to 8 kHz and measure auditory evoked responses to assess hearing threshold and middle ear function, primarily for early detection of sensorineural and conductive hearing loss in clinical and screening settings. ABR Systems command the highest capital allocation per unit due to their critical role in neonatal intensive care diagnostics, while automated technology platforms represent the fastest-expanding segment as health systems seek to reduce technician-dependent variability in school and occupational screening programs. Digital technology underpins most new installations, though hybrid architectures retain share in cost-sensitive clinic environments where legacy analog peripherals require phased replacement.
The FDA enforces premarket notification requirements under 21 CFR 874 for audiological diagnostic devices, while the EU Medical Device Regulation mandates CE marking and post-market surveillance for hearing screening equipment sold in European member states. OSHA's occupational noise exposure standards in the United States drive recurring demand for industrial audiometry programs, creating a parallel replacement market distinct from clinical capital cycles. Stakeholders must monitor how reimbursement shifts toward value-based newborn screening outcomes reshape device specification requirements and service contract structures.
Market Dynamics
Universal newborn hearing screening mandates are compressing replacement cycles for aging diagnostic fleets across hospital networks, while automated platform bundling reconfigures capital allocation toward integrated otoacoustic emissions and ABR systems.
Growth Catalysts
- FDA Newborn Screening Protocols:Tightened performance thresholds for otoacoustic emissions devices are forcing hospital procurement departments to accelerate fleet upgrades in neonatal intensive care units.
- OSHA Occupational Noise Standards:Recurring compliance requirements for industrial audiometry programs sustain parallel replacement demand outside clinical capital cycles.
- Automated Screening Platforms:Technician-independent variability reduction in school and occupational programs drives health system investment in self-contained diagnostic units.
Market Restraints
- Capital Equipment Concentration:ABR systems command disproportionate budget allocation per unit, crowding out middle ear analyzer purchases in constrained hospital capital plans.
- Hybrid Architecture Lock-in:Cost-sensitive clinic environments retain legacy analog peripherals, creating phased replacement friction that delays full digital adoption.
- Service Contract Bundling:Integrated workflow vendors tie diagnostic hardware to multi-year maintenance agreements, limiting buyer flexibility to unbundle components.
Strategic Opportunities
- School-Based Screening Expansion:Automated technology platforms open penetration pathways into district-level pediatric audiology programs previously served by mobile clinic visits.
- Teleaudiology Integration:Remote diagnostic interpretation capabilities enable rural and underserved clinic networks to access specialist-validated screening without on-site audiologists.
- Value-Based Reimbursement Alignment:Outcome-driven newborn screening contracts reward health systems that demonstrate reduced false-positive rates through upgraded device specifications.
Industry Challenges
- Pediatric Audiologist Shortage:Specialized training pipelines fail to match screening volume expansion, forcing reliance on automated systems that require clinical validation oversight.
- Legacy System Interoperability:Hospital information system integration demands custom middleware development for hybrid analog-digital diagnostic architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Screening Diagnostic Devices Market |
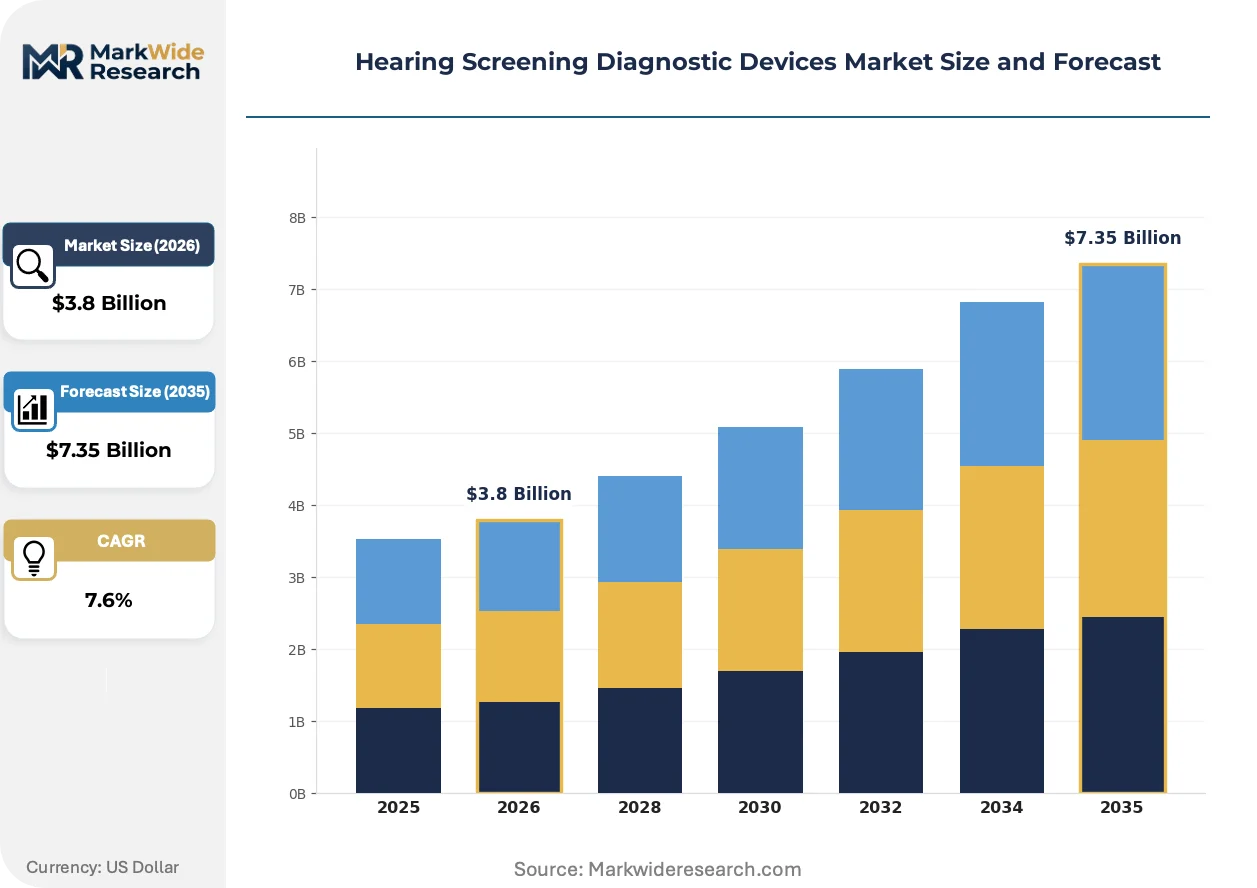
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Puretone Audiometers, Otoacoustic Emissions, ABR Systems, Middle Ear Analyzers End User: Hospitals, Clinics, Audiology Centers, Home Care Technology: Digital, Analog, Automated, Hybrid Market Application: Newborn Screening, Adult Screening, School Screening, Occupational Health |
| Companies Covered | Sonova Holding AG, Amplivox Ltd, MAICO Diagnostics, Interacoustics AS, INVENTIS SRL, Natus Medical Incorporated, Grason Stadler Inc, PATH MEDICAL GmbH, Demant A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Screening Diagnostic Devices Market Strategic Shifts
Digital signal processing and cloud-connected diagnostics are redistributing analytical capabilities from centralized hospital laboratories toward point-of-care screening environments.
Artificial intelligence-assisted threshold detection is decentralizing diagnostic interpretation from specialist audiologists to trained technicians in school and occupational settings. District health departments in the United States are deploying these platforms to reduce referral bottlenecks. The structural consequence is compressing the traditional clinical validation chain while expanding screening throughput.
The EU Medical Device Regulation mandates enhanced post-market surveillance and clinical evidence requirements for hearing screening equipment sold in European member states. Manufacturers must now maintain active safety monitoring systems beyond initial CE marking. Pediatric audiology departments in Germany and France are prioritizing vendors with established European notified body relationships to accelerate compliance timelines.
Buyer concentration among integrated delivery networks is consolidating vendor selection authority from individual hospital audiology departments to centralized procurement committees. Large health systems in the United States now specify modular platform configurations across entire diagnostic fleets. This behavioral shift favors suppliers with comprehensive otoacoustic emissions, ABR, and middle ear analyzer portfolios over specialized device manufacturers.
Hearing Screening Diagnostic Devices Market Segmentation
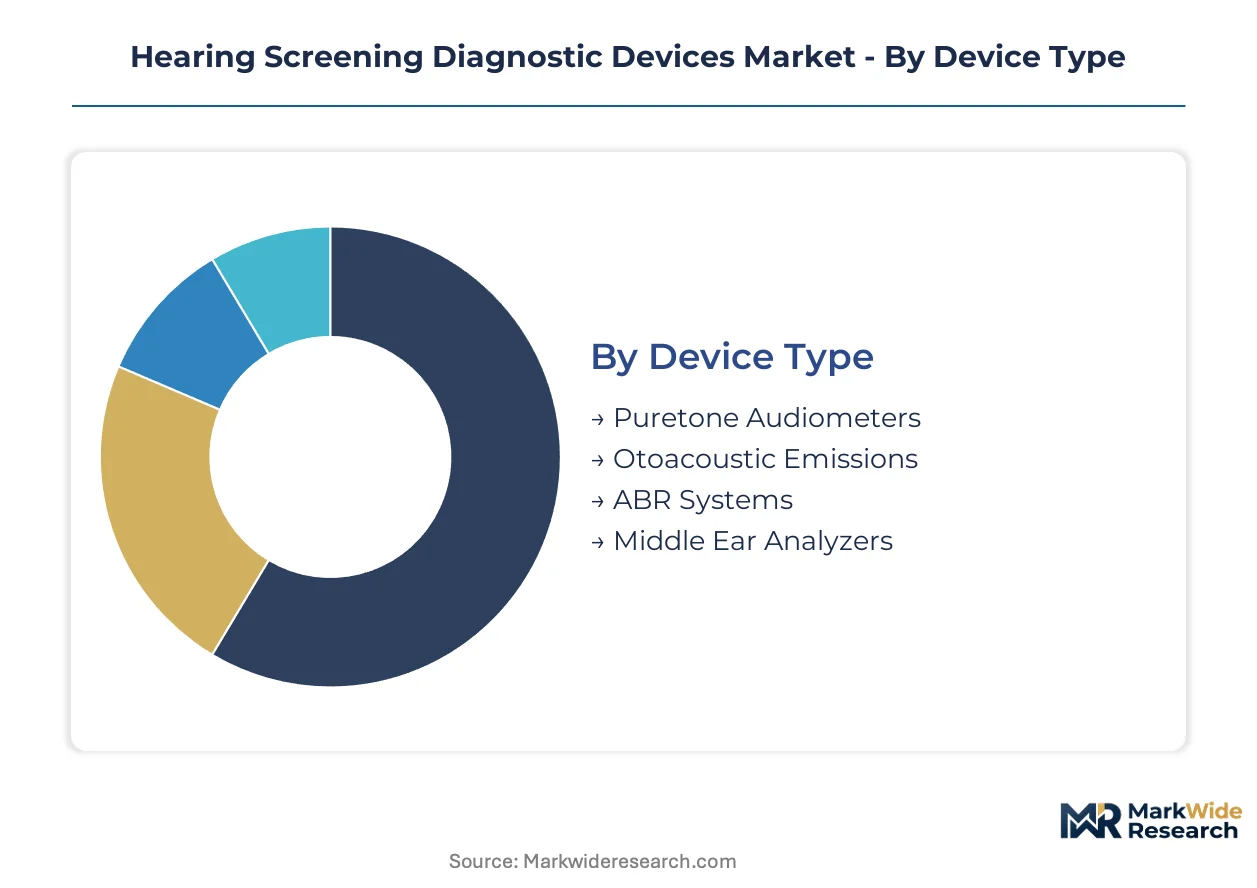
Device configurations diverge sharply between high-throughput screening environments requiring automated throughput and precision diagnostic settings demanding calibrated manual control. Procurement committees evaluate capital allocation across these splits based on patient volume, technician availability, and regulatory compliance burden.
Device Type:
ABR Systems capture premium capital allocation per unit while automated Otoacoustic Emissions platforms drive volume expansion across health system fleets.
- ABR Systems:Electrophysiological instruments measure auditory brainstem responses to click or tone-burst stimuli, delivering definitive threshold assessment for neonates who cannot provide behavioral feedback. Neonatal intensive care units in the United States concentrate procurement of these systems as FDA newborn screening protocols tighten performance requirements for diagnostic confirmation.
- Otoacoustic Emissions:Devices detect cochlear outer hair cell function through transient or distortion-product emissions, enabling rapid non-invasive screening without patient cooperation. School districts and occupational health programs favor automated variants to reduce technician-dependent variability in high-volume screening workflows.
- Puretone Audiometers:Standard diagnostic instruments generate calibrated puretone stimuli across 125 Hz to 8 kHz for behavioral threshold determination in cooperative patients.
- Middle Ear Analyzers:Tympanometry and acoustic reflex measurement systems assess conductive pathway function, occupying specialized clinical segments where middle ear pathology differential diagnosis is required.
Mature deployment sits with Puretone Audiometers in established audiology departments. Newer deployment is concentrated in Otoacoustic Emissions platforms as universal newborn screening mandates expand.
End User:
Hospital networks consolidate procurement authority while decentralized screening programs fragment demand across clinic and district-level buyers.
- Hospitals:Integrated delivery networks command the largest capital budgets, specifying modular platform configurations across neonatal intensive care, pediatric audiology, and otolaryngology departments. These buyers prioritize FDA-compliant ABR and otoacoustic emissions bundling with multi-year service contracts.
- Clinics:Independent and hospital-affiliated outpatient facilities concentrate demand for portable puretone audiometers and middle ear analyzers, constrained by capital limits that favor phased digital migration from legacy analog systems.
- Audiology Centers:Specialized diagnostic facilities deploy comprehensive device suites for complex case management and pre-cochlear-implant evaluation.
- Home Care:Emerging segment for teleaudiology-enabled remote screening, limited by reimbursement uncertainty and device validation requirements for unsupervised use.
Volume concentration remains with Hospitals. Margin expansion is shifting toward Audiology Centers as referral complexity increases.
Technology:
Digital architectures displace legacy analog installations while hybrid configurations persist in cost-constrained upgrade cycles.
- Digital:Signal processing platforms with cloud connectivity and electronic health record integration dominate new hospital installations, enabling automated quality control and remote diagnostic interpretation.
- Automated:Self-contained screening units with technician-independent operation are gaining share fastest in school and occupational health programs where specialist audiologist availability is limited.
- Analog:Legacy electroacoustic instruments with manual calibration persist in resource-limited international markets and older clinic infrastructure.
- Hybrid:Mixed digital-analog architectures retain presence in phased replacement environments where peripheral compatibility with existing transducers delays full platform conversion.
Established base sits with Analog and Hybrid systems. Technology transition is accelerating through Automated platforms in screening-dominant settings.
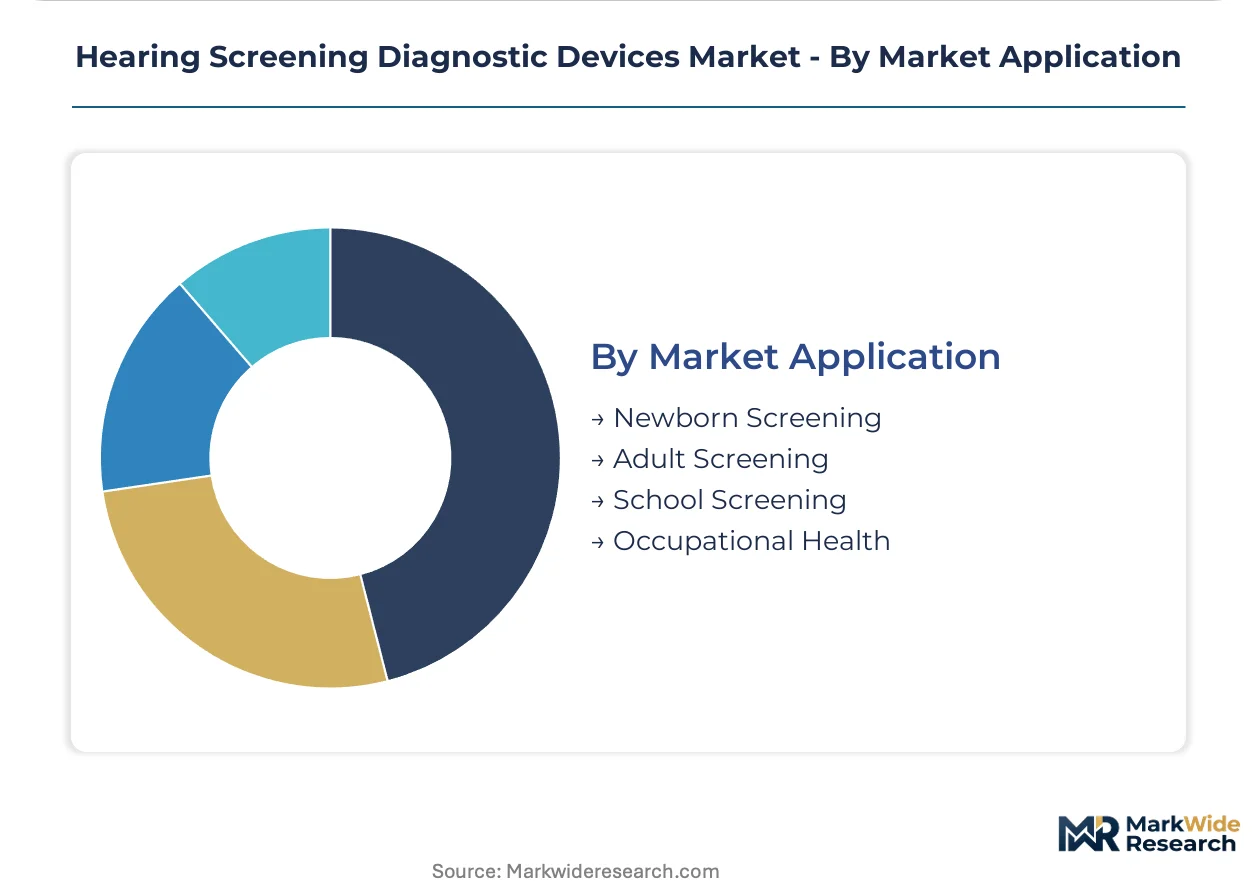
Market Application:
Newborn screening mandates anchor regulatory-driven replacement demand while occupational health creates parallel compliance-based procurement cycles.
- Newborn Screening:Universal hearing screening mandates in the United States and equivalent programs in European member states sustain replacement demand for otoacoustic emissions and ABR systems as performance thresholds tighten and fleet aging accelerates.
- Occupational Health:OSHA audiometric monitoring requirements for noise-exposed workers generate recurring demand for puretone audiometers and automated screening platforms in industrial and corporate health settings.
- Adult Screening:Diagnostic evaluation for age-related and noise-induced hearing loss in clinical populations, concentrated in audiology centers and hospital otolaryngology departments.
- School Screening:District-level pediatric audiology programs deploying automated platforms to replace mobile clinic visits and reduce referral bottlenecks.
Regulatory foundation rests with Newborn Screening. Application expansion is advancing through School Screening as district health departments automate previously manual workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Western Europe and North America, while procurement demand clusters in the United States and Germany where universal newborn screening mandates drive replacement cycles. Consumption patterns diverge between high-income markets with automated platform adoption and emerging systems retaining legacy analog infrastructure.
United States
FDA newborn screening protocols and OSHA occupational noise standards generate dual procurement streams for hospital networks and industrial health programs. The 21 CFR 874 premarket notification framework governs audiological diagnostic device clearance, tightening performance thresholds for otoacoustic emissions systems. Pediatric audiology departments in the Boston and Philadelphia hospital clusters are consolidating vendor selection authority through integrated delivery network procurement committees.
Germany
The EU Medical Device Regulation mandates enhanced post-market surveillance for hearing screening equipment, accelerating compliance-focused fleet upgrades in neonatal intensive care units. CE marking requirements under MDR force manufacturers to maintain active safety monitoring systems beyond initial certification. Medical technology procurement in the Baden-Württemberg and Bavaria industrial corridors favors vendors with established European notified body relationships.
Japan
PMDA medical device approval processes and METI industrial standards shape diagnostic equipment specification requirements for hospital networks. Aging demographics expand adult screening volumes for age-related hearing loss in Tokyo and Osaka metropolitan clinical networks. Domestic manufacturers anchor supply relationships with university hospital audiology departments through long-term maintenance contracts.
China
NMPA medical device registration requirements and MIIT industrial policy directives structure market entry pathways for foreign diagnostic equipment suppliers. Provincial health commissions in the Yangtze River Delta and Pearl River Delta are expanding newborn screening coverage to match urban hospital network capabilities. Local manufacturers compete on cost-sensitive clinic segments while imported platforms dominate tertiary hospital procurement.
United Kingdom
NHS newborn hearing screening program mandates sustain replacement demand for automated otoacoustic emissions platforms across England and Scotland. MHRA post-market surveillance requirements align with EU MDR transition timelines for devices placed on the UK market. London and Manchester hospital networks are piloting teleaudiology-enabled remote screening to address pediatric audiologist shortages in rural catchment areas.
Hearing Screening Diagnostic Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a moderately consolidated vendor base. The market structure tiers between integrated hearing healthcare groups with cochlear implant and diagnostic portfolios and specialized device manufacturers concentrating on single modality platforms. Three archetypes dominate: full-spectrum audiology conglomerates, newborn screening protocol specialists, and modular component suppliers. Competitive dynamics center on multi-year service contract bundling and hospital information system integration capabilities rather than standalone device pricing.
Within the integrated healthcare group tier, Sonova Holding AG and Demant A/S occupy positions spanning diagnostic equipment through hearing aid and cochlear implant solutions. Natus Medical Incorporated exemplifies the protocol specialist archetype through dominance in newborn screening installations. Interacoustics AS represents the modular premium segment with specialized analyzer configurations for differentiated clinical applications.
| Leading Market Players |
|---|
| Sonova Holding AG |
| Amplivox Ltd |
| MAICO Diagnostics |
| Interacoustics AS |
| INVENTIS SRL |
| Natus Medical Incorporated |
| Grason Stadler Inc |
| PATH MEDICAL GmbH |
| Demant A/S |
| Others |
Value Chain & Pricing Dynamics
Backward integration into transducer manufacturing and signal processing chip design anchors supply security for premium ABR system vendors while locking in margin structures that resist commoditization pressure from automated otoacoustic emissions competitors. FDA premarket notification requirements under 21 CFR 874 create certification moats that sustain pricing power for established suppliers against unqualified imports.
Pricing Analysis
Margin tightening in the automated otoacoustic emissions tier reflects volume concentration among integrated delivery network procurement committees extracting multi-year service bundling concessions. Pricing stratifies across premium ABR configurations, standard digital audiometers, and economy analog platforms, with differentiation driven by FDA clearance tier and embedded software validation depth. Cost-down pressure accelerates in the school screening segment as district health departments consolidate vendor selection authority. Hospital networks demonstrate lowest price sensitivity due to reimbursement alignment with newborn screening outcomes, while independent clinics face capital constraints that favor phased hybrid architecture migration.
Supply Chain Analysis
Dual-sourcing mandates from integrated delivery networks force qualified vendors to maintain redundant manufacturing footprints across Germany, the United States, and Switzerland for critical electroacoustic transducer assemblies. Component dependencies center on precision microphones, calibrated ear couplers, and application-specific integrated circuits for signal processing. Single-source vulnerability concentrates in European-sourced precision acoustic components subject to EU Medical Device Regulation post-market surveillance disruption. Distribution runs through authorized medical equipment distributors with biomedical engineering service capabilities, bypassing generalist channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA newborn screening protocol tightening erects barrier-to-entry moats favoring vendors with established 510(k) clearance track records and active safety monitoring infrastructure.
For Market Incumbents: To counter automated platform commoditization from Asian manufacturers, deepen software companion development for hospital information system integration and secure exclusive GPO contracts with pediatric audiology purchasing committees. Expand in-house production of OAE probe assemblies to defend margin position against component cost volatility.
For New Entrants and Emerging Players: Direct-to-clinic digital distribution routes open penetration pathways into independent audiology centers underserved by field-service-heavy incumbents. Target the teleaudiology-enabled remote screening application with cloud-connected automated platforms, leveraging the rural clinic white space where specialist audiologist shortages create demand for technician-independent validation.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated hearing healthcare conglomerates seeking diagnostic workflow bundling capabilities. Long-term viability favors vendors with dual FDA-CE marking compliance and established European notified body relationships. Watch for inflection in value-based reimbursement contract penetration as the signal indicating durable pricing power transition.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Clears automated otoacoustic emissions platforms for neonatal intensive care unit deployment under tightened performance thresholds. |
| CE Marking Pathway under EU MDR | Activates post-market surveillance obligations that favor vendors with established European notified body relationships in Germany and France. |
| Hospital System Partnership | Locks multi-year service contracts with integrated delivery networks specifying modular platform configurations across diagnostic fleets. |
| Software Companion Development | Enables electronic health record integration and remote diagnostic interpretation for teleaudiology-enabled rural clinic networks. |
| Reimbursement Strategy Alignment | Positions automated platforms for value-based newborn screening contracts rewarding reduced false-positive rates through upgraded specifications. |
Study Parameters
Independent corroboration across FDA 510(k) clearance databases, EU Medical Device Regulation notified body certifications, and hospital procurement contract filings underwrites the qualitative findings in this analysis. Primary interviews with pediatric audiology department heads, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at diagnostic equipment manufacturers combined with secondary validation from CMS Medicare reimbursement data, OSHA compliance reporting, and hospital capital expenditure disclosures. Bottom-up installation base modeling and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition across device type, end user configuration, technology architecture, and market application dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level growth rate blending weighted by installed base replacement cycles and procurement committee budget allocation patterns. Forecast inputs incorporate FDA protocol amendment timelines, EU MDR transition compliance deadlines, and integrated delivery network vendor consolidation behavioral shifts.
The model holds under stable regulatory enforcement intensity and continued universal newborn screening mandate maintenance; deviation in reimbursement paradigm shifts toward outcome-based contracting or pediatric audiologist training pipeline collapse would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Diagnostic Ophthalmic Devices Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Urine Analyzers Market
Diagnostic Devices
Automated Visual Field Analyzer Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Companion Diagnostics Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
US Point of Care Diagnostics Market
Diagnostic Devices
US Breath Analyzers Market