
 Absorbable Surgical Sutures Market | 2026-2036
Absorbable Surgical Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable Surgical Sutures Market Analysis
Premium braided sutures with proprietary coatings is decoupling from commodity monofilament lines on both price and clinical positioning. Ethicon leverages its vertical integration in polyglycolic acid resin production to sustain margin control across hospital purchasing contracts. B. Braun Melsungen AG anchors its European manufacturing base while competing aggressively in emerging markets through localized sterilization facilities. DemeTECH Corporation specializes in private-label braided sutures for ambulatory surgery chains, occupying a mid-tier niche between multinational brands and regional suppliers.
Absorbable surgical sutures are sterile, bioresorbable threads manufactured from synthetic polymers such as polydioxanone or polyglycolic acid, designed to lose tensile strength predictably through hydrolysis and eliminate the need for removal after tissue healing. Braided polyglycolic acid variants dominate general surgery applications due to superior knot security, while monofilament polydioxanone leads cardiac procedures where prolonged wound support matters. Coated sutures command premium positioning in orthopedic and gynecology settings where tissue drag reduction directly impacts surgical outcomes. Catgut material persists in select cost-sensitive clinics though synthetic alternatives are displacing collagen-based products across regulated channels.
The FDA enforces biocompatibility and degradation testing under ISO 10993 standards, while the EU Medical Device Regulation mandates clinical evidence for novel absorbable polymer formulations before CE marking approval. Health Canada and Japan's PMDA apply comparable polymer purity benchmarks, creating a harmonized barrier to entry for new material entrants. Stakeholders must monitor how regulators classify next-generation antibacterial-coated sutures, as this designation will determine whether clinical trial requirements expand or streamline for product registration.
Market Dynamics
Polymer degradation profile standardization is compressing formulation diversity as regulators harmonize hydrolysis-rate testing protocols across major jurisdictions. This convergence forces manufacturers to consolidate R&D pipelines around fewer base chemistries while raising barriers for novel material entrants.
Growth Catalysts
- Ambulatory Surgical Center Expansion:United States outpatient facilities are driving volume procurement of coated braided variants for same-day discharge protocols. Medicare reimbursement alignment with minimally invasive procedures accelerates this channel shift.
- ISO 10993 Biocompatibility Harmonization:Streamlined cytotoxicity and sensitization testing frameworks reduce redundant certification costs for multi-jurisdiction product launches. Manufacturers leverage mutual recognition agreements to accelerate market entry timelines.
- Synthetic Polymer Performance Gains:Advanced polyglycolic acid copolymers with tunable tensile strength decay curves displace collagen-based catgut in cost-sensitive clinics. Material science improvements narrow the price-performance gap with premium monofilament alternatives.
Market Restraints
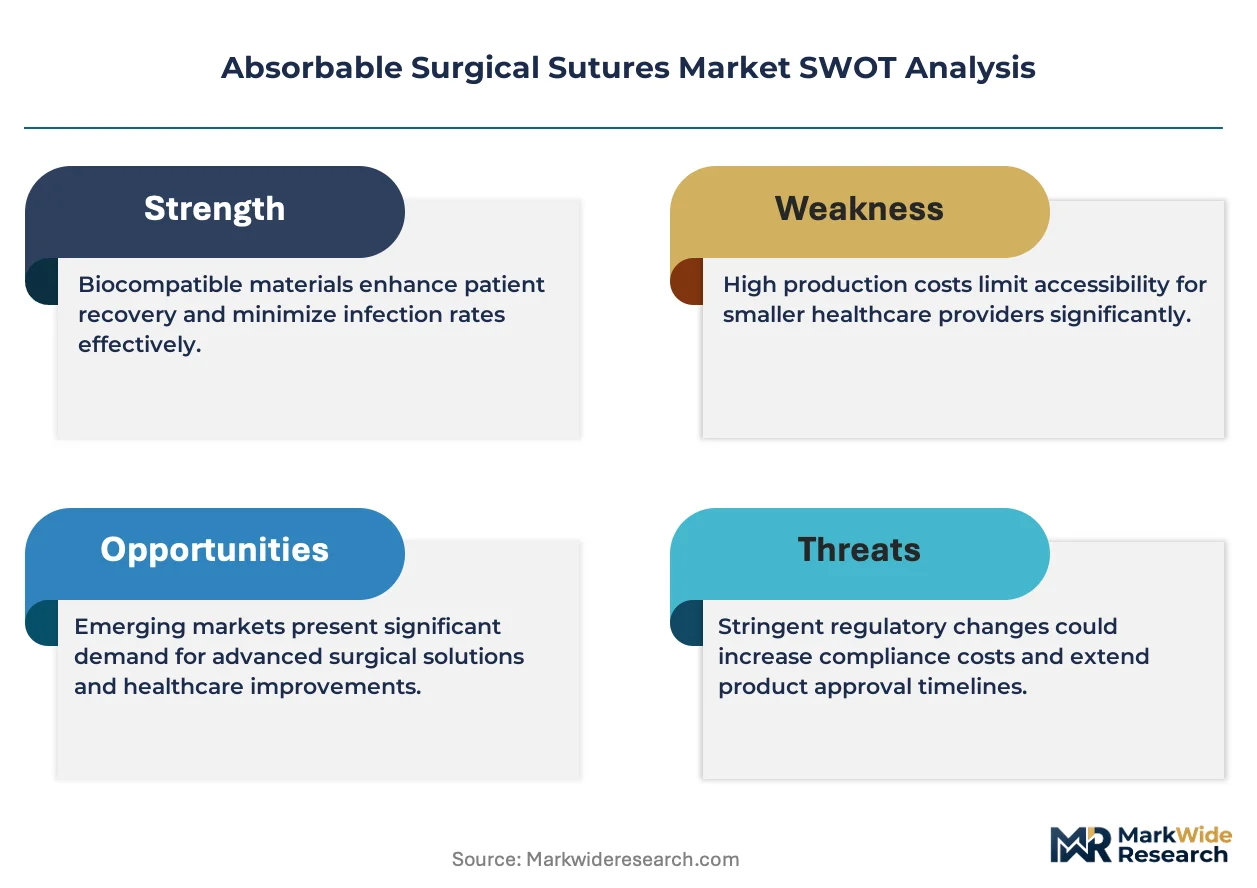
- Petrochemical Feedstock Volatility:Polydioxanone and polyglycolic acid resin production depends on ethylene oxide and glycol derivative pricing. Crude oil derivative fluctuations compress margin predictability for non-vertically integrated manufacturers.
- Regulatory Friction from MDR Clinical Evidence Requirements:EU Medical Device Regulation mandates prospective clinical data for novel absorbable polymer formulations. Small and mid-sized manufacturers face capital-intensive trial designs that delay CE marking by 18-36 months.
- Monofilament Substitution Threat:Barbed and knotless closure technologies reduce suture quantity per procedure in laparoscopic applications. Device companies promote mechanical alternatives that eliminate traditional knot-tying skill dependencies.
Strategic Opportunities
- Antibacterial Coating Regulatory Pathway Clarification:FDA and EMA convergence on drug-device combination classification for triclosan- or chlorhexidine-impregnated sutures creates predictable approval frameworks. Early movers secure premium positioning in orthopedic and colorectal surgery segments.
- India Manufacturing Localization:CDSCO streamlined medical device registration and PLI scheme production incentives attract contract sterilization and packaging investment. Cost arbitrage opportunities emerge for export-oriented braided suture production.
- 3D Printing Convergence with Bioabsorbable Scaffolds:Patient-specific suture anchors and fixation devices integrate resorbable polymer threads with additive manufacturing platforms. Orthopedic and maxillofacial surgery applications drive pilot commercialization partnerships.
Industry Challenges
- Polymer Chemist Talent Scarcity:Specialized expertise in hydrolysis-rate prediction and bioresorption kinetics concentrates in pharmaceutical and medical device hubs. Recruitment competition from drug delivery and tissue engineering sectors elevates compensation costs.
- Legacy Sterilization Facility Reconfiguration:Ethylene oxide emissions regulations in the United States and European Union force facility upgrades or alternative technology adoption. Capital allocation to gamma irradiation or nitrogen dioxide systems strains mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable Surgical Sutures Market |
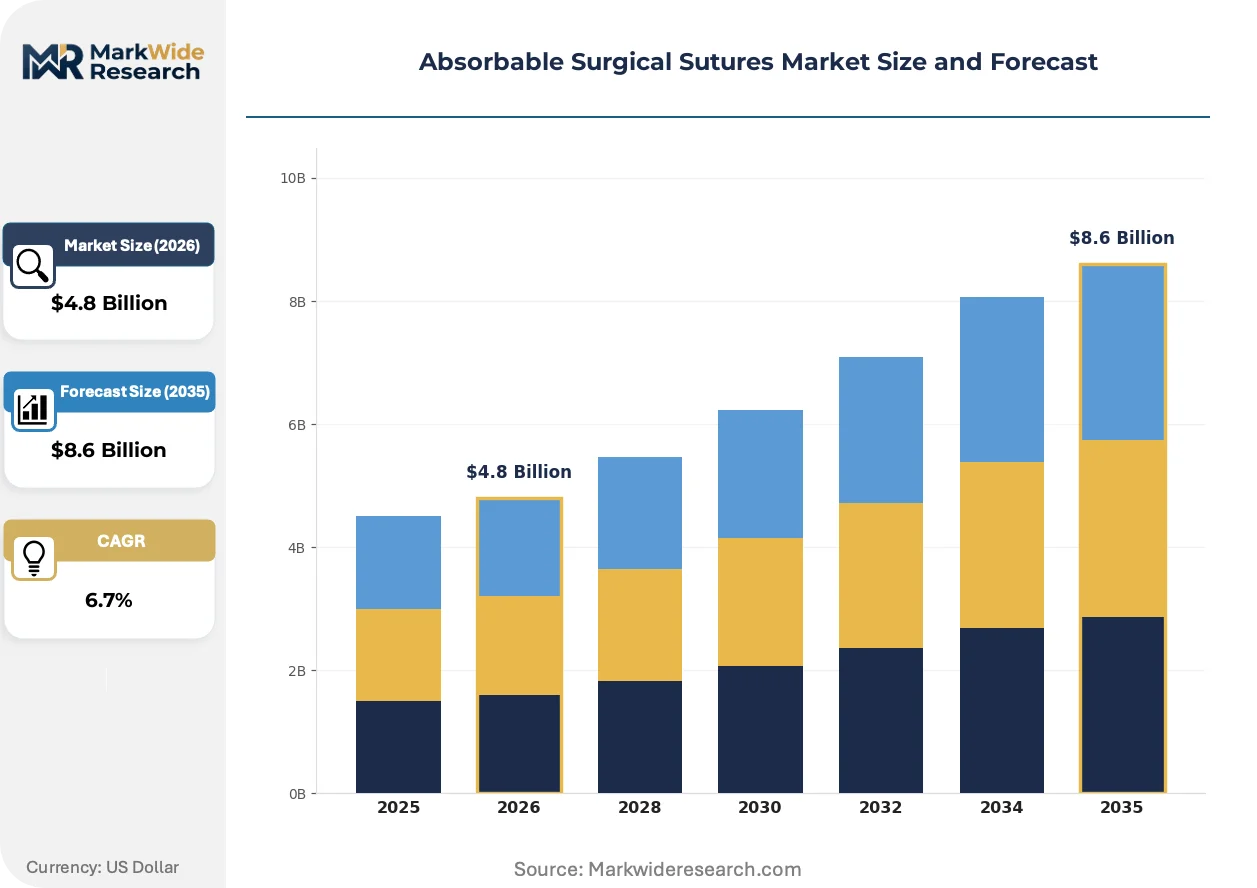
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofilament, Braided, Coated, Uncoated Material: Polyglycolic Acid, Polydioxanone, Catgut, Polycaprolactone Application: Cardiac, Orthopedic, General Surgery, Gynecology End User: Hospitals, Surgical Centers, Clinics, Ambulatory Care |
| Companies Covered | Ethicon, Medtronic, B. Braun Melsungen AG, DemeTECH Corporation, Johnson & Johnson Services, Inc., Smith & Nephew, Teleflex Incorporated, Genesis Medtech, Healthium Medtech Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable Surgical Sutures Market Emerging Trajectories
Real-time biodegradation monitoring capabilities and smart polymer responsiveness are redefining post-operative care protocols. These advances shift value capture toward data-integrated surgical ecosystems.
Antibacterial-impregnated braided sutures with controlled-release triclosan or ionic silver are decentralizing infection prevention responsibility from systemic antibiotics to localized implantable devices. Cardiac and orthopedic surgery departments in tertiary hospitals adopt these variants for prosthetic joint and sternal closure applications. The technology is decentralizing antimicrobial stewardship programs toward procedural supply chain decisions.
EU Medical Device Regulation's clinical evidence requirements for novel polymer formulations are compressing innovation timelines for small manufacturers while favoring established players with retrospective data repositories. Post-market surveillance obligations now mandate 15-year patient follow-up for Class III absorbable implants. Synthetic monofilament cardiac sutures face the most stringent scrutiny as regulators reclassify prolonged tensile strength products as long-term implants.
Hospital purchasing consortia and group procurement organizations are consolidating suture supplier panels to three-to-five preferred vendors per category. Ambulatory surgery chains negotiate multi-year coated braided suture contracts with volume guarantees and standardization clauses. United States integrated delivery networks lead this consolidation, extending compliance requirements to affiliated outpatient surgery centers.
Absorbable Surgical Sutures Market Segmentation
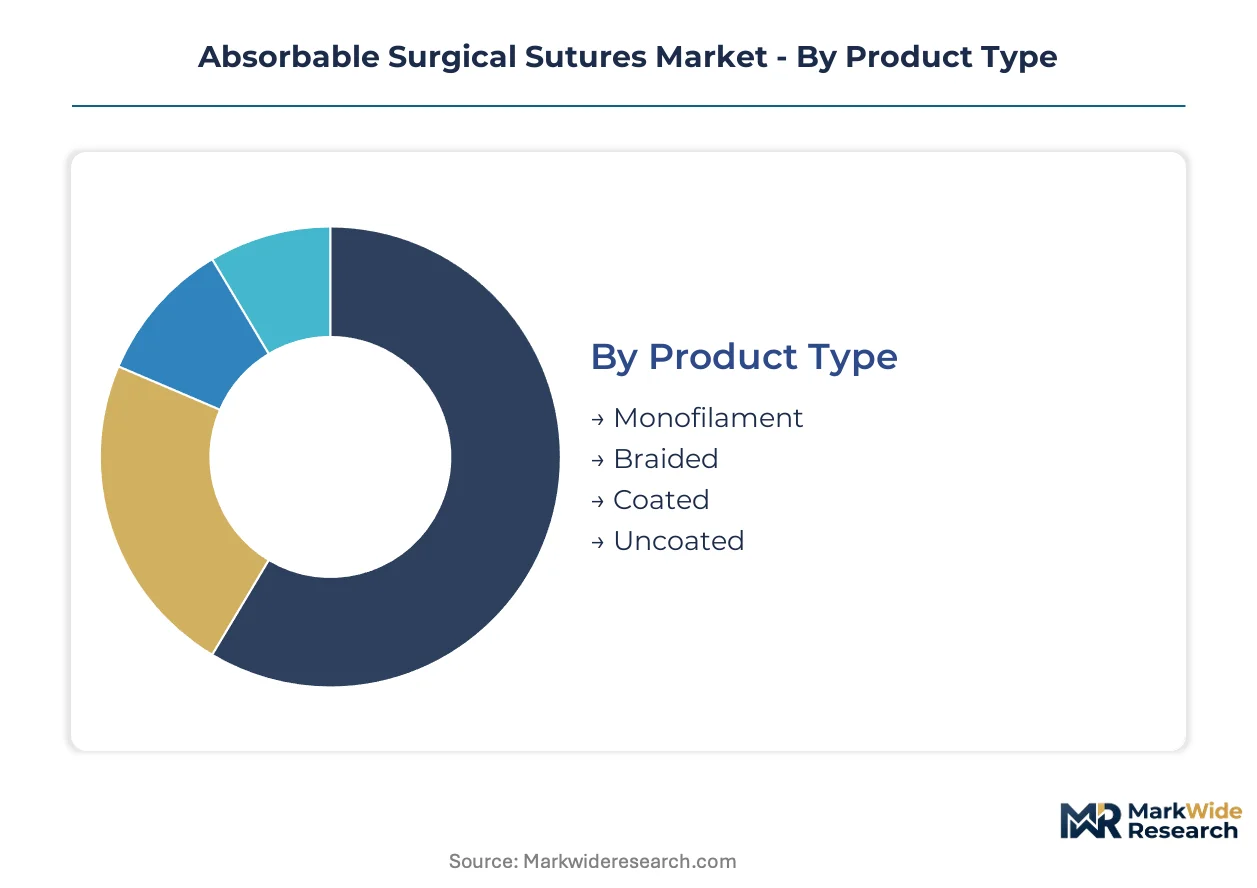
Absorbable suture purchasing behavior fragments sharply across clinical settings and procedure complexity. Hospital procurement committees weight tensile strength degradation curves against sterilization logistics, while ambulatory buyers prioritize knot security and same-day discharge compatibility.
Product Type:
Buyers in this category separate by wound closure complexity and surgeon training heritage.
- Braided:Multifilament construction from polyglycolic acid delivers superior knot security through capillary action between filaments. General surgery departments in United States tertiary hospitals specify braided variants for abdominal wall closures where suture line integrity determines readmission risk.
- Coated:Silicone or polymer surface treatments reduce tissue drag coefficients during needle passage. Orthopedic surgery suites in German university hospitals pay premiums for coated braided lines in tendon repair where gliding resistance affects functional recovery timelines.
- Monofilament:Single-strand polydioxanone structures minimize bacterial wicking through smooth surfaces. Cardiac surgeons favor these for sternal closures in diabetic patients.
- Uncoated:Raw multifilament construction persists in cost-constrained settings where tissue handling speed outweighs drag sensitivity.
Volume sits with Braided; growth tilts toward Coated.
Material:
Material selection tracks procedure duration requirements and institutional formulary politics.
- Polyglycolic Acid:Synthetic polymer hydrolyzes completely within 60-90 days through bulk erosion mechanisms. Mass absorption profiles align with general surgery healing windows.
- Polydioxanone:Extended tensile strength retention over 28 days suits cardiac and orthopedic applications demanding prolonged wound support. Japanese cardiac centers specify this chemistry for valve repair protocols.
- Catgut:Collagen-based absorbable persists in select Indian and Southeast Asian clinics where import substitution policies elevate synthetic pricing.
- Polycaprolactone:Slower degradation kinetics enable orthopedic soft-tissue fixation where scaffold persistence exceeds 180 days.
Polyglycolic Acid commands current procurement volumes; Polycaprolactone exhibits the steepest expansion trajectory in sports medicine applications.
Application:
Application segmentation reflects reimbursement differentials and malpractice exposure severity.
- General Surgery:Appendectomy, herniorrhaphy, and bowel resection procedures consume standardized braided polyglycolic acid in high volumes. United States ambulatory surgery centers negotiate category-specific contracts with guaranteed conversion clauses.
- Orthopedic:Ligament repair and rotator cuff fixation demand coated variants with predictable strength decay curves. German and Swiss trauma centers specify antibacterial-impregnated lines for open fracture protocols.
- Cardiac:Sternal closure and valve annuloplasty require extended support profiles. PMDA scrutiny of prolonged tensile strength products intensifies post-market surveillance obligations.
- Gynecology:Hysterectomy and pelvic floor reconstruction favor monofilament construction in laparoscopic ports.
General Surgery generates absolute volume; Orthopedic applications gain share fastest through sports medicine expansion.
End User:
End user category separates by capital equipment intensity and sterilization infrastructure ownership.
- Hospitals:Integrated delivery networks in the United States consolidate suture purchasing through centralized value analysis committees. Tertiary centers maintain formulary breadth spanning all material chemistries.
- Surgical Centers:Medicare-aligned outpatient facilities in Florida and Texas drive coated braided volume through bundled payment incentives. Standalone sterilization partnerships reduce capital barriers.
- Clinics:Physician office laboratories in rural markets rely on distributor consignment inventory with minimal carrying costs.
- Ambulatory Care:Emergency department fast-track units prioritize rapid inventory turnover over product specialization.
Hospitals retain procurement volume concentration; Surgical Centers capture the fastest expansion rate through site-of-service migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Brunswick anchors North American suture manufacturing through Johnson & Johnson's historic Ethicon operations, while demand concentrates in tertiary hospital clusters across the United States, Germany, Japan, India, and Brazil.
United States
Ambulatory surgical centers in Florida and Texas drive coated braided suture procurement through Medicare-aligned bundled payments. FDA tightened bioresorbable device guidance around polymer degradation profiles. New Brunswick, New Jersey hosts vertically integrated polyglycolic acid resin production serving hospital purchasing contracts nationwide.
Germany
Orthopedic surgery suites in university hospitals pay premiums for coated variants in tendon repair applications. EMA clinical evidence requirements under MDR extend CE marking timelines for novel polymer formulations. Tuttlingen in Baden-Württemberg anchors European manufacturing for braided suture exports.
Japan
Cardiac centers specify polydioxanone chemistry for valve repair protocols requiring extended tensile strength. PMDA intensifies post-market surveillance obligations for prolonged wound support products. Osaka-Kobe industrial corridor concentrates precision polymer processing for medical device applications.
India
CDSCO streamlined registration and PLI scheme incentives attract contract sterilization investment for export-oriented production. Cost-sensitive clinics in secondary cities retain catgut use though synthetics displace collagen-based products. Gujarat pharmaceutical corridors host emerging private-label manufacturing for ambulatory surgery chains.
Brazil
ANVISA harmonization with ISO 10993 standards accelerates multi-jurisdiction product launch strategies for multinational suppliers. São Paulo hospital consortia consolidate supplier panels to preferred vendors with volume guarantees. Southeast industrial zones develop regional packaging and sterilization capabilities.
Absorbable Surgical Sutures Market Vendor Landscape
Premium-margin players sit above commodity-margin players across coating technology and polymer formulation dimensions. The vendor base stratifies into three tiers: vertically integrated resin producers, regional sterilization specialists, and private-label contract manufacturers. Dominant competitive moves include backward integration into polymer feedstock production and geographic expansion through localized sterilization partnerships.
Among diversified medical technology conglomerates, Johnson & Johnson Services, Inc. and Medtronic occupy positions exemplifying scale-driven portfolio breadth, while B. Braun Melsungen AG represents European manufacturing anchoring with emerging market penetration. DemeTECH Corporation sits within the mid-tier specialist archetype between multinational brands and regional suppliers.
| Leading Market Players |
|---|
| Ethicon |
| Medtronic |
| B. Braun Melsungen AG |
| DemeTECH Corporation |
| Johnson & Johnson Services, Inc. |
| Smith & Nephew |
| Teleflex Incorporated |
| Genesis Medtech |
| Healthium Medtech Limited |
| Others |
Supply Flow & Price Mechanics
Ethylene oxide pricing indices cascade through polyglycolic acid and polydioxanone resin production costs, compressing margins for non-integrated manufacturers and forcing three-tier pricing stratification across premium coated, standard braided, and economy monofilament tiers.
Pricing Analysis
Surgical outcome guarantees anchor value-based pricing for antibacterial-impregnated variants in orthopedic and cardiac segments. Price differentiation rests on FDA device classification tier and proprietary coating chemistry, with premium braided lines commanding multiples over commodity monofilament. Cost compression in the economy tier intensifies as Indian contract manufacturers scale export-oriented sterilization capacity. Ambulatory surgery chains exhibit highest price sensitivity through volume-guarantee negotiations, while tertiary cardiac centers prioritize tensile strength performance over unit cost.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions elevates landed costs for European-manufactured braided sutures destined for United States surgical centers. Supply concentrates in the United States, Germany, and India, with New Brunswick and Tuttlingen anchoring resin-to-suture vertical production. Raw material dependencies center on ethylene oxide derivatives, glycol feedstocks, and medical-grade polymer catalysts. Single-source vulnerability concentrates in specialty coating chemical suppliers. Distribution runs through group purchasing organizations and hospital value analysis committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The absorbable sutures market functions as a cost-of-compliance arena where EU MDR clinical evidence requirements and FDA bioresorbable device guidance erect capital barriers that favor incumbent players with retrospective data repositories and sterilization infrastructure.
For Market Incumbents: Anchor manufacturing competitiveness through captive polyglycolic acid resin production and gamma irradiation sterilization upgrades ahead of ethylene oxide emissions restrictions. Defend against barbed closure device substitution by embedding suture lines within integrated surgical platform ecosystems. Prioritize CE marking pathway investments for next-generation antibacterial formulations.
For New Entrants and Emerging Players: Rural Indian clinics and Southeast Asian secondary hospitals represent underserved buyer archetypes where import substitution policies and catgut displacement create white-space opportunity. Target private-label contract manufacturing for United States ambulatory surgery chains seeking cost arbitrage. Pursue CDSCO registration and PLI scheme qualification to establish export-oriented sterilization capacity.
For Investors and Strategic Acquirers: The window for entry favors regional sterilization specialists with polymer chemistry capabilities and established hospital GPO relationships. Long-term viability hinges on regulatory compliance infrastructure rather than product innovation alone. Monitor FDA guidance evolution on drug-device combination classification for antibacterial coatings as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Ethicon's captive polyglycolic acid production insulates margin structure from ethylene oxide volatility. |
| Antibacterial Coating Regulatory Pathway | FDA drug-device combination classification clarity enables premium positioning in orthopedic segments. |
| Localized Sterilization Partnerships | B. Braun's emerging market facility investments reduce logistics costs and customs exposure. |
| Hospital System Partnership | Integrated delivery network consolidation favors suppliers with multi-year volume guarantee capacity. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements demand retrospective data repositories that small entrants lack. |
Methodological Framework
Document review covered FDA 510(k) filings, EMA MDR technical documentation, ISO 10993 biocompatibility standards, and hospital GPO contract databases, complemented by interviews with biomedical engineers, hospital purchasing committee members, polymer R&D directors, and ambulatory surgery center operations managers. Secondary validation drew from customs trade data, SEC medical device segment disclosures, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates and top-down polymer consumption data underwent cross-triangulation.
Segment-level value outputs trace product type, material chemistry, application specialty, and end-user facility tier across the projection horizon. CAGRs derive from installed base erosion rates, procedure volume migration to outpatient settings, and polymer substitution dynamics in cost-sensitive clinics. Forecast inputs incorporate PMDA post-market surveillance intensity evolution and CDSCO registration timeline compression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene oxide emissions regulatory stringency and barbed closure device adoption curves. Forecasts reflect documented assumptions on polymer degradation profile standardization and reimbursement alignment with ambulatory procedures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Global Syringe Market
Medical Supplies
Knife Sterilizer Market