
 Laparoscopic Retrieval Bags Market | 2026-2036
Laparoscopic Retrieval Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Laparoscopic Retrieval Bags Market Outlook
China is rewriting production economics for laparoscopic retrieval bags as domestic medical device manufacturing scales. Johnson & Johnson (Ethicon) leverages its suture and advanced polymer expertise to sustain premium positioning across North American hospital networks. Medtronic anchors its portfolio through integrated minimally invasive surgery ecosystems that bundle retrieval bags with stapling and energy platforms. Applied Medical Resources Corporation differentiates via direct-to-provider distribution that controls pricing and service levels.
Laparoscopic retrieval bags are sterile containment devices manufactured from polyethylene, polypropylene, nylon, or silicone, designed to isolate and extract excised tissue specimens through narrow trocar ports during minimally invasive surgery. These devices typically feature drawstring closures, reinforced seams, and calibrated volumes ranging from 5 mL to 3,000 mL to accommodate specimen sizes from biopsy fragments to intact organs. Single-use bags dominate commercial volume due to infection control protocols, while reusable variants persist in cost-constrained settings where sterilization infrastructure supports turnaround workflows. Nylon and silicone constructions command margin premiums in tumor resection applications where tear resistance prevents specimen fragmentation and subsequent contamination.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements govern material biocompatibility, shelf-life validation, and sterility assurance for all commercialized retrieval bags. Japan's PMDA enforces additional local testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving sterilization standards and single-use plastic reduction mandates across major jurisdictions to anticipate compliance-driven product redesign cycles.
Market Dynamics
EU MDR sterility validation requirements are forcing retrieval bag manufacturers to revalidate entire product lines, compressing margins for polyethylene and polypropylene suppliers while accelerating silicone and nylon adoption in premium segments.
Growth Catalysts
- Minimally Invasive Surgery Expansion:General surgery departments in US hospitals are converting open procedures to laparoscopic approaches, driving consistent retrieval bag consumption per operating room.
- REACH Compliance Premium:EU medical device regulations favor biocompatible silicone constructions that command higher unit economics and longer shelf-life certifications.
- Japan's Aging Surgical Population:PMDA-registered retrieval bags face extended local testing timelines, but the demographic shift toward elderly patients requiring organ resection sustains import demand.
Market Restraints
- Polymer Feedstock Volatility:Nylon and medical-grade polyethylene prices fluctuate with petrochemical input costs, squeezing margin structures for single-use bag manufacturers.
- Chinese Production Concentration:Domestic manufacturing scale in Jiangsu and Zhejiang provinces is consolidating export supply, creating dependency risk for Western distributors.
- Reusable Bag Substitution:Sterilization infrastructure in cost-constrained Indian and Southeast Asian hospitals supports turnaround workflows that displace single-use consumption.
Strategic Opportunities
- Brazilian Market Underpenetration:ANVISA registration pathways for Class II medical devices remain less burdensome than FDA 510(k) or EU MDR, creating first-mover positioning for nylon-reinforced tumor resection bags.
- Integrated MIS Ecosystem Bundling:Retrieval bag placement alongside energy platforms and stapling systems captures procurement decisions at the hospital system level.
- US Single-Use Plastic Mandates:State-level environmental regulations in California and New York are accelerating biodegradable polymer development for specimen containment applications.
Industry Challenges
- EU MDR Technical Documentation:Sterility assurance and shelf-life validation requirements demand extended certification timelines that delay product launches by 18-24 months.
- Polymer Biocompatibility Testing:ISO 10993 cytotoxicity and sensitization protocols require capital-intensive laboratory infrastructure that excludes smaller regional manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparoscopic Retrieval Bags Market |
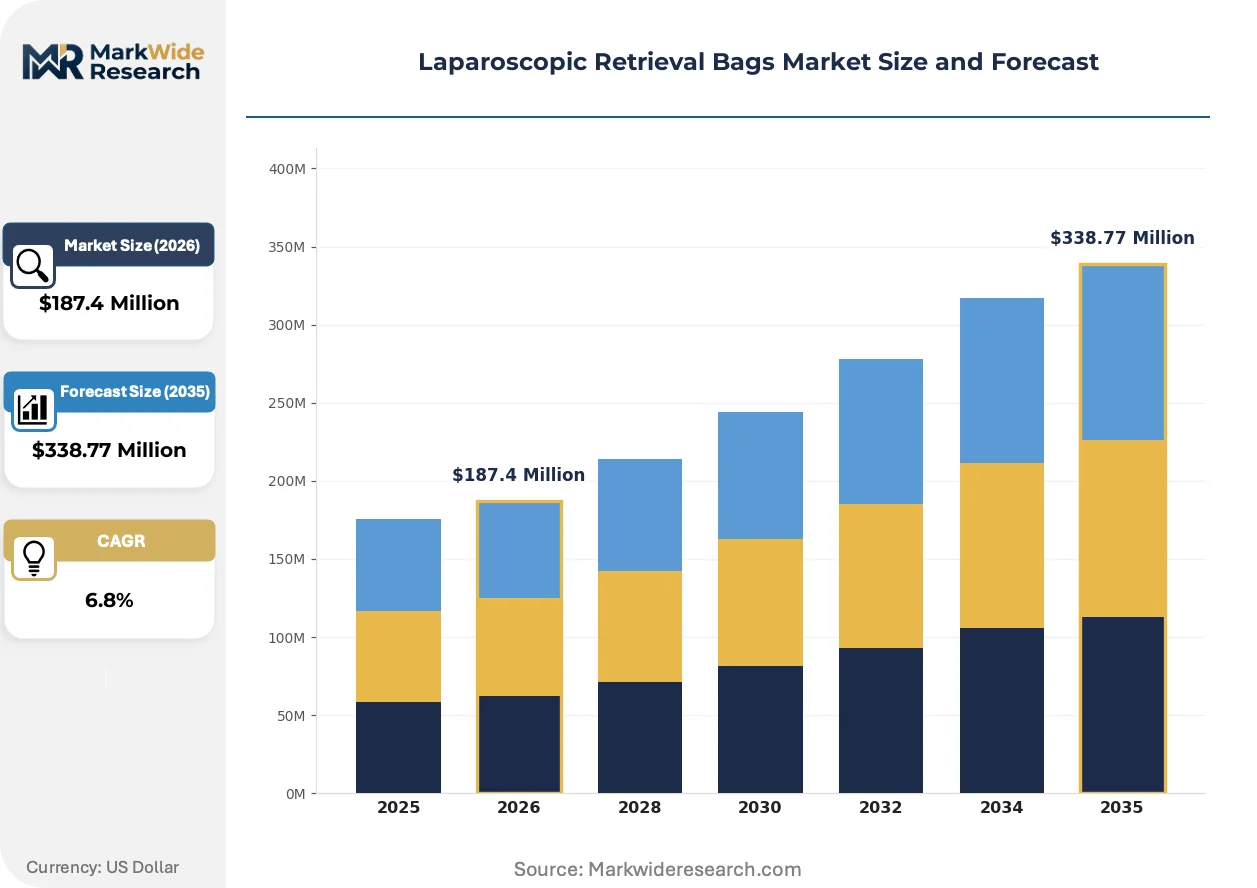
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Customizable, Standard Material: Polyethylene, Polypropylene, Nylon, Silicone End User: Hospitals, Surgical Centers, Clinics, Research Laboratories Application: Gallbladder Removal, Hernia Repair, Tumor Resection, Gynecological Surgery |
| Companies Covered | Johnson & Johnson (Ethicon), Medtronic, Applied Medical Resources Corporation, Teleflex Incorporated, CONMED Corporation, Vernacare Ltd., B. Braun SE, Stryker Corporation, Purple Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparoscopic Retrieval Bags Market Strategic Shifts
Material science breakthroughs and regulatory harmonization pressures are compressing product lifecycles while redrawing competitive boundaries between commodity polyethylene suppliers and specialty silicone compounders.
Silicone-coated nylon laminates are rendering obsolete standard polyethylene retrieval bags in tumor resection applications. Academic medical centers in Germany and Japan are adopting these constructions for specimen integrity during morcellation procedures. Tear-resistant barrier properties are rendering obsolete the risk of fragmentation contamination that constrains reimbursement for open conversion surgeries.
EU MDR Annex I general safety and performance requirements now mandate explicit biological evaluation for all patient-contacting polymers. Manufacturers must submit technical documentation demonstrating compliance with ISO 10993-1 evaluation endpoints before CE marking. Smaller polyethylene bag producers lacking in-house toxicology expertise are outsourcing biocompatibility assessments to notified body consultants, extending time-to-market.
Hospital procurement committees are consolidating retrieval bag purchasing into broader minimally invasive surgery capital equipment contracts. Integrated delivery networks in the United States are displacing individual surgeon preference cards with system-level vendor agreements that bundle bags with trocars and energy devices. This concentration is most visible in Texas and Florida where Catholic health systems and for-profit chains dominate surgical volume.
Laparoscopic Retrieval Bags Market Segmentation
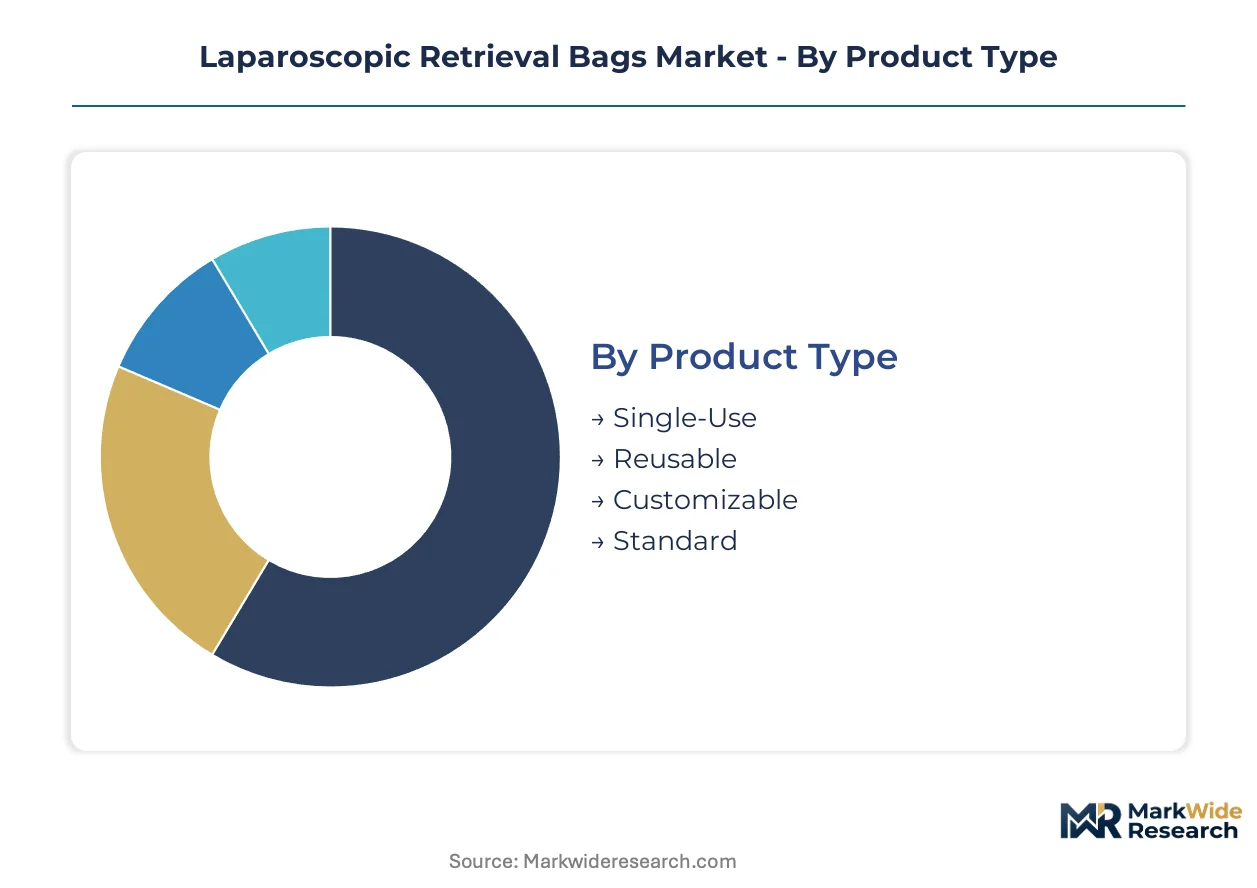
Segmentation in laparoscopic retrieval bags reveals how infection control protocols, material science advances, and surgical workflow requirements partition commercial opportunity across distinct product configurations and customer environments.
Product Type:
Mature single-use formats coexist with emerging reusable alternatives as sterilization infrastructure and cost pressures reshape hospital procurement calculus.
- Single-Use:Sterile polyethylene and polypropylene bags dominate operating room workflows where FDA and EU MDR infection control protocols eliminate cross-contamination risk. General surgery departments in US hospitals drive consistent consumption as minimally invasive procedure volumes expand.
- Reusable:Nylon and silicone constructions withstand gamma sterilization cycles in cost-constrained Indian and Southeast Asian facilities where turnaround logistics support multi-use workflows. Procurement committees in these markets prioritize per-procedure economics over convenience.
- Customizable:Volume-calibrated and drawstring-modified configurations address specialized specimen extraction requirements in academic medical centers.
- Standard:Fixed-dimension bags serve routine gallbladder and hernia procedures where procedural standardization reduces inventory complexity.
Single-Use retains volume leadership; Reusable holds the steepest expansion curve in emerging markets.
Material:
Cost tiers stratify sharply between commodity thermoplastics and specialty elastomers, with reimbursement sensitivity and tumor resection complexity driving material selection.
- Polyethylene:Low-density formulations provide cost-effective containment for routine biopsy fragments and small specimen extraction. Surgical centers in Germany and Japan specify medical-grade polyethylene for high-volume, lower-margin procedures where tear resistance remains secondary.
- Silicone:Platinum-cured elastomers deliver biocompatibility compliance under EU MDR Annex I requirements while offering superior elasticity for organ retrieval. Academic centers in the United States pay premium unit economics for silicone-coated constructions that prevent fragmentation during morcellation.
- Polypropylene:Higher melting point and chemical resistance suit autoclave sterilization protocols in reusable bag applications.
- Nylon:High tensile strength supports reinforced seams and barrier properties for tumor resection where specimen integrity affects oncologic outcomes.
Polyethylene commands the greatest shipment volumes; Silicone gains share fastest in premium tumor resection segments.
End User:
Customer type determines packaging scale, regulatory documentation requirements, and service intensity, with integrated delivery networks consolidating purchasing power.
- Hospitals:General surgery, gynecology, and oncology departments in US hospital systems drive bulk procurement through capital equipment bundling agreements. Catholic health systems and for-profit chains in Texas and Florida centralize retrieval bag purchasing alongside trocar and energy device contracts.
- Surgical Centers:Ambulatory facilities prioritize single-use polyethylene bags for rapid turnover and simplified sterilization logistics. Outpatient hernia and gallbladder volumes in Germany sustain steady consumption of standard configurations.
- Clinics:Lower procedural volumes favor distributor-mediated purchasing with reduced minimum order quantities.
- Research Laboratories:Preclinical and cadaveric training applications require specialized documentation and non-clinical grade materials.
Hospitals absorb the dominant procurement share; Surgical Centers climb fastest as ambulatory migration accelerates.
Application:
Procedure complexity and specimen size requirements segment demand across general surgery, oncology, and gynecology specialties with distinct material performance thresholds.
- Tumor Resection:Large-volume silicone and nylon bags with reinforced seams prevent fragmentation contamination during specimen extraction. Academic medical centers in Japan and Germany adopt tear-resistant laminates for oncologic procedures where open conversion carries reimbursement penalties.
- Gallbladder Removal:Cholecystectomy volumes in US hospitals sustain consumption of mid-size polyethylene bags calibrated for excised tissue dimensions. Standard drawstring closures suffice for this high-frequency, lower-complexity application.
- Hernia Repair:Mesh and tissue extraction requirements favor smaller-volume configurations in ambulatory surgical settings.
- Gynecological Surgery:Hysterectomy and myomectomy procedures demand specialized sizing for uterine specimen containment.
Gallbladder Removal anchors procedure volume; Tumor Resection generates the highest unit economics and material premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the procedural volume leader, with EU MDR technical documentation requirements reshaping competitive access across Western Europe. Japan's PMDA local testing protocols extend registration timelines while sustaining import demand from aging surgical populations.
United States
General surgery departments in Texas and Florida hospital systems drive consistent retrieval bag consumption as minimally invasive cholecystectomy volumes expand. FDA infection control protocols eliminate cross-contamination risk, cementing single-use polyethylene dominance. Catholic health systems and for-profit chains in these states centralize procurement through capital equipment bundling agreements.
Germany
Academic medical centers in Bavaria and Baden-Württemberg adopt silicone-coated nylon laminates for tumor resection procedures where specimen integrity affects oncologic outcomes. EU MDR Annex I biocompatibility requirements favor platinum-cured elastomer constructions. Surgical centers in the Rhine-Ruhr corridor sustain steady consumption of standard polyethylene configurations for outpatient hernia volumes.
Japan
PMDA-registered retrieval bags face extended local testing timelines that compress margin structures for foreign manufacturers. The demographic shift toward elderly patients requiring organ resection sustains import demand for large-volume silicone constructions. Tokyo and Osaka metropolitan areas concentrate procurement decisions at the hospital system level.
China
Domestic manufacturing scale in Jiangsu and Zhejiang provinces consolidates export supply for polyethylene and polypropylene bag production. NMPA registration pathways for Class II medical devices accelerate local substitution. Shanghai-based distributors control pricing and service levels across cost-constrained hospital networks.
Brazil
ANVISA registration pathways for Class II medical devices remain less burdensome than FDA 510(k) or EU MDR, creating first-mover positioning for nylon-reinforced tumor resection bags. São Paulo and Rio de Janeiro surgical centers prioritize per-procedure economics over convenience. Sterilization infrastructure supports reusable bag workflows that displace single-use consumption.
Laparoscopic Retrieval Bags Market Competitive Environment
Capability concentration sits with specialty silicone compounders and advanced polymer fabricators; scale advantage sits with diversified medical device conglomerates. The vendor base separates into three strategic archetypes: integrated minimally invasive surgery platform providers, direct-to-provider distribution specialists, and commodity polyethylene suppliers. M&A activity targets sterilization validation capabilities and biocompatibility testing infrastructure. Geographic expansion into Brazilian and Southeast Asian markets accelerates as ANVISA and local registration pathways offer faster commercialization timelines.
Among diversified platform providers, Johnson & Johnson (Ethicon) and Medtronic exemplify the integrated ecosystem approach that bundles retrieval bags with stapling and energy platforms. Applied Medical Resources Corporation occupies a distinct position through direct-to-provider distribution that controls pricing and service levels independent of traditional hospital supply chain intermediaries.
| Leading Market Players |
|---|
| Johnson & Johnson (Ethicon) |
| Medtronic |
| Applied Medical Resources Corporation |
| Teleflex Incorporated |
| CONMED Corporation |
| Vernacare Ltd. |
| B. Braun SE |
| Stryker Corporation |
| Purple Surgical |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Jiangsu and Zhejiang province medical-grade polymer production is compressing supplier margins while amplifying pricing leverage for domestic Chinese manufacturers serving export markets. This utilization squeeze propagates through polyethylene and polypropylene input costs, forcing Western distributors to absorb volatility or renegotiate long-term offtake terms with hospital procurement committees.
Pricing Analysis
Geographic price spreads between US hospital systems and Southeast Asian facilities exceed threefold for equivalent polyethylene configurations. Three-tier pricing structure across premium silicone-nylon laminates, standard medical-grade polyethylene, and economy polypropylene dominates procurement negotiations. Pricing pressure stems from EU MDR sterility revalidation costs that manufacturers cannot fully pass through to German academic centers. Ambulatory surgical centers in Brazil and India exhibit highest price sensitivity, while US integrated delivery networks prioritize specimen integrity over unit economics in tumor resection applications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for polyethylene and polypropylene bag distributors. Manufacturing concentrates in Jiangsu and Zhejiang provinces of China, with secondary capacity in Germany and Japan for silicone compounding. Raw material dependencies center on medical-grade polyethylene resin, platinum-cured silicone elastomer, and high-tensile nylon fiber. Single-source vulnerability pervades gamma sterilization services for reusable bag workflows. Distribution runs through hospital supply chain intermediaries in Western markets and direct-to-provider channels in cost-constrained regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable bag substitution threatens single-use polyethylene incumbents as sterilization infrastructure expands across Indian and Southeast Asian hospital networks. Incumbents must architect defensive positioning around irreplaceable performance attributes in premium segments.
For Market Incumbents: Pre-empt silicone-nylon laminate commoditization by locking exclusive supply agreements with platinum-cured elastomer compounders before EU MDR certification timelines compress further. Anchor hospital system relationships through integrated minimally invasive surgery platform bundling that embeds retrieval bags within capital equipment contracts. Defend against Chinese manufacturer encroachment by accelerating biodegradability R&D ahead of California and New York single-use plastic mandates. For New Entrants and Emerging Players: Pursue ANVISA-registered nylon-reinforced tumor resection bag positioning in Brazilian metropolitan surgical centers where FDA-equivalent validation burdens remain lighter. Exploit underpenetration in São Paulo and Rio de Janeiro by offering per-procedure economics that displace reusable workflows. Capture initial adoption through direct-to-provider distribution bypassing established supply chain intermediaries. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sterilization validation and ISO 10993 biocompatibility testing infrastructure. Long-term viability favors acquisition targets possessing in-house toxicology expertise and notified body relationships that compress EU MDR time-to-market. Monitor sterilization service provider consolidation as an inflection signal for downstream pricing power redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerated CE marking timelines defend German market access against undercertified competitors. |
| Silicone-Nylon Laminate Capacity Expansion | Captures premium tumor resection volumes in Japan and US academic medical centers. |
| Biodegradable Polymer R&D Partnership | Anticipates California and New York environmental compliance mandates before enforcement. |
| Direct-to-Provider Distribution Buildout | Displaces traditional intermediaries in Brazilian and Southeast Asian cost-constrained markets. |
| Integrated MIS Platform Bundling | Locks hospital procurement decisions alongside trocar and energy device capital contracts. |
Study Parameters
A spread of perspectives from hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions driving segmentation and demand modeling. Primary fieldwork across these stakeholder categories combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and customs trade records. Bottom-up procedure volume estimates and top-down polymer consumption data were triangulated to anchor market sizing.
Demand-supply balance dynamics across the analysis window shaped the forecast framework. Segmentation dimensions modeled include product type, material composition, end-user facility category, and surgical application complexity. CAGRs were derived from procedure volume trajectories, material substitution elasticities, and pricing pass-through coefficients. Key inputs encompassed laparoscopic surgery conversion rates in US hospital systems and EU MDR compliance cost absorption rates.
Sensitivities concentrate around EU MDR sterility revalidation timelines, Chinese export tariff policy shifts, and single-use plastic mandate enforcement schedules. Forecasts reflect documented assumptions regarding polymer feedstock price stability and hospital capital equipment procurement cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Bags Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Americas Medical Rubber and Balloon Product Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
Saudi Arabia Hospital Supplies Market
Medical Supplies
Suture Sleeve Kit Market