
 Drainage Bottles Market | 2026-2036
Drainage Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Drainage Bottles Market Intelligence
Post-surgical care is broadening as the dominant end-use vertical, pulling demand from traditional inpatient settings toward ambulatory surgical centers and home care transitions. B. Braun Melsungen AG leverages its European manufacturing footprint to sustain supply chain reliability across multiple continents. Rocket Medical Plc anchors its position through specialized closed drain system design. Jigsaw Medical competes on flexible production scales that serve mid-tier hospital networks.
Drainage bottles are sealed receptacles, typically manufactured from medical-grade polymers or silicone, engineered to collect and quantify bodily fluids while maintaining negative pressure or gravity-driven flow. Their primary purpose centers on post-operative fluid management, infection containment, and wound healing monitoring across acute and sub-acute care environments. Closed drain systems command the strongest margin pools due to sterility assurance requirements, while suction bottles lead volume through standardized operating room procurement. Plastic dominates material selection for disposability economics, though silicone gains traction in extended-wear applications where biocompatibility and flexibility reduce tissue trauma.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access barriers for manufacturers serving North American and European buyers. ISO 13485 quality management standards further constrain supplier qualification, particularly for sterile fluid-path components. Stakeholders must monitor evolving home care reimbursement codes and ambulatory surgery center accreditation standards, as these will determine whether premium closed-system designs capture share from conventional collection bottles.
Market Dynamics
Same-day discharge mandates across the United States, Germany, and Japan are compressing hospital length-of-stay windows, forcing fluid management systems to migrate from inpatient wards into ambulatory surgical centers and home care settings. This structural shift demands portable, closed-system designs that maintain sterility outside controlled clinical environments.
Growth Catalysts
- Ambulatory Surgery Center Accreditation Standards:Joint Commission and AAAHC requirements for infection control are mandating closed-drain systems in outpatient settings, expanding addressable demand beyond traditional hospitals.
- Silicone Biocompatibility:Extended-wear silicone bottles reduce tissue trauma in chronic wound applications, opening reimbursement pathways for home-based post-operative monitoring.
- Japan's Aging Surgical Population:METI-promoted same-day protocols for elderly patients require portable drainage solutions that bridge hospital-to-home transitions without readmission risk.
Market Restraints
- Medical-Grade Polymer Feedstock Volatility:Propylene and ethylene price swings squeeze margins on disposable plastic bottles, which constitute the volume-dominant material segment.
- EU MDR Technical Documentation Burden:Extended conformity assessment timelines for Class IIa fluid-path devices delay product launches and tie up regulatory capital for 18-24 months.
- Negative Pressure Wound Therapy Substitution:Single-use NPWT systems with integrated collection can displace standalone drainage bottles in select soft-tissue applications.
Strategic Opportunities
- Home Care Reimbursement Code Expansion:CMS and private payers in the United States are piloting remote patient monitoring codes that cover take-home closed-drain systems with digital output tracking.
- Smart Sensor Convergence:Bluetooth-enabled volume sensors paired with mobile health platforms enable real-time fluid monitoring, creating premium pricing tiers for connected devices.
- German Outpatient Surgery Infrastructure:Federal Hospital Structure Act incentives are accelerating ambulatory center construction, concentrating demand for compact, patient-portable collection systems.
Industry Challenges
- ISO 13485 Quality Management Talent Scarcity:Sterile fluid-path manufacturing requires specialized auditors and process engineers that mid-tier suppliers struggle to recruit and retain.
- FDA 510(k) Predicate Device Fragmentation:Evolving substantial equivalence standards for closed-system designs force repeated clinical validation studies, extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drainage Bottles Market |
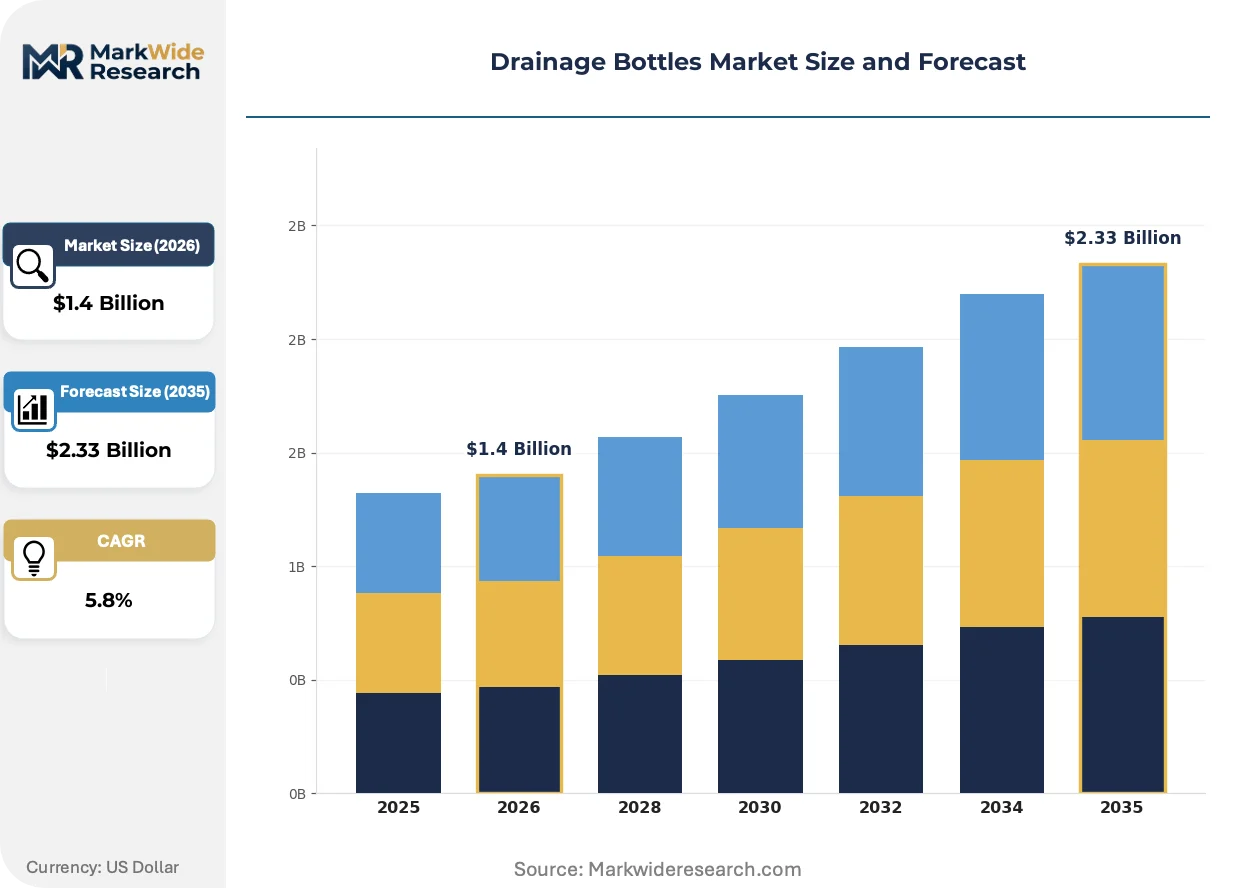
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suction Bottles, Collection Bottles, Drainage Bags, Closed Drain Systems Application: Post-Surgical Care, Wound Management, Fluid Monitoring, Abscess Treatment End User: Hospitals, Home Care Settings, Ambulatory Surgical Centers, Long-Term Care Facilities Material: Plastic, Glass, Silicone, Rubber |
| Companies Covered | B. Braun Melsungen AG, Rocket Medical Plc, Jigsaw Medical, Sterimed Group, PFM Medical, Hospitech, Lily Medical Corporation, Medinorm, PAHSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drainage Bottles Market Strategic Shifts & Innovations
Digital connectivity and materials science are converging to transform drainage bottles from passive collection vessels into active monitoring platforms. Three developments are compressing traditional product lifecycles and rewiring competitive advantage.
Antimicrobial polymer formulations incorporating silver-ion or copper-nanoparticle additives are converging with standard medical-grade plastics to reduce biofilm formation in extended-wear applications. Ambulatory surgical centers in Germany and Japan are piloting these surfaces for multi-day home discharge protocols. This convergence is enabling premium pricing for bottles that reduce per-patient infection risk below 2% thresholds.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for all fluid-path devices, including legacy drainage bottle designs previously grandfathered under the Medical Devices Directive. Manufacturers serving European buyers must rebuild quality management systems around post-market surveillance and risk management files. Class IIa closed-drain systems face the steepest compliance cost inflation as notified bodies apply stricter biological evaluation standards.
Hospital procurement departments are consolidating vendor lists around full-line fluid management suppliers, displacing standalone bottle specialists from tier-one contracts. Integrated operating room suites in the United States now specify suction-canister-drainage systems from single sources to simplify sterilization validation and reduce SKU complexity. This concentration is most visible in multi-hospital systems pursuing standardization across 50+ facility networks.
Drainage Bottles Market Segmentation
Drainage bottle procurement patterns diverge sharply across clinical settings, with infection control mandates in ambulatory environments and reimbursement pathways in home care creating distinct performance requirements for each segment. Manufacturers must align material selection and system design to these divergent buyer priorities rather than pursuing one-size-fits-all specifications.
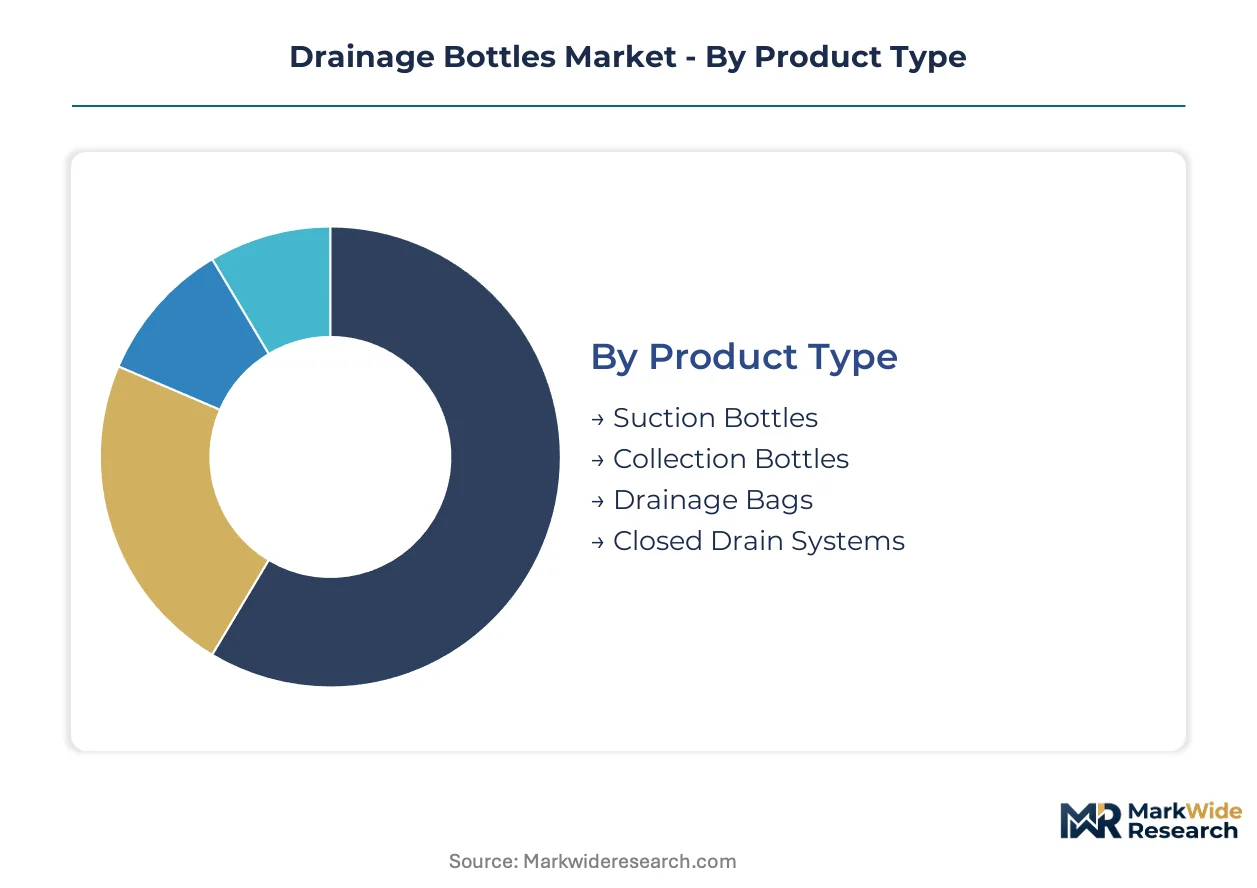
Product Type:
Hospital purchasing departments prioritize sterility assurance levels over unit cost when selecting between open and closed system architectures.
- Suction Bottles:Vacuum-assisted vessels engineered for operating room fluid evacuation connect directly to wall suction or portable pumps. Standardized procurement across United States hospital networks concentrates demand for high-volume disposable units, though propylene feedstock volatility squeezes margins on these price-sensitive contracts.
- Closed Drain Systems:Sealed fluid-path designs with integrated check valves and sampling ports maintain negative pressure without environmental contamination. Joint Commission accreditation requirements for ambulatory surgical centers in the United States and AAAHC standards are accelerating displacement of open collection methods in outpatient settings.
- Collection Bottles:Passive gravity-fed receptacles serve post-operative ward monitoring where suction infrastructure is unavailable. German hospital procurement coalitions favor these for standardized ward kits across multi-facility networks.
- Drainage Bags:Flexible polymer pouches with graduated measurement scales enable ambulatory patient mobility. Japan's METI-promoted same-day discharge protocols for elderly surgical patients drive demand for lightweight, concealable designs that bridge hospital-to-home transitions.
Suction bottles lead volumes today; closed drain systems are gaining share fastest.
Application:
Reimbursement coding density determines which applications attract premium system development versus commodity supply contracts.
- Post-Surgical Care:Fluid management following abdominal, thoracic, and orthopedic procedures requires precise output quantification for clinical decision-making. CMS remote patient monitoring pilot programs in the United States are creating reimbursement pathways for take-home closed-drain systems with digital output tracking.
- Wound Management:Extended-wear drainage for chronic or dehisced wounds demands biocompatible materials that minimize tissue trauma. Silicone bottle adoption climbs in German outpatient protocols where multi-day home discharge reduces readmission penalties.
- Fluid Monitoring:Quantitative measurement of pleural, peritoneal, or cerebrospinal fluid output supports diagnostic and therapeutic adjustments. Hospital laboratory integration requirements favor systems with standardized sampling ports.
- Abscess Treatment:Percutaneous drainage of deep-seated infections requires radiopaque materials compatible with imaging guidance. Interventional radiology departments in Japanese tertiary centers specify specialized high-visibility bottles.
Post-surgical care commands the largest revenue pool; wound management applications are expanding most quickly.
End User:
Facility accreditation standards and patient acuity levels create tiered performance requirements that fragment procurement specifications.
- Hospitals:Inpatient surgical wards and intensive care units specify integrated suction-canister systems from single-source suppliers to simplify sterilization validation. United States multi-hospital systems pursuing standardization across 50+ facility networks are consolidating vendor lists around full-line fluid management providers.
- Ambulatory Surgical Centers:Outpatient facilities face Joint Commission and AAAHC infection control mandates that mandate closed-drain systems with documented sterility maintenance. Federal Hospital Structure Act incentives in Germany are accelerating ambulatory center construction, concentrating demand for compact, patient-portable collection systems.
- Home Care Settings:Post-discharge fluid management requires portable designs that maintain safety outside controlled clinical environments. Bluetooth-enabled volume sensors paired with mobile health platforms are creating premium pricing tiers for connected devices in United States pilot markets.
- Long-Term Care Facilities:Skilled nursing environments manage chronic wound drainage with extended-wear systems that reduce staff intervention frequency. Reimbursement constraints favor cost-optimized plastic designs over silicone alternatives.
Hospitals retain the dominant volume position; ambulatory surgical centers are climbing the fastest.
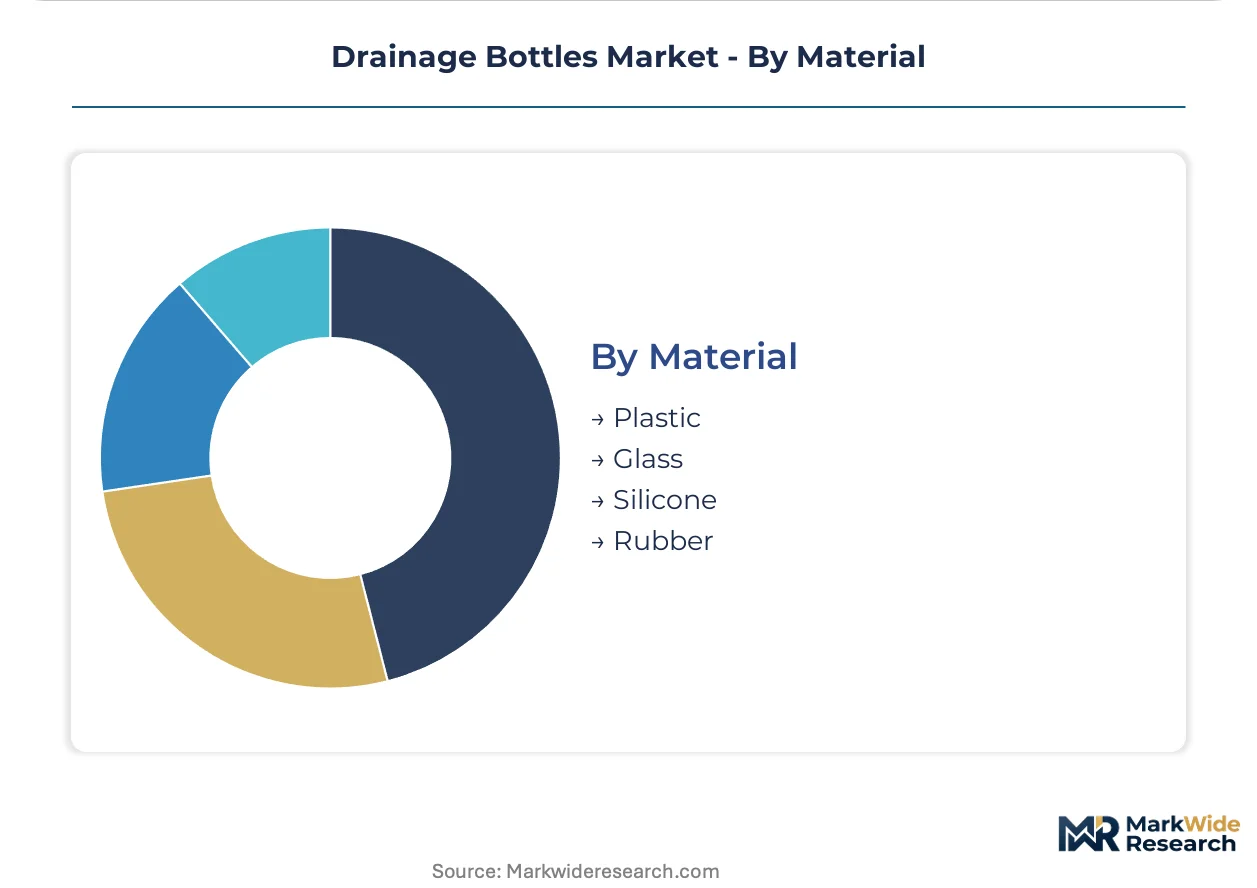
Material:
Cost-per-use economics and wear duration requirements split material selection between disposable and extended-use applications.
- Plastic:Medical-grade polypropylene and polyethylene dominate single-use applications where disposability economics outweigh material performance. Ethylene and propylene price volatility directly impacts manufacturing margins on high-volume contracts.
- Silicone:Biocompatible elastomers reduce tissue trauma in extended-wear wound management applications, opening reimbursement pathways for home-based post-operative monitoring in German and Japanese markets.
- Glass:Inert borosilicate vessels persist in laboratory and pharmaceutical manufacturing settings requiring chemical resistance and autoclave compatibility. Clinical drainage applications have largely displaced glass due to breakage risk.
- Rubber:Natural and synthetic elastomers serve specialized gaskets, seals, and flexible tubing components within integrated drainage systems. Latex-free formulations are mandatory for United States and European hospital procurement.
Plastic leads volumes today; silicone is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR compliance costs drive some production toward jurisdictions with lighter documentation burdens, though sterility-critical applications remain anchored in established medical-device clusters.
United States
Same-day discharge protocols from CMS are compressing hospital stays and forcing fluid management into ambulatory surgical centers. FDA 510(k) clearance requirements for closed-system designs create barriers for new entrants but protect incumbent positions. The Minneapolis-St. Paul corridor hosts dense clusters of suction-canister manufacturers serving integrated operating room suites.
Germany
Federal Hospital Structure Act incentives are accelerating ambulatory center construction across Baden-Württemberg and Bavaria. EU MDR Article 10 technical documentation mandates for Class IIa devices extend conformity timelines to 18-24 months. The Tuttlingen medical-device cluster sustains specialized closed-drain production for European hospital networks.
Japan
METI-promoted same-day protocols for elderly surgical patients require portable drainage bridging hospital-to-home transitions. PMDA quality management standards align with ISO 13485 but impose additional post-market surveillance obligations. The Kansai region around Osaka concentrates silicone bottle manufacturing for extended-wear applications.
China
NMPA regulatory harmonization with international standards is improving market access for imported closed-system designs while domestic manufacturers capture commodity suction bottle volumes. The Yangtze River Delta medical-device manufacturing belt scales production of disposable plastic collection vessels for Asia-Pacific distribution.
India
CDSCO medical device rules are tightening sterility documentation requirements for imported drainage systems while domestic producers expand capacity for standard ward collection bottles. The Gujarat pharmaceutical and medical-device corridor near Ahmedabad is adding polymer molding capacity for disposable fluid management products.
Drainage Bottles Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated full-line suppliers commanding tier-one hospital contracts while regional fabricators serve price-sensitive ward applications. The vendor base clusters around three strategic archetypes: European quality-leaders with MDR-validated quality systems, Asian scale-producers leveraging polymer conversion economics, and specialized closed-system designers competing on sterility assurance. Consolidation pressures are intensifying as multi-hospital systems reduce vendor counts, while technology licensing partnerships accelerate smart-sensor integration without captive R&D investment.
Among European quality-leaders, B. Braun Melsungen AG represents the vertically integrated multinational archetype with manufacturing footprints spanning multiple continents, while Rocket Medical Plc exemplifies the specialized closed-system designer focused on sterility-critical applications. Jigsaw Medical occupies a position within the flexible-production tier serving mid-tier hospital networks with adaptable scale economics. These three anchors illustrate how competitive positioning diverges between premium validated-system suppliers and volume-oriented commodity producers.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Rocket Medical Plc |
| Jigsaw Medical |
| Sterimed Group |
| PFM Medical |
| Hospitech |
| Lily Medical Corporation |
| Medinorm |
| PAHSCO |
| Others |
Cost & Logistics Intelligence
EU MDR Article 10 technical documentation mandates for Class IIa fluid-path devices gate qualified supply access and premium-tier pricing power for drainage bottle manufacturers. Sterility-critical applications command margin premiums only from suppliers with notified body-validated quality systems, while commodity suction bottle contracts face cost compression from polymer feedstock volatility.
Pricing Analysis
Distributor margins on closed-drain systems run 15-25 points above suction bottle equivalents due to sterility assurance complexity. Three-tier pricing structure across premium, standard, and economy levels separates MDR-validated European suppliers from Asian scale-producers and regional fabricators. Cost compression in plastic disposable tiers is intensifying because propylene and ethylene price swings squeeze contract margins. Ambulatory surgical centers exhibit highest price sensitivity for ward collection bottles; integrated operating room suites show lowest sensitivity for validated closed-system designs.
Supply Chain Analysis
Domestic-content requirements under India's CDSCO medical device rules and China's NMPA procurement preferences are reshaping sourcing toward local polymer conversion capacity. Medical-grade polypropylene supply concentrates in Germany, China, and the United States around specialized medical-device molding clusters. Raw material dependencies rest on propylene monomer, ethylene feedstock, and silicone elastomer grades. Single-source vulnerability runs through European notified body capacity for MDR conformity assessments. Distribution runs through hospital procurement coalitions, GPO contracts, and ambulatory center group purchasing in tier-one markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drainage bottles market functions as a regulatory compounder where EU MDR compliance timelines and FDA 510(k) predicate fragmentation continuously elevate barriers for undercapitalized competitors, concentrating returns among validated-system suppliers.
For Market Incumbents: Cement tier-one hospital system relationships through exclusive suction-canister-drainage system contracts that simplify sterilization validation across 50-plus facility networks. Expand backward integration into medical-grade polymer compounding to buffer propylene feedstock volatility on high-volume disposable contracts. Negative pressure wound therapy substitution threat demands accelerated smart-sensor development to preserve premium positioning. For New Entrants and Emerging Players: Launch via direct-to-ambulatory-center distribution models targeting German Federal Hospital Structure Act incentive zones where compact patient-portable collection systems face supply shortages. Home care reimbursement code expansion in United States pilot markets represents the most penetrable white-space for Bluetooth-enabled volume sensor platforms. Bypass hospital procurement consolidation by anchoring in mid-tier ASC networks outside integrated system orbits. For Investors and Strategic Acquirers: Roll-up economics work for specialized closed-system designers because EU MDR technical documentation burdens create stranded asset opportunities among undercapitalized regional fabricators facing 18-to-24 month conformity delays. Five-to-ten year viability hinges on sterility-critical application exposure rather than commodity ward supply positioning. Watch CMS remote patient monitoring code finalization as inflection indicator for connected device premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Rebuild | Notified body validation unlocks European hospital procurement access for Class IIa closed-drain systems. |
| Smart Sensor Platform Development | Bluetooth-enabled volume tracking creates premium pricing tiers in United States home care pilot markets. |
| Polymer Compounding Integration | In-house medical-grade polypropylene production buffers ethylene price volatility on disposable contracts. |
| Ambulatory Center Partnership | Joint Commission accreditation requirements mandate closed-drain systems in outpatient construction booms. |
| Silicone Biocompatibility Investment | Extended-wear elastomer formulations reduce tissue trauma for German and Japanese elderly discharge protocols. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture procurement pattern shifts and regulatory interpretation variance. Primary engagement spanned hospital purchasing committee members, GPO contracts managers, biomedical engineers, and ambulatory surgical center accreditation officers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation databases, CMS reimbursement code proposals, and hospital procurement coalition contract disclosures. Bottom-up facility-level demand modeling and top-down polymer feedstock consumption analysis triangulated volume estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baseline utilization patterns and post-MDR implementation compliance cost trajectories. Segmentation modeling captured product type architecture, application reimbursement density, end-user accreditation tier, and material biocompatibility grade. CAGRs derived from facility construction pipelines, same-day discharge protocol adoption curves, and raw material price elasticity assumptions. Silicone extended-wear adoption rates and smart sensor attach rates served as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints or polymer feedstock supply disruptions. Analytical boundaries exclude non-medical fluid collection applications and veterinary surgical markets. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
Medical Disposables Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Disposable Masks Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Global Needles Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Bleeding Control Kit Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Surgical and Examination Gloves Market