
 Aspirating System Market | 2026-2036
Aspirating System Market Size, Share, and Industry Trends Forecast 2026-2036
Aspirating System Market Outlook
Certified fire safety technician shortages across Western Europe are unwinding project timelines for large-scale centralized aspirating installations. Stryker Corporation leverages its hospital equipment integration expertise to bundle aspirating systems with surgical suites. Honeywell International Inc. dominates commercial building fire safety channels where aspirating smoke detection requirements are tightening. Siemens AG anchors European project pipelines through direct relationships with infrastructure contractors and regulatory consultants.
An aspirating system draws air samples through a network of pipes to a centralized detection unit, achieving sensitivity thresholds of 0.005% obs/m for early smoke identification in critical environments. Fixed systems lead hospital and data center deployments due to permanent infrastructure integration and lower lifetime maintenance burden. Software-integrated systems represent the fastest-expanding technology segment as building management platforms demand real-time airflow analytics and predictive filter-replacement alerts. Portable systems occupy a mature niche in emergency services where rapid deployment outweighs sensitivity optimization.
NFPA 72 standards in the United States and EN 54-20 certification in Europe mandate minimum sensitivity and false-alarm resistance thresholds that filter out uncertified aspirating equipment. FDA oversight of surgical suction devices and EPA ventilation requirements for laboratory environments create dual compliance pathways for manufacturers serving healthcare and research end users. Stakeholders must monitor divergence between mechanical and electronic system certification timelines as software-integrated platforms introduce cybersecurity review layers previously absent from fire safety product approval processes.
Market Dynamics
Centralized aspirating architecture is displacing point-source detection in hospitals and data centers, driven by NFPA 72 sensitivity mandates and the operational cost of maintaining distributed sensor networks across sprawling facilities.
Growth Catalysts
- NFPA 72 Chapter 17:United States fire safety codes now mandate enhanced smoke detection sensitivity in healthcare occupancies, forcing hospital infrastructure upgrades toward aspirating networks.
- Data center thermal density:Hyperscale computing facilities in Germany and Japan are installing fixed aspirating systems to achieve sub-fire suppression thresholds and protect server uptime.
- Filter analytics software:Predictive maintenance algorithms embedded in building management platforms are reducing downtime costs and accelerating replacement of legacy detection hardware.
Market Restraints
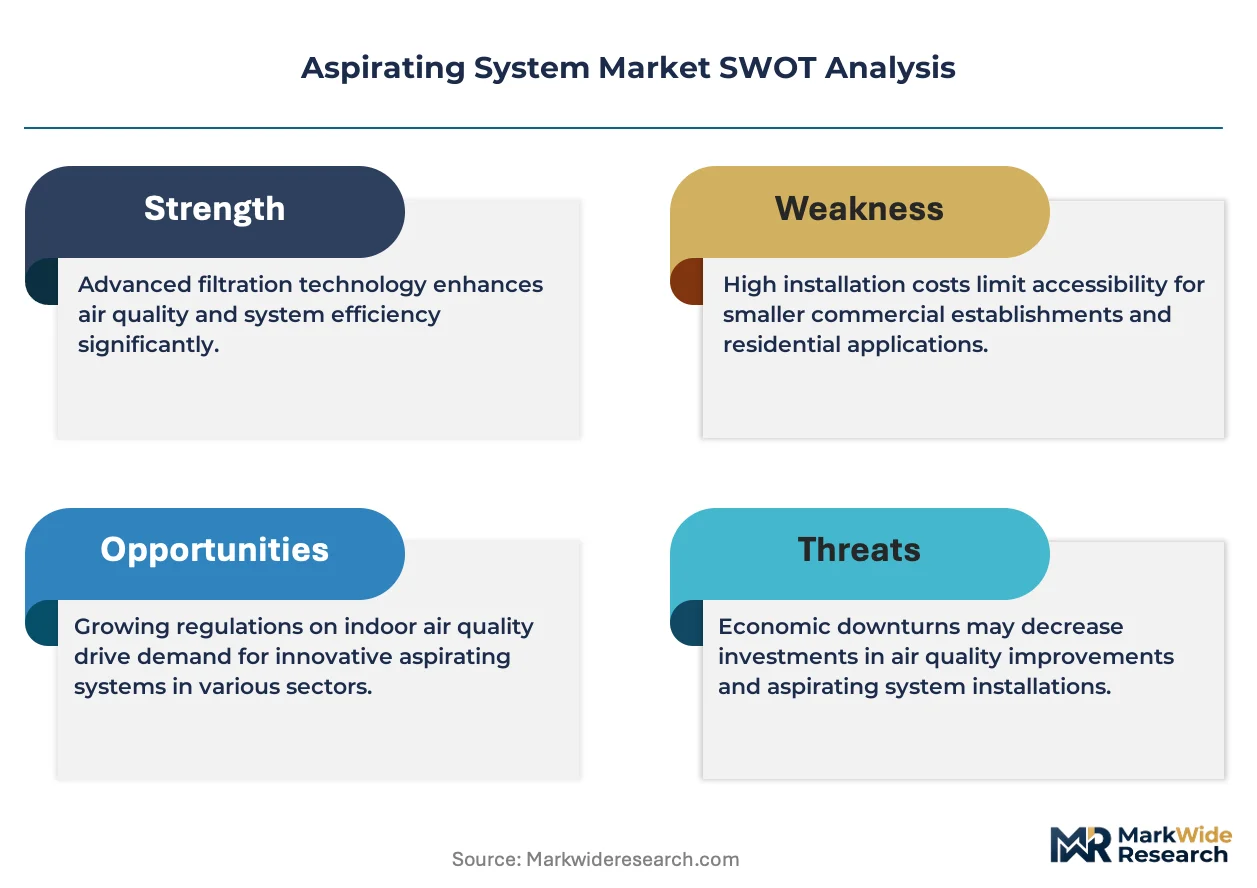
- Certified technician scarcity:Western Europe faces acute shortages of EN 54-20 qualified installation specialists, extending project timelines for centralized systems by six to twelve months.
- Copper and polymer input volatility:Pipe network materials face commodity price swings that compress margins on fixed-installation contracts with locked pricing.
- Point-source sensor substitution:Advanced photoelectric detectors with wireless mesh networking threaten aspirating penetration in smaller commercial buildings under five thousand square meters.
Strategic Opportunities
- India healthcare infrastructure:Government hospital modernization programs under the National Health Mission create first-mover advantage for aspirating system vendors establishing local service networks.
- Laboratory containment convergence:Integration of aspirating smoke detection with EPA-mandated ventilation monitoring opens dual-revenue streams in pharmaceutical and biosecurity facilities.
- Direct-to-contractor distribution:Bypassing traditional fire safety distributors through digital specification platforms reduces channel costs and accelerates specification capture in commercial construction.
Industry Challenges
- Cybersecurity certification layers:Software-integrated aspirating platforms now face FDA and FCC review timelines that lag mechanical system approvals by eight to fourteen months.
- Legacy building integration:Retrofit installations in pre-1990 hospital infrastructure require custom pipe routing that doubles labor content and extends commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aspirating System Market |
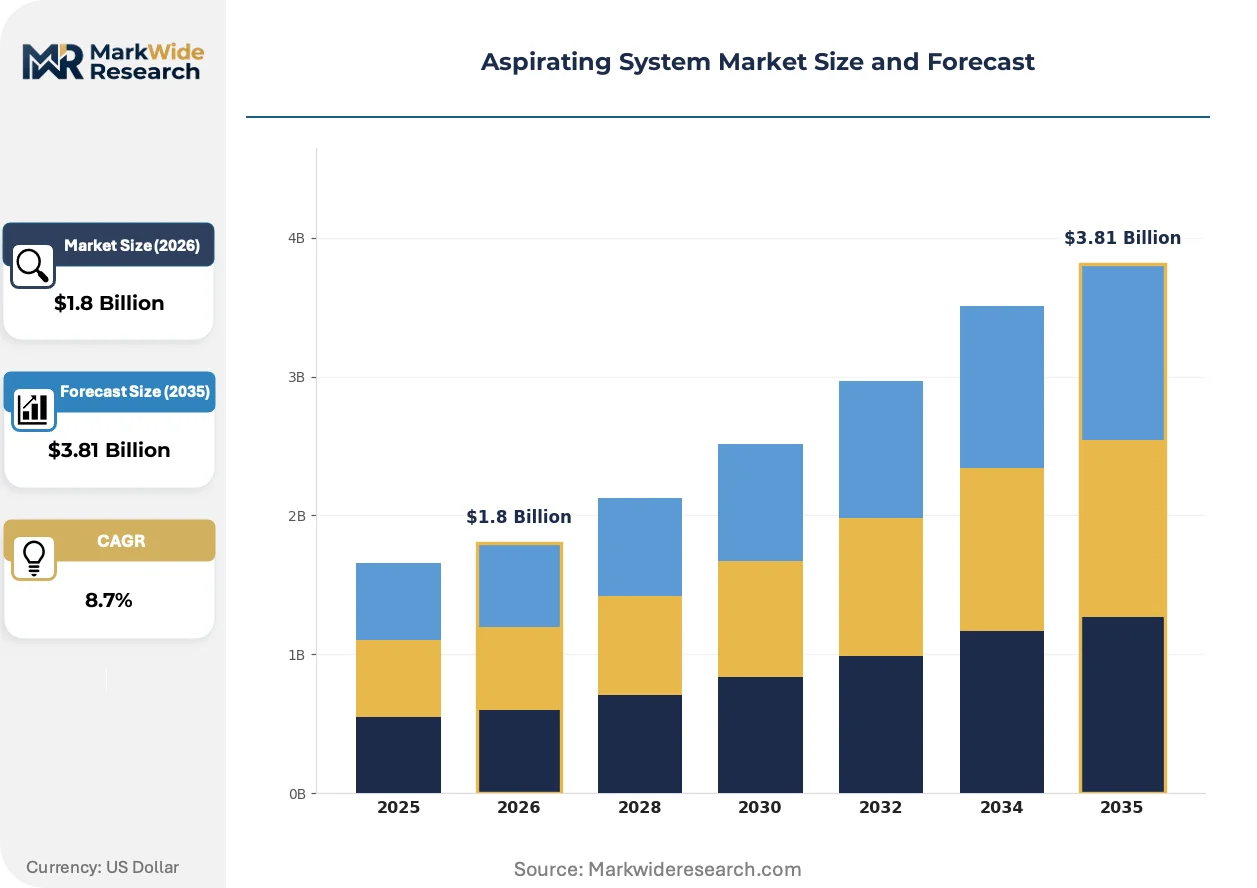
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Fixed Systems, Centralized Systems, Custom Systems End User: Hospitals, Clinical Labs, Research Institutions, Diagnostic Centers Application: Emergency Services, Surgical Procedures, Laboratory Analysis, Environmental Monitoring Technology: Mechanical Systems, Electronic Systems, Software-Integrated Systems, Advanced Automation |
| Companies Covered | Stryker Corporation, Penumbra Inc., Honeywell International Inc., Johnson Controls, Teleflex Incorporated, Siemens AG, Boston Scientific Corporation, Bosch Security Systems, Medtronic Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aspirating System Market Strategic Shifts
Detection sensitivity thresholds, regulatory harmonization pressures, and procurement model fragmentation are simultaneously compressing product cycles and expanding the addressable installed base for aspirating technologies.
Multi-channel infrared laser detection is miniaturizing. This technology replaces single-wavelength sources to discriminate between smoke particulates and common airborne contaminants. Hospital surgical suites and pharmaceutical cleanrooms in Japan and Germany are adopting these units at twice the pace of standard configurations. The form factor reduction is miniaturizing centralized detection units from rack-mounted enclosures to wall-mounted panels, opening retrofit applications previously inaccessible due to space constraints.
REACH substance restrictions on halogenated flame retardants are forcing pipe material reformulation across European deployments. Manufacturers must validate alternative polymer compounds for smoke transport efficiency and long-term degradation resistance. Germany and France are experiencing the most acute compliance pressure, with project specifications now requiring material safety data sheets documenting full chemical composition prior to bid submission.
Hospital procurement departments are unbundling aspirating system specification from general fire safety contracts. This shift fragments vendor relationships that previously consolidated detection, suppression, and notification under single-source agreements. Medical center purchasing consortia in the United States are driving this pattern, using centralized capital planning to extract volume discounts on aspirating hardware while retaining local contractor relationships for installation and commissioning.
Aspirating System Market Segmentation
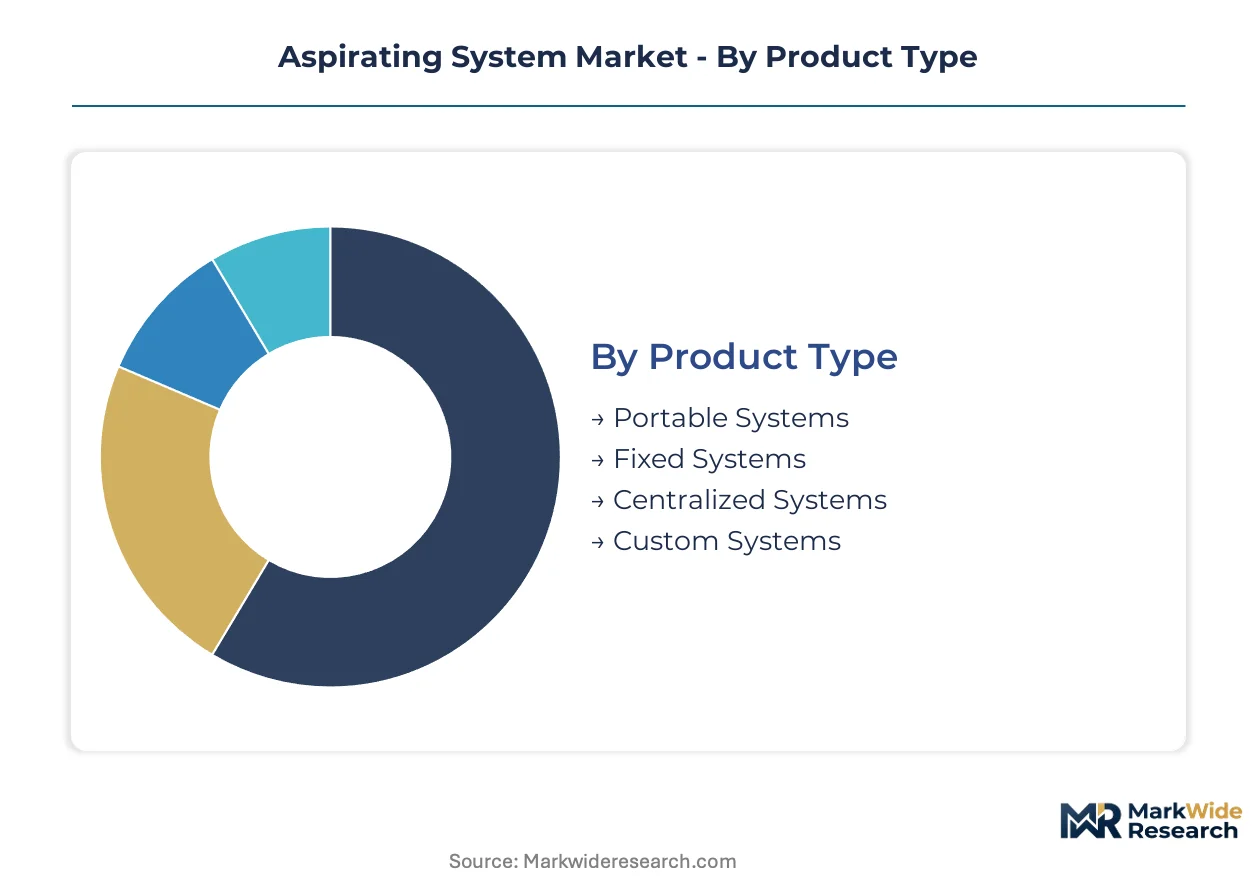
Aspirating system procurement splits sharply between permanent infrastructure investments and mobile emergency deployments, with technology integration levels determining lifetime service revenue potential. Understanding where specification authority sits—facilities engineering, clinical departments, or procurement consortia—shapes go-to-market economics across each segment axis.
Product Type:
Margin pools concentrate in fixed and centralized installations where pipe network complexity extends project duration and service attachment rates.
- Portable Systems:Battery-powered or cart-mounted units deliver suction capability for field emergency response and patient transport. Demand clusters with municipal fire departments and ambulance services in Germany and Japan where EN 54-20 and JIS standards mandate rapid-deployment redundancy.
- Fixed Systems:Wall-mounted or ceiling-recessed units with dedicated power and exhaust infrastructure dominate hospital surgical suites and intensive care wards. The United States accounts for disproportionate fixed-system volume as NFPA 72 Chapter 17 drives replacement of legacy point-source detection in healthcare occupancies.
- Centralized Systems:Multi-zone pipe networks feeding rack-mounted detection units achieve 0.005% obs/m sensitivity thresholds for data center and pharmaceutical cleanroom protection.
- Custom Systems:Bespoke configurations address atypical ceiling geometries or contamination-critical environments such as BSL-4 laboratories.
The dominant share belongs to Fixed Systems, while Centralized Systems is closing the gap fastest as hyperscale computing facilities expand in Germany and Japan.
End User:
Specification authority and procurement cycle length vary dramatically across clinical versus research environments, with hospitals consolidating purchasing through equipment standardization programs.
- Hospitals:Acute care facilities drive the majority of aspirating system revenue through surgical suite renovations and fire safety infrastructure mandates. United States medical centers under Joint Commission accreditation pressure are unbundling aspirating specification from general fire safety contracts to extract volume discounts.
- Clinical Labs:Diagnostic testing facilities require aspirating smoke detection integrated with EPA-mandated ventilation monitoring for chemical fume containment. Germany's REACH substance restrictions on pipe materials create compliance complexity for laboratory deployments.
- Research Institutions:University and government laboratories prioritize sensitivity optimization over cost in grant-funded infrastructure projects.
- Diagnostic Centers:Imaging and outpatient testing facilities represent a price-sensitive segment where point-source sensor substitution threatens aspirating penetration.
Hospitals command the largest installed base, though Clinical Labs are expanding most quickly as laboratory containment convergence creates dual-revenue opportunities.
Application:
Performance requirements and regulatory oversight intensity diverge across life-critical versus environmental monitoring use cases, shaping certification pathway selection.
- Emergency Services:Rapid deployment scenarios prioritize reliability and portability over sensitivity thresholds. Fire departments in the United States specify NFPA-compliant portable units for hazardous materials response and mass casualty incidents.
- Surgical Procedures:Operating room suction and smoke evacuation demands continuous negative pressure with fail-safe redundancy. Stryker Corporation bundles aspirating systems with surgical suite equipment packages to capture integrated specification.
- Laboratory Analysis:Research and quality control applications require chemical compatibility and particulate discrimination capabilities.
- Environmental Monitoring:Cleanroom and containment facility applications integrate aspirating detection with building management platforms for real-time airflow analytics.
Surgical Procedures holds the revenue concentration, while Environmental Monitoring is gaining share fastest as predictive maintenance algorithms reduce downtime costs.
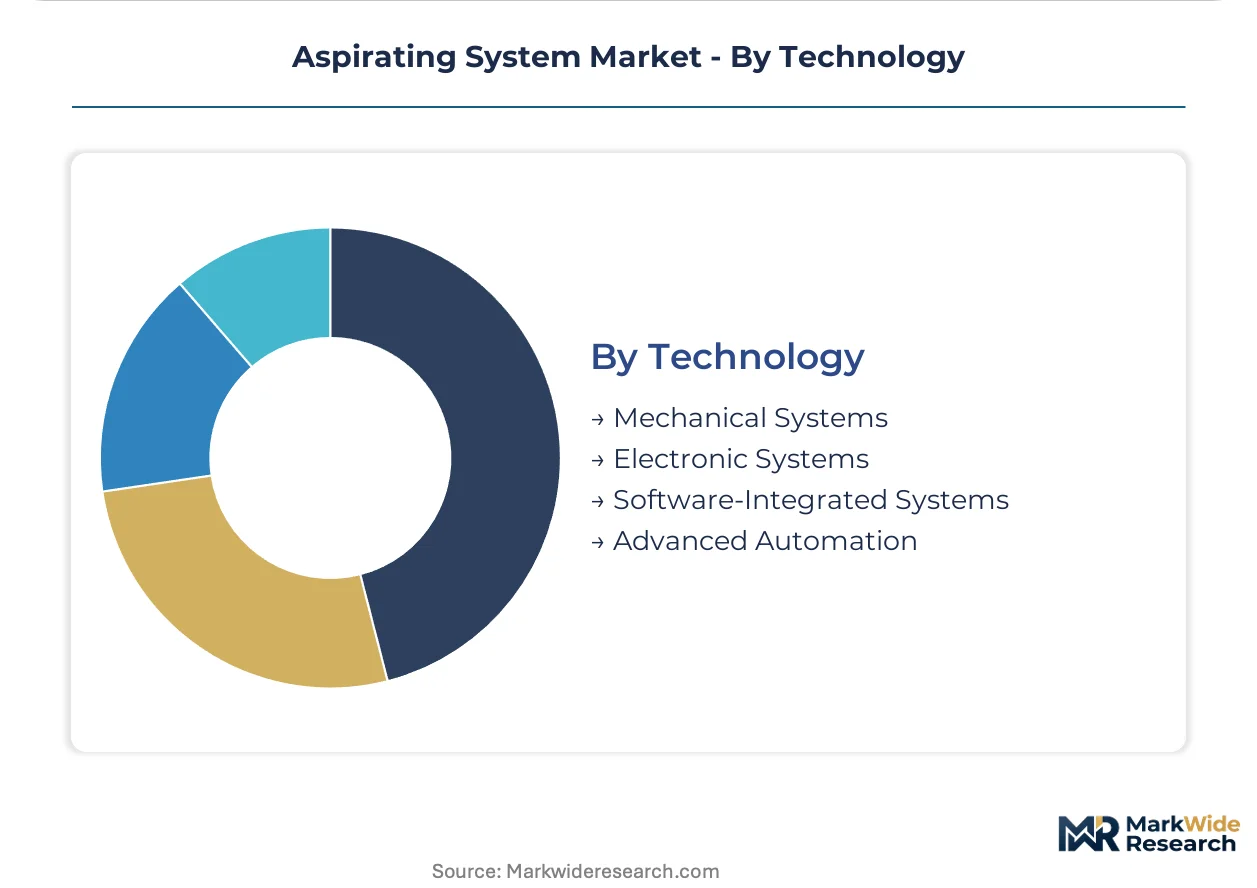
Technology:
Software integration and cybersecurity review layers are extending approval timelines and shifting competitive advantage toward vendors with regulatory navigation capabilities.
- Mechanical Systems:Pneumatic and electromechanical suction without digital control interfaces face commoditization pressure but retain share in cost-constrained diagnostic centers. These systems avoid FDA and FCC review timelines that lag electronic platform approvals.
- Electronic Systems:Microprocessor-controlled units with digital pressure sensing and alarm integration dominate mid-tier hospital installations. Honeywell International Inc. leverages commercial building fire safety channel relationships to specify electronic aspirating detection.
- Software-Integrated Systems:Building management platform connectivity with predictive filter-replacement alerts and real-time airflow analytics represents the steepest expansion trajectory. Siemens AG anchors European project pipelines through direct infrastructure contractor relationships.
- Advanced Automation:Multi-channel infrared laser detection with particulate discrimination capabilities miniaturizes form factors for retrofit applications.
Electronic Systems maintains the largest installed base, though Software-Integrated Systems is climbing the fastest as cybersecurity certification layers reshape vendor selection criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of surgical suction devices anchors the United States as the dominant geography, while EN 54-20 certification mandates and healthcare infrastructure renewal programs drive parallel expansion across Germany and Japan.
United States
Joint Commission accreditation pressure forces hospital infrastructure upgrades toward aspirating networks, particularly in surgical suites and intensive care wards. NFPA 72 Chapter 17 mandates enhanced smoke detection sensitivity in healthcare occupancies, accelerating replacement of legacy point-source detection. Medical center purchasing consortia in Texas and California are unbundling aspirating specification from general fire safety contracts to extract volume discounts.
Germany
Hyperscale computing facilities in Frankfurt and Munich are installing fixed aspirating systems to achieve sub-fire suppression thresholds and protect server uptime. REACH substance restrictions on halogenated flame retardants force pipe material reformulation, with project specifications now requiring full chemical composition documentation prior to bid submission. The Rhine-Ruhr corridor experiences acute certified technician scarcity, extending centralized system project timelines.
Japan
METI industrial safety directives and JIS standards mandate rapid-deployment redundancy for municipal fire departments and ambulance services. Multi-channel infrared laser detection with particulate discrimination capabilities is penetrating hospital surgical suites and pharmaceutical cleanrooms at twice the pace of standard configurations. The Kanto region around Tokyo anchors demand for miniaturized wall-mounted detection units.
India
Government hospital modernization programs under the National Health Mission create first-mover advantage for vendors establishing local service networks. BIS certification requirements for medical electrical equipment create compliance complexity for imported aspirating hardware. Maharashtra and Karnataka are experiencing concentrated demand as private hospital chains expand tertiary care capacity.
United Kingdom
NHS estate renewal programs are driving replacement of aging fire safety infrastructure in acute care facilities. Building Regulations Part B and BS 5839 standards mandate aspirating smoke detection in certain healthcare and data center applications. The Greater London area concentrates procurement activity as hospital trusts consolidate capital planning through regional purchasing hubs.
Aspirating System Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the aspirating system market. The upper tier comprises diversified industrial conglomerates with hospital equipment integration expertise and commercial building fire safety channel dominance. The specialist tier includes pure-play medical device manufacturers and regional fire safety equipment vendors. Three strategic archetypes define competitive positioning: surgical suite integrators bundling aspirating systems with operating room equipment, commercial building safety specialists leveraging distributor relationships, and infrastructure project anchors cultivating direct contractor ties. Dominant competitive moves include backward integration into pipe network materials and geographic expansion through local service network establishment.
Within the surgical suite integrator tier, Stryker Corporation exemplifies equipment bundling strategies that capture integrated specification authority. Honeywell International Inc. anchors the commercial building safety vector, occupying a position where fire safety channel relationships determine specification outcomes. Siemens AG represents the infrastructure project archetype, sitting within European contractor ecosystems through direct regulatory consultant engagement. These three entities collectively illustrate how vertical integration depth, channel control, and project pipeline access segment competitive advantage across distinct end-use environments.
| Leading Market Players |
|---|
| Stryker Corporation |
| Penumbra Inc. |
| Honeywell International Inc. |
| Johnson Controls |
| Teleflex Incorporated |
| Siemens AG |
| Boston Scientific Corporation |
| Bosch Security Systems |
| Medtronic Plc |
| Others |
Value Chain & Pricing Dynamics
Six-to-twelve-month lead times for EN 54-20 certified installation specialists in Western Europe concentrate pricing power with incumbent service networks while compressing margins on fixed-installation contracts with locked pricing. This scarcity dynamic elevates aftermarket service attach rates above hardware margins and reshapes procurement negotiations toward long-term maintenance bundling.
Pricing Analysis
German project specifications command 15-25% premiums over United States equivalents for centralized aspirating systems due to REACH-compliant pipe material documentation requirements and certified technician scarcity. Three-tier pricing structure across premium software-integrated, standard electronic, and economy mechanical levels stratifies by cybersecurity certification depth and predictive analytics capability. Cost compression in the mechanical tier intensifies because point-source photoelectric detectors threaten substitution in sub-five-thousand-square-meter commercial buildings. Diagnostic centers and outpatient imaging facilities exhibit highest price sensitivity, while data center operators prioritize uptime protection over capital expenditure minimization.
Supply Chain Analysis
Germany and Japan anchor precision detection unit manufacturing, while China dominates polymer pipe extrusion and copper conductor processing for network infrastructure. Raw material dependencies center on halogen-free flame-retardant compounds, medical-grade silicone tubing, and infrared laser diode arrays. Single-source vulnerability concentrates in specialized polymer formulations meeting REACH substance restrictions, where qualified alternative suppliers require twelve-month validation cycles. Distribution runs through fire safety equipment distributors in North America, direct infrastructure contractor relationships in Europe, and hospital procurement consortia extracting volume discounts through centralized capital planning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive filter-replacement analytics and real-time airflow monitoring subscriptions expand service revenue pools faster than hardware shipments, repositioning vendor economics toward recurring-revenue capture. Software-integrated platforms with building management connectivity now determine competitive viability.
For Market Incumbents: Consolidate service network density in certified technician-scarce regions to defend against project timeline erosion and capture maintenance bundling premiums. Backward integration into REACH-compliant polymer pipe production reduces material cost volatility exposure. Lock in data center operator relationships through hyperscale computing facility expansion in Frankfurt and Munich before competitor infrastructure project anchors establish contractor ties. For New Entrants and Emerging Players: Anchor in India's National Health Mission hospital modernization programs, where government infrastructure spending outpaces established vendor service network coverage. Municipal fire departments in Maharashtra and Karnataka represent the most penetrable entry segment given BIS certification complexity barriers for imported hardware. Pursue direct-to-contractor digital specification platforms to bypass traditional fire safety distributor markups and accelerate specification capture. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming medical device divisions holding dormant hospital equipment integration capabilities. Five-to-ten-year viability hinges on cybersecurity certification navigation capacity as FDA and FCC review layers extend software-integrated platform approval timelines. Monitor divergence between mechanical and electronic system certification timelines as the inflection signal for vendor selection criteria shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker Corporation leverages surgical suite bundling to capture integrated specification authority from clinical departments. |
| CE Marking Pathway | EN 54-20 certification mandates filter uncertified equipment from European project pipelines, anchoring vendor selection. |
| Software Companion Development | Predictive maintenance algorithms embedded in building management platforms reduce downtime costs and accelerate hardware replacement. |
| Backward Integration | Captive supply of REACH-compliant polymer compounds insulates margins from halogenated flame retardant restriction compliance costs. |
| Geographic Expansion | Local service network establishment in India creates first-mover advantage under National Health Mission infrastructure programs. |
Study Parameters
Operator-level perspectives from hospital biomedical engineers, fire safety system contractors, GPO contracts managers, and infrastructure project developers anchored the qualitative base. Primary interviews combined with secondary validation against NFPA 72 regulatory filings, EN 54-20 certification databases, hospital procurement records, and hyperscale facility capex disclosures. Bottom-up installation volume estimates triangulated against top-down healthcare infrastructure spending analysis.
Sensitivity analysis tested forecast robustness across technician availability scenarios, copper and polymer price volatility bands, and point-source sensor substitution penetration rates. Segmentation dimensions spanned product type, end user, application, and technology integration level across the projection horizon. CAGRs derived from weighted average of historical replacement cycle analysis and regulatory mandate acceleration effects, with data center thermal density thresholds and surgical suite renovation backlogs as key demand inputs.
Underlying assumptions cover NFPA 72 Chapter 17 enforcement consistency, REACH substance restriction stability, and hyperscale computing facility expansion continuity, with deviation risk concentrated in certified technician pipeline shortages and cybersecurity certification timeline extensions. Recalibration cycles align with material shifts in healthcare infrastructure renewal program funding and fire safety code amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Epinephrine Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
US Anesthesiology Service Market
Anesthesiology
Anesthetics Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Airway Catheters Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Artificial Coma/Medically Induced Coma Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Dental Anesthesia Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market
Anesthesiology
Anaesthesia Machines Market