
 Knife Sterilizer Market | 2026-2036
Knife Sterilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Knife Sterilizer Market Outlook
Stainless steel is decoupling from lower-grade alloys in knife sterilizer chassis construction as manufacturers chase corrosion resistance and thermal cycling durability. Philips leverages its healthcare lighting heritage to dominate UV-C source integration for commercial units. Hobart sustains its position in North American foodservice through captive distribution networks and in-house production of wash-rinse-sanitize systems. Xiaomi anchors the residential segment with compact, app-connected sterilizer designs priced for Asian apartment kitchens.
A knife sterilizer is a dedicated sanitization appliance that exposes cutting blades to ultraviolet radiation, elevated thermal cycles, or chemical vapor at specified intensities and durations to achieve log-reduction of microbial contamination. Its primary commercial purpose is to eliminate cross-contamination risk in food preparation and surgical environments where blade reuse is mandatory. Ultraviolet product types now command the largest installed base among food production end users due to mercury-free LED source maturation and reduced cycle times. Chemical vapor variants retain margin concentration in hospital sterilization departments where sporicidal claims are non-negotiable. Contact-based technology competes for share in compact residential units where electrolytic approaches face consumer skepticism about residual chemistry.
FDA food code provisions in the United States mandate blade sanitation between raw and ready-to-eat food contact, directly expanding commercial kitchen procurement of validated sterilizer units. EFSA guidance across Europe harmonizes hygiene requirements for catering equipment, creating a unified compliance target for manufacturers serving multiple member states. China's SAMR enforces GB standards for electrical appliances in food contact, shaping export certification burdens for foreign suppliers. Stakeholders must monitor whether electrolytic technology achieves regulatory equivalence with thermal and UV modalities in hospital accreditation frameworks.
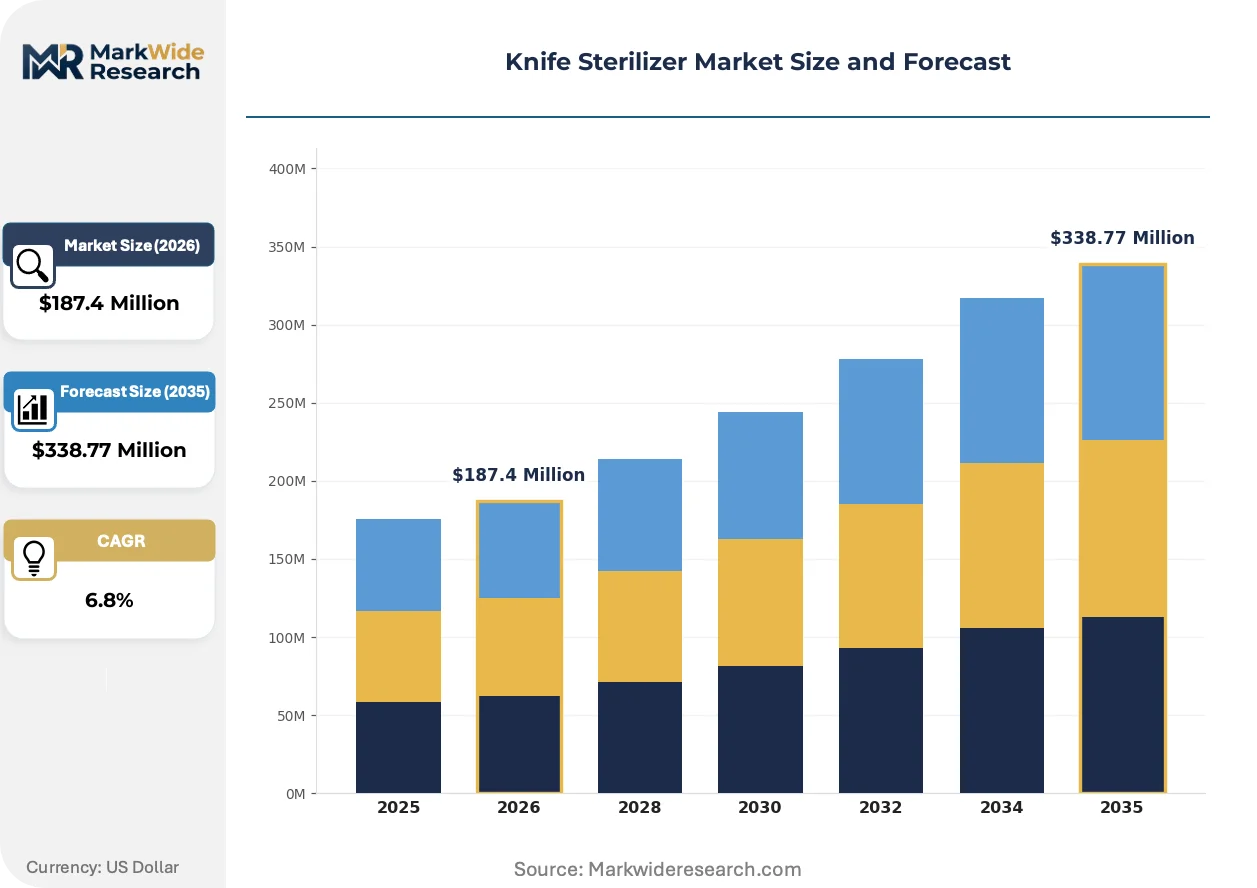
Market Dynamics
UV-C LED source maturation is compressing sterilization cycle times while mercury-free designs unlock regulatory compliance in foodservice chains, forcing incumbents to retool chassis thermal management around solid-state emitter arrays.
Growth Catalysts
- FDA Food Code blade sanitation mandates:Full-service restaurant chains in the United States must validate blade sanitation between raw and ready-to-eat contact, expanding procurement of third-party certified units.
- Solingen equipment cluster concentration:Germany's cutlery manufacturing hub generates localized demand for industrial-scale sterilizers integrated into production finishing lines.
- Electrolytic chemistry advancement:Compact residential units now achieve log-reduction claims without thermal cycling, penetrating Asian apartment kitchens where space constraints dominate.
Market Restraints
- UV-C LED input cost volatility:Sapphire substrate and epitaxial wafer supply concentrates among East Asian foundries, squeezing margins for chassis integrators.
- Sporicidal validation gaps:Electrolytic and contact-based modalities lack equivalent hospital accreditation framework acceptance versus thermal and chemical vapor systems.
- Substitution by single-use blades:Low-cost disposable cutting tools in casual dining segments erode sterilizer attachment rates in price-sensitive channels.
Strategic Opportunities
- Underpenetrated cloud kitchen infrastructure:Ghost kitchen operators in India lack standardized blade sanitation protocols, creating first-mover positioning for validated compact units.
- EU Green Deal circularity incentives:Reusable blade certification programs subsidize sterilizer procurement in European institutional catering contracts.
- Convergence of IoT telemetry and UV dosage monitoring:Real-time emitter degradation tracking enables predictive maintenance contracts in high-throughput food processing.
Industry Challenges
- Multiphysics simulation talent scarcity:Thermal-fluids-optical modeling for LED array placement exceeds capabilities of traditional appliance engineering teams.
- Legacy wash-rinse-sanitize system integration:Hobart and similar incumbents control captive distribution, complicating standalone sterilizer placement in existing kitchen workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knife Sterilizer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultraviolet, Chemical, Thermal, Plasma Application: Catering, Healthcare, Residential, Industrial Technology: Radiant Energy, Contact-Based, Chemical Vapor, Electrolytic End User: Restaurants, Hospitals, Homes, Food Production |
| Companies Covered | Philips, Xiaomi, Haier, Panasonic, Midea, Electrolux, Hobart, JBT Corporation, Steri-Techno Fab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knife Sterilizer Market Strategic Shifts
Mercury-free solid-state sterilization is displacing legacy lamp technologies while regulatory pressure on food contact surfaces intensifies validation requirements across commercial kitchen procurement.
Far-UVC emitter arrays operating at 222 nanometers are integrating into commercial chassis designs for occupied-space operation without photobiological safety enclosures. Full-service restaurant chains in North America pilot these systems for continuous blade sanitation during service hours. This wavelength selection is integrating real-time sterilization into workflow designs previously requiring batch cycling.
EFSA guidance harmonization across European member states compresses certification fragmentation for equipment manufacturers serving cross-border catering operators. The unified compliance target reduces redundant testing burdens but elevates baseline hygiene validation standards. Central kitchen operators in Germany, France, and Italy consolidate procurement specifications around this framework.
Equipment-as-a-service financing is displacing capital purchase models in North American foodservice chains facing balance sheet constraints. Sterilizer vendors retain ownership and bundle validation testing, emitter replacement, and compliance documentation into per-cycle fees. This model concentrates most visibly in franchise systems where individual operators lack technical staffing depth.
Knife Sterilizer Market Segmentation
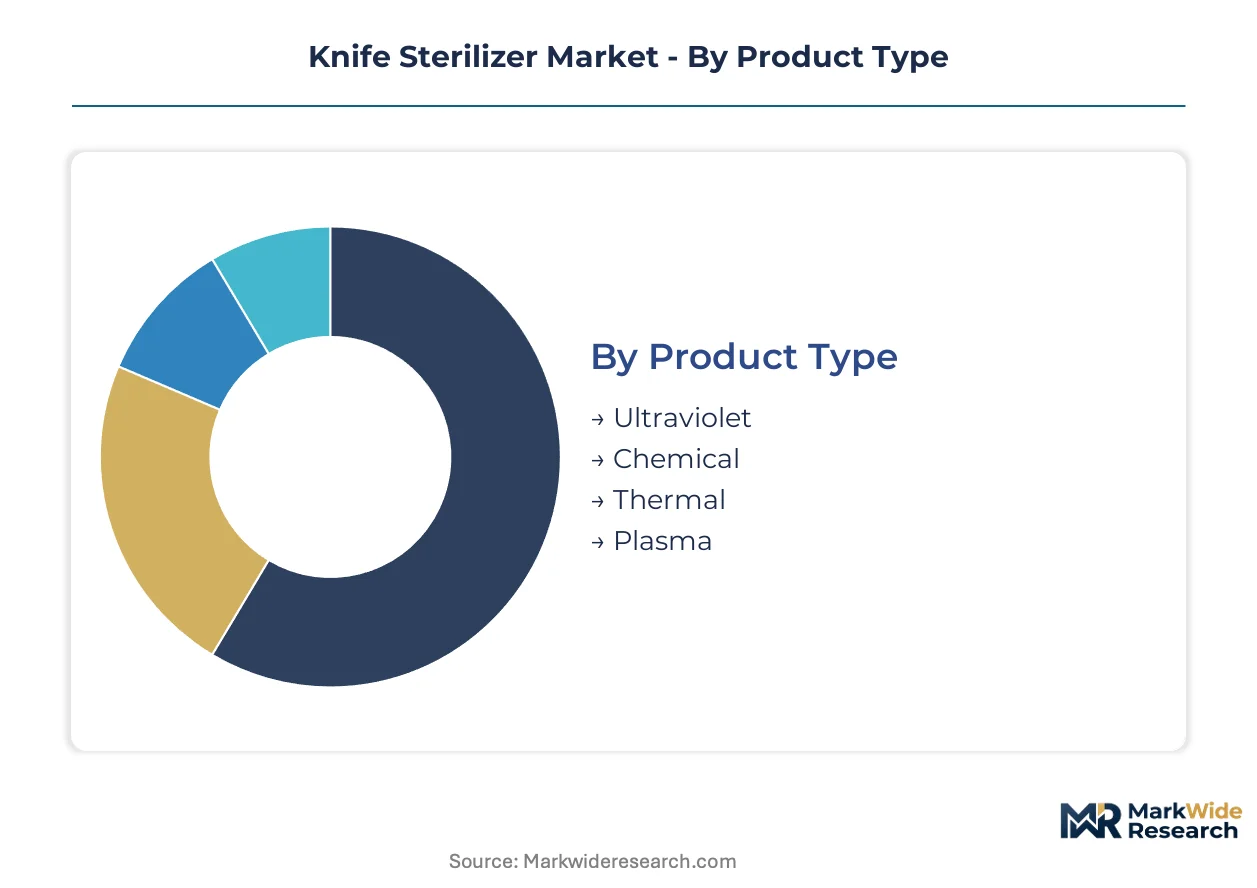
Knife sterilizer procurement patterns diverge sharply across sterilization modality, end-use environment, and operational scale. Segment-specific engineering requirements drive chassis design, validation protocols, and distribution channel selection.
Product Type:
Capital intensity varies most dramatically across sterilization source technologies, with emitter subsystem costs dominating bill-of-materials structures.
- Ultraviolet:Solid-state UV-C LED arrays now displace mercury vapor lamps in commercial chassis designs, reducing thermal management overhead while enabling continuous-duty operation in occupied kitchen spaces. Full-service restaurant chains in the United States specify these units for FDA Food Code compliance between raw and ready-to-eat contact cycles.
- Chemical:Vapor-phase sterilants using hydrogen peroxide or peracetic acid achieve sporicidal validation thresholds mandatory for surgical instrument reprocessing in hospital central sterile supply departments. Equipment costs concentrate in vapor containment and aeration subsystems.
- Thermal:Dry-heat or steam-based systems leverage existing kitchen infrastructure but require extended cycle times limiting throughput in high-volume catering operations.
- Plasma:Low-temperature hydrogen peroxide plasma penetrates complex blade geometries for specialty surgical applications where thermal degradation risks exclude other modalities.
Ultraviolet systems absorb the bulk of installed capacity; chemical configurations are expanding most quickly in healthcare accreditation frameworks.
Application:
Volume concentration tracks foodservice labor intensity and regulatory inspection frequency across operational environments.
- Catering:Institutional feeding contracts in Germany, France, and Italy consolidate procurement around EFSA-harmonized validation standards, with central kitchen operators demanding integrated wash-rinse-sanitize-sterilize workflows.
- Healthcare:Operating suites and sterile processing departments enforce blade-level log-reduction documentation for joint commission accreditation, with chemical vapor and plasma modalities dominating capital budgets.
- Residential:Compact countertop units with electrolytic or UV-C LED sources penetrate Asian apartment kitchens where space constraints and single-person households reshape appliance form factors.
- Industrial:Continuous-line sterilizers integrate into cutlery manufacturing finishing operations in Solingen, Germany, where blade output volumes justify dedicated capital equipment.
Catering applications command the greatest aggregate unit shipments; residential configurations are climbing the fastest as Asian urbanization accelerates.
Technology:
Margin structures correlate with intellectual property concentration in emitter source and process control subsystems.
- Radiant Energy:UV-C and far-UVC wavelengths dominate commercial foodservice specifications, with 222-nanometer emitter arrays enabling occupied-space operation without photobiological safety enclosures previously mandatory for 254-nanometer sources.
- Contact-Based:Electrolytic approaches generate reactive oxygen species through water electrolysis, achieving microbial reduction without consumable chemistry in compact residential units where consumer skepticism about residual compounds constrains adoption.
- Chemical Vapor:Sporicidal claims validated against Geobacillus stearothermophilus biological indicators retain margin concentration in hospital sterilization departments where accreditation frameworks demand documented kill kinetics.
- Electrolytic:Advances in electrode materials and power electronics enable log-reduction performance previously restricted to thermal or radiant modalities, penetrating price-sensitive residential channels in China and India.
Radiant energy technologies retain the largest installed base; electrolytic systems are gaining share fastest in residential penetration efforts.
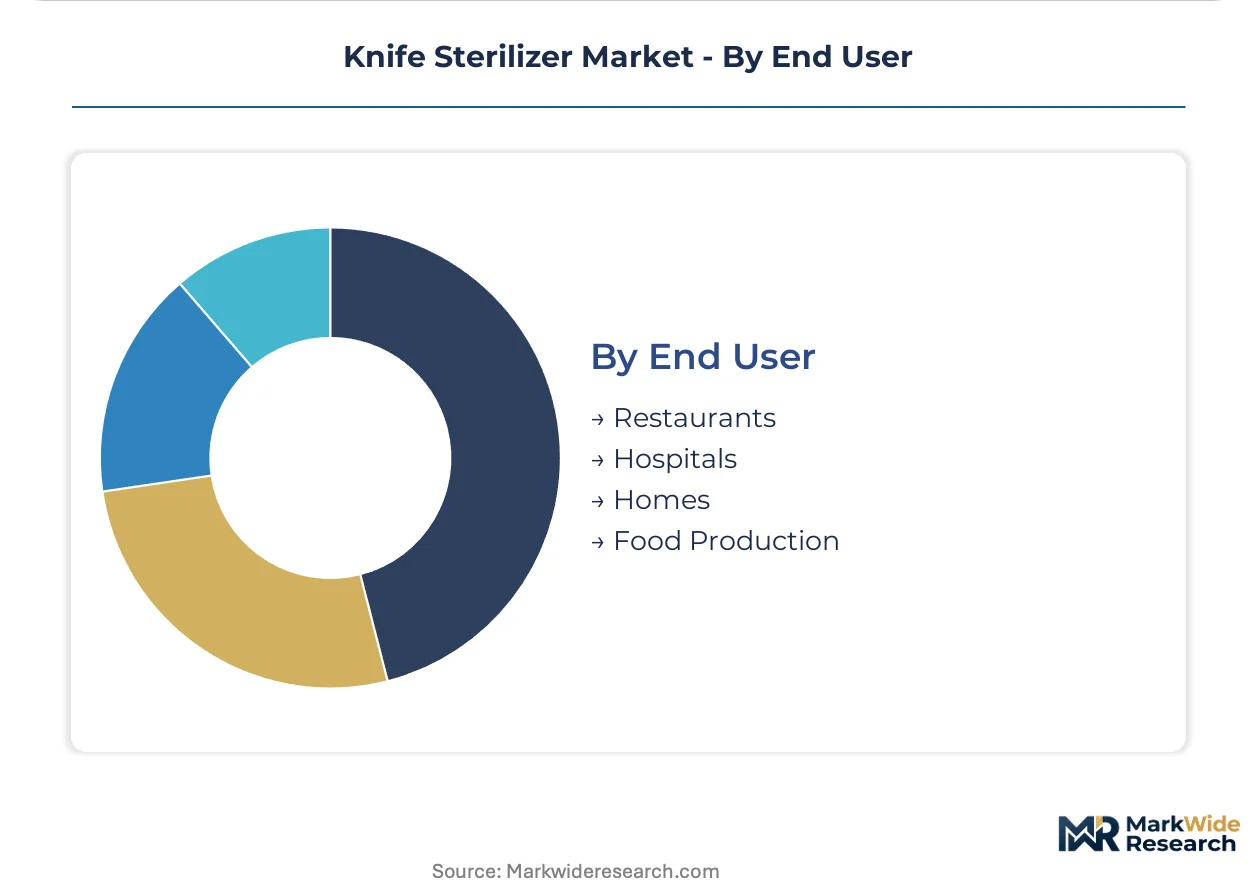
End User:
Procurement authority and technical staffing depth determine equipment specification complexity and service contract attachment rates.
- Restaurants:Full-service chains in the United States face FDA Food Code blade sanitation mandates between raw protein and ready-to-eat preparation, driving third-party certified unit procurement with validation documentation for health department inspections.
- Hospitals:Central sterile supply departments and operating room suites enforce sporicidal performance standards with chemical vapor or plasma modalities, bundling equipment-as-a-service contracts covering maintenance and revalidation testing.
- Homes:Individual consumers prioritize countertop footprint and app connectivity over cycle time or log-reduction documentation, with Asian markets showing highest category penetration.
- Food Production:Cutlery manufacturers and protein processing facilities integrate sterilizers into HACCP-critical control points, with throughput requirements favoring continuous-duty radiant energy configurations.
Restaurant end users represent the largest addressable equipment volume; home installations follow the steepest expansion trajectory as compact electrolytic designs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Full-service restaurant chains in the United States drive the largest commercial procurement volumes, while Germany's Solingen cluster anchors industrial-scale sterilizer integration for cutlery manufacturing operations.
United States
FDA Food Code blade sanitation mandates between raw and ready-to-eat food contact expand third-party certified unit procurement across full-service restaurant chains. Health department inspection protocols require validation documentation for commercial kitchen operators. Texas and California metro areas concentrate ghost kitchen infrastructure where standardized blade sanitation protocols remain underpenetrated.
Germany
EFSA-harmonized hygiene requirements unify compliance targets for equipment manufacturers serving cross-border catering operators. The EU Green Deal circularity incentives subsidize sterilizer procurement in institutional catering contracts. Solingen's cutlery manufacturing hub generates localized demand for industrial-scale sterilizers integrated into production finishing lines.
China
SAMR enforcement of GB standards for electrical appliances in food contact shapes export certification burdens for domestic and foreign suppliers. Compact residential units with electrolytic or UV-C LED sources penetrate urban apartment kitchens where space constraints dominate appliance selection. Yangtze River Delta manufacturing clusters supply emitter subsystems to chassis integrators worldwide.
India
FSSAI hygiene mandates for commercial food preparation expand equipment validation requirements across institutional catering and restaurant segments. Cloud kitchen operators in Mumbai and Bangalore lack standardized blade sanitation protocols, creating first-mover positioning for validated compact units. Maharashtra and Karnataka industrial corridors host emerging domestic sterilizer assembly operations.
Japan
METI efficiency standards for commercial kitchen equipment shape sterilizer thermal management and power consumption specifications. Compact countertop designs with app connectivity penetrate single-person households in Tokyo and Osaka metro areas. Kansai region precision manufacturing capabilities support high-reliability emitter subsystem production for domestic and export markets.
Knife Sterilizer Market Competitive Environment
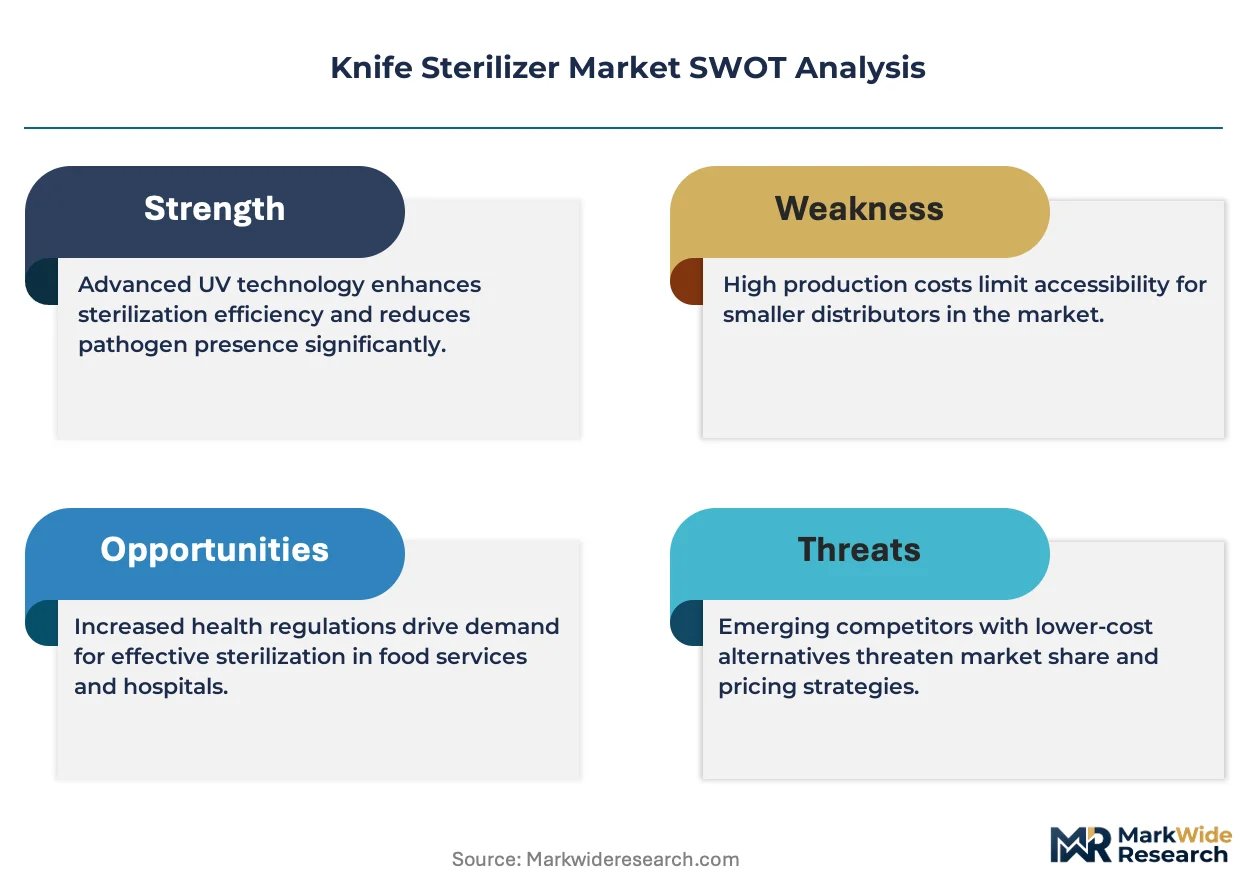
Branded specialists and contract manufacturers split share differently across segments, with healthcare-oriented lighting companies and diversified appliance conglomerates controlling distinct technology vectors. The market structure concentrates UV-C source integration among healthcare heritage players while Asian electronics conglomerates dominate residential compact segments. Three archetypes prevail: healthcare lighting specialists, diversified appliance multinationals, and commercial foodservice equipment incumbents. Competitive moves center on captive distribution network expansion and emitter subsystem backward integration.
Among healthcare heritage lighting companies, Philips occupies a position exemplifying UV-C source integration for commercial units. Xiaomi and Haier represent the diversified appliance archetype anchoring residential segment penetration with compact, connected designs. Hobart sits within the commercial foodservice equipment tier, sustaining positioning through captive distribution networks and in-house production of integrated wash-rinse-sanitize systems.
| Leading Market Players |
|---|
| Philips |
| Xiaomi |
| Haier |
| Panasonic |
| Midea |
| Electrolux |
| Hobart |
| JBT Corporation |
| Steri-Techno Fab |
| Others |
Value Chain & Pricing Dynamics
Captive distribution networks anchor both supply positioning and pricing power for commercial foodservice equipment incumbents. Hobart's in-house production of wash-rinse-sanitize systems locks out standalone sterilizer vendors from existing kitchen workflows, forcing new entrants to absorb channel access premiums or accept margin compression through third-party dealer markups.
Pricing Analysis
Volume concentration in full-service restaurant chains splits sharply from margin capture in hospital sterilization departments. Equipment-as-a-service financing bundles validation testing and emitter replacement into per-cycle fees for franchise operators lacking technical staffing. FDA Food Code compliance documentation commands premium pricing tiers against standard commercial units. Ghost kitchen operators in price-sensitive channels exhibit highest price elasticity, while hospital central sterile supply departments prioritize sporicidal validation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from chassis integrators mandate multi-supplier qualification for UV-C LED emitters and sapphire substrates. East Asian foundries in Taiwan, South Korea, and China dominate epitaxial wafer production. Supply chains draw from hydrogen peroxide vapor containment specialists in Germany and precision machining clusters in Japan. Single-source vulnerability concentrates in mercury-free LED substrate supply. Distribution runs through captive dealer networks for commercial foodservice and GPO contracts for healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Food Code blade sanitation mandates create a cost-of-compliance moat that rewards validated incumbents while screening out uncertified competitors. EFSA harmonization extends this barrier across European procurement consolidation.
For Market Incumbents: Hedge against electrolytic technology advancement by accelerating backward integration into UV-C LED emitter production. Lock in Solingen cutlery manufacturers through exclusive industrial sterilizer supply agreements before domestic Chinese competitors achieve CE marking equivalence. Prioritize certification investment for far-UVC 222-nanometer occupied-space operation to preempt regulatory shifts away from batch cycling requirements. For New Entrants and Emerging Players: Cloud kitchen operators in Indian metro corridors represent the most penetrable buyer archetype lacking standardized blade sanitation protocols. Target compact electrolytic designs for Asian apartment kitchens where Xiaomi's app-connected positioning leaves service gaps. Pursue equipment-as-a-service financing partnerships with franchise systems to bypass Hobart's captive distribution control. For Investors and Strategic Acquirers: Exit pathways concentrate in healthcare heritage lighting companies with UV-C source integration capabilities. Five-to-ten year viability hinges on regulatory equivalence achievement for electrolytic modalities in hospital accreditation frameworks. Monitor FDA guidance updates on far-UVC photobiological safety thresholds as inflection indicator for continuous-duty sterilizer demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| UV-C LED Backward Integration | Philips leverages healthcare lighting heritage to secure emitter supply against East Asian foundry concentration. |
| Far-UVC 222nm Regulatory Submission | FDA photobiological safety clearance enables occupied-space operation without batch cycling enclosures. |
| Equipment-as-a-Service Financing Launch | Franchise systems in North America adopt per-cycle fee structures to bypass capital purchase constraints. |
| Cloud Kitchen Pilot Deployment | Mumbai and Bangalore operators establish first-mover positioning in underpenetrated blade sanitation protocols. |
| EFSA Harmonization Certification | Central kitchen operators in Germany, France, and Italy consolidate procurement around unified compliance targets. |
Study Parameters
Trade association filings, customs export records, and hospital procurement databases formed the secondary backbone. Primary interviews with commercial kitchen equipment procurement managers, biomedical engineers in sterile processing departments, and regulatory affairs specialists at emitter subsystem manufacturers validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down equipment spending allocations across foodservice and healthcare capital budgets.
Historical trendline analysis mapped UV-C LED cost curves and sterilization cycle time compression against mercury vapor lamp displacement rates. Segmentation modeling captured product type, application environment, technology modality, and end-user procurement authority across the projection horizon. CAGR derivation weighted FDA Food Code enforcement intensity, EFSA guidance adoption velocity, and SAMR GB standard export certification burdens.
Revisions become necessary when far-UVC photobiological safety thresholds shift, electrolytic technology achieves hospital accreditation equivalence, or single-use blade substitution accelerates in casual dining channels. Deviation in East Asian foundry supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Finger Splint Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
Freeze Drying Masks Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Contrast Media Consumables Market