
 Global Dental Bone Void Filler Market | 2026-2036
Global Dental Bone Void Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Bone Void Filler Market Intelligence
The migration of clinical procedures toward ready-to-use synthetic putties from complex-to-handle xenograft blocks is reconfiguring the value chain for dental surgeons. Geistlich Pharma dominates the premium xenograft and allograft segments with its established clinical evidence base. Dentsply Sirona leverages its extensive distribution network to promote a broad portfolio of both natural and synthetic options. Meanwhile, Stryker competes through its focus on orthopedic and maxillofacial applications, extending its reach into dental surgery.
A dental bone void filler is a biocompatible material used to fill bony defects in the jaw or alveolar ridge. Characterized by specific porosity and resorption rates, it acts as a scaffold for new bone formation, a process called osteoconduction. While xenografts command a large share, synthetic bone substitutes are expanding rapidly due to their safety and supply consistency. Granules remain a standard delivery form, but putty formulations are gaining preference in implant dentistry applications for their ease of use.
Market access hinges on stringent regulatory approvals, such as those from the US FDA's 510(k) pathway and the EU's Medical Device Regulation (MDR). Compliance with ISO 13485 for quality management systems is a baseline requirement for manufacturers seeking to operate across multiple jurisdictions like Japan and Canada. Navigating the evolving clinical data requirements for novel composite grafts will be critical for securing premium reimbursement.
Market Dynamics
The central dynamic shaping the dental bone void filler market is the procedural shift toward user-friendly synthetic putties, which simplifies surgical workflows. This move away from technically demanding xenograft block preparation is lowering barriers for general practitioners to perform more complex implant cases.
Growth Catalysts
- Synthetic Material Innovation:Advances in bioactive glass and biphasic calcium phosphate formulations are delivering improved osteoconductive and resorption profiles, accelerating their adoption over natural-origin grafts in routine dental procedures.
- Expanding Implant Dentistry:A rising volume of dental implant procedures, particularly in countries like Germany and South Korea with aging populations and high standards of dental care, directly fuels consumption of bone void fillers.
- Government Healthcare Initiatives:Favorable policies in China, aimed at improving public access to advanced dental treatments through state-funded programs, are unlocking significant demand for both synthetic and xenograft materials.
Market Restraints
- Reimbursement Hurdles:Securing premium reimbursement for novel composite or synthetic grafts is challenging, as payers often require extensive long-term clinical data to justify costs over established, lower-priced alternatives.
- High Cost of Biologics:The premium pricing of allografts and xenografts, stemming from complex sourcing and processing, restricts their use in price-sensitive healthcare systems and for non-essential aesthetic procedures.
- Regulatory Scrutiny:Stringent clinical evidence requirements under frameworks like the US FDA's 510(k) pathway and the EU's MDR create high barriers to entry and extend development timelines for new materials.
Strategic Opportunities
- Patient-Specific Implants:The convergence of 3D printing technology with resorbable biomaterials creates an opportunity for custom-fabricated scaffolds that match the precise anatomy of a patient's bony defect, improving surgical outcomes.
- Emerging Market Penetration:Untapped demand exists in Latin American markets such as Brazil and Mexico, where a growing middle class and expanding dental tourism are creating new avenues for growth.
- Maxillofacial and Cranial Applications:Extending the application of dental-grade bone fillers into adjacent surgical fields like cranio-maxillofacial trauma and reconstructive surgery offers a significant avenue for market expansion.
Industry Challenges
- Specialized Clinician Training:The effective use of new injectable and putty formulations requires specific handling techniques, creating a need for manufacturers to invest heavily in surgeon education and training programs.
- Sterilization and Logistics:Maintaining the sterility and, for some allografts, the cold chain integrity from manufacturing to the point of use presents significant logistical complexity and cost for suppliers.
- Clinical Data Generation:Conducting long-term clinical trials to prove the non-inferiority or superiority of new synthetic materials against the gold standard of autografts is a costly and time-consuming process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Bone Void Filler Market |
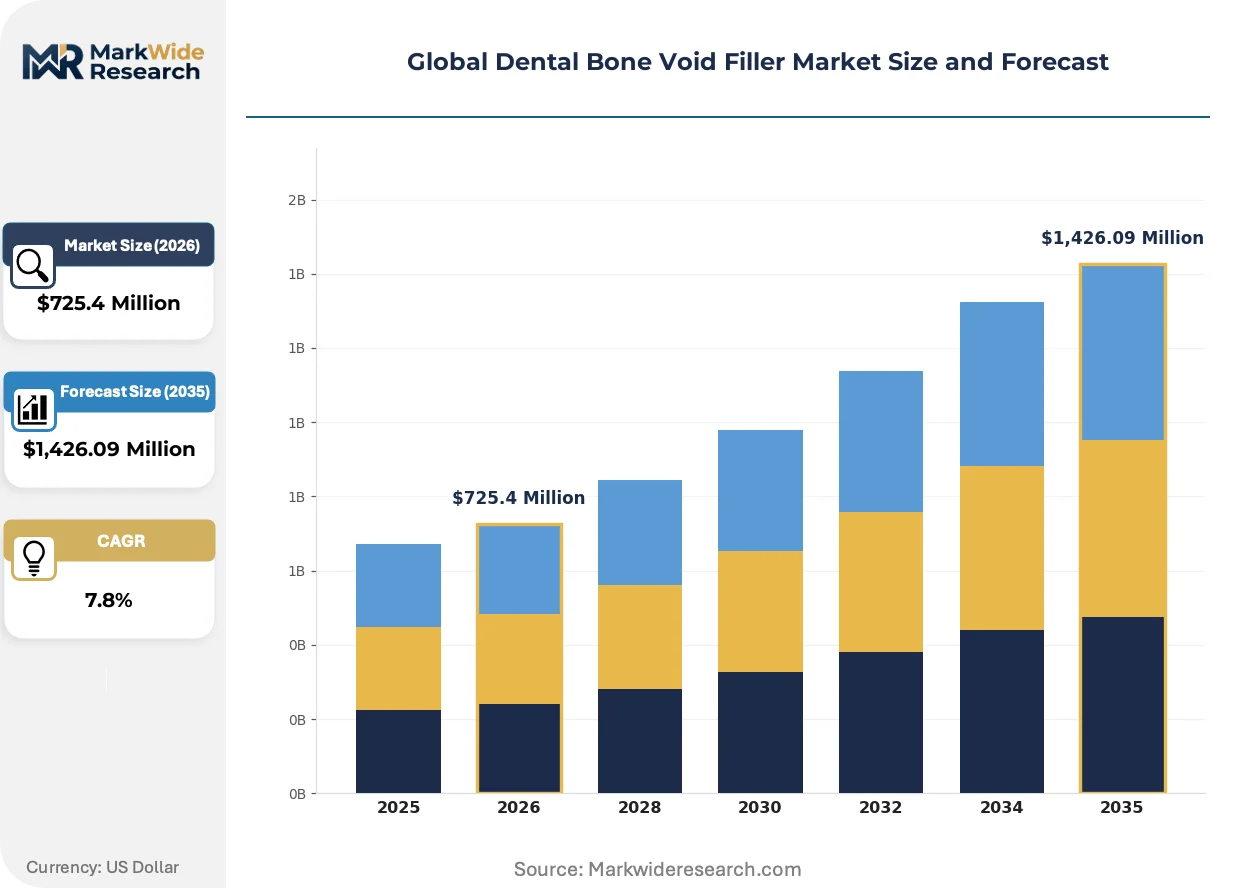
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,426.09 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autograft, Allograft, Xenograft, Synthetic Bone Substitutes, Composite Grafts Application: Periodontal Regeneration, Oral & Maxillofacial Surgery, Implant Dentistry, Ridge Augmentation, Alveolar Ridge Preservation End User: Dental Clinics, Oral Surgery Centers, Specialty Dental Hospitals, Outpatient Care Centers, Academic Research Institutes Delivery Form: Granules, Putty, Chips, Paste, Block Grafts |
| Companies Covered | Medtronic, ZimVie, Curasan Inc, Stryker, Dentsply Sirona, Graftys, Olympus Terumo Biomaterials, Geistlich Pharma, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Bone Void Filler Market Strategic Shifts & Innovations
Material science advancements are enabling the creation of bone void fillers with tailored handling properties and predictable resorption rates. This evolution allows products to be matched more precisely to specific clinical indications, from simple socket preservation to complex ridge augmentations.
Ready-to-use synthetic putties, which combine a bioactive ceramic or polymer with a resorbable carrier, provide superior handling and placement control. Implantologists and general dental surgeons are adopting these formulations for their efficiency in the operating room. This material evolution is collapsing the preparation time and technical skill required for grafting procedures, making them more accessible.
The European Union's Medical Device Regulation (MDR) has intensified the requirements for clinical evidence and post-market surveillance for all medical devices, including bone grafts. This change forces manufacturers to invest more in generating robust, long-term clinical data to support their product claims. The synthetic graft segment is particularly affected, as it must now build an evidence base to rival that of long-established xenografts.
Dental Service Organizations (DSOs) are standardizing procurement protocols for dental consumables, including bone void fillers, across their networks. This trend shifts purchasing decisions from individual clinicians to centralized committees that prioritize products based on a combination of clinical performance, ease of use, and cost-effectiveness. This purchasing model is most developed in the United States, influencing which brands gain dominant share within large clinic groups.
Global Dental Bone Void Filler Market Segmentation
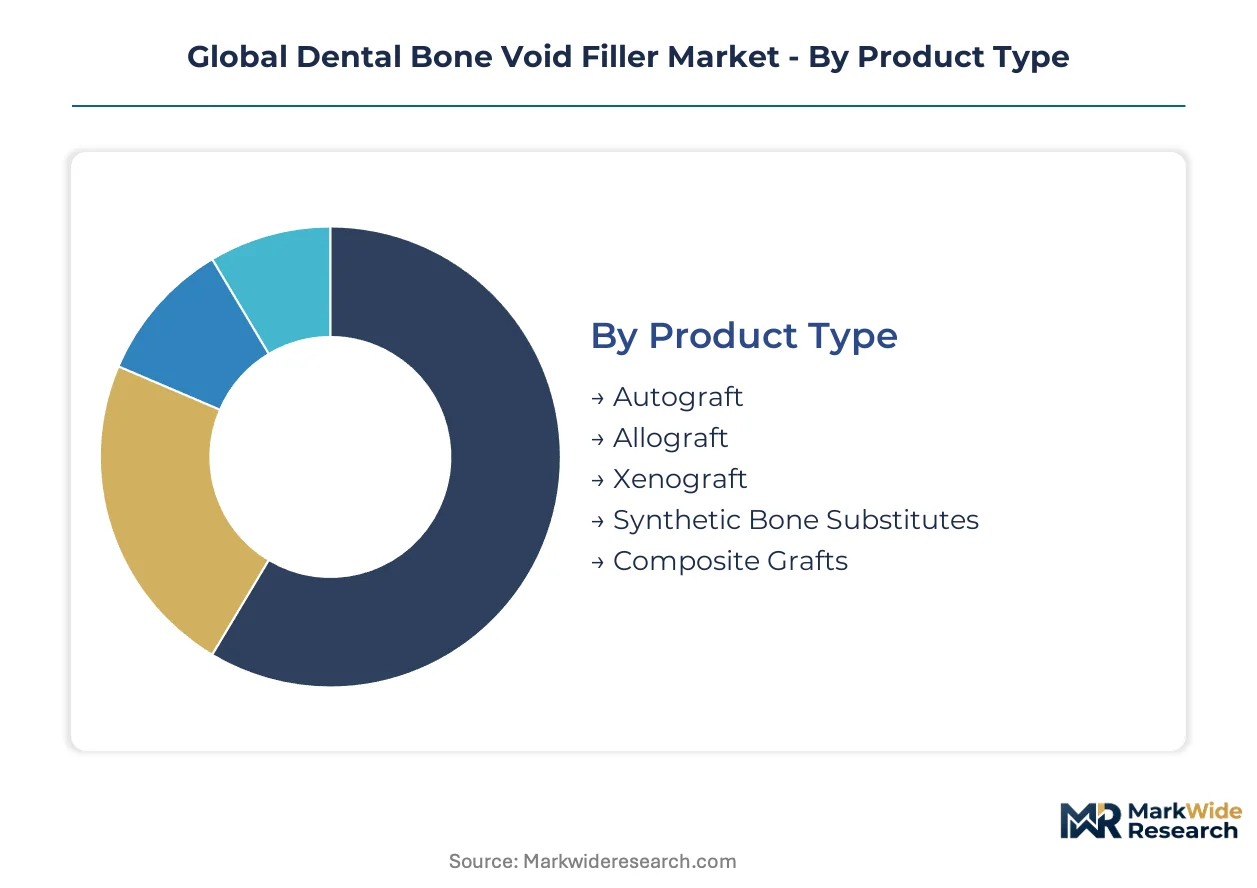
Segmentation of the dental bone void filler market reveals critical insights into product adoption patterns and the diverse requirements of clinical procedures. This granular view helps manufacturers tailor product development and market strategies to specific end-user needs and application demands. Understanding these distinctions is fundamental for navigating the competitive landscape.
Product Type:
The varied product types in the dental bone void filler market demand distinct levels of post-sale support and clinician training, influencing manufacturer investment in education and technical assistance.
- Synthetic Bone Substitutes:Bioactive glass and biphasic calcium phosphate formulations provide enhanced osteoconductivity and predictable resorption profiles. Demand for these materials is rapidly expanding in routine dental procedures across Germany and South Korea due to their safety and supply consistency.
- Xenograft:Derived from animal sources, these materials offer a natural collagen matrix for bone ingrowth and integration. They command a large share in specific premium segments, particularly within established clinical practices requiring extensive bone regeneration.
- Autograft:Harvested from the patient's own body, providing osteoinductive and osteogenic properties with minimal immunological risk.
- Allograft:Sourced from human donors, offering osteoconductive and osteoinductive potential for various bone grafting applications.
- Composite Grafts:Combine different materials, such as synthetic and natural components, to leverage synergistic properties for complex bone regeneration challenges.
By volume, xenografts command a large share. By growth pace, synthetic bone substitutes are expanding rapidly.
Application:
Applications for dental bone void fillers vary significantly in procedural complexity and required material properties, from simple socket preservation to extensive reconstructive surgeries.
- Implant Dentistry:This application involves filling bone defects to support dental implants, often utilizing putty formulations for their ease of use and handling. A rising volume of dental implant procedures, particularly in countries with aging populations, fuels this segment.
- Oral & Maxillofacial Surgery:Encompasses a broad range of procedures requiring substantial bone reconstruction, from trauma repair to tumor resection. This segment demands materials with robust structural integrity and predictable resorption characteristics.
- Periodontal Regeneration:Focuses on restoring bone and tissue lost due to periodontal disease, often requiring materials that support guided tissue regeneration.
- Ridge Augmentation:Increases the width or height of the alveolar ridge to accommodate dental implants or improve prosthetic fit.
- Alveolar Ridge Preservation:Minimizes bone loss after tooth extraction, maintaining bone volume for future prosthetic placement.
Demand concentrates heavily in implant dentistry and oral & maxillofacial surgery due to their high procedural volumes.
End User:
Different end-user segments exhibit distinct purchasing patterns and procurement protocols for dental bone void fillers, influencing distribution strategies.
- Dental Clinics:General practitioners and implantologists within these settings increasingly adopt user-friendly synthetic putties for routine procedures. Dental Service Organizations standardize procurement for these clinics, impacting brand dominance.
- Oral Surgery Centers:These specialized facilities perform complex bone grafting procedures, requiring a broad range of materials including premium xenografts and allografts. These centers often have dedicated surgical teams.
- Specialty Dental Hospitals:Provide comprehensive dental care, often handling advanced cases requiring specialized bone void fillers and complex surgical interventions.
- Outpatient Care Centers:Offer accessible surgical interventions, including minor bone grafting procedures that benefit from efficient and cost-effective materials.
- Academic Research Institutes:Focus on developing novel biomaterials and evaluating the clinical efficacy of new bone void fillers through preclinical and clinical studies.
Dental clinics and oral surgery centers represent strategically important segments for volume sales and advanced procedural adoption.
Delivery Form:
Delivery forms significantly impact surgical workflow and ease of handling, influencing clinician preference and procedural efficiency.
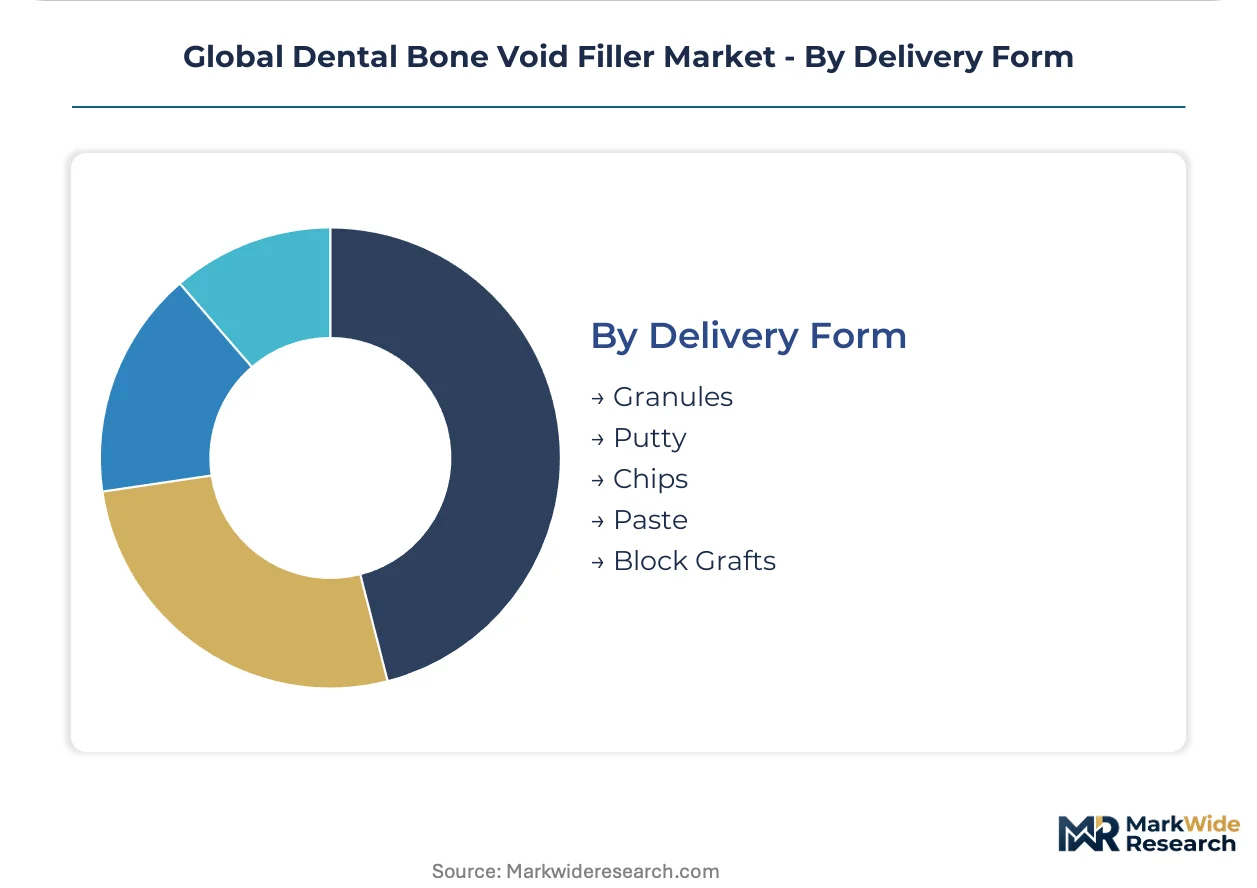
- Putty:Ready-to-use synthetic putties combine bioactive ceramics with resorbable carriers, offering superior handling and placement control. Implantologists and general dental surgeons widely adopt these for their efficiency in the operating room.
- Granules:This standard delivery form provides a versatile option for filling various bone defects, often mixed with blood or saline to achieve desired consistency. Granules remain a foundational material in many grafting protocols.
- Chips:Irregularly shaped particles used for filling defects, providing a scaffold for bone regeneration in areas requiring particulate graft material.
- Paste:Flowable formulations that conform to irregular spaces, offering ease of application in specific anatomical sites where precise molding is beneficial.
- Block Grafts:Solid blocks of bone material, typically xenograft, used for large-volume augmentation requiring structural integrity and mechanical stability.
Putty formulations are gaining preference in implant dentistry, while granules maintain a strong presence as a standard option.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across global markets, with some regions demonstrating high price sensitivity while others prioritize clinical efficacy and advanced material properties. Emerging markets often seek cost-effective solutions, whereas established economies frequently invest in premium, evidence-backed bone void fillers.
United States
Expanding implant dentistry procedures drive demand for dental bone void fillers, particularly user-friendly synthetic putties. The US FDA's 510(k) pathway sets rigorous standards for market entry and product claims. New York's dental research institutions actively develop novel biomaterial formulations, pushing innovation in regenerative therapies.
Germany
An aging population and high dental care standards fuel the consumption of advanced synthetic materials, such as bioactive glass formulations. Compliance with the EU's Medical Device Regulation (MDR) is essential for manufacturers operating here. Munich's medical technology cluster focuses on developing next-generation osteoconductive scaffolds for complex cases.
China
Government healthcare initiatives, aimed at improving public access to advanced dental treatments, significantly expand the market for both synthetic and xenograft materials. NMPA approvals are critical for market penetration and product distribution. Shanghai's burgeoning medical device industry is central to domestic production and localized distribution networks.
South Korea
High volumes of dental implant procedures, driven by an aging demographic and sophisticated dental practices, accelerate the adoption of synthetic bone substitutes. The MFDS enforces stringent requirements for medical device registration and post-market surveillance. Seoul's specialized dental clinics lead in the clinical evaluation of innovative resorbable materials.
Brazil
Untapped demand from a growing middle class and expanding dental tourism creates new avenues for market growth, particularly for cost-effective and efficient materials. ANVISA regulations govern the approval and commercialization of dental biomaterials within the country. São Paulo's robust dental equipment sector supports local manufacturing and distribution capabilities.
Global Dental Bone Void Filler Market Key Industry Players
Capability concentration sits with one tier of manufacturers, specializing in advanced biomaterials and clinical evidence, while scale advantage sits with another, focusing on broad distribution and diverse portfolios. The market structure exhibits a tiered consolidation, where a few global players command significant segments. Strategic archetypes include specialized biomaterial innovators, diversified dental solution providers, and orthopedic-focused companies extending into dental. Dominant competitive moves include extensive clinical data generation and the strategic acquisition of niche material technologies.
Specialized biomaterial innovators, such as Geistlich Pharma, anchor the premium segments with their established clinical evidence base in xenografts and allografts. Diversified dental solution providers, exemplified by Dentsply Sirona, leverage extensive distribution networks to promote a broad portfolio spanning natural and synthetic options. Meanwhile, Stryker, a company with a strong orthopedic and maxillofacial focus, extends its reach into dental surgery applications, competing on robust structural integrity and predictable resorption characteristics.
| Leading Market Players |
|---|
| Medtronic |
| ZimVie |
| Curasan Inc |
| Stryker |
| Dentsply Sirona |
| Graftys |
| Olympus Terumo Biomaterials |
| Geistlich Pharma |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
The transatlantic shipping corridor's fluctuating freight costs directly influence the concentrated supply of advanced biomaterials, subsequently driving price differentiation across premium and standard dental bone void filler segments. This dynamic impacts both manufacturer margins and end-user adoption patterns across global markets.
Pricing Analysis
After-sales training and technical support services drive significant lifetime value for dental bone void filler manufacturers. Pricing stratifies across premium, standard, and economy tiers, primarily differentiated by clinical evidence and regulatory certifications like US FDA 510(k) clearance. Pricing softness stems from the increasing adoption of cost-effective synthetic alternatives by general practitioners. Specialized oral surgery centers, however, exhibit lower price sensitivity for established, clinically proven xenografts and allografts.
Supply Chain Analysis
Specialized biomaterial contract manufacturers in Germany and the United States hold significant capacity for advanced synthetic bone void fillers. The supply chain draws from key raw materials like medical-grade calcium phosphate and bovine collagen. Regulatory restrictions on animal-derived products, particularly under the EU's MDR, pose a structural risk, especially for xenografts. Distribution runs through a network of specialized dental distributors and direct sales forces targeting oral surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental bone void filler market presents a significant service-attach opportunity, with clinician training programs and technical support expanding faster than the underlying hardware sales. This trend underscores the importance of educational ecosystems for product adoption and loyalty.
For Market Incumbents: Insulate premium xenograft segments by investing in robust long-term clinical data generation, countering the threat from cost-effective synthetic alternatives. Deepen channel control through exclusive partnerships with Dental Service Organizations in the United States, securing volume sales. Manufacturers should also enhance their regulatory affairs capabilities to navigate evolving EU MDR requirements, maintaining market access for established products.
For New Entrants and Emerging Players: Build out specialized product portfolios targeting patient-specific implant applications, leveraging 3D printing technology for custom scaffolds. The Latin American market, particularly Brazil, represents a penetrable geography due to expanding dental tourism and a growing middle class. A direct-to-clinician sales model, emphasizing ease of use and reduced procedural complexity for general practitioners, offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Niche biomaterial technology developers with strong IP in bioactive glass formulations represent attractive acquisition targets over a five-to-ten-year window. These innovators offer pathways to next-generation osteoconductive scaffolds, enhancing long-term portfolio value. The signal to watch is the increasing rate of US FDA 510(k) clearances for novel synthetic composite grafts, indicating market readiness for advanced materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Generation for Synthetics | This initiative establishes evidence for novel materials, rivaling established xenografts in the European Union. |
| 3D Printing Bioceramic Scaffolds | Custom-fabricated patient-specific implants improve surgical outcomes for complex maxillofacial cases. |
| Expand Clinician Training Programs | Surgeon education on new putty formulations boosts adoption among general dental surgeons. |
| Regulatory Approval in Brazil | Securing ANVISA approval unlocks access to a growing middle-class market in Latin America. |
| Partnership with Dental Service Organizations | Standardized procurement protocols within DSOs drive volume sales for preferred brands in the United States. |
Research Approach
Desk research of regulatory filings, academic literature, and industry reports preceded structured interviews with implantologists, oral surgeons, and hospital procurement managers. This primary engagement validated market dynamics and pricing structures through a bottom-up approach. Secondary data from US FDA 510(k) clearances and EU MDR compliance documents provided a top-down market sizing framework.
Assumptions regarding regulatory stability and dental procedure volumes were held fixed, while material innovation rates were varied across the analysis window. The analytical framework modeled market segments by product type, application, end-user, delivery form, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected adoption rates for synthetic materials. Dental implant procedure volumes served as a key forecast input.
Stress conditions across raw material availability and reimbursement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect current market dynamics and anticipated technological advancements. Cross-checking against national dental association statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Alloys Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Artificial Teeth Market
Dental Materials
Dental Gypsum Market
Dental Materials
Fluoride Materials Market
Dental Materials
Global Dental Cements Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Dental Polymerization Lamps Market