
 Dental Fiberglass Posts Market | 2026-2036
Dental Fiberglass Posts Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Fiberglass Posts Market Outlook
Asset-light leasing models for CAD/CAM milling equipment is rewriting competitive entry barriers for mid-sized dental laboratories seeking in-house post fabrication capabilities. COLTENE Group leverages its vertically integrated composite manufacturing to sustain cost advantages across European distribution networks. Dentsply Sirona anchors its position through direct sales relationships with university dental hospitals in North America. Angelus Indústria de Produtos Odontológicos dominates Latin American markets with localized production and regulatory registration depth.
Dental fiberglass posts are cylindrical reinforcements composed of epoxy resin-impregnated glass fibers, typically exhibiting flexural strengths exceeding 600 MPa and elastic moduli approximating dentin to reduce root fracture risk during functional loading. Prefabricated posts lead volume consumption due to standardized sizing and immediate chairside availability, while custom posts capture premium margin pools through patient-specific anatomical adaptation. Core build-up materials represent the fastest-growing adjunct segment as clinicians integrate post placement with immediate coronal restoration protocols.
FDA 510(k) clearance pathways and ISO 6876 endodontic sealing standards govern product commercialization in the United States, while the EU MDR requires notified body intervention for all implantable dental devices including intraradicular posts. Health Canada and Japan's PMDA maintain parallel biocompatibility testing protocols that manufacturers must navigate for multi-regional approval. Stakeholders should monitor evolving MDR classification debates around permanent versus temporary post indications, as reclassification would trigger additional clinical evidence requirements and reshape competitive registration timelines.
Market Dynamics
EU MDR biocompatibility testing requirements are compressing product registration timelines and forcing manufacturers to rebuild clinical evidence portfolios for intraradicular post classifications.
Growth Catalysts
- Prefabricated Post Standardization:Chairside availability protocols in Brazilian private dental clinics are accelerating same-day restoration workflows and reducing laboratory turnaround dependency.
- MDR Compliance Infrastructure:Notified body intervention requirements for implantable dental devices are filtering out marginal competitors and consolidating compliant supplier bases.
- CAD/CAM Leasing Models:Asset-light equipment financing is lowering capital barriers for mid-sized dental laboratories pursuing in-house post fabrication capabilities.
Market Restraints
- Epoxy Resin Input Volatility:Petrochemical feedstock price swings directly compress gross margins for composite-integrated manufacturers without captive resin supply.
- German Manufacturing Concentration:Production gravity around Baden-Württemberg and Bavaria creates single-region exposure to energy cost shocks and logistics bottlenecks.
- Bioceramic Substitution:Zirconia and lithium disilicate post alternatives are capturing anterior aesthetic cases where metal-free claims drive patient preference.
Strategic Opportunities
- Core Build-Up Integration:Immediate coronal restoration protocols are expanding addressable procedure value per patient visit beyond standalone post placement.
- University Hospital Direct Sales:North American academic dental centers represent concentrated volume anchors for training-driven product standardization.
- Latin American Localization:In-country manufacturing and regulatory registration depth unlock preferential tender access across Brazilian and Mexican public health systems.
Industry Challenges
- MDR Classification Uncertainty:Pending debates over permanent versus temporary post indications threaten to trigger additional clinical evidence requirements and reshape competitive registration timelines.
- Multi-Regulatory Testing Redundancy:Parallel biocompatibility protocols at Health Canada, Japan's PMDA, and FDA 510(k) pathways force duplicated expenditure without harmonized acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Fiberglass Posts Market |
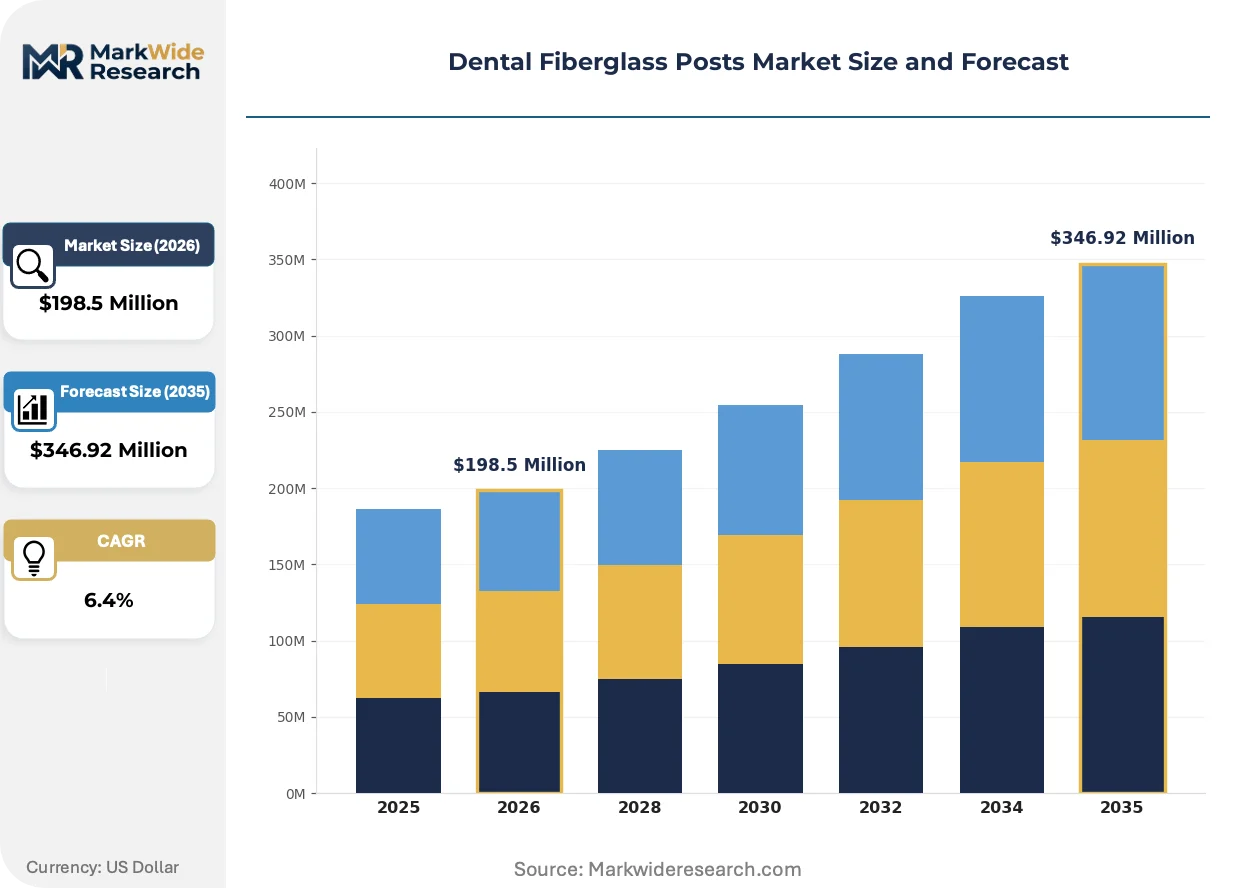
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $346.92 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefabricated Posts, Custom Posts, Core Build-up, Endodontic Posts Application: Root Canal Treatment, Reconstructive Procedures, Pediatric Dentistry, Restorative Dentistry End User: Private Clinics, Dental Hospitals, Academic Institutions, Research Laboratories Distribution Channel: Online Sales, Direct Sales, Third-Party Distributors, Wholesale Suppliers |
| Companies Covered | COLTENE Group, Dentatus, 3M Company, Angelus Indústria de Produtos Odontológicos, Ultradent Products, Ivoclar Vivadent, VOCO GmbH, Harald Nordin, Dentsply Sirona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Fiberglass Posts Market Strategic Shifts
Digital fabrication workflows are collapsing traditional boundaries between laboratory production and chairside delivery, reconfiguring how fiberglass posts reach end-users.
CAD/CAM milling systems are digitizing custom post production by translating intraoral scan data into patient-specific anatomical geometries. German dental laboratories are deploying these systems at accelerating rates to bypass prefabricated sizing limitations. The technology is digitizing margin capture from chairside specialists who previously relied exclusively on standardized post libraries.
EU MDR Article 10 clinical evaluation requirements are extending documentation burdens for endodontic device manufacturers seeking CE marking renewal. The regulation forces systematic biocompatibility reassessment across legacy product portfolios. German notified bodies are processing implantable dental device applications with extended review cycles, compressing revenue recognition timelines for registrants.
Brazilian private clinics are consolidating procurement around single-source post-and-core system suppliers to streamline inventory and training overhead. Distributors are responding with bundled pricing architectures that tie fiberglass post volumes to adjunct composite and cement purchases. This concentration is most visible in São Paulo and Rio de Janeiro metropolitan markets where clinic chains command purchasing leverage.
Dental Fiberglass Posts Market Segmentation
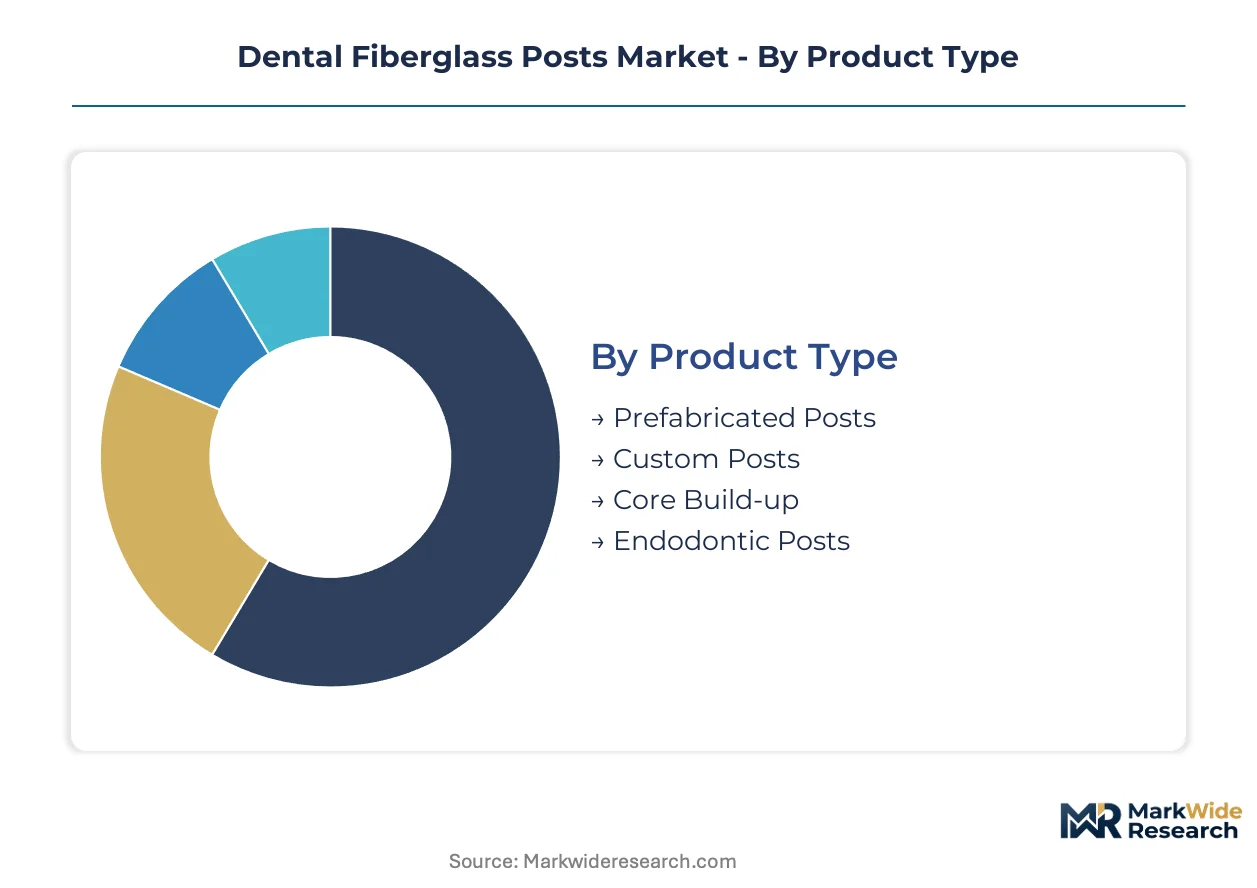
Segmentation in the dental fiberglass posts market reveals how clinical workflows, procurement patterns, and regulatory pathways fragment addressable demand. Each dimension exposes different margin pools and competitive entry points for manufacturers and distributors.
Product Type:
After-sales service intensity varies sharply across product types, with custom fabrication demanding technical support infrastructure that prefabricated lines rarely require.
- Prefabricated Posts:Epoxy resin-impregnated glass fiber cylinders with standardized diameters and tapers enable immediate chairside placement without laboratory involvement. Brazilian private dental clinics in São Paulo and Rio de Janeiro metropolitan markets are consolidating procurement around single-source post-and-core system suppliers to streamline inventory and training overhead.
- Custom Posts:CAD/CAM-milled or laboratory-fabricated patient-specific geometries adapt to irregular root canal morphologies that standardized sizes cannot address. German dental laboratories around Baden-Württemberg and Bavaria are deploying digital fabrication systems at accelerating rates to capture margin from chairside specialists who previously relied exclusively on prefabricated post libraries.
- Core Build-up:Composite materials integrated with post placement for immediate coronal restoration.
- Endodontic Posts:Specialized intraradicular reinforcements designed specifically for endodontically treated teeth.
Prefabricated posts hold the largest share; momentum sits with core build-up as clinicians integrate immediate restoration protocols.
Application:
Cost tier stratification separates high-volume routine procedures from premium reconstructive interventions with distinct reimbursement and equipment requirements.
- Root Canal Treatment:Standard endodontic therapy followed by post placement for coronal reconstruction represents the foundational application volume. Private dental clinics across Brazil are expanding adoption of prefabricated fiberglass post systems to accelerate same-day restoration workflows and reduce laboratory turnaround dependency.
- Reconstructive Procedures:Complex multi-unit restorations and post-and-core foundations for crowns and bridges demand precise biomechanical compatibility. The EU MDR biocompatibility testing requirements for implantable dental devices are filtering out marginal competitors and consolidating compliant supplier bases for these higher-risk indications.
- Pediatric Dentistry:Modified post designs for immature permanent teeth and primary tooth pulpectomies.
- Restorative Dentistry:Broad category encompassing direct and indirect coronal restorations supported by intraradicular posts.
Root canal treatment commands the greatest volume; reconstructive procedures are climbing the fastest as aesthetic demands intensify.
End User:
Customer type determines purchasing authority, with institutional procurement following tender protocols that diverge sharply from private clinic decision-making.
- Private Clinics:Independent and chain-affiliated practices with direct clinician-driven purchasing autonomy. Bundled pricing architectures tie fiberglass post volumes to adjunct composite and cement purchases, concentrating supplier relationships around integrated system vendors.
- Dental Hospitals:High-volume institutional settings with centralized procurement and training standardization requirements.
- Academic Institutions:University dental hospitals in North America represent concentrated volume anchors where direct sales relationships drive training-driven product standardization and future practitioner preference formation.
- Research Laboratories:Specialized facilities investigating post biomechanics and novel material formulations.
Private clinics generate the dominant revenue stream; academic institutions are gaining share fastest through training-driven standardization effects.
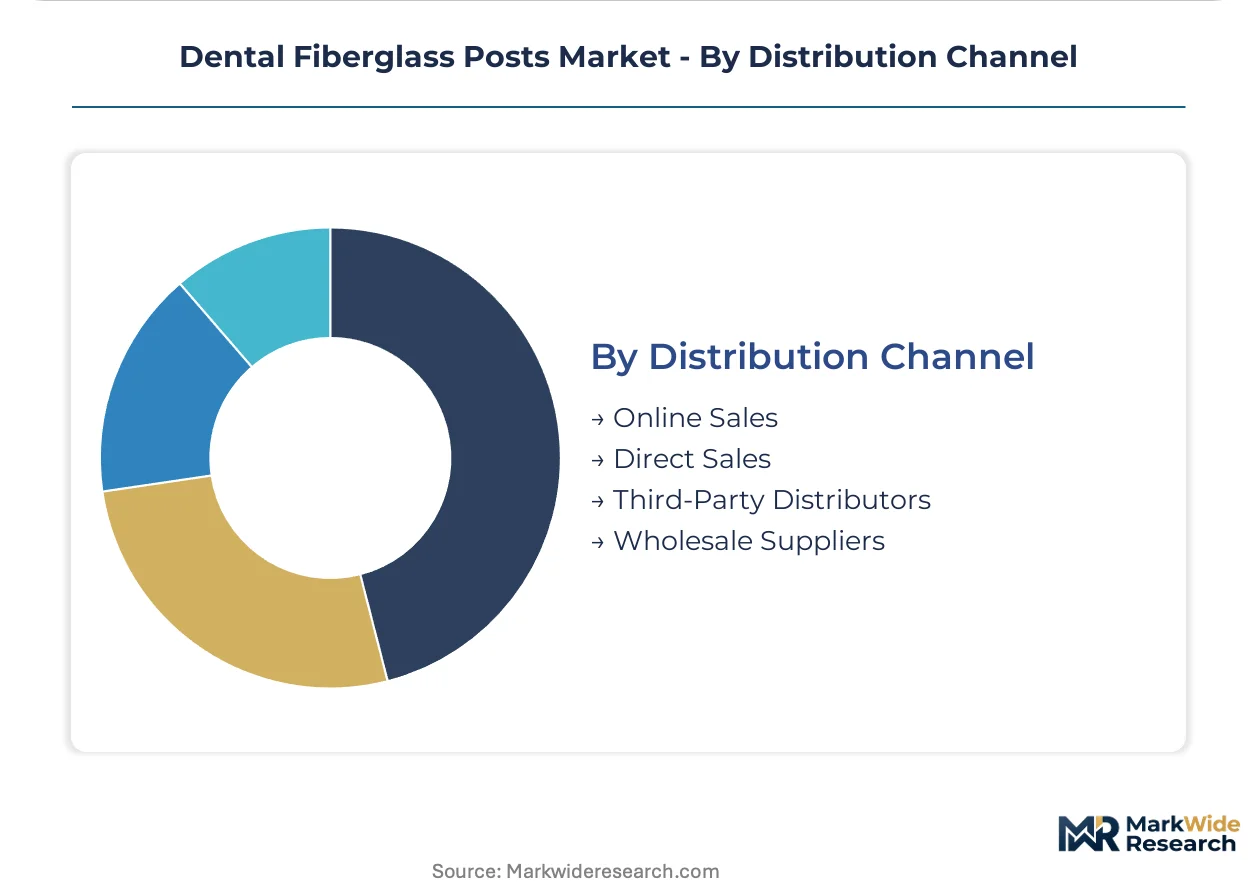
Distribution Channel:
Supply concentration in German manufacturing clusters shapes how products reach end-users across diverging channel economics.
- Direct Sales:Manufacturer-to-institution relationships bypass intermediary margins and enable technical training integration. Dentsply Sirona anchors its market position through direct sales relationships with university dental hospitals in North America.
- Third-Party Distributors:Regional specialists with regulatory registration depth and localized logistics capabilities. Angelus Indústria de Produtos Odontológicos dominates Latin American markets through this channel by leveraging in-country manufacturing and preferential tender access across Brazilian and Mexican public health systems.
- Online Sales:E-commerce platforms serving smaller clinics with immediate availability and transparent pricing.
- Wholesale Suppliers:Broad-line dental distributors with consolidated catalog offerings across multiple product categories.
Third-party distributors retain the largest share; direct sales are expanding most quickly as manufacturers seek training integration and margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German manufacturing clusters supply prefabricated post systems to dental distributors across Western Europe and Latin America, while Brazilian clinics import composite-integrated kits from regional hubs in Argentina and Mexico to bypass Atlantic shipping bottlenecks.
Germany
Baden-Württemberg and Bavaria host concentrated dental manufacturing infrastructure serving EU-wide demand through CE-marked distribution networks. The EU MDR notified body intervention requirements for implantable devices are extending registration review cycles for regional exporters. Stuttgart-area laboratories are deploying CAD/CAM milling systems at accelerating rates to capture custom post fabrication margins from chairside specialists.
United States
University dental hospitals in North America anchor training-driven volume for prefabricated post standardization among future practitioners. FDA 510(k) clearance pathways govern commercialization timelines for epoxy resin-impregnated fiber systems entering the market. Greater Boston and Pacific Northwest metropolitan clusters concentrate specialty dental laboratory capacity for complex reconstructive post-and-core procedures.
Brazil
Private dental clinics in São Paulo and Rio de Janeiro metropolitan markets are consolidating procurement around single-source post-and-core system suppliers to streamline inventory overhead. ANVISA registration requirements for implantable dental devices create preferential access for manufacturers with in-country regulatory depth. Localized production facilities in Minas Gerais state supply bundled post-composite-cement kits to public health tenders.
Japan
PMDA biocompatibility testing protocols parallel FDA requirements, forcing duplicated expenditure for manufacturers seeking multi-regional approval without harmonized acceptance. Tokyo and Osaka dental laboratory clusters import German-manufactured prefabricated posts while developing domestic CAD/CAM custom fabrication capabilities. METI industrial standards for dental materials are tightening epoxy resin purity specifications for intraradicular applications.
Canada
Health Canada maintains biocompatibility testing protocols that mirror FDA 510(k) pathways without mutual recognition, extending registration timelines for US-manufactured post systems. Ontario and Quebec dental laboratory networks rely on cross-border supply chains from US Midwest manufacturing clusters. Provincial procurement tenders for academic dental hospitals concentrate volume in Toronto and Montreal metropolitan corridors.
Dental Fiberglass Posts Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin and fiber supply. The vendor base stratifies between multinational dental conglomerates with direct hospital sales infrastructure and mid-sized regional fabricators with regulatory registration depth. Three archetypes dominate: vertically integrated composite manufacturers, CAD/CAM equipment lessors with captive post libraries, and localized distributors with tender access. Competitive moves concentrate on M&A for regulatory portfolio consolidation and asset-light equipment financing partnerships to lower laboratory entry barriers.
Among European-based manufacturers, COLTENE Group exemplifies the vertically integrated archetype through captive composite manufacturing, while VOCO GmbH occupies a position within German dental materials specialization. Dentsply Sirona anchors the platform-integrator tier through direct sales relationships with academic institutions. Angelus Indústria de Produtos Odontológicos represents the localized-distributor model with Latin American regulatory depth and in-country production advantages.
| Leading Market Players |
|---|
| COLTENE Group |
| Dentatus |
| 3M Company |
| Angelus Indústria de Produtos Odontológicos |
| Ultradent Products |
| Ivoclar Vivadent |
| VOCO GmbH |
| Harald Nordin |
| Dentsply Sirona |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin feedstock volatility compresses gross margins for composite-integrated manufacturers without captive supply, forcing pricing tier spreads that separate vertically integrated incumbents from import-dependent distributors while reshaping procurement patterns toward bundled post-and-core system contracts.
Pricing Analysis
Private dental clinics anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation resting on ISO 6876 certification grade and after-sales technical support intensity. Cost compression in the standard tier is intensifying because Brazilian clinic chains leverage bundled procurement volumes to extract cement and composite concessions. Price sensitivity peaks among independent single-practitioner clinics in São Paulo's peripheral districts, while German academic hospitals exhibit lowest sensitivity due to training-driven standardization budgets.
Supply Chain Analysis
Contract manufacturing for epoxy resin-impregnated glass fiber cylinders concentrates around Baden-Württemberg and Bavaria processing facilities, with secondary finishing operations in Minas Gerais serving Latin American tender markets. Raw material dependencies draw from German petrochemical feedstock streams, Japanese glass fiber roving imports, and Swiss precision taper grinding equipment. Single-source vulnerability sits with energy-intensive resin curing operations exposed to German industrial electricity tariffs. Distribution runs through third-party dental distributors with ANVISA and FDA registration depth, supplemented by direct manufacturer-to-hospital relationships for academic institutional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Core build-up material integration and CAD/CAM technical service contracts are expanding addressable revenue per procedure faster than standalone post hardware, converting transactional supply relationships into recurring service architectures.
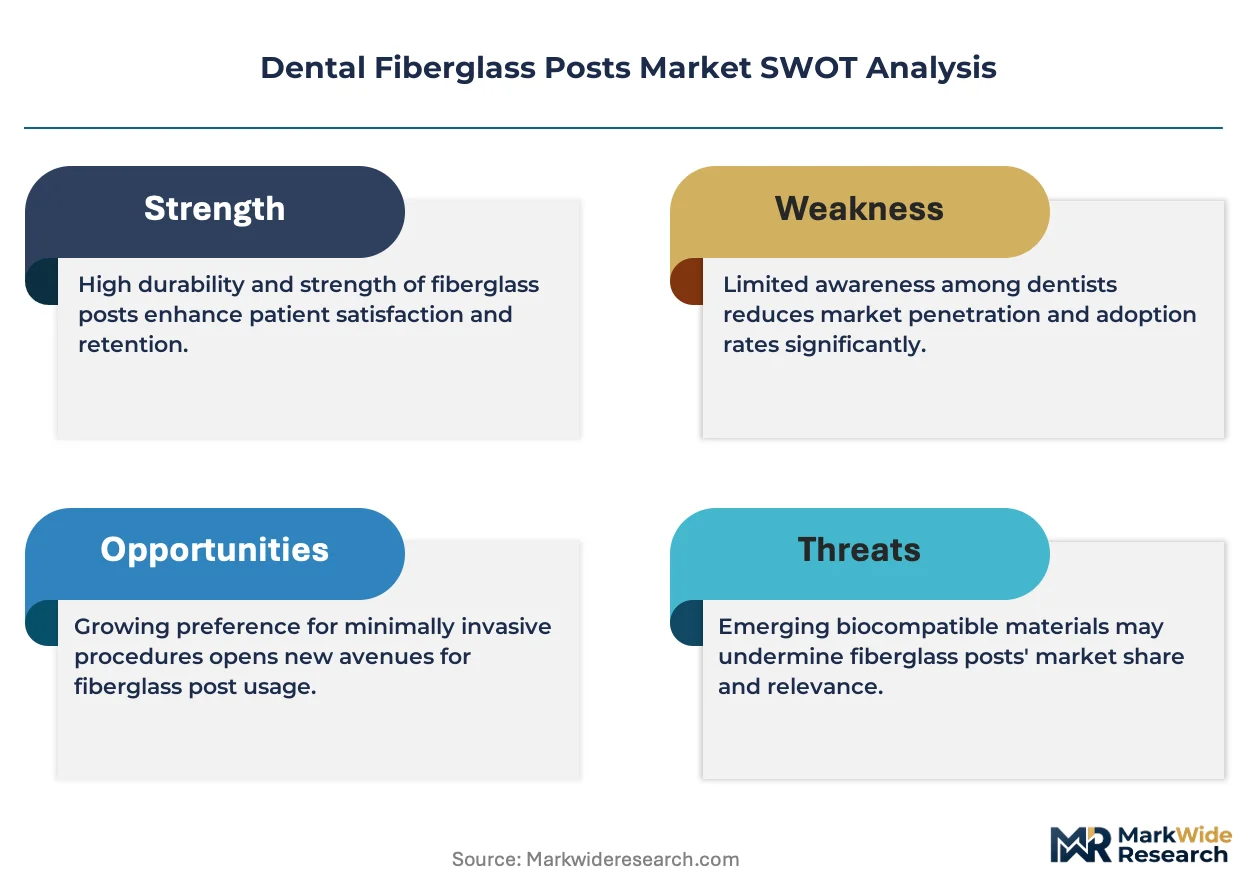
For Market Incumbents: Entrench position through backward integration into epoxy resin formulation to offset petrochemical volatility, while deepening notified body relationships to compress EU MDR renewal cycles before classification debates trigger additional clinical evidence requirements. Bioceramic substitution in anterior aesthetic cases demands defensive R&D investment in translucent fiber post variants. For New Entrants and Emerging Players: Pursue white-space capture in Brazilian public health tenders where ANVISA registration depth creates preferential access barriers for foreign competitors, and exploit asset-light CAD/CAM leasing partnerships to penetrate mid-sized German laboratories seeking custom fabrication capabilities without capital commitment. A training-centric go-to-market angle targeting university hospital residents builds future practitioner preference formation. For Investors and Strategic Acquirers: EU MDR Article 10 clinical evaluation requirements reshape the acquisition landscape toward targets with established notified body relationships and legacy portfolio documentation completeness. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than manufacturing scale alone. The signal to watch is MDR classification determinations on permanent versus temporary post indications, which would trigger differential clinical evidence burdens and revalue registration portfolios accordingly.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Infrastructure Investment | Notified body pre-submission meetings compress CE marking timelines for implantable device classifications. |
| Core Build-up Material Integration | Immediate coronal restoration protocols expand procedure value capture beyond standalone post placement. |
| CAD/CAM Leasing Partnership | Asset-light equipment financing lowers laboratory entry barriers for in-house custom post fabrication. |
| Latin American Localization | In-country ANVISA registration unlocks preferential tender access across Brazilian public health systems. |
| University Hospital Direct Sales | Academic institutional relationships drive training-driven product standardization among future practitioners. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, ISO 6876 endodontic sealing standards, and EU MDR notified body guidance documents. Clinical endodontists, dental laboratory technicians, GPO contracts managers, and biomedical procurement officers at academic hospitals provided structured input. Customs trade data from German export statistics and Brazilian ANVISA registration databases supplied volume triangulation. Bottom-up procedure frequency estimates and top-down manufacturing capacity assessments were cross-validated.
Forecast inputs include prefabricated versus custom post adoption curves, CAD/CAM equipment penetration rates in German laboratories, and bundled procurement contract expansion across Brazilian clinic chains. Segmentation dimensions span product type, application workflow, end-user purchasing authority, and distribution channel economics. CAGRs were derived from procedure volume elasticity to dental workforce growth and equipment financing availability across the analysis window. Epoxy resin price indices and MDR registration timeline assumptions inform margin trajectory modeling.
Macroeconomic conditions sit as an overlay; deviation in German industrial energy tariffs or Atlantic shipping rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory classification stability and biocompatibility testing protocol harmonization timelines. Quarterly review of notified body queue lengths, ANVISA registration approval rates, and Brazilian private clinic M&A activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Australia and New Zealand Dental Biomaterials Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Dental Plaster Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Dental Wax Market
Dental Materials
Dental Resins Market
Dental Materials
Toothpaste Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Global Demineralized Bone Matrix Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Dental Alginate Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Amalgam Market