
 Fluoride Mouthwash Market | 2026-2036
Fluoride Mouthwash Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoride Mouthwash Market Analysis
Stannous fluoride is recalibrating product economics across the fluoride mouthwash category as manufacturers reformulate away from sodium fluoride to capture antimicrobial dual-action benefits. Colgate-Palmolive Company leverages its captive stannous supply chain to control input costs across Latin American production. Procter & Gamble Company sustains formulation leadership through sustained-release polymer systems in its therapeutic rinse lines. Kenvue Inc. anchors North American retail distribution through pharmacy-exclusive professional-strength variants.
Fluoride mouthwash denotes an aqueous oral rinse solution containing soluble fluoride salts, typically at concentrations between 0.02% and 0.05% sodium fluoride or stannous fluoride, designed to deliver topical fluoride ions that promote enamel remineralization and inhibit demineralization. The alcohol-free segment leads volume growth as consumers reject ethanol-based formulations linked to mucosal irritation and dry mouth. Dental clinics represent the fastest-expanding distribution channel as practitioners integrate prescription-strength rinses into caries management protocols. Traditional bottled formats still dominate value capture, though single-use sachets are penetrating travel and institutional segments.
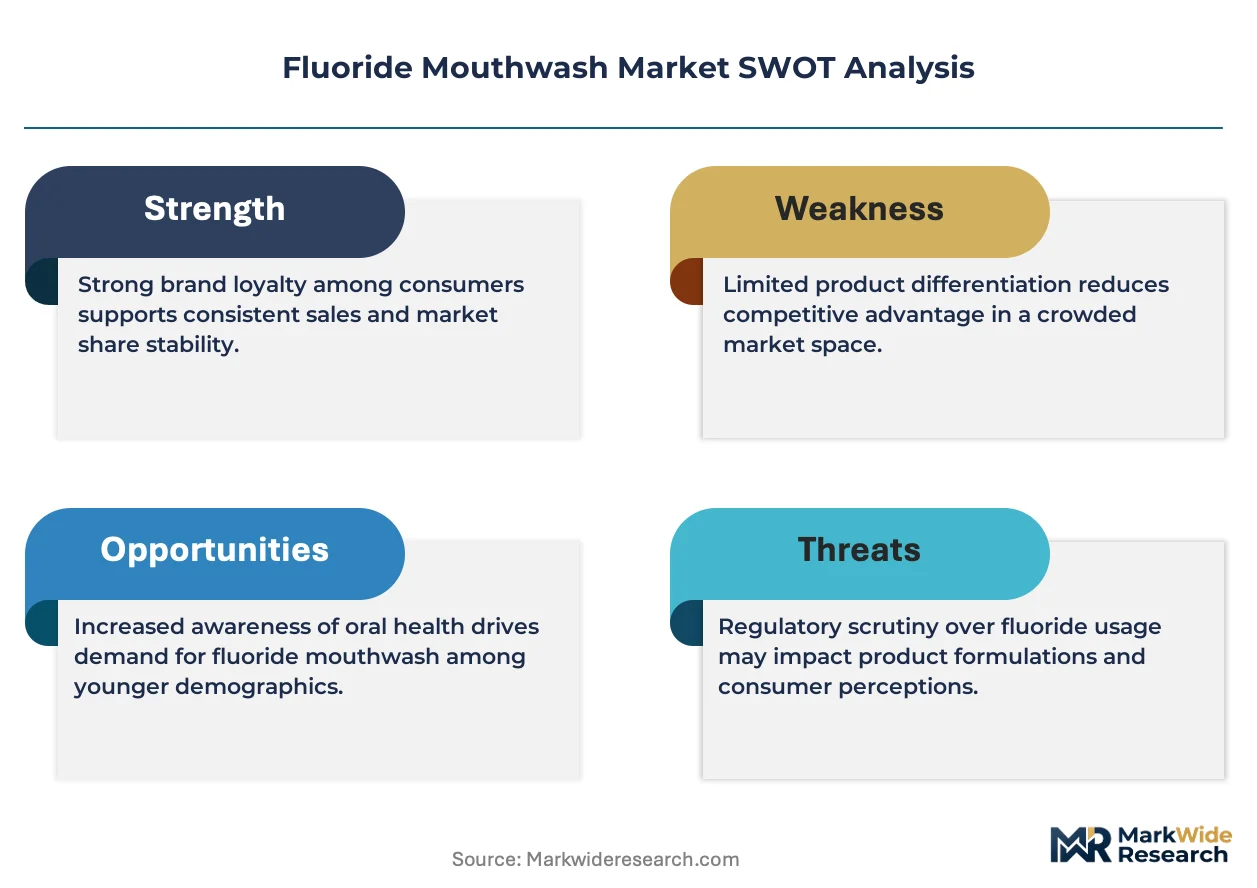
The FDA regulates fluoride mouthwash as either cosmetic or drug depending on therapeutic claims, requiring New Drug Application pathways for anti-cavity indications above cosmetic thresholds. The EPA monitors fluoride discharge from manufacturing facilities under Clean Water Act provisions, elevating compliance costs for domestic producers. EMA and national European regulators enforce REACH compliance on fluoride sourcing and packaging recyclability mandates. Stakeholders must monitor evolving classification thresholds that could resegment professional versus over-the-counter channels.
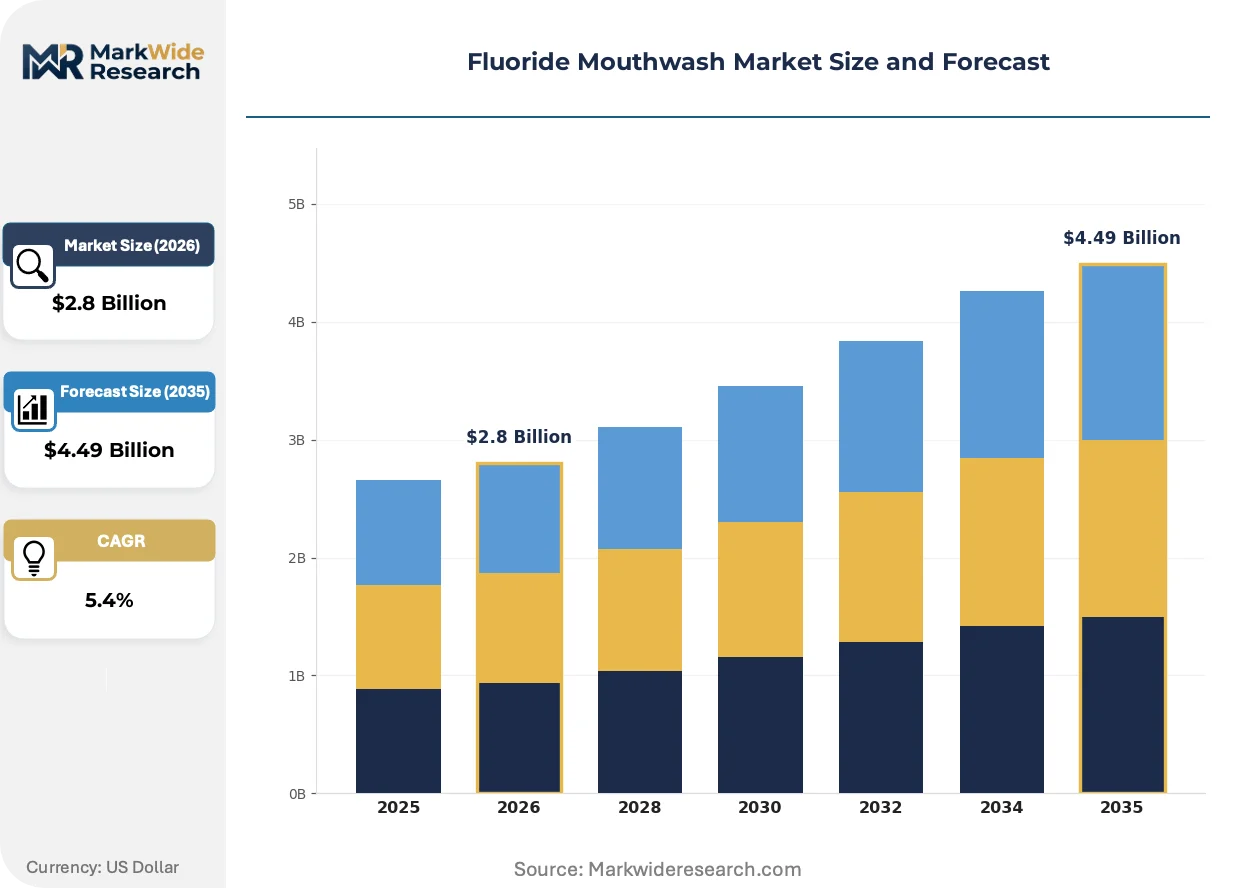
Market Dynamics
The fluoride mouthwash market is restructuring around stannous fluoride substitution as manufacturers abandon sodium fluoride to capture antimicrobial dual-action benefits and command premium shelf positioning.
Growth Catalysts
- REACH packaging recyclability mandates:European cosmetic safety standards are accelerating alcohol-free formulation adoption as ethanol-based rinses face regulatory scrutiny for mucosal irritation.
- Pediatric dental programs:Institutional procurement in the United States is expanding as school-based caries prevention protocols integrate prescription-strength fluoride rinses.
- Stannous fluoride chemistry:Dual-action antimicrobial benefits are driving reformulation investments as manufacturers seek enamel remineralization plus bacterial inhibition in single products.
Market Restraints
- Tin supply concentration:Stannous fluoride feedstock depends on concentrated Southeast Asian tin smelting capacity, exposing formulators to raw material volatility.
- FDA New Drug Application thresholds:Therapeutic anti-cavity claims above cosmetic thresholds trigger protracted approval pathways, delaying product launches by 18-36 months.
- Xylitol substitution threat:Natural sweetener-based oral care products are capturing price-sensitive consumers seeking fluoride alternatives.
Strategic Opportunities
- Travel-size sachet formats:Single-use packaging is penetrating institutional and airline amenity channels where portability and hygiene compliance converge.
- EPA Clean Water Act compliance services:Fluoride discharge monitoring mandates are creating adjacent revenue streams for environmental consulting firms serving manufacturing facilities.
- Tele-dentistry integration:Remote oral health consultations are expanding prescription rinse distribution beyond traditional dental clinic channels.
Industry Challenges
- Polymer formulation expertise:Sustained-release fluoride delivery systems require specialized polymer chemistry talent that concentrates among legacy pharmaceutical excipient suppliers.
- Dual regulatory classification:Cosmetic-versus-drug ambiguity forces parallel compliance investments, straining mid-tier manufacturers with limited regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoride Mouthwash Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Alcohol-Free, Gel-Based, Spray End User: Adults, Children, Pregnant Women, Seniors Distribution Channel: Pharmacies, Supermarkets, Online Stores, Dental Clinics Packaging Type: Bottles, Sachets, Tubes, Pouches |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble Company, Kenvue Inc., Johnson & Johnson, GlaxoSmithKline plc, Lion Corporation, Haleon plc, Church & Dwight Co., Inc., Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoride Mouthwash Market Emerging Trajectories
Formulation chemistry and distribution architecture are converging to redefine competitive advantage, with polymer science, regulatory arbitrage, and channel specialization emerging as the decisive vectors.
Smart dispensing technology is automating dosage precision in professional settings. Dental clinics are deploying connected rinse stations that log patient compliance and automate refill ordering. This infrastructure is automating inventory management burdens while generating adherence data that insurers increasingly require for preventive care reimbursement.
EMA and national European regulators are tightening cosmetic safety standards on ethanol content, forcing reformulation investments across export-oriented manufacturers. The industrial consequence is accelerated alcohol-free pipeline development. Premium therapeutic lines are responding fastest, repositioning ethanol-free chemistry as a clinical benefit rather than compliance necessity.
Pharmacy-exclusive professional-strength variants are consolidating retail access as mass-market channels face margin compression. Independent pharmacies and clinic dispensaries are displacing supermarket shelf space for high-concentration formulations. Germany and France exhibit the most pronounced channel bifurcation, where reimbursement codes reinforce professional gatekeeping.
Fluoride Mouthwash Market Segmentation
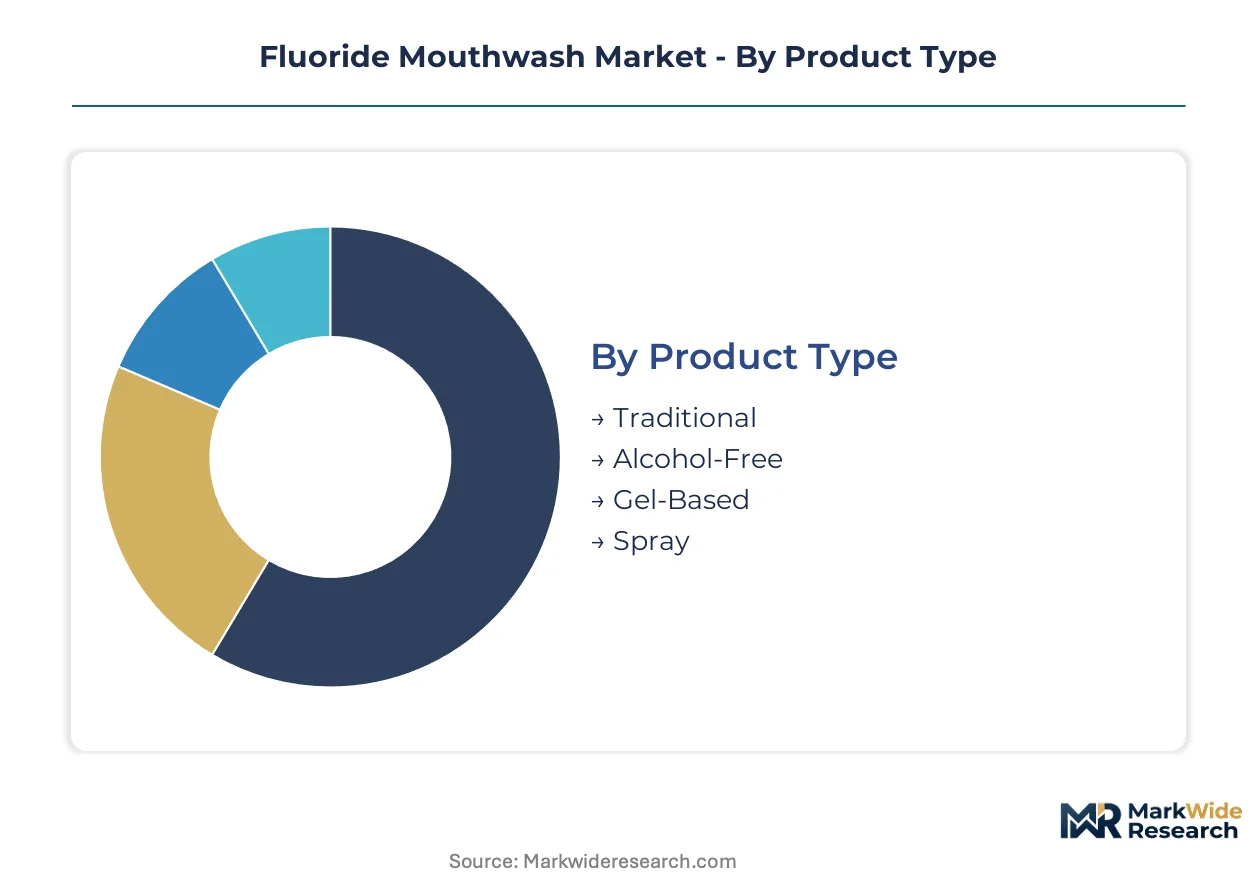
Fluoride mouthwash segmentation reflects divergent consumer priorities across therapeutic efficacy, sensory experience, and procurement context. Manufacturers calibrate formulation chemistry, concentration levels, and packaging formats to match distinct usage occasions and regulatory pathways.
Product Type:
Customization intensity spans from commodity aqueous solutions to specialized delivery systems requiring polymer engineering expertise.
- Traditional:Ethanol-based formulations containing sodium fluoride at cosmetic-grade concentrations dominate institutional procurement contracts. School-based caries prevention programs in the United States specify these rinses for weekly supervised applications.
- Alcohol-Free:Glycerin-propylene glycol vehicles replace ethanol to eliminate mucosal irritation while maintaining fluoride solubility. EMA cosmetic safety standards in Europe are accelerating reformulation investments as ethanol content faces tightening scrutiny.
- Gel-Based:Thickened rheology extends tissue contact time for enhanced enamel remineralization in high-caries-risk patients.
- Spray:Metered-dose aerosol formats target pediatric compliance and travel convenience segments.
Leading the category by volume: Traditional. Growing fastest: Alcohol-Free.
End User:
Physiological vulnerability and fluoride tolerance thresholds determine concentration limits and flavor masking requirements across demographic cohorts.
- Adults:Standard 0.05% sodium fluoride formulations support daily maintenance regimens for general caries prevention. Pharmacy channels capture the bulk of self-directed procurement.
- Children:Reduced-concentration 0.02% formulations with intense flavoring systems address compliance challenges in supervised school programs. Pediatric dental protocols specify weekly rather than daily application frequencies.
- Pregnant Women:Alcohol-free chemistry is mandatory given teratogenic concerns with ethanol exposure during gestation.
- Seniors:Xerostomia-friendly bases accommodate medication-induced dry mouth prevalent in polypharmacy populations.
Dominant demand source: Adults. Steepest expansion trajectory: Children via institutional procurement growth.
Distribution Channel:
Channel selection dictates regulatory classification thresholds and reimbursement eligibility, separating cosmetic from therapeutic positioning.
- Pharmacies:Professional-strength 0.05% formulations with pharmacy-exclusive SKUs command premium positioning. Germany and France exhibit pronounced channel bifurcation where reimbursement codes reinforce professional gatekeeping.
- Supermarkets:Mass-market 0.02% cosmetic-grade rinses compete on shelf price and brand recognition.
- Online Stores:Subscription models and bulk purchasing are penetrating price-sensitive household segments.
- Dental Clinics:Prescription-strength rinses with compliance-tracking packaging integrate into caries management protocols. Connected rinse stations logging patient adherence are automating inventory and generating insurer-required data.
Highest value capture: Dental Clinics. Expanding most quickly: Online Stores.
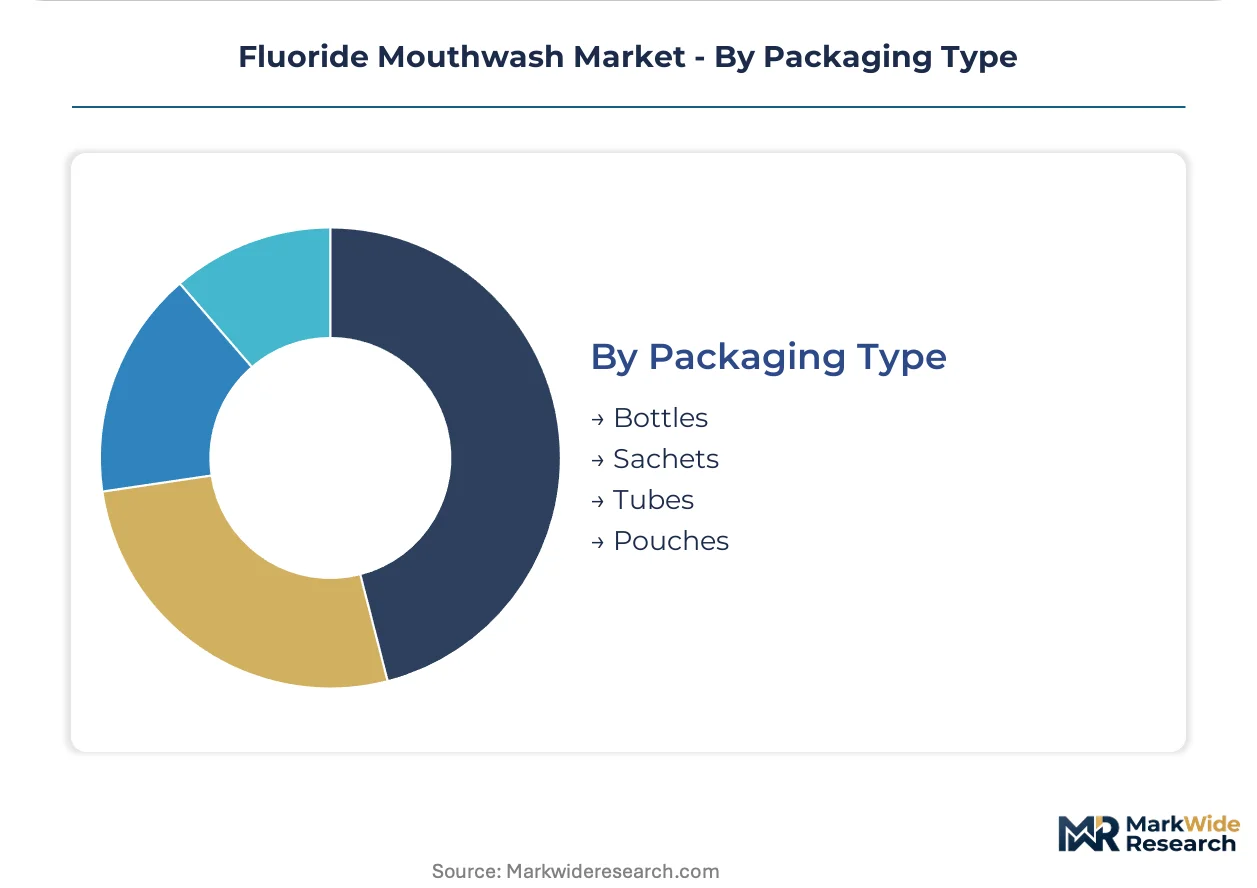
Packaging Type:
Unit economics and contamination risk trade off against portability and dosing precision across format selection.
- Bottles:Multi-dose PET containers with child-resistant closures dominate household purchasing. EPA Clean Water Act compliance costs elevate for domestic manufacturing facilities handling bottle washing discharge.
- Sachets:Single-use foil-laminate pouches eliminate cross-contamination in institutional and airline amenity channels. REACH packaging recyclability mandates in Europe are forcing material transitions.
- Tubes:Collapsible aluminum or laminate structures suit gel-based formulations requiring precise extrusion control.
- Pouches:Flexible stand-up formats with spouts target value-conscious emerging market consumers.
Standard format by volume: Bottles. Gaining share fastest: Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fluoride mouthwash concentrates in the United States, where pediatric dental programs and institutional procurement channels anchor volume. Germany, Japan, India, and Brazil represent distinct growth vectors shaped by regulatory frameworks and distribution infrastructure maturity.
United States
School-based caries prevention protocols and pharmacy-exclusive professional-strength variants drive procurement expansion. The FDA's cosmetic-versus-drug classification thresholds shape channel strategies, with therapeutic claims triggering New Drug Application pathways. Greater Boston and the Research Triangle host polymer chemistry talent pools supplying sustained-release formulation expertise to manufacturers.
Germany
EMA cosmetic safety standards and REACH packaging recyclability mandates accelerate alcohol-free reformulation investments. Reimbursement codes reinforce professional gatekeeping through pharmacy-exclusive distribution. The Rhine-Ruhr industrial corridor concentrates contract manufacturing capacity serving export-oriented oral care brands.
Japan
Aging demographics and xerostomia-friendly product demand expand senior-targeted formulations. METI standards on cosmetic safety and polymer excipient quality elevate technical barriers for market entry. The Kansai region around Osaka anchors domestic production of gel-based and spray-format specialty rinses.
India
Price-sensitive household segments and expanding pharmacy retail networks drive mass-market penetration. CDSCO regulates therapeutic claims while state-level school health programs pilot institutional fluoride rinse distribution. Maharashtra and Gujarat host formulation facilities serving both domestic consumption and export to Southeast Asian markets.
Brazil
ANVISA oversight of cosmetic and pharmaceutical classifications creates dual compliance pathways for market entrants. Rising middle-class oral health awareness expands supermarket and online channel penetration. São Paulo state concentrates multinational subsidiary operations and regional distribution hubs for Latin American markets.
Fluoride Mouthwash Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational consumer goods conglomerates commanding premium therapeutic positioning while regional formulators capture price-sensitive volume. The vendor base concentrates around three strategic archetypes: polymer science leaders, captive stannous supply chain operators, and pharmacy-channel exclusivity specialists. Competitive moves center on sustained-release technology licensing and backward integration into tin smelting partnerships.
Within the polymer science tier, Procter & Gamble Company exemplifies sustained-release formulation leadership. Colgate-Palmolive Company occupies a position as the archetypal captive supply chain operator with stannous fluoride integration. Kenvue Inc. anchors the pharmacy-exclusive distribution vector through professional-strength retail positioning.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble Company |
| Kenvue Inc. |
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Lion Corporation |
| Haleon plc |
| Church & Dwight Co., Inc. |
| Unilever PLC |
| Others |
Supply Flow & Price Mechanics
Tin price volatility on the London Metal Exchange cascades through fluoride mouthwash manufacturing, compressing margins for stannous-dependent formulators while rewarding operators with captive smelter partnerships or sodium fluoride alternatives.
Pricing Analysis
Volume capture concentrates in mass-market 0.02% cosmetic-grade rinses sold through supermarkets and online channels, while margin extraction concentrates in pharmacy-exclusive 0.05% therapeutic formulations with professional gatekeeping. Price differentiation rests on fluoride concentration tier and regulatory classification status, with FDA drug-pathway products commanding premiums over cosmetic-grade equivalents. Pricing pressure stems from xylitol-based natural alternatives capturing price-sensitive household segments. Institutional procurement through school dental programs exhibits lowest price sensitivity due to reimbursement code insulation, while emerging-market consumers demonstrate highest elasticity.
Supply Chain Analysis
Reverse-logistics infrastructure for multi-dose bottle returns remains underdeveloped, though REACH packaging recyclability mandates in Europe are forcing material transitions toward aluminum-laminate sachets with established collection schemes. Raw material sourcing draws from Malaysian and Indonesian tin smelting capacity for stannous fluoride, Chinese polymer excipient production for sustained-release systems, and domestic US chemical manufacturing for sodium fluoride alternatives. Supply chain risk centers on single-source vulnerability in Southeast Asian tin concentrate processing. Distribution runs through pharmacy wholesale networks for professional-strength variants, mass-market retail for cosmetic-grade products, and direct clinic dispensing for prescription protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around polymer formulation expertise and stannous supply chain control, with REACH compliance costs and FDA drug-pathway timelines forcing mid-tier manufacturers toward exit or acquisition.
For Market Incumbents: To counter xylitol substitution threats and margin compression in mass-market channels, incumbents should deepen backward integration into tin smelting partnerships or regional polymer excipient supply agreements, while accelerating alcohol-free pipeline development to preempt EMA cosmetic safety tightening. For New Entrants and Emerging Players: Tele-dentistry subscription platforms offer the most penetrable white-space entry, bypassing pharmacy gatekeeping through remote prescription fulfillment and compliance-tracking rinse delivery. Target travel-size sachet formats for airline amenity and institutional procurement channels where established brands maintain weaker positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor polymer chemistry specialists in Greater Boston and the Research Triangle, where formulation talent scarcity creates defensive moats. Long-term viability hinges on regulatory arbitrage capacity across cosmetic-drug classification thresholds. Watch FDA New Drug Application backlog clearance rates as inflection signal for therapeutic-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Stannous Fluoride Backward Integration | Captive tin supply from Malaysian smelters insulates Colgate-Palmolive from LME volatility. |
| Sustained-Release Polymer Licensing | Procter & Gamble's excipient partnerships extend fluoride contact time for clinical differentiation. |
| Tele-Dentistry Platform Partnership | Remote prescription channels expand Kenvue's pharmacy-exclusive reach beyond physical retail. |
| Alcohol-Free Reformulation Acceleration | EMA compliance investments reposition ethanol-free chemistry as clinical benefit. |
| Smart Dispensing Infrastructure Deployment | Connected rinse stations in dental clinics automate inventory and generate insurer-required adherence data. |
Methodological Framework
Document review covered FDA 510(k) filings, EMA cosmetic safety guidance, EPA Clean Water Act discharge monitoring reports, and London Metal Exchange tin price benchmarks, complemented by interviews with formulation chemists at multinational oral care manufacturers, procurement managers at pharmacy wholesale networks, regulatory affairs specialists navigating drug-cosmetic classification, and dental clinic administrators supervising school-based caries prevention programs. Secondary validation drew from customs trade data, SEC 10-K disclosures, and Nielsen retail audit information. Bottom-up volume builds across concentration tiers, packaging formats, and distribution channels were triangulated against top-down market sizing from industry association estimates.
Segment-level projections across the analysis window were generated through regression modeling of fluoride concentration adoption curves, alcohol-free formulation penetration rates, and institutional procurement expansion in pediatric dental programs. The analytical framework incorporated product type, end-user demographic, distribution channel, and packaging format as core segmentation dimensions, with regional regulatory cluster as an industry-specific overlay. CAGRs were derived from fitted growth curves rather than linear extrapolation, with sensitivity testing around tin price volatility and FDA approval timeline scenarios.
The model holds under stable REACH enforcement and FDA classification thresholds; deviation in EMA ethanol-content restrictions or EPA discharge mandate tightening would shift volume trajectories toward alcohol-free and sachet formats respectively. Material deviation in London Metal Exchange tin price bands or FDA New Drug Application backlog clearance rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Teeth Whitening Market
Dental Materials
Dental Cavity Filling Material Market
Dental Materials
Dental Alloys Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Global Dental Cements Market
Dental Materials
Sensitive Toothpaste Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Crack Tooth Syndrome Market
Dental Materials
Dental Gypsum Market
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Toothpaste Market
Dental Materials
Global Dental Zirconia Block Market
Dental Materials
Dental Amalgam Market