
 Calcium Hydroxylapatite Fillers Market | 2026-2036
Calcium Hydroxylapatite Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Hydroxylapatite Fillers Market Analytics
Buyer concentration among cosmetic clinics is consolidating as multi-site dermatology chains and private equity-backed aesthetics platforms expand their purchasing power across metropolitan markets. Merz Pharma leverages its established European manufacturing footprint to sustain supply relationships with these consolidating buyers. BioScience GmbH differentiates through specialized product formulations targeting facial contouring applications. CGBio Co. Ltd anchors its competitive position with integrated biocompatible material science capabilities rooted in South Korean research clusters.
Calcium hydroxylapatite fillers consist of synthetic or biogenic calcium phosphate microspheres suspended in aqueous carrier gels, typically formulated at particle sizes between 25 and 45 microns for optimal tissue integration and collagen neogenesis stimulation. These injectable implants primarily restore dermal volume and correct moderate-to-severe facial wrinkles through biostimulatory mechanisms rather than passive space-filling. Injectable fillers command the dominant revenue share given their established reimbursement pathways and clinician familiarity, while bone grafting substitutes represent the fastest-growing category as oral surgeons and orthopedic specialists adopt ceramic-based alternatives to autograft harvesting. Aesthetic fillers concentrate margin pools in premium positioning segments where formulation purity and sustained duration claims justify price premiums.
The US FDA maintains stringent 510(k) and PMA pathways for calcium hydroxylapatite-based devices, directly shaping product development timelines and clinical evidence requirements for market authorization. EMA's Medical Device Regulation and REACH chemical safety standards govern European commercialization, creating layered compliance obligations for cross-border suppliers. China's NMPA biocompatibility testing protocols and South Korea's MFDS quality management requirements add further territorial gatekeeping complexity. Stakeholders must monitor evolving regulatory convergence between major jurisdictions while calibrating clinical trial investments against regional approval timelines and reimbursement dynamics.
Market Dynamics
Multi-site dermatology chains and private equity-backed aesthetics platforms are consolidating purchasing power across metropolitan markets, compressing supplier margins while demanding formulation customization and volume guarantees from calcium hydroxylapatite manufacturers.
Growth Catalysts
- Biostimulatory mechanism preference:Cosmetic clinics favor calcium hydroxylapatite's collagen neogenesis over hyaluronic acid's passive volumizing, extending treatment intervals and patient retention rates.
- FDA 510(k) pathway clarity:The US regulator's established premarket notification framework for injectable devices accelerates compliant product introductions while filtering substandard competitors.
- South Korean research cluster density:Seoul-based biocompatible ceramic synthesis capabilities enable domestic manufacturers to reduce import dependency and capture regional demand.
Market Restraints
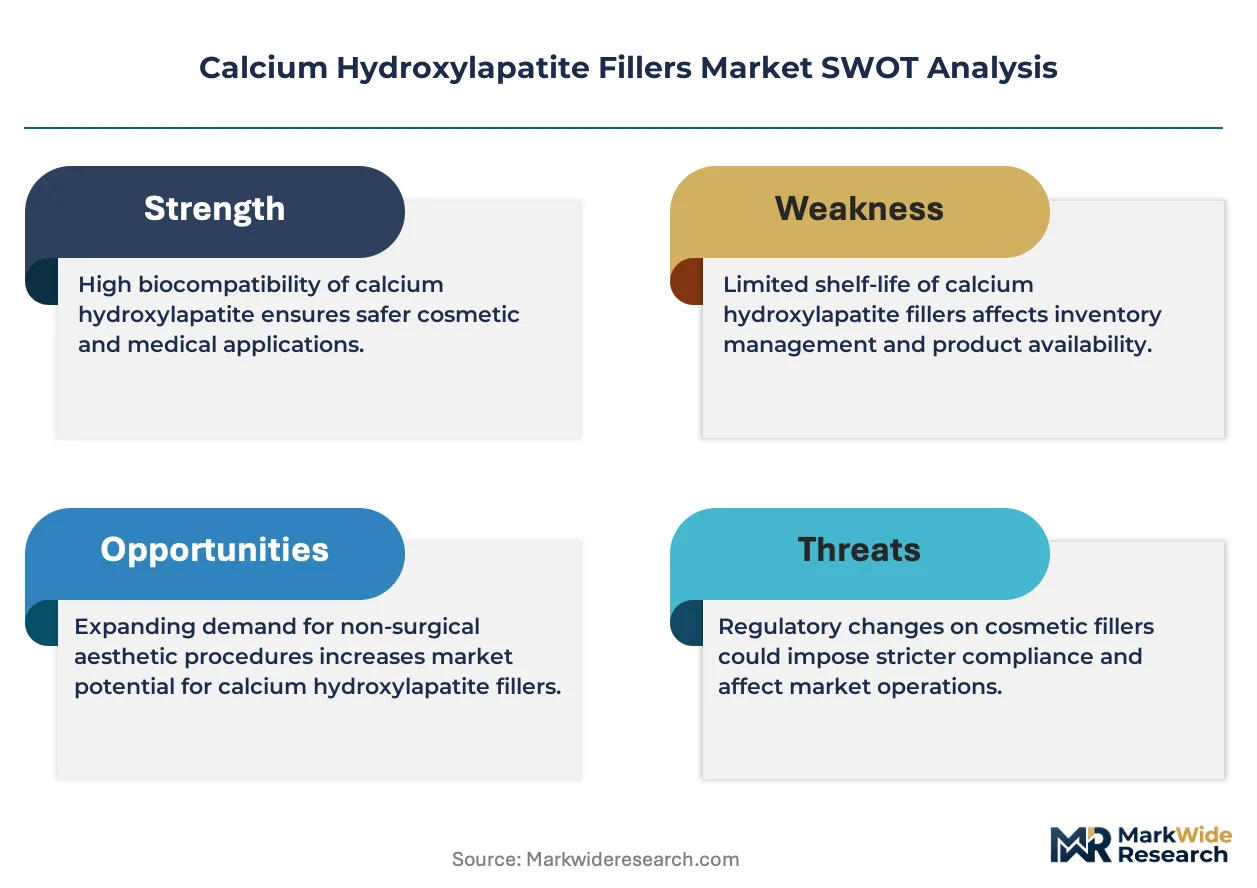
- Input cost volatility:Synthetic calcium phosphate precursor prices fluctuate with phosphate rock mining output and energy-intensive calcination costs.
- Supply concentration risk:European Union manufacturing footprints dominate high-purity microsphere production, creating geographic single-source vulnerabilities.
- Technical limitation:Particle size distribution control below 25 microns remains technically demanding, constraining superficial dermal application formulations.
Strategic Opportunities
- Underpenetrated oral surgery applications:Brazilian and Mexican maxillofacial specialists are adopting ceramic-based bone graft substitutes as autograft harvesting declines.
- Technology convergence:Combination products pairing calcium hydroxylapatite microspheres with lidocaine-integrated carrier gels are integrating pain management into single-injection protocols.
- Distribution channel innovation:Direct-to-clinic e-procurement platforms are disintermediating traditional medical device distributors in Australian and Canadian metropolitan markets.
Industry Challenges
- Specialized injector training requirements:Deep dermal and supraperiosteal placement techniques demand certified practitioner programs that clinics struggle to staff and fund.
- EMA MDR compliance timeline:European Economic Area re-registration under Medical Device Regulation imposes clinical evidence burdens and notified body bottlenecks on legacy product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Hydroxylapatite Fillers Market |
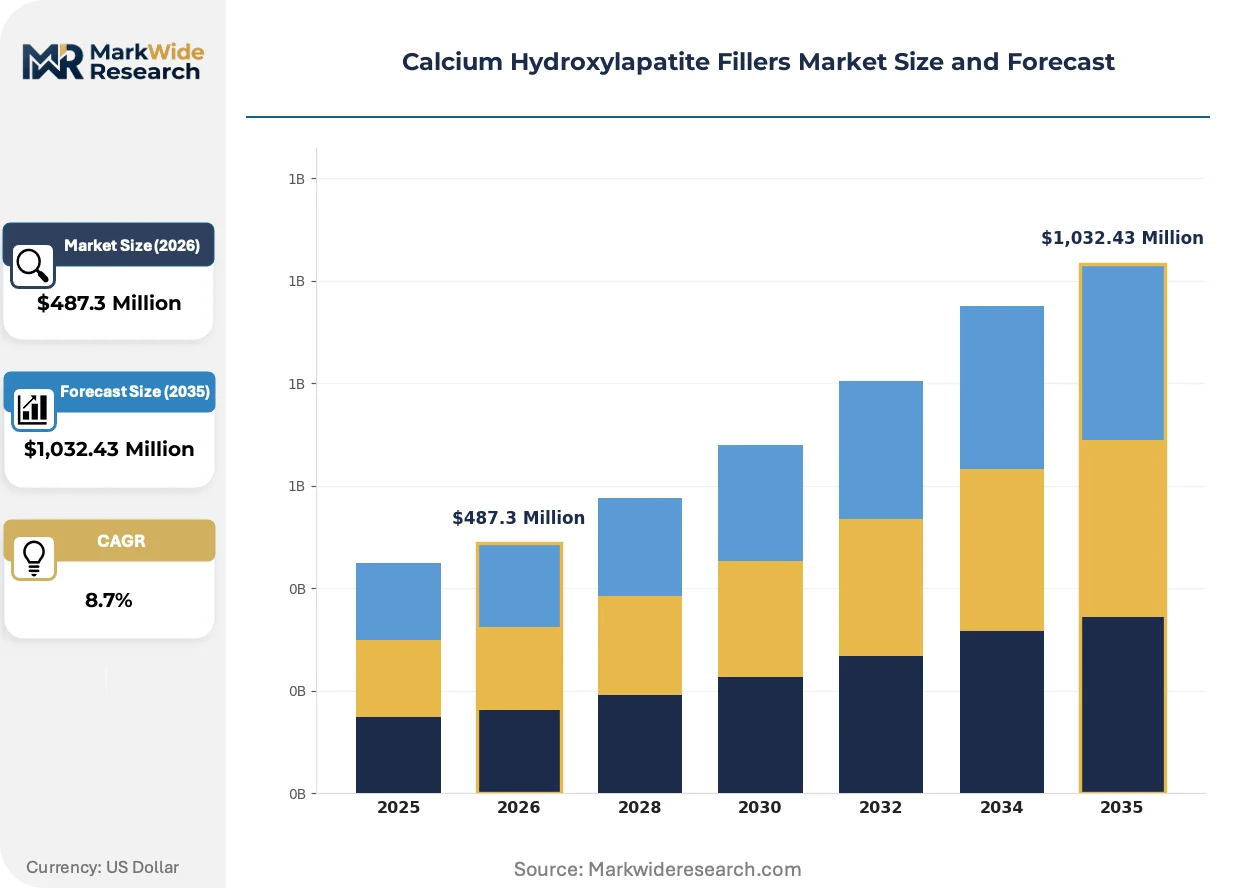
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aesthetic Fillers, Injectable Fillers, Dermal Fillers, Bone Grafting Substitutes End User: Cosmetic Clinics, Dermatology Centers, Hospitals, Plastic Surgery Centers Delivery Mode: Injection, Surgical Implant, Topical Application, Transdermal Patch Application: Facial Contouring, Wrinkle Reduction, Volume Restoration, Osteoporosis Treatment |
| Companies Covered | Dr. Korman Laboratories, Sinclair Pharma, Merz Pharma, BioScience GmbH, Suneva Medical Inc, CGBio Co. Ltd, Prollenium Medical Technologies Inc, IMEIK Technology Development Co., Cytophil Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Hydroxylapatite Fillers Market Evolving Landscape
Formulation science and carrier gel engineering are compressing injection pain and downtime, while regulatory harmonization efforts across major jurisdictions are reshaping clinical trial investment patterns for biostimulatory aesthetic devices.
Cross-linked carboxymethylcellulose carrier gels are integrating lidocaine and epinephrine for simultaneous anesthesia and vasoconstriction, reducing patient discomfort and bruising incidence. Aesthetic clinic chains in Germany and Spain are adopting these enhanced formulations at accelerated procurement cycles. The technology is integrating pain management and procedural efficiency into premium positioning tiers that justify elevated price points against standard hyaluronic acid alternatives.
EMA's Medical Device Regulation and REACH chemical safety standards are layering compliance obligations on European commercialization strategies, extending product development timelines by twelve to eighteen months. Manufacturers must now submit clinical performance data and post-market surveillance protocols that exceed previous directive requirements. Injectable filler categories face the steepest documentation burdens, prompting several suppliers to prioritize bone graft substitute segments where predicate device pathways remain more navigable.
Cosmetic clinic procurement departments are consolidating vendor relationships through multi-year volume agreements that bundle calcium hydroxylapatite with complementary toxin and energy-based device purchases. This behavior concentrates supplier selection power among three to five platform vendors per metropolitan market. The pattern is most visible in United States coastal cities and South Korean Seoul-Incheon corridor, where private equity-backed dermatology groups now control fifteen to twenty percent of injectable filler purchasing volume.
Calcium Hydroxylapatite Fillers Market Segmentation
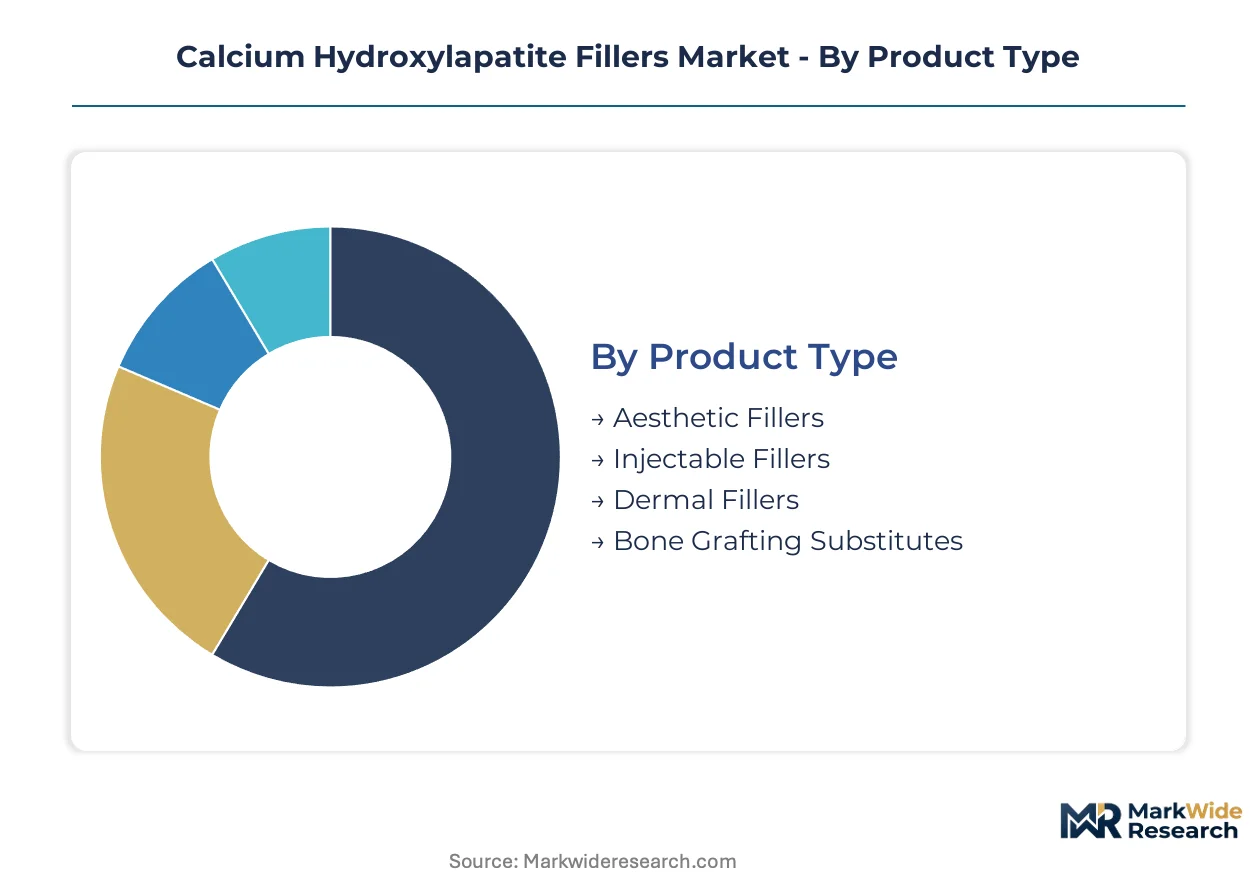
Calcium hydroxylapatite fillers segment across four critical dimensions that determine regulatory pathways, clinical training requirements, and procurement economics. Each category reflects distinct certification burdens and margin structures that shape supplier strategy.
Product Type:
FDA 510(k) clearance requirements vary sharply across product categories, with injectable devices demanding the most extensive biocompatibility documentation while bone graft substitutes navigate predicate device pathways more efficiently.
- Aesthetic Fillers:Premium formulations targeting facial rejuvenation concentrate revenue pools where sustained duration claims justify elevated price positioning against hyaluronic acid alternatives. Cosmetic clinics in Seoul and Los Angeles metropolitan corridors drive procurement volume for these high-margin products.
- Injectable Fillers:Suspended calcium phosphate microspheres in aqueous carrier gels command dominant commercial share through established reimbursement codes and clinician familiarity. The category faces steepest EMA MDR documentation burdens as legacy products undergo European Economic Area re-registration.
- Dermal Fillers:Superficial placement formulations requiring particle size control below 25 microns remain technically constrained. Manufacturers struggle with distribution uniformity for these applications.
- Bone Grafting Substitutes:Ceramic-based alternatives to autograft harvesting are expanding most quickly as oral surgeons and orthopedic specialists adopt synthetic solutions. Brazilian and Mexican maxillofacial practices show concentrated demand acceleration.
Injectable fillers sit at the top of the volume ranking, with bone graft substitutes climbing the fastest.
End User:
Customer concentration patterns diverge sharply between institutional purchasing departments and independent practice procurement, with multi-site chains extracting volume discounts that compress supplier margins.
- Cosmetic Clinics:Private equity-backed aesthetics platforms now control fifteen to twenty percent of injectable filler purchasing volume in United States coastal cities and South Korean metropolitan corridors. These buyers demand formulation customization and multi-year supply guarantees.
- Dermatology Centers:Academic and hospital-affiliated practices maintain stricter credentialing requirements for injector certification programs. Their procurement emphasizes clinical evidence packages and post-market surveillance data.
- Hospitals:Centralized purchasing departments prioritize bone graft substitute categories where surgical volume and orthopedic integration drive contract decisions.
- Plastic Surgery Centers:Boutique facilities concentrate in premium aesthetic filler segments where brand reputation and patient outcomes justify selective supplier relationships.
Cosmetic clinics generate the highest absolute volume, though dermatology centers show the steepest expansion trajectory as hospital systems acquire specialty practices.
Delivery Mode:
Route of administration determines training infrastructure requirements and malpractice exposure, with surgical implantation demanding operating theater protocols that injection-based alternatives circumvent.
- Injection:Deep dermal and supraperiosteal placement techniques require certified practitioner programs that clinics struggle to staff. Lidocaine-integrated carrier gels are compressing patient discomfort and procedural downtime.
- Surgical Implant:Orthopedic and maxillofacial applications rely on sterile field preparation and implant fixation protocols distinct from aesthetic practice workflows.
- Topical Application:Limited commercial penetration due to calcium phosphate particle size constraints preventing effective dermal penetration without mechanical disruption.
- Transdermal Patch:Experimental delivery formats remain preclinical for calcium hydroxylapatite given molecular weight and solubility limitations.
Injection dominates current volume, while surgical implant formats gain share fastest as ceramic bone substitutes displace autograft harvesting.
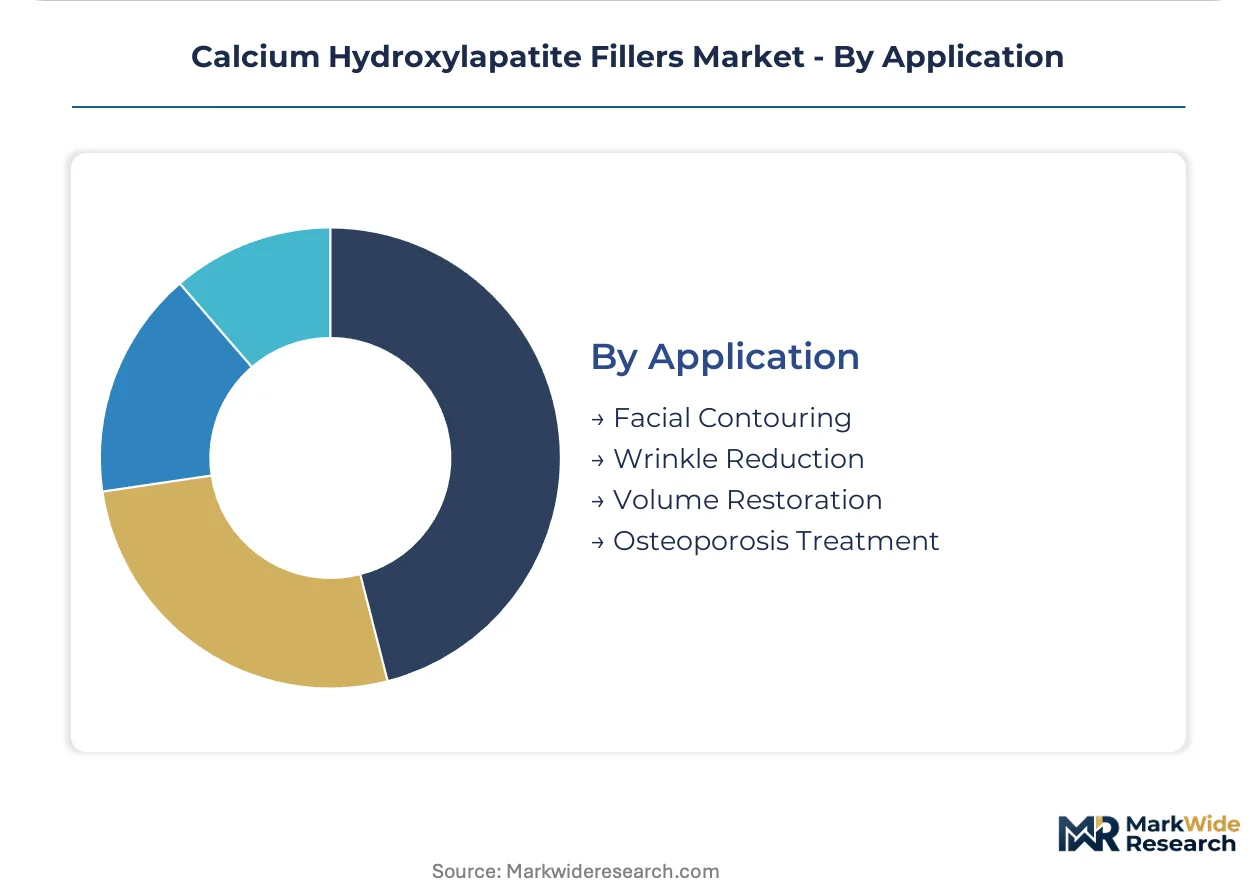
Application:
Clinical indication determines regulatory classification intensity, with therapeutic osteoporosis applications triggering pharmaceutical-grade evidence requirements absent from cosmetic volume restoration claims.
- Facial Contouring:Jawline and cheek augmentation applications command premium positioning where formulation purity and sustained duration claims support elevated pricing. German and Spanish aesthetic clinic chains are accelerating procurement of enhanced carrier gel formulations.
- Wrinkle Reduction:Nasolabial fold correction represents the most established indication with predicate device pathways streamlining FDA 510(k) submissions. Patient retention rates exceed hyaluronic acid alternatives due to extended treatment intervals.
- Volume Restoration:HIV-associated facial lipoatrophy and age-related fat pad atrophy drive medical necessity claims with stronger reimbursement support than purely cosmetic applications.
- Osteoporosis Treatment:Injectable bone substitutes for vertebral compression and fragility fractures face the most demanding clinical evidence requirements, with trials spanning multiple years for regulatory authorization.
Wrinkle reduction holds the volume lead, while facial contouring gains share fastest as injector technique sophistication expands treatable anatomical zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized injector training programs concentrate in metropolitan medical education corridors across multiple continents, anchoring regional demand patterns for calcium hydroxylapatite formulations.
United States
Coastal dermatology chains in Los Angeles and New York metropolitan areas drive procurement volume through private equity-backed consolidation. FDA 510(k) pathway clarity accelerates compliant product introductions while filtering substandard competitors. Miami and Dallas aesthetic hubs expand certified practitioner programs to meet multi-site clinic staffing requirements.
Germany
Aesthetic clinic chains in Berlin and Munich accelerate procurement of lidocaine-integrated carrier gel formulations. EMA Medical Device Regulation imposes clinical evidence burdens and notified body bottlenecks on legacy product portfolios. The Frankfurt-Rhine-Main corridor concentrates high-purity microsphere distribution infrastructure.
South Korea
Seoul-Incheon corridor manufacturers scale biocompatible ceramic synthesis capabilities to reduce import dependency. MFDS quality management requirements add territorial gatekeeping complexity for foreign suppliers. Busan-Ulsan research clusters anchor domestic production of facial contouring formulations.
Brazil
Maxillofacial specialists in São Paulo and Rio de Janeiro adopt ceramic-based bone graft substitutes as autograft harvesting declines. ANVISA biocompatibility testing protocols shape product registration timelines. The Southeast region concentrates oral surgery training programs driving technical adoption.
China
Cosmetic clinics in Shanghai and Beijing metropolitan areas seek longer-lasting facial rejuvenation alternatives to hyaluronic acid. NMPA biocompatibility testing protocols and dual carbon goals influence manufacturing investment decisions. The Yangtze River Delta anchors domestic filler formulation capabilities.
Calcium Hydroxylapatite Fillers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated vendor landscape. European manufacturing footprints dominate high-purity microsphere production, while Asian research clusters incubate ceramic synthesis capabilities. Three archetypes anchor competitive positioning: integrated biocompatible material science specialists, established pharmaceutical-device hybrids with regulatory navigation expertise, and regional champions leveraging domestic certification advantages. Capacity expansion in carrier gel engineering and strategic partnerships for distribution channel innovation represent the dominant competitive moves.
Within the European manufacturing tier, Merz Pharma and BioScience GmbH exemplify pharmaceutical-device hybrid archetypes with regulatory navigation capabilities. CGBio Co. Ltd anchors the Asian specialist tier, representing integrated biocompatible material science capabilities rooted in South Korean research infrastructure. These three entities occupy distinct competitive positions without overlapping geographic or technological footprints.
| Leading Market Players |
|---|
| Dr. Korman Laboratories |
| Sinclair Pharma |
| Merz Pharma |
| BioScience GmbH |
| Suneva Medical Inc |
| CGBio Co. Ltd |
| Prollenium Medical Technologies Inc |
| IMEIK Technology Development Co. |
| Cytophil Inc |
| Others |
Value Network & Pricing Analysis
Cross-linked carboxymethylcellulose carrier gel engineering simultaneously compresses manufacturing cost curves and concentrates formulation expertise among European and South Korean production clusters. This technological transition rewards scaled manufacturers with proprietary synthesis protocols while fragmenting price-setting power across regional certification tiers.
Pricing Analysis
Bundled toxin-and-filler procurement agreements dominate metropolitan cosmetic clinic purchasing, while independent practices negotiate unbundled per-unit pricing. Three-tier pricing structure across premium lidocaine-integrated, standard aqueous gel, and economy bone graft formulations reflects certification grade and sustained duration claims. Pricing pressure stems from multi-site dermatology chains extracting volume guarantees that compress supplier margins. Private equity-backed aesthetics platforms demonstrate lowest price sensitivity; independent oral surgery practices in Brazil and Mexico show highest.
Supply Chain Analysis
Temperature-controlled freight costs for aqueous gel formulations constrain distribution radius economics and reinforce regional manufacturing footprints. High-purity calcium phosphate microsphere production concentrates in Germany, South Korea, and the United States. Synthetic precursor sourcing draws from phosphate rock mining operations in Morocco and China, with energy-intensive calcination tethered to natural gas pricing. Single-source vulnerability persists in European Union high-purity microsphere capacity. Distribution runs through medical device distributors facing disintermediation from direct-to-clinic e-procurement platforms in Australian and Canadian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where patient retention through extended treatment intervals shifts demand toward premium biostimulatory formulations with validated collagen neogenesis claims.
For Market Incumbents: Deepen backward integration into synthetic calcium phosphate precursor production to buffer input cost volatility from phosphate rock mining fluctuations. Prioritize EMA MDR clinical evidence investments to defend legacy product portfolios against notified body bottlenecks that threaten European market access. Capacity expansion in Seoul-Incheon ceramic synthesis clusters captures regional procurement consolidation. For New Entrants and Emerging Players: Enter via Brazilian and Mexican maxillofacial surgery segments where ceramic bone graft substitute adoption accelerates and regulatory pathways remain less congested than aesthetic filler categories. Target oral surgery training program partnerships as the most penetrable channel given declining autograft harvesting trends. Pursue ANVISA biocompatibility certification as the critical go-to-market enabler. For Investors and Strategic Acquirers: Valuations sit cheapest among integrated biocompatible material science specialists with captive ceramic synthesis capabilities and MFDS or NMPA domestic certification advantages. Long-term viability hinges on formulation science differentiation rather than commodity microsphere production. Watch for inflection signals in direct-to-clinic e-procurement platform penetration rates that reshape distributor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Lidocaine-Integrated Carrier Gel Development | German and Spanish clinic chains accelerate procurement cycles for pain-reduced injection protocols. |
| EMA MDR Clinical Evidence Investment | Legacy injectable fillers face twelve-to-eighteen month timeline extensions for European Economic Area re-registration. |
| Seoul-Based Ceramic Synthesis Scale-Up | Domestic South Korean manufacturers reduce import dependency through Busan-Ulsan research cluster expansion. |
| Brazilian Maxillofacial Surgeon Training Programs | Southeast region oral surgery adoption of ceramic bone substitutes displaces autograft harvesting volume. |
| Direct-to-Clinic E-Procurement Platform Launch | Australian and Canadian metropolitan markets disintermediate traditional medical device distributor relationships. |
Research Methodology
Bottom-up cosmetic clinic procurement modeling reconciled against top-down calcium phosphate microsphere production tracking forms the analytical core. Primary interviews with dermatology chain purchasing directors, oral surgery training program directors, biomedical engineers at ceramic synthesis facilities, and GPO contracts managers combined with secondary validation. FDA 510(k) filings, EMA MDR submission databases, MFDS quality management registrations, and ANVISA biocompatibility testing records anchor supply-side verification. Customs data on synthetic calcium phosphate precursor trade flows and hospital procurement database extracts complete demand-side triangulation.
Input-output matrices map particle size distribution capabilities to end-use application requirements across the projection horizon. Segmentation dimensions include product type, end user archetype, delivery mode, and application indication, with regional regulatory cluster as the industry-specific overlay. CAGRs derive from fitted growth curves against validated base-year consumption estimates. Forecast inputs incorporate certified practitioner program expansion rates and private equity-backed clinic consolidation velocity.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time multi-site chain contract terms introduce uncertainty bands around vendor concentration estimates. Forecasts reflect documented assumptions on EMA MDR implementation timelines and MFDS enforcement intensity. Model refresh is warranted upon material change in FDA 510(k) pathway clarity or notified body capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Dental Polymerization Lamps Market
Dental Materials
Dental Plaster Market
Dental Materials
Fluoride Mouthwash Market
Dental Materials
Dental Materials for 3D Printing Market
Dental Materials
Dental Fluoride Varnish Market
Dental Materials
Dental Fiber Posts Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Dental Resins Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Zirconia Powder Market
Dental Materials
Acrylic Dental Material Market
Dental Materials
Dental Amalgam Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Dental Bleaching Materials Market
Dental Materials
Dental Bonding Agent Market