
 Fluoride Materials Market | 2026-2036
Fluoride Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoride Materials Market Foresight
Semiconductor fabricators is consolidating as the fastest-expanding end-user category, displacing traditional metal foundry offtake. Solvay S.A. sustains European supply leadership through captive fluorspar refining and pharmaceutical-grade certification. Daikin Industries Ltd. leverages vertical fluoropolymer integration to anchor premium electronics chemical pricing. Honeywell competes in North American optical coatings through specialized magnesium fluoride deposition precursors.
Fluoride materials encompass inorganic compounds containing the fluorine anion, typically manufactured via neutralization of hydrofluoric acid with metal oxides or carbonates, yielding purity grades from technical to electronic-grade exceeding 99.99%. These compounds serve as essential reagents in aluminum electrolysis, lithography etchants, and anti-reflective thin-film deposition. Calcium fluoride dominates volume through sustained aluminum smelter demand, while potassium fluoride and ammonium fluoride capture margin pools in semiconductor wet processing. Optical coatings applications mature with stable pricing, whereas electronics manufacturing segments attract capacity expansion due to wafer fab buildouts.
China's MEE enforces fluorochemical discharge limits that elevate capital requirements for domestic producers. The EPA regulates fluoride emissions from aluminum production under Clean Air Act provisions, shaping product formulation standards in U.S. operations. REACH and RoHS compliance in Europe restricts certain fluoride impurities in electronics supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to optimize manufacturing location and certification investment.
Market Dynamics
Semiconductor wet processing is displacing aluminum smelting as the dominant demand driver, compressing traditional volume-margin relationships while elevating purity certification requirements across the supply base.
Growth Catalysts
- GB Standards Tightening:China's evolving national standards on fluorochemical emissions are forcing domestic producers to upgrade purification infrastructure, creating captive demand for high-grade fluoride precursors in East China manufacturing clusters.
- Etchant Chemistry:Advanced node lithography below 7nm is consuming ammonium fluoride and buffered oxide etchants at intensified rates, pulling material specifications toward electronic-grade thresholds.
- East China Concentration:The Yangtze River Delta chemical manufacturing corridor serves both domestic wafer fabs and export-oriented aluminum smelters, generating scale economies in fluoride processing infrastructure.
Market Restraints
- Fluorspar Supply Concentration:Acid-grade fluorspar mining concentrates in Mongolia and Mexico, exposing processors to concentrate availability shocks and freight cost volatility.
- Hydrofluoric Acid Handling:Technical constraints around anhydrous HF transport and storage limit facility siting options, particularly in dense urban manufacturing zones.
- REACH Compliance Burden:European chemicals registration requirements impose documentation and testing costs that disproportionately burden smaller specialty fluoride compound producers.
Strategic Opportunities
- India Electronics Manufacturing:The country's PLI scheme for semiconductor and display fabrication is attracting greenfield chemical processing investments to serve emerging domestic wafer capacity.
- Optical Thin-Film Convergence:Magnesium fluoride and lanthanum fluoride deposition precursors are capturing expanded use in augmented reality waveguide manufacturing.
- Dual Carbon Policy Tailwind:China's national carbon neutrality targets are accelerating aluminum smelter technology upgrades that favor high-purity fluoride bath chemistry for energy efficiency.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:USP and EP compliance for fluoride excipients requires 18-24 month validation cycles that delay market entry for new production facilities.
- Semiconductor Supply Chain Reconfiguration:Geographic diversification of wafer fab capacity is fragmenting previously consolidated chemical supply relationships, forcing multi-site qualification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoride Materials Market |
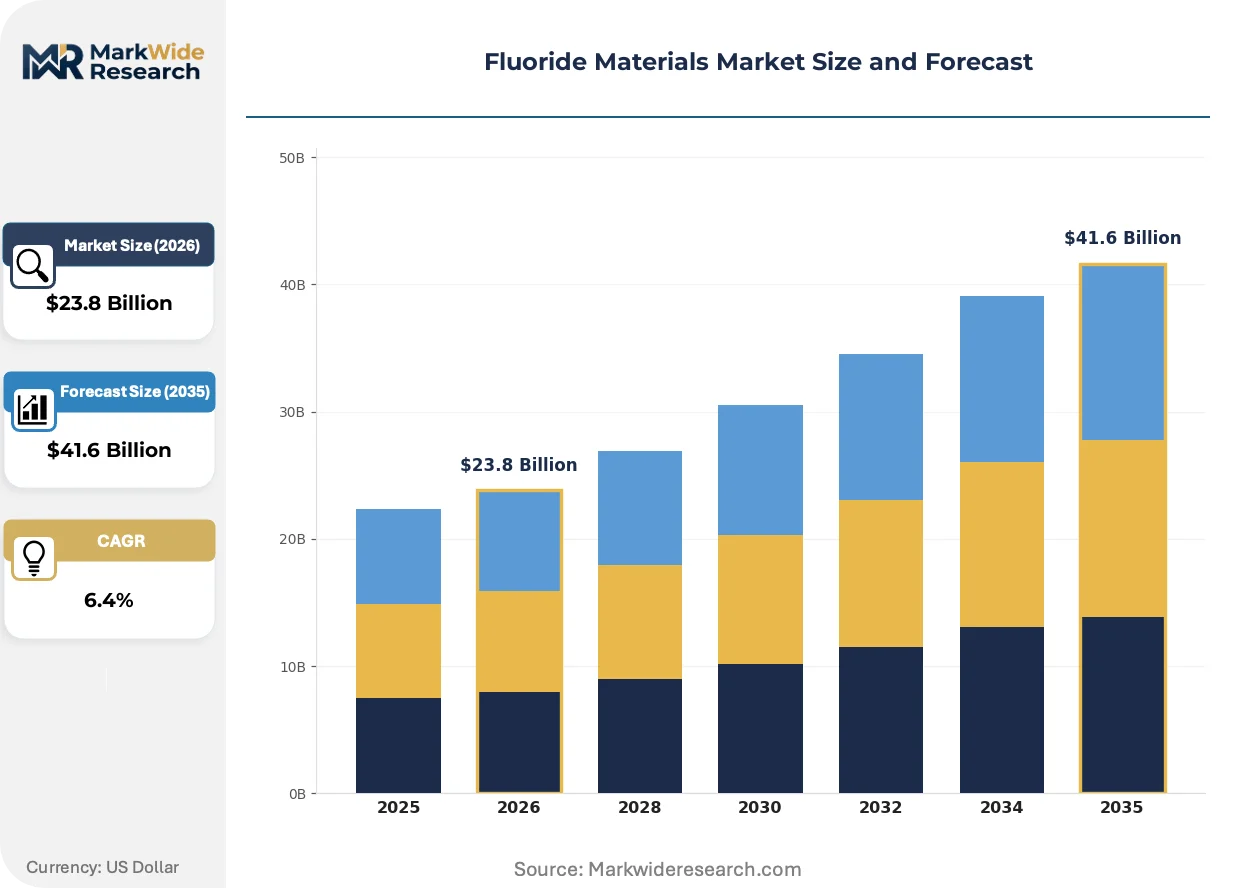
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Fluoride, Sodium Fluoride, Potassium Fluoride, Ammonium Fluoride, Magnesium Fluoride Application: Aluminum Production, Optical Coatings, Water Treatment, Pharmaceuticals, Electronics Manufacturing End User: Metal Foundries, Chemical Manufacturers, Water Utilities, Specialty Glass Producers, Semiconductor Fabricators Packaging Type: Bulk Bags, Drums, Fiberboard Boxes, Plastic Containers, Loose Powder Packaging |
| Companies Covered | Arkema S.A., Daikin Industries Ltd., Solvay S.A., Chemours Company, Kureha Corporation, Do-Fluoride Chemicals, Honeywell, Shanghai Ofluorine Chemical Technology Co. Ltd., Dyneon GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoride Materials Market Shifts & Advancements
Fluoride material specifications are bifurcating between commodity aluminum-grade volumes and hyper-purity electronic-grade premiums, with processing technology becoming the primary competitive differentiator.
Gas-phase fluoride precursors for atomic layer deposition are integrating into advanced node manufacturing workflows. Leading memory and logic fabricators in Taiwan and South Korea are adopting tungsten hexafluoride and nitrogen trifluoride alternatives for conformal thin-film applications. This integration is compressing liquid-phase chemical consumption per wafer while elevating gas handling infrastructure requirements across the supply chain.
EPA Clean Air Act provisions on fluoride emissions from primary aluminum production are tightening discharge thresholds. Smelters in the US Gulf Coast and Pacific Northwest are retrofitting scrubber systems and reformulating bath chemistry to reduce perfluorocarbon releases. Bath-grade cryolite and aluminum fluoride suppliers are responding with modified particle size distributions that improve capture efficiency without disrupting electrolytic performance.
Direct procurement relationships between semiconductor fabricators and fluoride compound producers are consolidating channel structures. Long-term offtake agreements with minimum purity guarantees are displacing spot market transactions for electronic-grade materials. This pattern is most visible in Taiwan's Hsinchu Science Park and South Korea's Yongin cluster, where captive chemical supply has become a condition of advanced process node qualification.
Fluoride Materials Market Segmentation
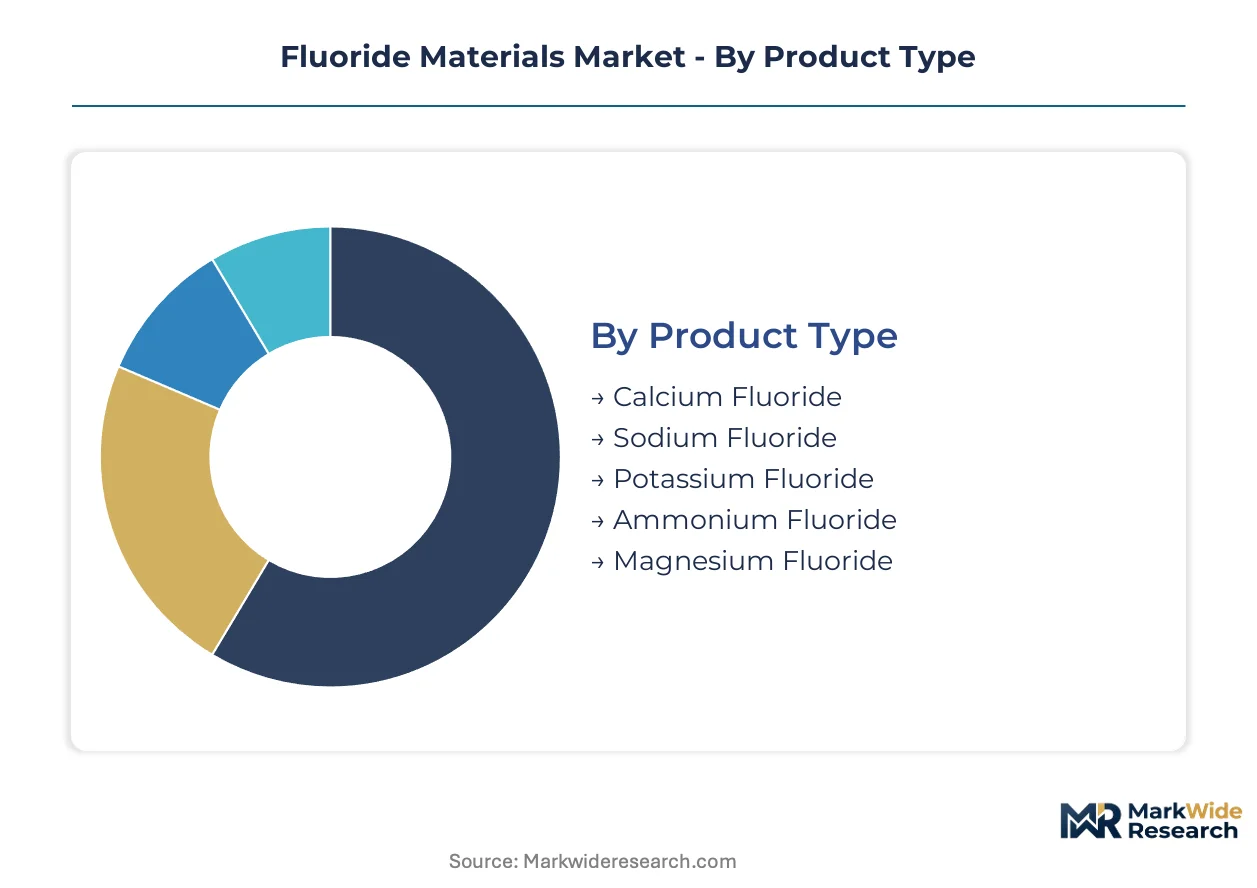
Fluoride material specifications diverge sharply across end-use applications, with aluminum smelters tolerating technical-grade impurities while semiconductor fabricators demand electronic-grade purity exceeding 99.99%. Understanding these tiered requirements illuminates why pricing spreads widen dramatically within the same chemical family.
Product Type:
Buyers in this category differentiate primarily by the purity threshold their process tolerates, with electronic-grade specifications commanding substantial premiums over technical grades.
- Calcium Fluoride:Technical-grade calcium fluoride serves aluminum electrolysis bath chemistry, where particle size distribution matters more than trace metal content. East China's smelter clusters consume captive volumes through integrated fluorspar processing. Dual carbon policy targets are accelerating bath reformulations that favor high-purity grades for energy efficiency gains.
- Ammonium Fluoride:Buffered oxide etchants for sub-7nm lithography pull specifications toward ultra-high purity with stringent metallic impurity controls. Taiwan's Hsinchu Science Park and South Korea's Yongin cluster anchor demand through direct procurement relationships with qualified suppliers.
- Potassium Fluoride:Electronics wet processing applications favor this compound for controlled etch rates in wafer cleaning sequences.
- Sodium Fluoride:Municipal water fluoridation programs and dental applications drive steady offtake with pharmacopeia compliance requirements.
- Magnesium Fluoride:Anti-reflective thin-film deposition precursors serve optical coatings and emerging augmented reality waveguide manufacturing.
Calcium fluoride leads volumes today; ammonium fluoride is gaining share fastest.
Application:
Application selection correlates with margin capture potential, with semiconductor processing commanding price multiples over mature industrial uses.
- Electronics Manufacturing:Wafer fab buildouts in Taiwan, South Korea, and India are consuming electronic-grade fluorides at intensified rates. Advanced node lithography below 7nm requires ammonium fluoride and specialized etchants with metallic impurity specifications below parts-per-billion thresholds. Long-term offtake agreements with purity guarantees now displace spot market transactions.
- Aluminum Production:Primary smelters in the US Gulf Coast and Pacific Northwest reformulate bath chemistry to meet EPA Clean Air Act fluoride emission thresholds. Cryolite and aluminum fluoride suppliers are modifying particle size distributions to improve scrubber capture efficiency without disrupting electrolytic performance.
- Optical Coatings:Magnesium fluoride and lanthanum fluoride deposition precursors serve anti-reflective thin-film applications with stable, mature pricing dynamics.
- Water Treatment:Municipal fluoridation programs sustain steady sodium fluoride demand with pharmacopeia-grade certification requirements.
- Pharmaceuticals:USP and EP compliance for fluoride excipients imposes 18-24 month validation cycles that delay market entry for new production facilities.
Aluminum production retains volume dominance; electronics manufacturing exhibits the steepest expansion trajectory.
End User:
End-user procurement power determines contract structure, with semiconductor fabricators extracting multi-year supply guarantees while metal foundries transact on spot markets.
- Semiconductor Fabricators:Taiwan's TSMC and Samsung's foundry operations qualify suppliers through rigorous multi-site validation protocols. Captive chemical supply has become a condition of advanced process node certification, consolidating channel structures around direct procurement relationships.
- Metal Foundries:Aluminum smelters in East China and the US Gulf Coast purchase technical-grade fluorides through distributors with limited purity specifications.
- Chemical Manufacturers:Intermediate processors in the Yangtze River Delta convert acid-grade fluorspar into derivative compounds for downstream electronics and metallurgical applications.
- Water Utilities:Municipal procurement of sodium fluoride follows public health regulatory frameworks with price-sensitive tender processes.
- Specialty Glass Producers:Optical fiber and precision lens manufacturers source high-purity fluorides for refractive index control.
Metal foundries anchor current volume; semiconductor fabricators are climbing the fastest.
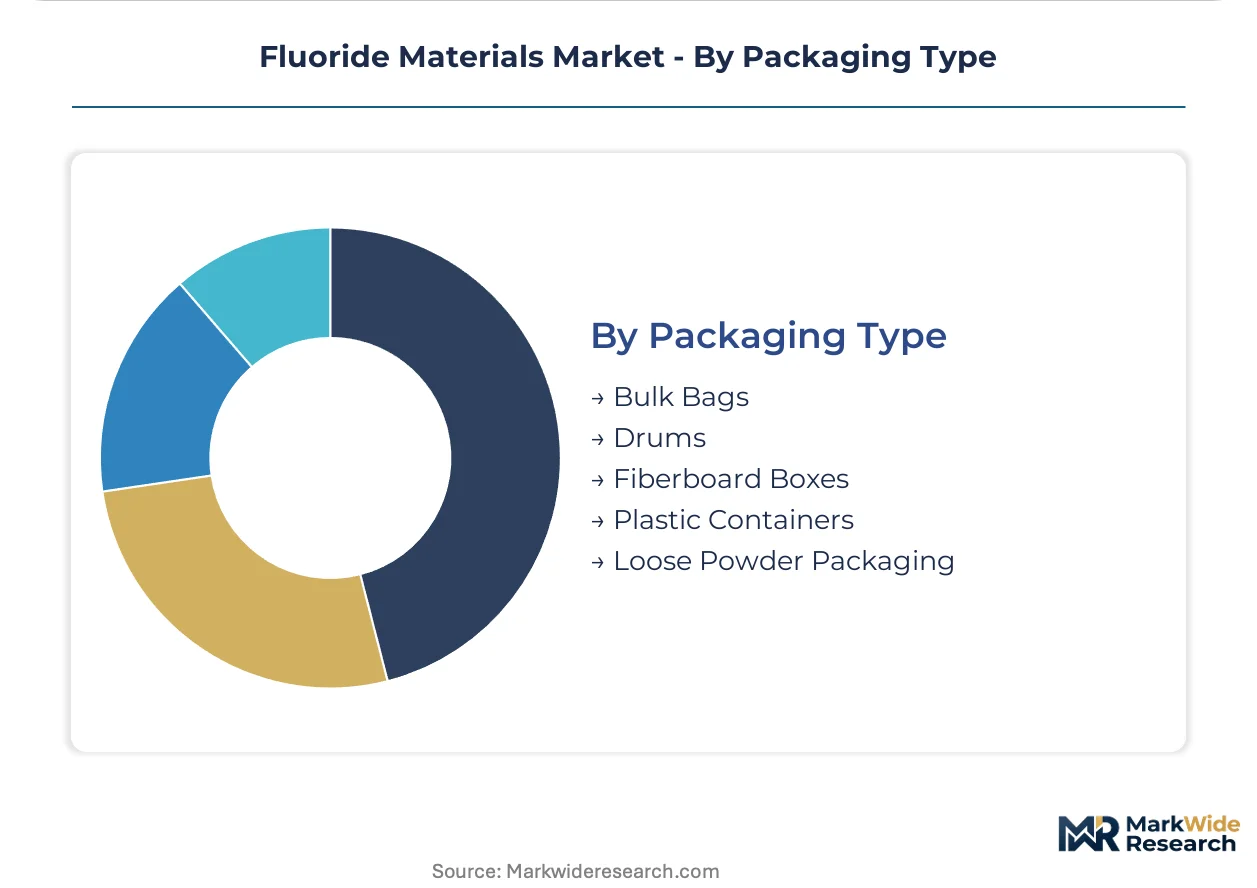
Packaging Type:
Packaging selection reflects hazard classification and handling infrastructure, with anhydrous and high-purity grades requiring specialized containment systems.
- Drums:Stainless steel and fluoropolymer-lined drums contain electronic-grade liquids and hygroscopic solids for semiconductor chemical supply chains. Cleanroom-compatible drum designs with particle-controlled filling protocols support wafer fab delivery requirements in Taiwan and South Korea.
- Bulk Bags:Technical-grade calcium fluoride for aluminum smelters moves via flexible intermediate bulk containers with standard liner configurations.
- Fiberboard Boxes:Laboratory and pharmaceutical quantities of sodium fluoride ship in UN-certified fiberboard with moisture barriers.
- Plastic Containers:Water treatment chemicals and mid-volume industrial grades utilize HDPE containers with tamper-evident closures.
- Loose Powder Packaging:Captive integrated operations receive bulk powder via pneumatic transfer systems without intermediate packaging.
Bulk bags dominate aluminum industry shipments; drums capture the premium electronics segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting fluoride materials investment toward jurisdictions where compliance costs align with end-market proximity. Producers are relocating purification capacity to exploit gaps between emission enforcement stringency and semiconductor cluster density.
China
East China's Yangtze River Delta chemical corridor supplies both domestic wafer fabs and export aluminum smelters with captive fluoride processing. NMPA and evolving GB standards on fluorochemical emissions are forcing purification infrastructure upgrades across manufacturing clusters. Shanghai Ofluorine Chemical Technology and Do-Fluoride Chemicals anchor supply relationships with local semiconductor fabricators.
United States
EPA Clean Air Act provisions on fluoride emissions from primary aluminum production are driving bath chemistry reformulations in Gulf Coast and Pacific Northwest smelters. Honeywell maintains optical coatings supply positioning through specialized magnesium fluoride precursors. Texas and Arizona chemical processing infrastructure serves domestic semiconductor buildouts with electronic-grade material qualification.
South Korea
Yongin cluster semiconductor fabricators are consolidating direct procurement relationships with fluoride compound producers for advanced node manufacturing. MFDS pharmaceutical-grade certification requirements govern excipient applications with extended validation timelines. Daikin Industries leverages regional fluoropolymer integration to anchor premium electronics chemical positioning.
Germany
REACH and RoHS compliance frameworks restrict fluoride impurities in electronics supply chains entering European markets. Dyneon GmbH & Co. KG represents fluoropolymer specialist positioning within regional chemical manufacturing. Bavarian and North Rhine-Westphalia industrial corridors maintain aluminum smelter demand alongside precision optics manufacturing.
Japan
Kureha Corporation exemplifies domestic specialty fluoride production serving memory and logic fabricator requirements. METI industrial policy supports gas-phase precursor development for atomic layer deposition workflows. Kyushu and Chubu regional chemical infrastructure balances semiconductor supply with mature optical coatings demand.
Fluoride Materials Market Competitive Landscape
Capacity expansion dominates the current landscape as electronic-grade demand outstrips qualified supply. The vendor base separates into three tiers: integrated fluorspar-to-fluoropolymer conglomerates, mid-scale specialty fluoride compounders, and regional aluminum-grade processors. European and Japanese incumbents occupy premium certification positions, while Chinese producers scale purification capabilities. Competitive moves concentrate on captive fluorspar securing and multi-site semiconductor qualification.
Among European-headquartered suppliers, Solvay S.A. represents integrated fluorspar refining with pharmaceutical-grade certification capabilities. Daikin Industries occupies the vertical fluoropolymer integration archetype, anchoring premium electronics chemical pricing through in-house tetrafluoroethylene production. Honeywell exemplifies North American specialization in optical coatings precursors, particularly magnesium fluoride deposition materials for anti-reflective applications.
| Leading Market Players |
|---|
| Arkema S.A. |
| Daikin Industries Ltd. |
| Solvay S.A. |
| Chemours Company |
| Kureha Corporation |
| Do-Fluoride Chemicals |
| Honeywell |
| Shanghai Ofluorine Chemical Technology Co. Ltd. |
| Dyneon GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Semiconductor fabricator procurement consolidation in Taiwan's Hsinchu Science Park and South Korea's Yongin cluster anchors long-term offtake contracting as the dominant pricing model. Direct qualification relationships compress distributor margins for electronic-grade materials while aluminum smelters transact through spot markets with freight-adjusted pricing.
Pricing Analysis
Distributor margins collapse in semiconductor supply chains as fabricators enforce direct procurement with multi-year purity guarantees. Electronic-grade ammonium fluoride commands substantial premiums over technical-grade calcium fluoride based on metallic impurity thresholds and GB standards compliance. Cost compression in aluminum-grade segments intensifies due to dual carbon policy efficiency mandates. Metal foundries exhibit highest price sensitivity; memory and logic fabricators prioritize supply security over unit cost.
Supply Chain Analysis
Acid-grade fluorspar supply rests on Mongolian and Mexican mining concentration, exposing processors to concentrate availability shocks. Hydrofluoric acid production draws from Chinese and Mexican fluorspar beneficiation capacity, with anhydrous HF transport constraints limiting facility siting options. Single-source vulnerability concentrates in East China's Yangtze River Delta chemical corridor. Distribution runs through stainless steel drum networks for electronics-grade materials and flexible intermediate bulk containers for smelter volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoride materials investment functions as a geographic-arbitrage play exploiting gaps between China's MEE emission enforcement stringency and semiconductor cluster density in Taiwan and South Korea.
For Market Incumbents: To counter emerging Chinese purification capacity upgrades, Solvay S.A. and Daikin Industries should deepen backward integration into captive fluorspar refining and accelerate multi-site semiconductor qualification across India's PLI-driven fabrication zones. Certification investment in USP and EP pharmaceutical-grade standards creates defensive moats against commodity-grade entrants. For New Entrants and Emerging Players: Capture India's electronics manufacturing expansion through greenfield chemical processing investments serving domestic wafer capacity buildouts. The country's PLI scheme for semiconductor fabrication represents the most penetrable demand pocket. Position through direct procurement relationships with emerging foundry operations rather than distributor channel penetration. For Investors and Strategic Acquirers: Specialty chemical conglomerates with fluoropolymer integration capabilities are the most active acquirer in this space, seeking electronic-grade purification assets. Long-term viability hinges on qualification relationships with advanced node fabricators. Watch for NMPA enforcement actions against non-compliant Chinese producers as the inflection indicator for supply reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Captive concentrate supply secures margin control against Mongolian export volatility. |
| Electronic-Grade Purification Capacity Expansion | GB standards tightening in East China forces infrastructure upgrades for compliant production. |
| Multi-Site Semiconductor Qualification | Direct procurement relationships with TSMC and Samsung consolidate channel structures. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance creates 18-24 month barriers against commodity competitors. |
| Joint Venture in India Electronics Corridor | PLI scheme incentives attract greenfield chemical processing for emerging wafer capacity. |
Research Methodology
Multiple input streams — procurement directors at semiconductor fabricators, technical R&D leads at fluoride compounders, and distribution channel partners — were reconciled against customs trade data, SEC 10-K filings, and NMPA regulatory disclosures. Primary interviews with aluminum smelter bath chemistry specialists and optical coatings manufacturers were cross-validated through secondary sources. Bottom-up volume modeling and top-down market sizing were triangulated to converge estimates.
Historical capacity utilization patterns were cross-referenced against panel input from plant managers and procurement leads to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry vertical, packaging format, and regional production hub. CAGRs were derived from supply-demand balance projections incorporating wafer fab buildout schedules and aluminum smelter technology upgrade cycles.
Regulatory enforcement shifts, fluorspar concentrate supply disruptions, and semiconductor capital expenditure revisions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around GB standards implementation timelines and EPA Clean Air Act compliance trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Amalgam Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Global Endodontic Consumables Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Cold Light Teeth Whitening Kit Market
Dental Materials
Toothpaste Market
Dental Materials
Global Dental Membrane and Bone Graft Substitutes Market
Dental Materials
Tooth Filling Materials Market
Dental Materials
Oral Bone Implant Material Market
Dental Materials
Calcium Hydroxylapatite Fillers Market
Dental Materials
Dental Impression Material Market
Dental Materials
Dental Biomaterials Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Restorative and Regenerative Material Market
Dental Materials
Dental Resins Market
Dental Materials
Zirconia Based Dental Ceramics Market