
 Dental Polymerization Lamps Market | 2026-2036
Dental Polymerization Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Polymerization Lamps Market Outlook
Private dental clinics is collapsing the historical dominance of hospital procurement channels for polymerization lamps. Dentsply Sirona Inc. leverages its integrated digital dentistry platform to control distribution across North American and European dental practices. Ivoclar Vivadent AG anchors its position through deep specialization in adhesive curing systems tied to its consumables portfolio. Ultradent Products Inc. differentiates via high-intensity LED platforms designed for orthodontic bracket bonding workflows.
Dental polymerization lamps are handheld or countertop devices that emit calibrated light energy, typically in the 450-470 nanometer blue spectrum, to photoinitiate resin polymerization in restorative and orthodontic procedures. LED lamps now dominate product type segmentation due to superior energy efficiency, reduced heat generation, and extended emitter lifespans compared to legacy halogen and plasma arc alternatives. Within usage segmentation, cosmetic dentistry represents the fastest-expanding application as patient-funded veneer and composite procedures proliferate in private practice settings. Power rating segmentation shows medium-power units capturing the broadest addressable base, though ultra-high-power systems command premium positioning for bulk-fill resin protocols.
The FDA regulates these devices as Class II medical devices under 21 CFR 872.6070, requiring 510(k) premarket notification for light-curing equipment with modified energy outputs. The EU Medical Device Regulation (MDR) imposes stricter clinical evaluation and post-market surveillance obligations on manufacturers selling into European dental markets. ISO 4049 standards govern the acceptance criteria for polymerization depth and degree of conversion in restorative resins, directly shaping lamp performance specifications that manufacturers must meet. Stakeholders must monitor how evolving biocompatibility testing requirements under revised ISO 10993 frameworks will cascade into updated curing protocol validations and device labeling obligations.
Market Dynamics
LED curing technology is displacing halogen and plasma arc systems as the dominant photopolymerization platform, compressing equipment lifecycles and forcing manufacturers to redirect R&D budgets toward emitter efficiency and thermal management.
Growth Catalysts
- EU F-Gas Regulation:Stricter energy-efficiency mandates accelerate manufacturer investment in low-power LED architectures and phase out mercury-containing lamp technologies.
- Cosmetic dentistry procedures:Patient-funded veneer and composite bonding workflows in private clinics drive replacement demand for high-intensity curing systems.
- German dental service consolidation:Concentrated procurement by multi-site practice chains standardizes on premium LED platforms with digital workflow integration.
Market Restraints
- Blue LED emitter supply concentration:Dominance of East Asian semiconductor foundries creates vulnerability in upstream component availability for lamp manufacturers.
- ISO 4049 compliance costs:Rigorous polymerization depth validation requirements extend product development timelines and certification expenses.
- Halogen lamp aftermarket persistence:Legacy equipment installed base in price-sensitive markets delays full technology transition and caps pricing power.
Strategic Opportunities
- Orthodontic bracket bonding workflows:Rising clear aligner and fixed appliance volumes create specialized demand for ultra-high-power portable curing systems.
- China dental clinic expansion:Tier-2 and tier-3 city network growth offers first-mover positioning for mid-power LED platforms with localized service support.
- EU MDR post-market surveillance data:Manufacturers leveraging real-world performance analytics can differentiate through predictive maintenance and outcome documentation services.
Industry Challenges
- Biocompatibility testing under ISO 10993:Evolving cytotoxicity and sensitization protocols require revalidation of curing protocols and updated device labeling.
- Digital dentistry platform integration:Lamp manufacturers must engineer seamless connectivity with intraoral scanners and CAD/CAM systems to maintain distribution access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Polymerization Lamps Market |
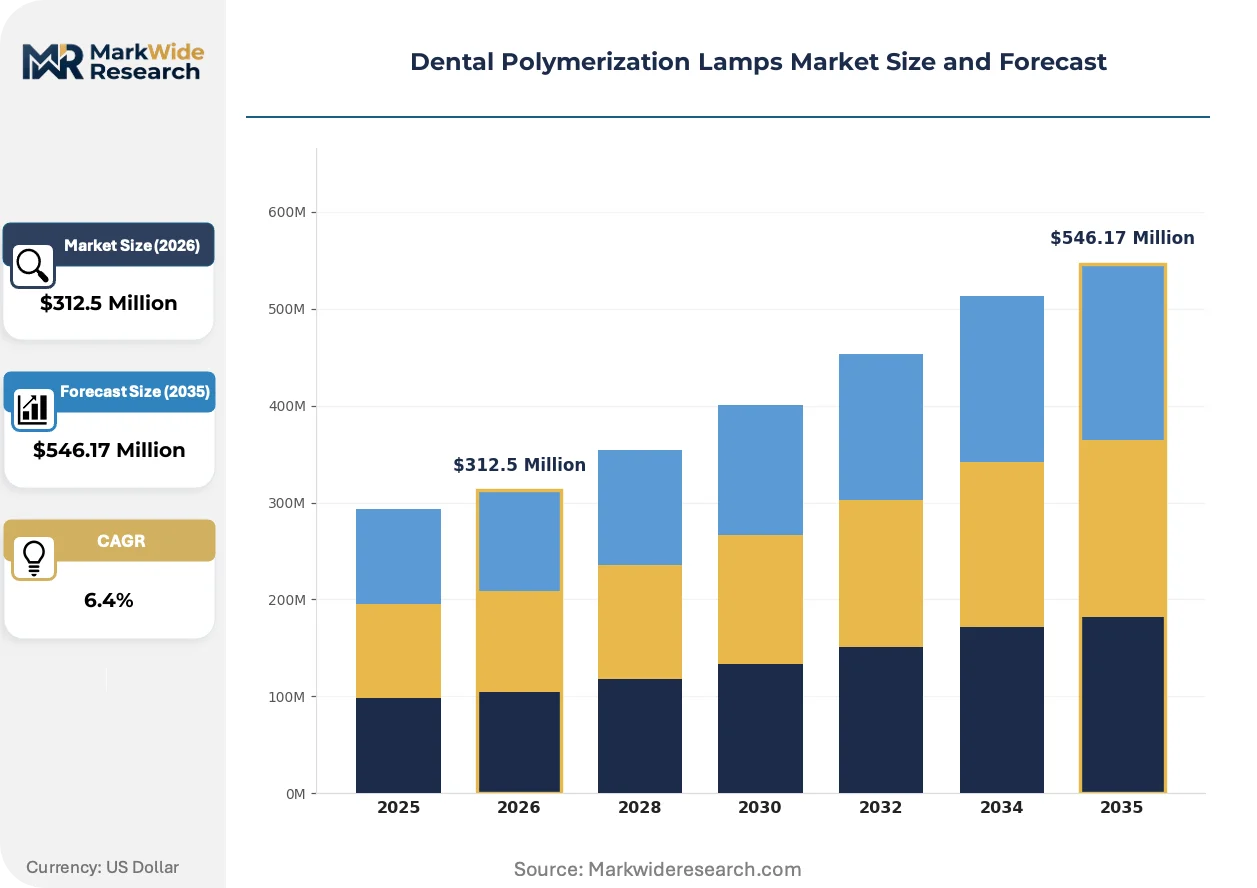
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lamps, Halogen Lamps, Plasma Arc Lamps, Laser Lamps Usage: General Dentistry, Orthodontics, Cosmetic Dentistry, Endodontics Power Rating: Low Power, Medium Power, High Power, Ultra High Power Connectivity: Wired, Wireless, Bluetooth, USB |
| Companies Covered | 3M Co., Dentsply Sirona Inc., Ivoclar Vivadent AG, A-dec Inc., COLTENE Holding AG, Ultradent Products Inc., VOCO GmbH, Kerr Corporation, Henry Schein Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Polymerization Lamps Market Strategic Shifts
Photopolymerization equipment is undergoing rapid platform transformation as solid-state emitter technology matures and regulatory pressure intensifies on legacy energy-inefficient systems.
Multi-peak LED arrays capable of dual-wavelength output are miniaturizing handheld lamp form factors while maintaining curing depth performance. Private dental clinics in Germany and the United States are adopting these compact units to free chairside space and reduce operator fatigue. The technology is compressing equipment replacement cycles as practices prioritize portability over legacy countertop systems.
The EU Medical Device Regulation imposes stricter clinical evaluation and post-market surveillance obligations on manufacturers selling into European dental markets. Device labeling must now incorporate detailed biocompatibility documentation and traceable production records. Medium-power lamp segments face the steepest compliance cost increases as volume manufacturers lack specialized regulatory affairs capacity.
Dental service organizations are consolidating procurement decisions at regional headquarters, stripping traditional distributors of their historical role in equipment selection. Multi-site practice chains in the United States now negotiate direct manufacturer relationships with standardized specification requirements. This concentration is most visible in Texas and Florida, where large dental support organizations command significant purchasing leverage.
Dental Polymerization Lamps Market Segmentation
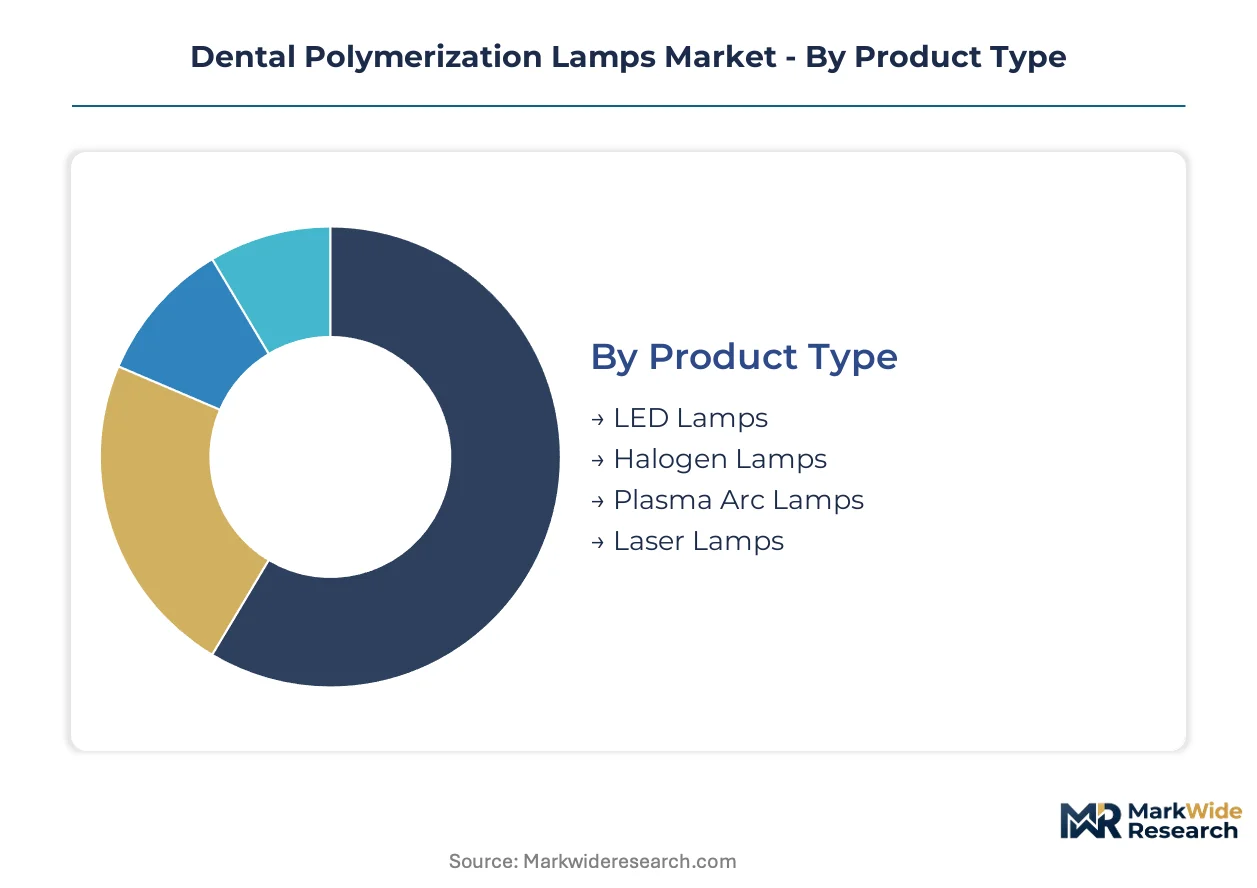
Segmentation in dental polymerization lamps reveals how regulatory pressure on energy efficiency and clinical workflow specialization are fragmenting demand across distinct performance tiers. Manufacturers must align R&D priorities with the specific compliance burdens and usage intensity profiles that govern each category.
Product Type:
FDA 510(k) requirements under 21 CFR 872.6070 and EU F-Gas Regulation mandates create divergent compliance pathways across emitter technologies, with energy-efficiency thresholds favoring solid-state architectures over legacy gas-discharge systems.
- LED Lamps:Solid-state blue spectrum emitters operating at 450-470 nanometers deliver calibrated photoinitiation with minimal thermal load. Private dental clinics in Germany and the United States are consolidating procurement around these platforms as EU efficiency mandates phase out mercury-containing alternatives.
- Halogen Lamps:Tungsten-filament broadband sources require higher wattage and generate substantial heat, extending curing cycles. Price-sensitive markets in Eastern Europe and Latin America maintain installed bases that delay full transition despite regulatory pressure.
- Plasma Arc Lamps:High-intensity discharge systems utilizing xenon plasma deliver rapid polymerization for bulk-fill protocols.
- Laser Lamps:Monochromatic coherent sources enable precise energy delivery for specialized adhesive systems.
LED Lamps handles the majority of throughput; Laser Lamps is the fastest mover on share.
Usage:
Procedure reimbursement patterns and patient out-of-pocket contribution levels stratify demand intensity across dental specialties, with cosmetic workflows commanding premium equipment specifications.
- General Dentistry:Restorative composite placement and sealant applications constitute the volume base. Medium-power LED units dominate chairside configurations in United States private practices where procedure throughput drives equipment utilization rates.
- Cosmetic Dentistry:Veneer bonding and aesthetic composite layering demand precise curing depth control and color stability. Patient-funded procedures in German and Chinese urban clinics are expanding fastest as aesthetic treatment acceptance rises.
- Orthodontics:Bracket adhesive curing for fixed appliances and clear aligner attachment protocols.
- Endodontics:Root canal obturation material polymerization and post cementation workflows.
General Dentistry anchors equipment volume; Cosmetic Dentistry is expanding most quickly on share.
Power Rating:
Energy output specifications correlate directly with resin formulation chemistry and clinical protocol requirements, creating tiered pricing architectures that match performance to procedure complexity.
- Medium Power:Output ranges of 800-1200 mW/cm² address the broadest procedure mix including standard composite restorations. This tier captures the largest addressable base as German dental service organizations standardize procurement specifications across multi-site networks.
- Ultra High Power:Intensities exceeding 2000 mW/cm² enable single-exposure curing of bulk-fill resins up to 4mm depth. United States orthodontic practices specializing in clear aligner workflows are driving fastest adoption for rapid attachment bonding.
- Low Power:Reduced output systems for pediatric applications and sensitive tissue protocols.
- High Power:Intermediate intensities for accelerated curing without thermal risk escalation.
Medium Power carries the broadest installed base; Ultra High Power is gaining share fastest.
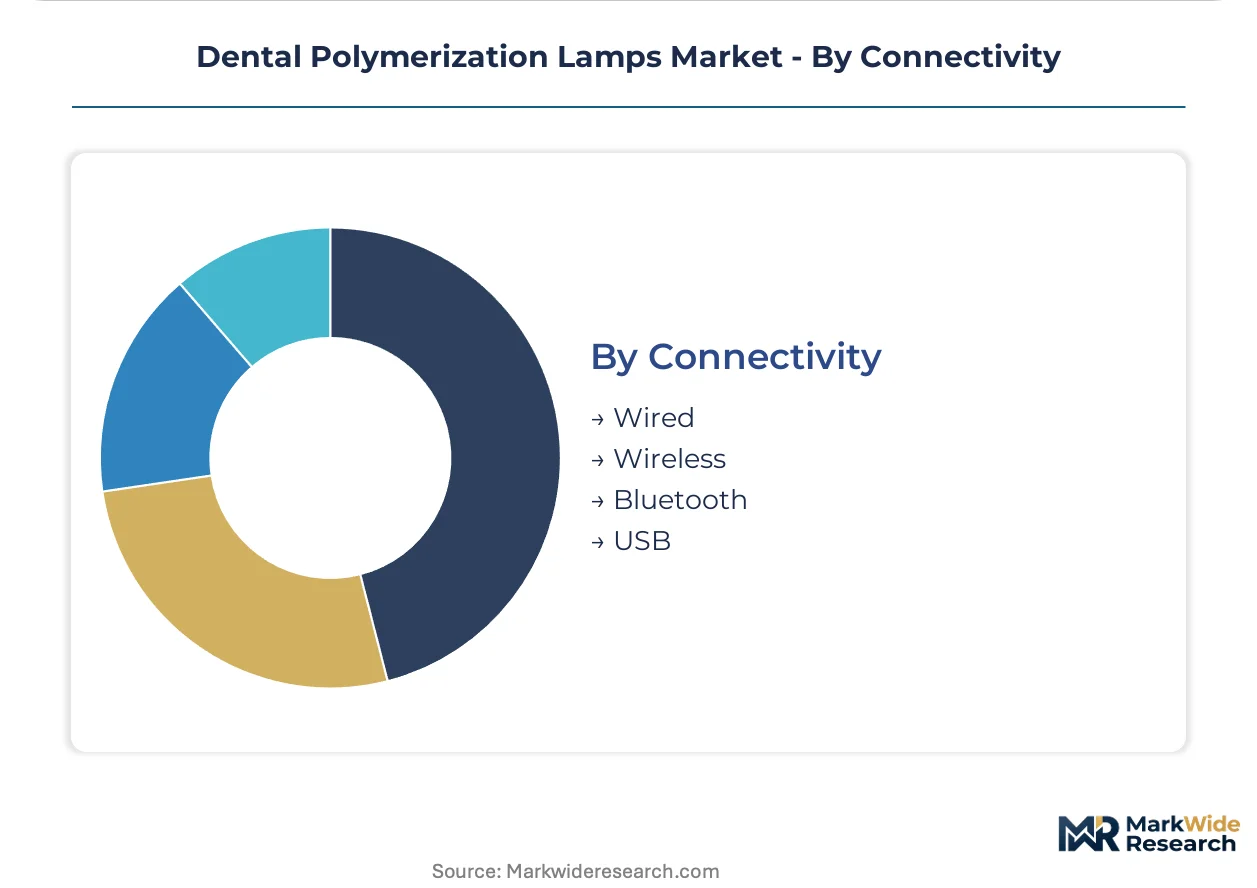
Connectivity:
Digital dentistry platform integration requirements are elevating connectivity from convenience feature to procurement prerequisite as practices consolidate around integrated workflow ecosystems.
- Wireless:Battery-powered operation with inductive charging eliminates tether constraints and improves operator ergonomics. United States private clinics are prioritizing these configurations to maximize chairside flexibility and reduce cable maintenance.
- Bluetooth:Protocol-enabled data exchange supports curing parameter logging and equipment tracking within practice management systems. German dental support organizations are mandating this capability for centralized asset monitoring across regional networks.
- Wired:Continuous power supply through corded connection maintains consistent output for high-volume procedures.
- USB:Direct digital interface for firmware updates and performance diagnostics.
Wireless dominates current procurement volumes; Bluetooth is climbing the fastest on adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private dental clinic chains now concentrate procurement power across the United States, Germany, and China, replacing hospital-based purchasing as the dominant buyer archetype in each market.
United States
Dental service organizations in Texas and Florida command regional purchasing leverage for high-intensity LED platforms. The FDA's 510(k) premarket notification under 21 CFR 872.6070 shapes equipment validation protocols. Greater Boston's dental technology corridor drives digital workflow integration requirements for curing lamp connectivity specifications.
Germany
Multi-site practice chains standardize procurement specifications across Bavaria and North Rhine-Westphalia for medium-power LED units. The EU F-Gas Regulation accelerates phase-out of mercury-containing lamp technologies. Stuttgart's precision manufacturing cluster supplies emitter thermal management components to lamp fabricators.
China
Tier-2 and tier-3 city clinic expansion drives replacement demand for mid-power LED platforms with localized service support. The National Medical Products Administration oversees Class II medical device registration for imported curing equipment. The Yangtze River Delta's dental consumables manufacturing base integrates lamp distribution into regional supply networks.
Japan
Aesthetic dentistry acceptance in Tokyo and Osaka metropolitan areas expands patient-funded veneer procedure volumes. The Pharmaceuticals and Medical Devices Agency enforces stringent clinical evaluation requirements for photopolymerization equipment. The Chubu region's Nagoya-based dental equipment distributors consolidate procurement for central Japan practice networks.
Switzerland
Swissmedic's medical device surveillance framework imposes rigorous post-market performance documentation obligations on lamp manufacturers. The Basel-Zurich corridor's precision optics industry supplies calibrated light measurement systems for curing validation. Geneva's private dental clinics prioritize wireless portable configurations for ergonomic chairside operation.
Dental Polymerization Lamps Market Competitive Environment
Player mix skews toward integrated dental equipment conglomerates with consumables portfolios, compressing standalone lamp specialists into niche positioning. Three to four multinational groups control distribution access through digital dentistry platform bundling. Strategic archetypes include full-workflow integrators, adhesive-system specialists, and high-intensity platform developers. Competitive moves center on R&D redirection toward emitter efficiency and direct procurement relationships with consolidating clinic chains.
Among North American and European equipment conglomerates, Dentsply Sirona Inc. and Ivoclar Vivadent AG exemplify contrasting strategic positions. Dentsply Sirona Inc. occupies a position as a full-workflow integrator leveraging digital dentistry platform control. Ivoclar Vivadent AG anchors the adhesive-system specialist archetype through curing technology tied to consumables portfolios. Ultradent Products Inc. represents the high-intensity platform developer tier focused on specialized orthodontic workflows.
| Leading Market Players |
|---|
| 3M Co. |
| Dentsply Sirona Inc. |
| Ivoclar Vivadent AG |
| A-dec Inc. |
| COLTENE Holding AG |
| Ultradent Products Inc. |
| VOCO GmbH |
| Kerr Corporation |
| Henry Schein Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) premarket notification requirements under 21 CFR 872.6070 and EU MDR clinical evaluation obligations simultaneously gate supply qualification and stratify price tiers across LED, halogen, and plasma arc platforms. Private dental clinics in Germany and the United States face divergent compliance cost burdens that manufacturers pass through as certification-grade pricing spreads.
Pricing Analysis
Next-generation multi-peak LED arrays command 40-60% premiums over legacy halogen units, while mid-power LED platforms occupy the volume-standard tier. Price differentiation rests on ISO 4049 compliance depth and wireless connectivity bundling. Cost compression in the halogen aftermarket intensifies as EU F-Gas Regulation deadlines approach. Price sensitivity concentrates in Eastern European and Latin American clinic networks still amortizing installed halogen bases.
Supply Chain Analysis
East Asian semiconductor foundries in Taiwan, South Korea, and China control blue LED emitter fabrication, creating single-source vulnerability for lamp manufacturers. German precision optics clusters and Swiss thermal management specialists feed downstream assembly. Tariff exposure on Chinese-sourced emitters disrupts cost planning for North American fabricators. Distribution runs through dental service organization procurement hubs that strip traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where predictive maintenance contracts and calibration subscription tiers expand faster than hardware unit sales. Recurring revenue from EU MDR-mandated post-market surveillance data services now matches equipment margin contribution in German multi-site chains.
For Market Incumbents: Compound platform control by embedding curing lamps within integrated digital dentistry ecosystems that lock out standalone competitors. Deepen backward integration into emitter thermal management components sourced from Stuttgart-area suppliers. Defend against orthodontic-focused high-intensity specialists by accelerating ultra-high-power platform roadmaps. For New Entrants and Emerging Players: Differentiate on China tier-2 and tier-3 city service localization where incumbent field support remains thin. Target mid-power LED configurations for price-sensitive clinic networks consolidating in Sichuan and Henan provinces. Pursue direct procurement relationships with provincial dental service organizations bypassing national distributor layers. For Investors and Strategic Acquirers: EU MDR post-market surveillance documentation requirements reshape the acquisition landscape toward targets with regulatory affairs capacity and real-world performance databases. Five-to-ten year viability favors adhesive-system specialists with consumables-tied installed bases over standalone equipment plays. Monitor FDA 510(k) clearance velocity for LED platform modifications as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Platform Launch | Battery-powered LED units capture chairside flexibility demand in United States private clinics. |
| EU MDR Compliance Investment | Clinical evaluation documentation capabilities unlock German dental service organization procurement. |
| Emitter Backward Integration | In-house thermal management production reduces dependency on Stuttgart precision optics suppliers. |
| Orthodontic Workflow Partnership | Clear aligner attachment curing protocols drive ultra-high-power platform adoption in Texas practices. |
| China Localization Partnership | Regional service networks in Yangtze River Delta secure tier-2 city clinic expansion. |
Study Parameters
A spread of perspectives from dental equipment procurement managers, biomedical engineers at multi-site practice chains, regulatory affairs leads at lamp manufacturers, and GPO contracts specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and dental service organization capital expenditure disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across emitter technology tiers.
Segmentation dimensions modeled span product type, power rating, connectivity protocol, usage application, and regional regulatory cluster across the projection horizon. CAGRs derived from logistic diffusion curves fitted to LED technology substitution patterns and dental clinic consolidation trajectories. Forecast inputs incorporated EU F-Gas Regulation phase-out schedules and China NMPA Class II device registration timelines.
Decision-makers should treat outputs as directional under assumptions of continued LED cost parity achievement and stable semiconductor foundry capacity; material deviation in emitter supply availability or MDR enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as German dental service organization procurement concentration and China tier-3 clinic network expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Materials
Dental Fiberglass Posts Market
Dental Materials
Dental Putty Market
Dental Materials
Oral Care Chemicals Market
Dental Materials
Dental Amalgam Market
Dental Materials
Remineralizing Gum Market
Dental Materials
Dental Composites Market
Dental Materials
Zirconia Based Dental Ceramics Market
Dental Materials
Nanotechnology Toothpaste Formulations Market
Dental Materials
Dental Plaster Market
Dental Materials
Global Dental Cements Market
Dental Materials
Global Dental Bone Void Filler Market
Dental Materials
Global Dental Adhesive Market
Dental Materials
Dental Bonding Agent Market
Dental Materials
Dental Resins Market
Dental Materials
Dental Matrix Systems Market
Dental Materials
Fluoride Materials Market