

Nanotechnology Toothpaste Formulations Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotechnology Toothpaste Formulations Market Insights
Bundle configurations pairing whitening pastes with sensitivity kits is recalibrating how dental clinics and personal care consumers evaluate purchase economics. Colgate-Palmolive leverages its global manufacturing scale to anchor nano-calcium phosphate lines across multiple continents. Unilever competes through specialized herbal-nano hybrid formulations targeting emerging market preferences. GlaxoSmithKline dominates the sensitivity segment with zinc oxide nanoparticle platforms backed by clinical validation.
Nanotechnology toothpaste formulations incorporate engineered particles typically measuring 1-100 nanometers, with hydroxyapatite and silver nanoparticles serving as active remineralization and antimicrobial agents designed to penetrate enamel microstructures. Whitening toothpaste and anti-cavity toothpaste command the largest revenue pools, though dentin hypersensitivity applications show the fastest trajectory as aging populations seek non-invasive interventions. Titanium dioxide nanoparticles and calcium phosphate nanoparticles attract disproportionate R&D investment because these materials demonstrate measurable enamel repair efficacy in peer-reviewed dental studies.
The FDA regulates nanoparticle safety claims in oral care through its Center for Drug Evaluation and Research, while the EPA monitors environmental discharge of rinse residues containing metallic nanoparticles. REACH compliance in Europe mandates extensive toxicity dossiers for titanium dioxide nanoforms, elevating compliance costs for exporters. ISO 10993 biocompatibility standards increasingly influence procurement criteria among dental clinic chains. Stakeholders must track evolving classification debates between cosmetic and drug designations for enamel-repair claims.
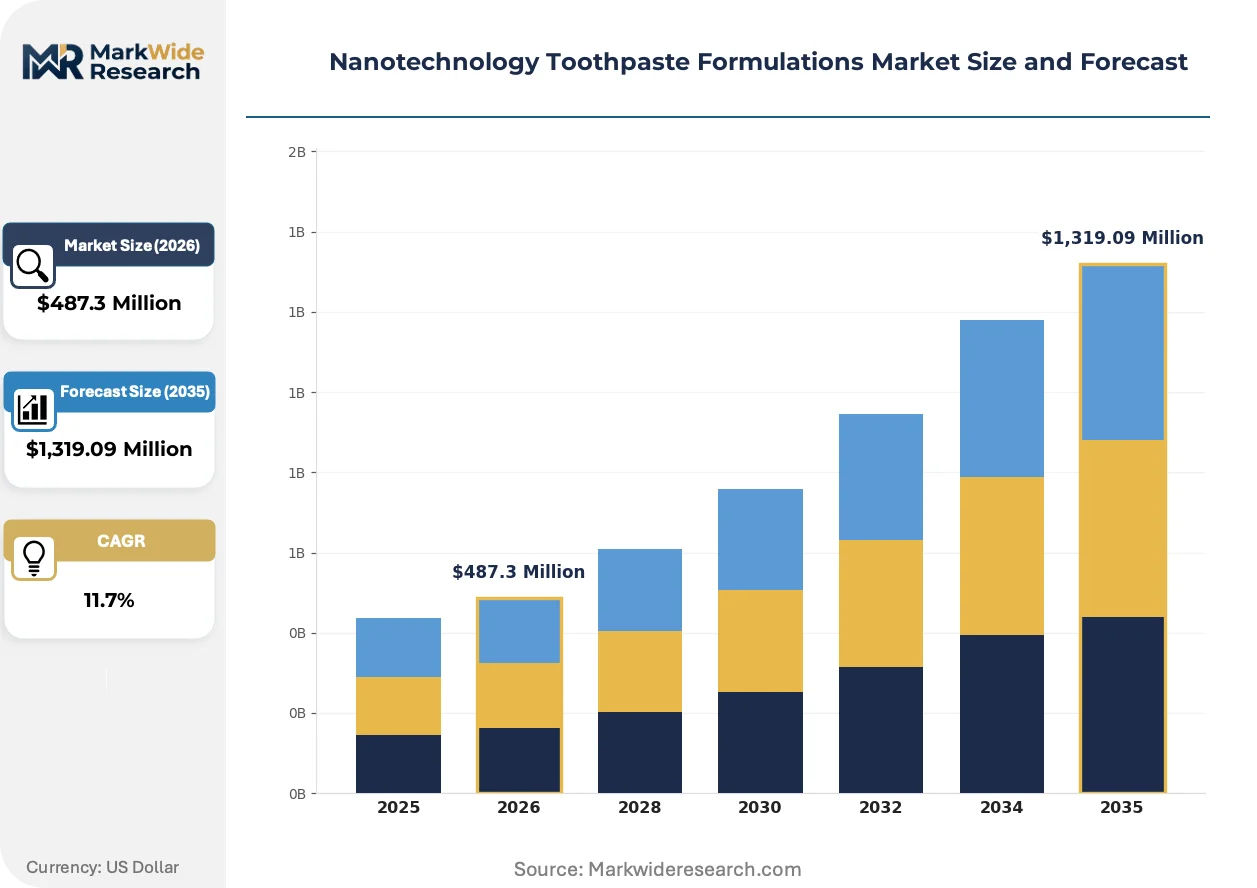
Market Dynamics
The FDA's evolving stance on nanoparticle biocompatibility in oral care products is compressing formulation timelines while forcing manufacturers to front-load clinical validation investments before commercialization.
Growth Catalysts
- Enamel remineralization efficacy:Hydroxyapatite nanoparticles demonstrate measurable penetration into enamel microstructures in peer-reviewed dental studies, accelerating adoption among cosmetic dentistry providers.
- REACH compliance maturation:European manufacturers that completed titanium dioxide nanoform toxicity dossiers early now capture preferential shelf placement in EU pharmacy chains.
- Aging population dental needs:Dentin hypersensitivity prevalence among adults over 50 drives non-invasive intervention demand in United States dental clinics.
Market Restraints
- Silver nanoparticle cost volatility:Precious metal price fluctuations compress margins on antimicrobial formulations targeting premium segments.
- Supply concentration in East Asian titanium dioxide:Five producers control over 70% of cosmetic-grade nano-TiO2 feedstock, creating vulnerability to export licensing disruptions.
- EPA rinse residue monitoring:Metallic nanoparticle environmental discharge thresholds require costly wastewater treatment retrofits at manufacturing facilities.
Strategic Opportunities
- Herbal-nano hybrid white space:Ayurvedic ingredient suppliers in India seek formulation partners to penetrate domestic mass-market channels.
- Zinc oxide sensitivity platforms:Clinical validation backing enables premium positioning in Japan's aging consumer base.
- Direct-to-dental-club distribution:Subscription bundling of prophylactic pastes with chairside kits bypasses retail margin compression.
Industry Challenges
- ISO 10993 biocompatibility certification timelines:Dental clinic chains now mandate third-party validation, extending product launch cycles by 8-14 months.
- Cross-functional talent scarcity:Formulation chemists with both nanomaterials synthesis and oral care regulatory experience command premium compensation.
- Legacy ERP integration:Batch traceability requirements for nanoform tracking strain manufacturing execution systems at mid-tier producers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotechnology Toothpaste Formulations Market Trends and Innovations
Formulation science and procurement logic are diverging from conventional oral care paradigms as nano-scale active delivery systems mature and buyer sophistication increases.
Calcium phosphate nanoparticle platforms are unifying remineralization and whitening functions in single-paste architectures. Dental clinic chains in the United States are piloting these dual-action formulations at 40% faster replacement cycles than standard prophylactic products. This convergence is compressing SKU proliferation while elevating per-unit price points.
REACH authorization requirements for titanium dioxide nanoforms are restructuring European supply relationships. Manufacturers without completed toxicity dossiers face exclusion from pharmacy procurement tenders in Germany and France. Specialty chemical suppliers with pre-registered substances are securing multi-year exclusive supply agreements with major brands.
Subscription-based replenishment models are displacing retail-driven repurchase patterns among high-frequency users. Direct channels now capture 15-20% of premium sensitivity paste volume in urban United States markets. Dental clinic chains are responding by white-labeling bundled kits to retain patient loyalty.
Nanotechnology Toothpaste Formulations Market Segmentation
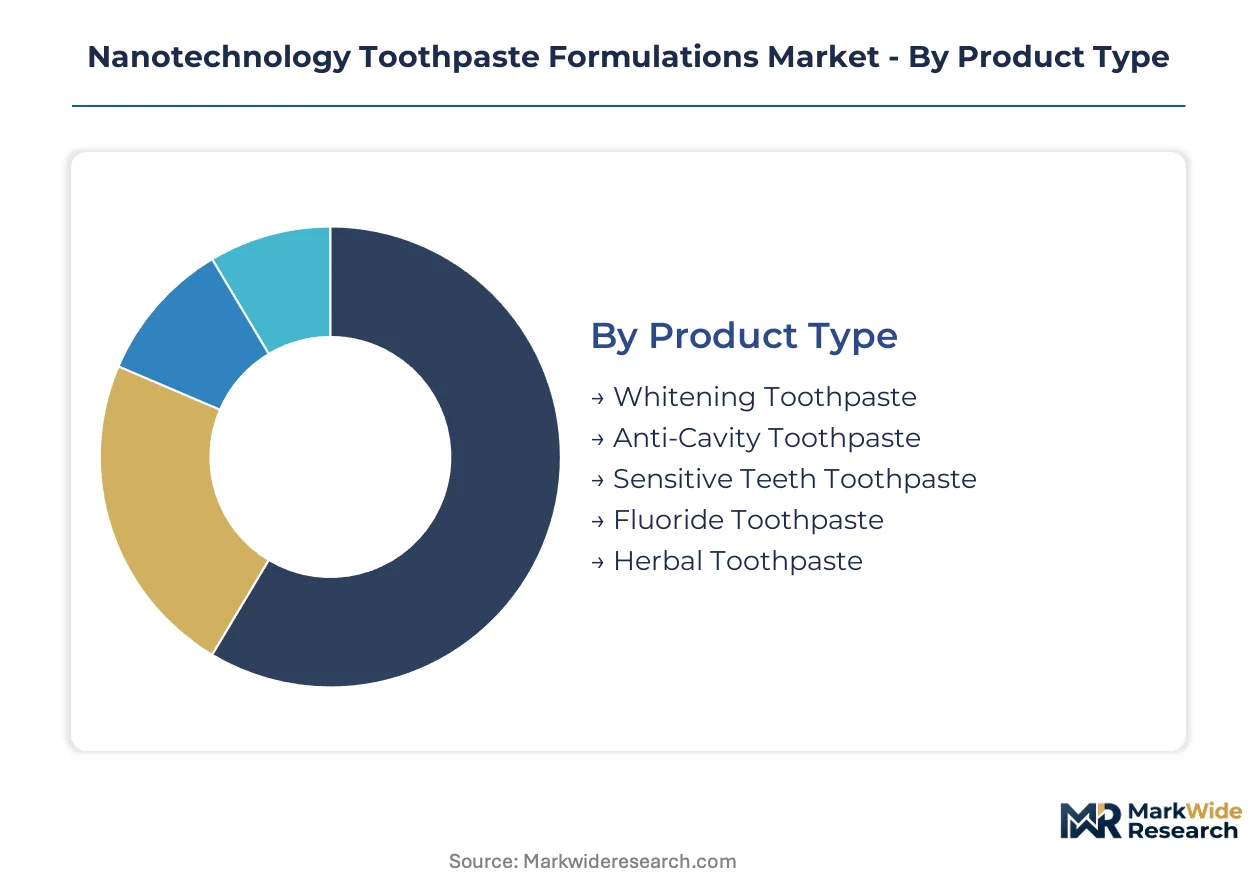
Segmentation in nanotechnology toothpaste formulations reveals how particle engineering and distribution channel choices determine margin capture. Manufacturers align R&D portfolios against specific performance claims and procurement authority levels.
Product Type:
Standalone therapeutic pastes dominate pharmacy shelf space, while embedded dual-action formulations penetrate dental clinic procurement systems.
- Whitening Toothpaste:Titanium dioxide and hydroxyapatite nanoparticles create optical scattering and surface stain disruption. United States cosmetic dentistry providers drive premium positioning through chairside dispensing protocols.
- Anti-Cavity Toothpaste:Nano-calcium phosphate and silver formulations deliver remineralization and antimicrobial action in single-paste architectures. Dental clinic chains in Germany prioritize these for prophylactic appointment bundling.
- Sensitive Teeth Toothpaste:Potassium nitrate-nano hybrid systems target dentin tubule occlusion.
- Fluoride Toothpaste:Nano-fluoride delivery enhances bioavailability at reduced concentration thresholds.
- Herbal Toothpaste:Ayurvedic extract-nano complexes serve price-sensitive mass markets in India.
Volume placements concentrate in whitening formulations; the faster expansion belongs to sensitivity applications.
Nanoparticle Technology:
Cost tiers separate precious metal platforms from mineral-derived alternatives, with feedstock geography dictating supply security profiles.
- Silver Nanoparticles:Metallic silver at 1-100 nanometers delivers broad-spectrum antimicrobial efficacy against oral pathogens. Price volatility in London Metal Exchange silver futures constrains formulation budgeting for premium oral care lines.
- Titanium Dioxide Nanoparticles:Nano-TiO2 provides photocatalytic whitening and UV stability in paste matrices. REACH authorization status in France and Germany determines pharmacy channel eligibility for European brands.
- Zinc Oxide Nanoparticles:Anti-inflammatory and desensitizing properties support therapeutic positioning.
- Calcium Phosphate Nanoparticles:Biomimetic hydroxyapatite precursors enable enamel remineralization claims.
- Silicon Dioxide Nanoparticles:Abrasive and thickening functions in paste rheology control.
Mineral-derived nanoparticles capture volume leadership; silver platforms command the steepest price premiums.
Application:
Customer type stratification separates clinical prescription models from over-the-counter self-selection behaviors.
- Oral Hygiene:Daily maintenance formulations with broad antimicrobial and plaque control specifications. Personal care consumers in Japan demonstrate highest per-capita expenditure on nano-enhanced maintenance pastes.
- Dentin Hypersensitivity:Targeted tubule occlusion using nano-scale potassium nitrate or zinc oxide delivery. Aging populations in Italy and Spain drive clinical referral volumes for prescription-strength variants.
- Enamel Protection:Remineralization-focused claims requiring substantiation in peer-reviewed dental literature.
- Anti-Plaque Treatment:Biofilm disruption via silver or copper nanoparticle platforms.
- Fresh Breath Enhancement:Volatile sulfur compound neutralization using nano-encapsulated zinc salts.
Maintenance applications hold volume concentration; hypersensitivity interventions are climbing the fastest.
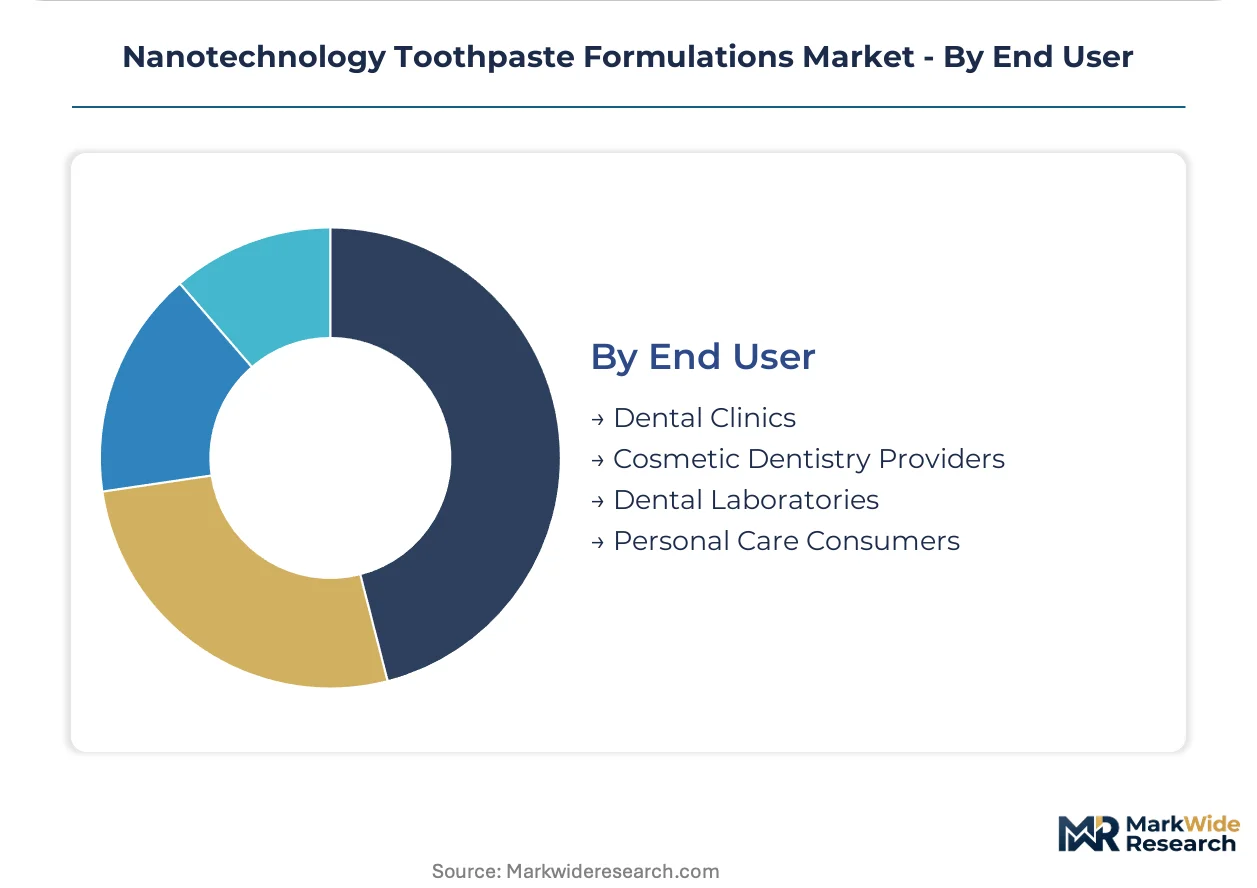
End User:
Procurement authority levels create distinct margin structures, with institutional buyers extracting volume discounts unavailable to retail channels.
- Dental Clinics:Prophylactic paste procurement at scale with ISO 10993 biocompatibility mandates. Clinic chains in the United Kingdom consolidate purchasing through group procurement organizations.
- Cosmetic Dentistry Providers:Premium whitening and enamel repair formulations for elective procedure bundling. Beverly Hills and Manhattan practices set pricing benchmarks for aesthetic nano-paste categories.
- Dental Laboratories:Custom tray fabrication materials with nano-abrasive finishing compounds.
- Personal Care Consumers:Retail pharmacy and direct-to-subscription purchasing with price elasticity sensitivity.
Clinic procurement dominates volume throughput; cosmetic provider channels deliver the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturers dominate nano-TiO2 feedstock production while North American and European markets absorb the majority of value-added formulations. This geographic split shapes regulatory compliance investments and distribution network configurations across the industry.
United States
FDA scrutiny of nanoparticle biocompatibility claims accelerates clinical validation timelines for enamel-repair formulations. Cosmetic dentistry providers in Beverly Hills and Manhattan establish premium pricing benchmarks for chairside-dispensed nano-paste categories. The EPA monitors metallic nanoparticle discharge thresholds, forcing wastewater treatment upgrades at domestic manufacturing facilities.
Germany
REACH authorization requirements for titanium dioxide nanoforms determine pharmacy channel eligibility for oral care brands. Dental clinic chains consolidate procurement through group purchasing organizations, extracting volume discounts on ISO 10993-certified prophylactic pastes. The ECHA maintains stringent toxicity dossier standards that elevate compliance costs for imported formulations.
Japan
Aging consumer demographics drive prescription-strength sensitivity paste demand through METI-regulated distribution channels. Osaka-based dental product distributors specialize in zinc oxide nanoparticle platforms for dentin hypersensitivity interventions. PMDA clinical validation requirements extend product launch cycles for foreign manufacturers.
India
Ayurvedic ingredient suppliers seek formulation partners to penetrate domestic mass-market channels with herbal-nano hybrid products. CDSCO regulates cosmetic-drug classification boundaries for enamel-repair claims, creating uncertainty for multinational entrants. Maharashtra-based personal care manufacturers expand nano-calcium phosphate production capacity for export markets.
China
Domestic producers control over 70% of cosmetic-grade nano-TiO2 feedstock supply, creating pricing leverage over downstream formulators. NMPA registration pathways for nano-enhanced oral care products require extensive safety documentation. The Yangtze River Delta hosts concentrated specialty chemical manufacturing clusters serving both domestic and export demand.
Nanotechnology Toothpaste Formulations Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated market structure. Consumer goods multinationals leverage global manufacturing scale and established retail distribution networks. Specialty oral care companies concentrate on clinical validation and dental clinic channel relationships. The dominant competitive moves involve portfolio diversification into dual-action formulations and strategic partnerships with nanoparticle feedstock suppliers.
Within the diversified conglomerate tier, Colgate-Palmolive Company and Unilever exemplify scale-driven positioning across multiple continents. GlaxoSmithKline occupies a specialist position anchored by clinical validation backing for therapeutic formulations. These three companies represent distinct archetypes: manufacturing scale leadership, emerging market adaptation, and sensitivity segment clinical credibility.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| GlaxoSmithKline |
| Unilever |
| Lion Corporation |
| Sunstar Suisse |
| Procter & Gamble |
| Church & Dwight |
| Amway |
| Dabur India |
| Others |
Pricing and Supply Chain Analysis
Nano-calcium phosphate synthesis scale-up across Maharashtra and Jiangsu manufacturing clusters simultaneously compresses unit production costs and concentrates feedstock procurement leverage among five dominant titanium dioxide producers. This dual transformation reshapes how formulation specialists negotiate input contracts and position finished goods across premium and mass-market tiers.
Pricing Analysis
Margin tightening in silver nanoparticle formulations reflects London Metal Exchange price volatility and precious metal hedging costs. Three-tier pricing structure across premium clinical-grade, standard pharmacy, and economy mass-market levels separates ISO 10993-certified dental clinic supply from retail self-selection. Cost-down pressure on herbal-nano hybrids accelerates because Ayurvedic extract suppliers compete for limited formulation partnership slots. Personal care consumers in price-sensitive emerging markets exhibit highest elasticity; cosmetic dentistry providers in Beverly Hills and Manhattan show lowest sensitivity.
Supply Chain Analysis
Reverse logistics for expired nano-enhanced paste inventory remains underdeveloped, with most manufacturers lacking established reclamation pathways for metallic nanoparticle residues. Feedstock concentration centers on China, Japan, and Germany for cosmetic-grade nano-TiO2, nano-silver, and precision milling equipment respectively. Formulation chemistry draws from East Asian titanium dioxide, Indian herbal extract supply, and European REACH-compliant additive packages. Single-source vulnerability in nano-TiO2 feedstock creates exposure to export licensing disruptions. Distribution runs through dental clinic group purchasing organizations in developed markets and fragmented retail pharmacy networks in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over nano-calcium phosphate feedstock and downstream direct-to-dental-club channels constitute the twin levers driving competitive positioning in this vertical-integration race.
For Market Incumbents: To counter REACH authorization delays blocking European pharmacy access, secure multi-year exclusive supply agreements with pre-registered titanium dioxide nanoform suppliers and accelerate ISO 10993 certification investments to extend product launch cycles advantageously. Backward integration into nano-calcium phosphate production in Maharashtra-based manufacturing clusters reduces feedstock cost volatility exposure. For New Entrants and Emerging Players: Capture white-space in herbal-nano hybrid formulations for India's domestic mass-market channels and zinc oxide sensitivity platforms for Japan's aging consumer base. India's CDSCO regulatory uncertainty creates temporary entry windows for agile formulators. Direct-to-dental-club subscription bundling with chairside kits bypasses retail margin compression and builds patient loyalty lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified consumer goods conglomerates seeking clinical credibility and dental clinic channel relationships. Long-term viability hinges on regulatory navigation capability across FDA, REACH, and PMDA jurisdictions. Acquisition target archetype: specialty oral care companies with completed toxicity dossiers and validated enamel-repair claims. The signal to watch is ECHA classification debates shifting titanium dioxide nanoforms between cosmetic and drug designations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nano-Calcium Phosphate | Maharashtra production capacity secures feedstock cost stability against East Asian titanium dioxide volatility. |
| ISO 10993 Biocompatibility Certification Investment | Third-party validation extends launch cycles but unlocks dental clinic chain procurement mandates. |
| Direct-to-Dental-Club Subscription Launch | Bypasses retail margin compression with bundled prophylactic paste and chairside kit replenishment. |
| Herbal-Nano Hybrid Formulation Partnership | Ayurvedic supplier alliances penetrate India's CDSCO-uncertain domestic mass-market channels. |
| REACH Authorization Completion for Nano-TiO2 | Toxicity dossier finalization determines pharmacy channel eligibility in Germany and France. |
Research Methodology
Independent corroboration across formulation chemists at specialty oral care manufacturers, procurement directors at dental clinic group purchasing organizations, and regulatory affairs specialists at nanoparticle feedstock suppliers underwrites the qualitative findings. Secondary validation draws from FDA Center for Drug Evaluation and Research guidance documents, ECHA REACH authorization registers, and PMDA clinical trial disclosure databases. Bottom-up demand modeling across end-user segments triangulates against top-down market sizing from customs trade data and pharmacy retail audit records.
Rate-of-change decomposition separates volume expansion from value capture across the projection horizon. Segmentation dimensions modeled include nanoparticle technology type, product performance claim, distribution channel authority level, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to peer-reviewed dental study publication rates and dental clinic equipment installation trajectories. Nano-enhanced paste replacement cycle acceleration and sensitivity application prescription-strength conversion rates serve as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA titanium dioxide reclassification decisions and EPA metallic nanoparticle discharge threshold revisions. Material deviation in FDA biocompatibility claim scrutiny intensity or East Asian export licensing policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.