
 Global Bone Grafts and Substitutes Market | 2026-2036
Global Bone Grafts and Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Grafts and Substitutes Market Intelligence
Use of bone grafts in ambulatory surgical centers is expanding, shifting procedural volume from hospitals. Medtronic PLC leverages its distribution network to supply spine and orthopedic segments. Zimmer Biomet differentiates with a broad portfolio of synthetic and allograft options for joint reconstruction. Stryker competes through its focus on trauma and spine applications, offering specialized graft materials.
Bone grafts and substitutes are implantable materials used to promote bone healing, fill voids, and provide structural support in skeletal defects. These materials function via osteoconduction or osteoinduction, with compositions ranging from human tissue to synthetic ceramics like hydroxyapatite. Allografts and demineralized bone matrix (DBM) products continue to hold significant share due to their proven biological properties and surgeon familiarity. However, synthetic grafts are gaining prominence, driven by lower immunogenicity risk and consistent supply.
Market access is governed by stringent regulatory frameworks, including the U.S. FDA's 510(k) clearance pathway and the EU's Medical Device Regulation (MDR). In parallel, China's NMPA and Brazil's ANVISA impose their own rigorous approval processes, influencing regional market entry strategies. Navigating the evolving standards for tissue sourcing, sterilization, and synthetic material biocompatibility remains a critical hurdle for all manufacturers.
Market Dynamics
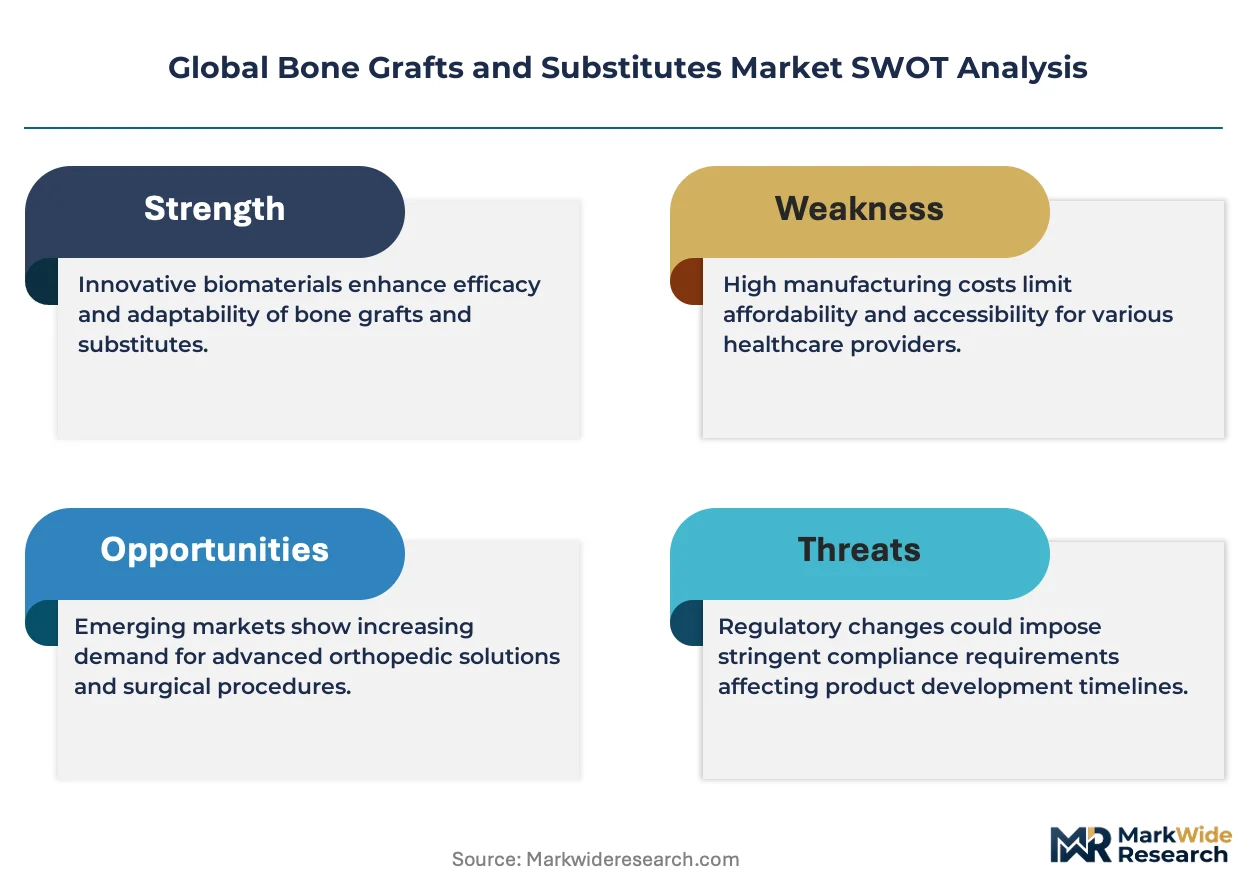
The market's core tension stems from the clinical trade-off between the established osteoinductive performance of allografts and the supply chain consistency and reduced immunogenicity offered by next-generation synthetic substitutes, a choice heavily mediated by global regulatory bodies.
Growth Catalysts
- Aging Demographics:An expanding elderly population in countries like China and Japan increases the incidence of degenerative bone diseases and fractures, requiring more reconstructive surgeries.
- Material Science Innovation:Advances in biocompatible materials, particularly synthetic ceramics like hydroxyapatite and beta-tricalcium phosphate, provide safer alternatives to human-derived grafts.
- Procedural Volume Shift:The migration of spinal and orthopedic procedures to ambulatory surgical centers creates new, high-volume demand channels for cost-effective graft materials.
Market Restraints
- Regulatory Scrutiny:Stringent clinical data requirements under the EU's MDR and the FDA's 510(k) pathway create significant time-to-market delays and costs for novel graft materials.
- Allograft Supply Constraints:The availability of human donor tissue is inherently limited and subject to strict screening protocols, leading to potential supply chain volatility and higher procurement costs.
- Clinical Performance Gaps:Some synthetic substitutes lack the osteoinductive signaling capabilities of allografts, limiting their effectiveness in challenging healing environments without biologic augmentation.
Strategic Opportunities
- Bioactive Formulations:Developing grafts that incorporate therapeutic agents, such as antibiotics or growth factors, addresses unmet needs for infection prevention and enhanced bone regeneration.
- Patient-Specific Implants:Leveraging 3D printing technology enables the creation of custom-scaffolded grafts that precisely match complex skeletal defects, particularly in craniomaxillofacial surgery.
- Emerging Market Penetration:Expanding access to advanced surgical procedures in Latin American countries like Brazil and Mexico presents a significant growth avenue for graft manufacturers.
Industry Challenges
- International Standardization:Manufacturers face complexity in harmonizing product sterilization and tissue processing methods to comply with disparate standards set by the NMPA, ANVISA, and EMA.
- Surgical Training Requirements:The adoption of advanced composite or cell-seeded grafts necessitates specialized training for surgeons to ensure proper handling and optimal clinical outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Grafts and Substitutes Market |
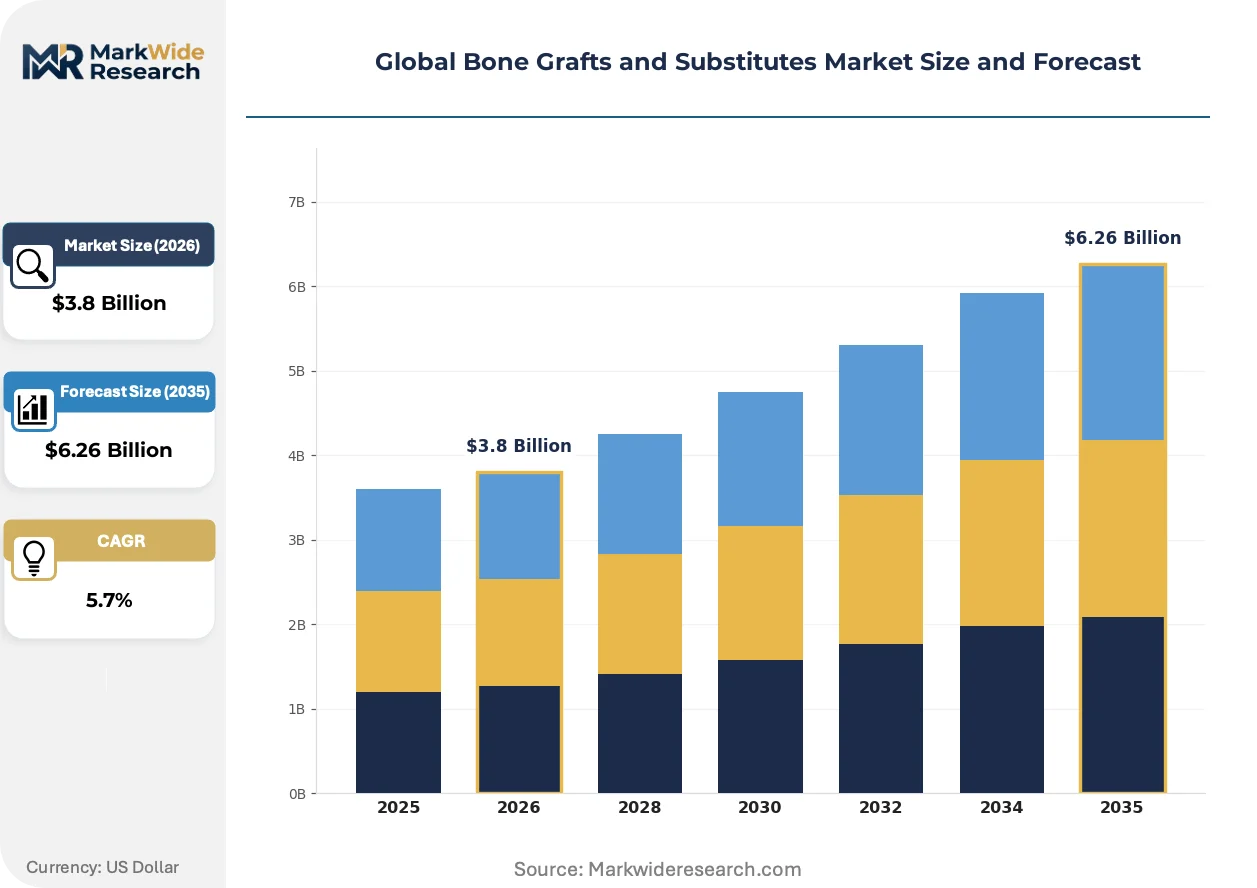
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autografts, Allografts, Xenografts, Synthetic Grafts, Demineralized Bone Matrix Application: Orthopedic Surgery, Spine Surgery, Dental Surgery, Trauma Repair, Maxillofacial Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialized Clinics, Dental Offices, Research Institutes Form: Cortical, Cancellous, Composite, Injectable, Granules |
| Companies Covered | Medtronic PLC, Stryker, Zimmer Biomet, DePuy Synthes Companies, Smith & Nephew plc, AlloSource, SeaSpine, Bioventus, Orthofix Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Grafts and Substitutes Market Strategic Shifts & Innovations
A fundamental transition toward bioactive materials that actively participate in and direct cellular healing processes is underway. This evolution moves beyond grafts as simple structural fillers, emphasizing materials that can orchestrate a more predictable and rapid biological response.
Bioactive glass composites function by releasing specific ions that stimulate gene expression related to bone formation. Orthopedic surgeons are increasingly adopting these materials for challenging fusions where predictable biologic activity is paramount. This technology is expanding into spinal and trauma applications that traditionally relied on autograft or costly biologics, offering a synthetic, off-the-shelf alternative.
The U.S. FDA's heightened scrutiny on human cells, tissues, and cellular and tissue-based products (HCT/Ps) is tightening the compliance landscape. This enforcement clarifies the boundary between minimally manipulated allografts and products requiring more rigorous biologic license application pathways. Demineralized bone matrix (DBM) manufacturers are most affected, needing to validate processing methods to avoid higher regulatory classifications.
Hospital value analysis committees are mandating evidence of clinical efficacy and economic benefit for new product approvals. This committee-driven model disrupts traditional surgeon-preference procurement, favoring grafts with strong health economics data. The trend is most visible within large integrated delivery networks (IDNs) in the United States, where cost containment is a primary objective.
Global Bone Grafts and Substitutes Market Segmentation
Understanding the varied compositions and applications of bone grafts is essential for market participants. The bone grafts and substitutes market diversifies across material types, surgical applications, and end-user settings. This granular segmentation reveals distinct demand patterns and regulatory considerations across the industry.
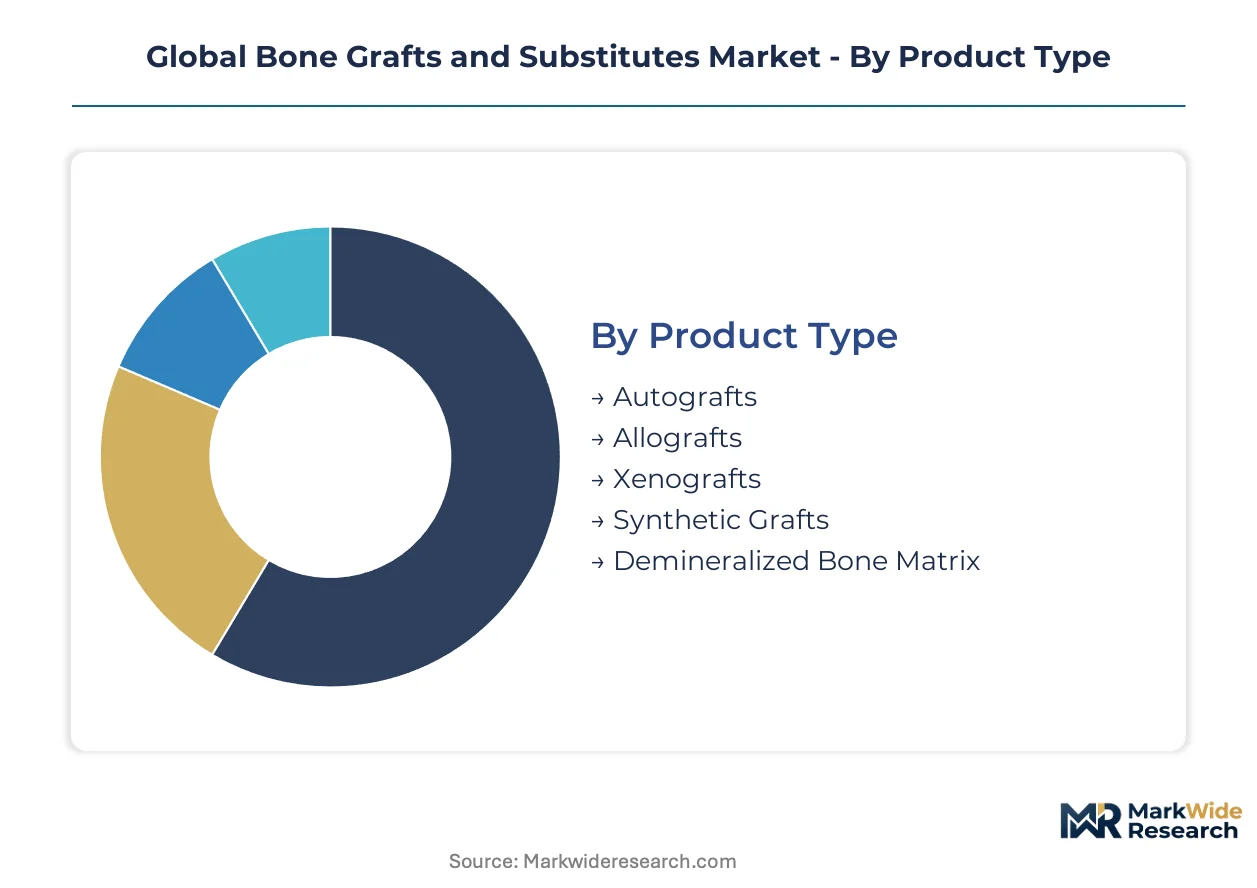
Product Type:
The technological sophistication of bone graft materials defines their clinical utility and market penetration. These materials range from human-derived tissues to advanced synthetic compounds, each offering specific advantages for bone regeneration.
- Autografts:These grafts involve tissue harvested directly from the patient's own body, offering excellent biocompatibility and osteoinductive properties without immunogenic risk. Demand remains consistent in complex reconstructive surgeries where optimal healing is paramount.
- Allografts:Derived from human donors, these materials provide osteoconductive scaffolds and some osteoinductive factors, benefiting from surgeon familiarity and proven biological properties. Strict regulatory frameworks from the U.S. FDA and EU's MDR govern their processing and use.
- Xenografts:These grafts utilize bone tissue from non-human species, typically bovine or porcine, after extensive processing to remove immunogenic components. They serve as osteoconductive scaffolds in various orthopedic and dental procedures.
- Synthetic Grafts:Engineered materials like calcium phosphates and bioactive glasses offer consistent supply and reduced immunogenicity compared to human-derived options. Their prominence grows in spinal and trauma applications due to material science innovation.
- Demineralized Bone Matrix:DBM products are processed allografts that expose bone morphogenetic proteins, enhancing osteoinduction. Manufacturers face heightened scrutiny from regulators like the U.S. FDA regarding their processing methods.
Mature deployment sits with Allografts. Newer deployment is concentrated in Synthetic Grafts.
Application:
The procedural scope for bone grafts spans a wide array of surgical specialties requiring bone repair or augmentation. Each application presents unique demands on graft material properties and surgical techniques.
- Orthopedic Surgery:This broad category includes joint reconstruction, fracture repair, and tumor resection, where grafts provide structural support and promote healing. The migration of procedures to ambulatory surgical centers influences material selection for cost-effectiveness.
- Spine Surgery:Grafts are critical for spinal fusions, stabilizing vertebrae and promoting bone growth between segments. Innovation in bioactive glass composites offers new synthetic alternatives for challenging fusions.
- Dental Surgery:Grafts are used for alveolar ridge augmentation, sinus lifts, and periodontal defect repair, creating a significant source of new volume. Patient demographics in countries like China drive demand for these procedures.
- Trauma Repair:These applications address bone defects resulting from severe injuries, often requiring materials that can rapidly integrate and provide mechanical stability. Stryker focuses on specialized graft materials for these critical needs.
- Maxillofacial Surgery:Grafts are employed for facial bone reconstruction, cleft palate repair, and dental implant placement within the craniofacial region. Patient-specific implants leveraging 3D printing technology offer precise solutions for complex defects.
The largest volume of procedures occurs within Orthopedic Surgery. Dental Surgery is expanding most quickly.
End User:
The care setting where bone grafts are utilized significantly impacts procurement patterns and product distribution. Different facilities prioritize varying factors such as volume, cost, and specialized surgical needs.
- Hospitals:These institutions remain primary consumers of bone grafts for complex and inpatient surgeries, including major orthopedic and spinal procedures. Value analysis committees within integrated delivery networks influence purchasing decisions.
- Ambulatory Surgical Centers:ASCs are increasingly performing spinal and orthopedic procedures, driving demand for cost-effective, off-the-shelf graft materials. This shift represents an expanding channel for Medtronic PLC and other suppliers.
- Specialized Clinics:These facilities, often focusing on sports medicine or reconstructive surgery, require specific graft types for niche procedures. They demand materials with proven clinical efficacy for targeted applications.
- Dental Offices:Dental professionals utilize bone grafts for a range of oral and maxillofacial procedures, frequently purchasing directly from distributors. The segment represents a consistent source of new volume for graft materials.
- Research Institutes:These entities use bone grafts and substitutes for preclinical studies, material science development, and tissue engineering research. Their demand focuses on novel and experimental graft formulations for scientific inquiry.
Traditional procurement channels center on Hospitals. New procurement models are emerging from Ambulatory Surgical Centers.
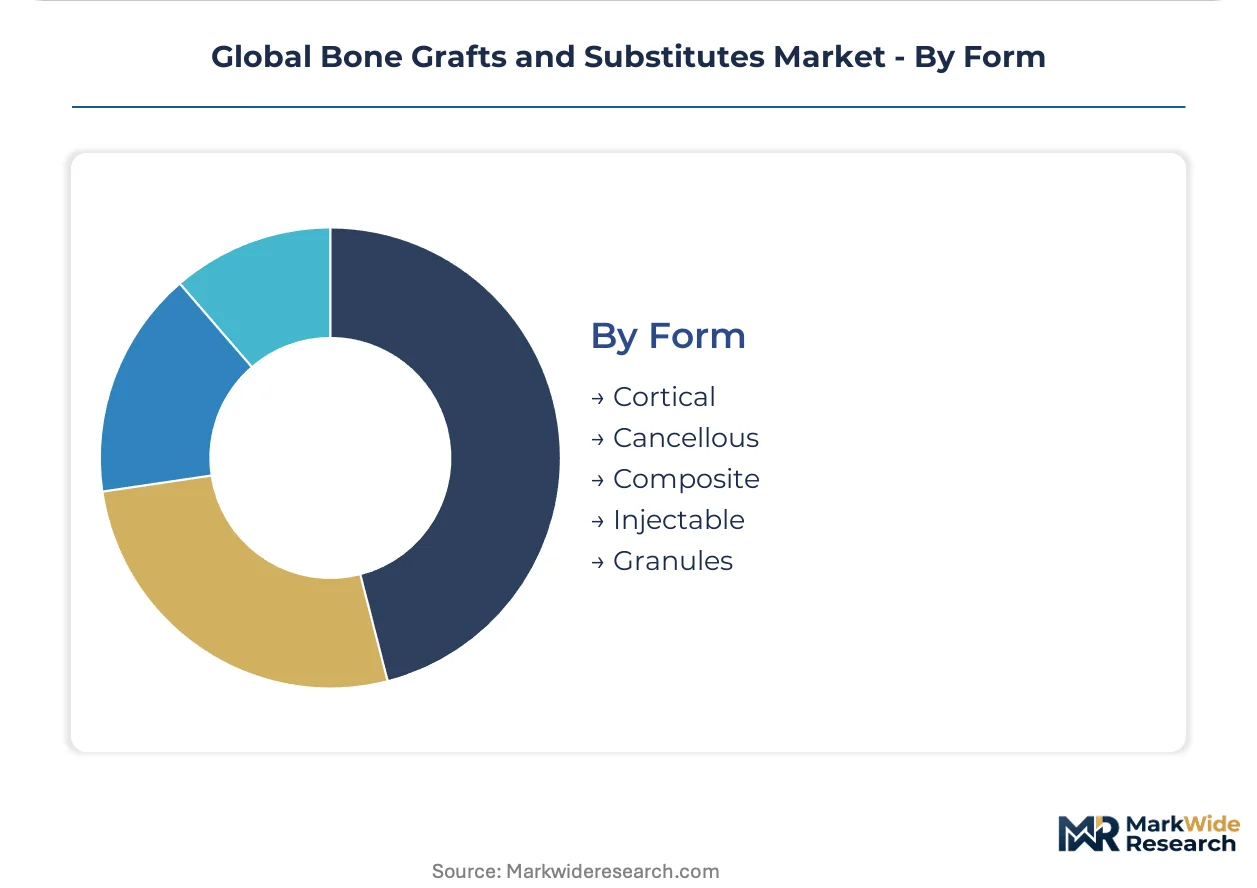
Form:
The physical presentation of bone graft materials dictates their ease of handling, surgical application, and ability to conform to defect sites. Manufacturers offer various forms to suit diverse clinical requirements.
- Cortical:These forms consist of dense bone, providing structural support and mechanical strength, often used in load-bearing applications. They offer a stable scaffold for bone ingrowth in orthopedic reconstruction.
- Cancellous:Characterized by its porous, spongy structure, cancellous bone is osteoconductive and readily integrates with host bone. It is frequently used to fill voids and promote healing in non-load-bearing areas.
- Composite:These grafts combine different materials, such as allograft with synthetic components or growth factors, to leverage multiple biological properties. Zimmer Biomet offers a broad portfolio including such advanced options.
- Injectable:Formulated as pastes or gels, injectable grafts allow for minimally invasive delivery and conform readily to irregular defect shapes. Their use simplifies application in spinal and dental procedures.
- Granules:Small particles of graft material, often synthetic or allograft, are packed into bone defects to provide an osteoconductive matrix. Granules are versatile for filling irregular spaces and promoting bone regeneration.
The most widespread formats include Cortical. The most versatile formats are found in Composite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A fundamental production-vs-consumption divide characterizes the global bone grafts and substitutes market, with advanced economies driving demand for complex procedures. Emerging markets like China are rapidly increasing their consumption volume. This dynamic influences investment and regulatory strategies across key regions.
United States
Aging demographics and a high incidence of orthopedic conditions fuel demand for bone grafts in the United States. The FDA's 510(k) clearance pathway governs market access for novel materials, ensuring product safety and efficacy. Major medical device hubs like Boston and Minneapolis concentrate research and development and manufacturing for advanced bone regeneration solutions.
Germany
Germany's robust healthcare infrastructure and an aging population create sustained demand for orthopedic and spinal graft materials. The EU's Medical Device Regulation (MDR) imposes stringent clinical data requirements for all bone graft products. Munich and Berlin are centers for biomedical research, fostering innovation in synthetic graft development.
China
Expanding access to advanced healthcare and a large elderly population drive significant demand for bone grafts in China. The NMPA's rigorous approval processes shape market entry strategies for both local and international manufacturers. Shanghai and Beijing are key hubs for medical device production and distribution, supporting domestic market growth.
Japan
Japan experiences high demand for spinal and dental bone grafts due to its rapidly aging demographic and advanced surgical practices. The PMDA regulates medical devices, requiring comprehensive clinical evidence for new bone graft technologies. Tokyo and Osaka host numerous orthopedic and dental implant companies, focusing on high-quality material solutions.
Brazil
Growing access to specialized surgical procedures and a rising middle class increase the need for bone grafts in Brazil. ANVISA imposes its own rigorous approval processes, influencing regional market entry strategies for graft manufacturers. São Paulo and Rio de Janeiro are major medical centers, driving adoption of innovative bone regeneration techniques.
Global Bone Grafts and Substitutes Market Key Industry Players
Top-tier vendors anchor the global bone grafts and substitutes market, while a diverse array of specialized manufacturers occupies niche segments. The market structure exhibits a tiered consolidation, with large players offering broad portfolios and smaller firms focusing on specific material types. Strategic archetypes include diversified medical device conglomerates and pure-play bone graft specialists. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand market reach.
On the premium-tier vector, Medtronic PLC, a diversified medical technology leader, exemplifies a broad distribution network across spine and orthopedic segments. Zimmer Biomet, an orthopedic reconstruction specialist, represents a comprehensive portfolio of synthetic and allograft options. Stryker, known for its focus on trauma and spine applications, anchors the specialized graft materials segment with its targeted offerings.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker |
| Zimmer Biomet |
| DePuy Synthes Companies |
| Smith & Nephew plc |
| AlloSource |
| SeaSpine |
| Bioventus |
| Orthofix Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration into tissue processing facilities anchors the supply position for allograft manufacturers, enabling them to control quality and exert pricing power over human-derived graft materials. This structure influences overall market pricing dynamics.
Pricing Analysis
Premium pricing for short lead times characterizes human-derived allografts, reflecting their limited supply and critical surgical demand. The dominant pricing model is per-unit transactional, influenced by material type and regulatory certification level, such as FDA 510(k) clearance. Pricing softness affects synthetic grafts due to increasing competition and consistent supply. Hospitals and integrated delivery networks exhibit high price sensitivity, while specialized clinics prioritize proven clinical efficacy over cost.
Supply Chain Analysis
Direct-to-hospital channels dominate distribution for complex allografts, while distributors serve ambulatory surgical centers and dental offices. Geographic supply concentration for human-derived grafts centers on the United States and Europe, drawing from donor tissue banks. Synthetic grafts rely on ceramic powders and biocompatible polymers, primarily sourced from China and Germany. Regulatory restrictions on tissue sourcing present a significant structural supply chain risk for the entire market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone grafts and substitutes market functions as a cost-of-compliance story, where stringent regulatory frameworks like the EU's Medical Device Regulation (MDR) create significant barriers to entry for non-compliant manufacturers. This environment favors established players with robust quality systems.
For Market Incumbents: To counter the rising competitive pressure from synthetic graft alternatives, established players must deepen vertical integration into advanced material science R&D. Investing in FDA 510(k) and EU MDR compliance for novel composite grafts also reinforces market position. Expanding distribution networks into high-growth ambulatory surgical centers provides a defensive move against market share erosion. Prioritizing surgeon education on complex graft handling maintains product differentiation. For New Entrants and Emerging Players: Enter via niche applications like craniomaxillofacial surgery, leveraging 3D printing for patient-specific implants. The most penetrable segment is synthetic grafts for dental surgery, offering consistent supply and lower immunogenicity risks. A go-to-market angle focusing on cost-effective, off-the-shelf solutions for ambulatory surgical centers can secure early market share. Prioritize rapid NMPA or ANVISA approvals for emerging market access. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized bone graft manufacturers with proprietary bioactive material platforms. The long-term viability of this market over the next decade remains strong, driven by aging demographics and surgical demand. Acquisition targets should be mid-sized firms possessing advanced synthetic graft technologies or strong intellectual property in tissue engineering. The signal to watch is the increasing adoption rate of next-generation composite grafts in routine orthopedic procedures.| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bioactive Glass Composites | These materials actively stimulate bone formation, offering superior clinical outcomes in challenging fusions. |
| Expand 3D Printing Capabilities | Patient-specific implants for maxillofacial surgery address complex defect anatomies with precision. |
| Secure NMPA/ANVISA Approvals | Penetrating China and Brazil unlocks significant growth in expanding surgical procedure volumes. |
| Invest in Surgeon Training Programs | Proper handling of advanced composite grafts ensures optimal clinical results and product adoption. |
| Strengthen Health Economics Data | Evidence of clinical efficacy and economic benefit influences hospital value analysis committee procurement decisions. |
Research Approach
Multi-period observation of surgical procedure volumes and material innovation anchored the trend analysis, supplemented by interviews with orthopedic surgeons, dental professionals, and hospital procurement managers. This approach integrated primary insights with secondary validation from FDA 510(k) filings, EU MDR documentation, and national healthcare expenditure reports. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation. The study also engaged regulatory affairs leads and material science R&D directors.
An input-output matrix structured the quantitative model, projecting market evolution across the analysis window. Segmentation dimensions included product type, surgical application, end-user settings, and material form. Compound annual growth rates were derived from historical trends, expert projections, and anticipated regulatory shifts. Key forecast inputs considered aging demographics and advancements in biocompatible synthetic materials.
Revisions become necessary when unforeseen global health crises or significant shifts in regulatory policy materialize, impacting market trajectory. Forecasts reflect a specific set of underlying assumptions regarding technology adoption and economic stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Mushroom Materials Market
Biomaterials
Self-Healing Hydrogels Market
Biomaterials
Spine Surgery Gels Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
US Heparin Market
Biomaterials
Polysaccharide Hemostatic System Market
Biomaterials
Brazil Bone Graft and Substitutes Market
Biomaterials
Global Implantable Biomaterial Market
Biomaterials
Global Collagen Meniscus Implants Market
Biomaterials
Biomimetic Materials Market
Biomaterials
Bone Distractors Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Chitosan Supplements Market
Biomaterials
Chitosan Market