
 Bone Substitutes Market | 2026-2036
Bone Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Substitutes Market Analysis
Aftermarket service revenue from graft handling and surgical training is narrowing as manufacturers bundle these services into core product contracts. Stryker leverages its integrated trauma platform to control hospital purchasing decisions. Zimmer Biomet anchors its position through deep specialization in ceramic and composite formulations for joint reconstruction. Medtronic PLC competes by extending its biologics portfolio into spine-specific delivery systems.
Bone substitutes are synthetic, natural, or engineered materials designed to replace or augment autograft and allograft bone in defect repair, typically formulated from hydroxyapatite, beta-tricalcium phosphate, collagen matrices, or bioactive glasses that osteoconduct or osteoinduce new bone formation. Ceramic products dominate current volume due to established clinical validation in spinal fusion and trauma voids, while polymer and composite segments attract accelerated R&D investment for tunable resorption rates. Application demand in spine surgery generates premium pricing relative to trauma surgery, where standardized granules compete on procurement cost.
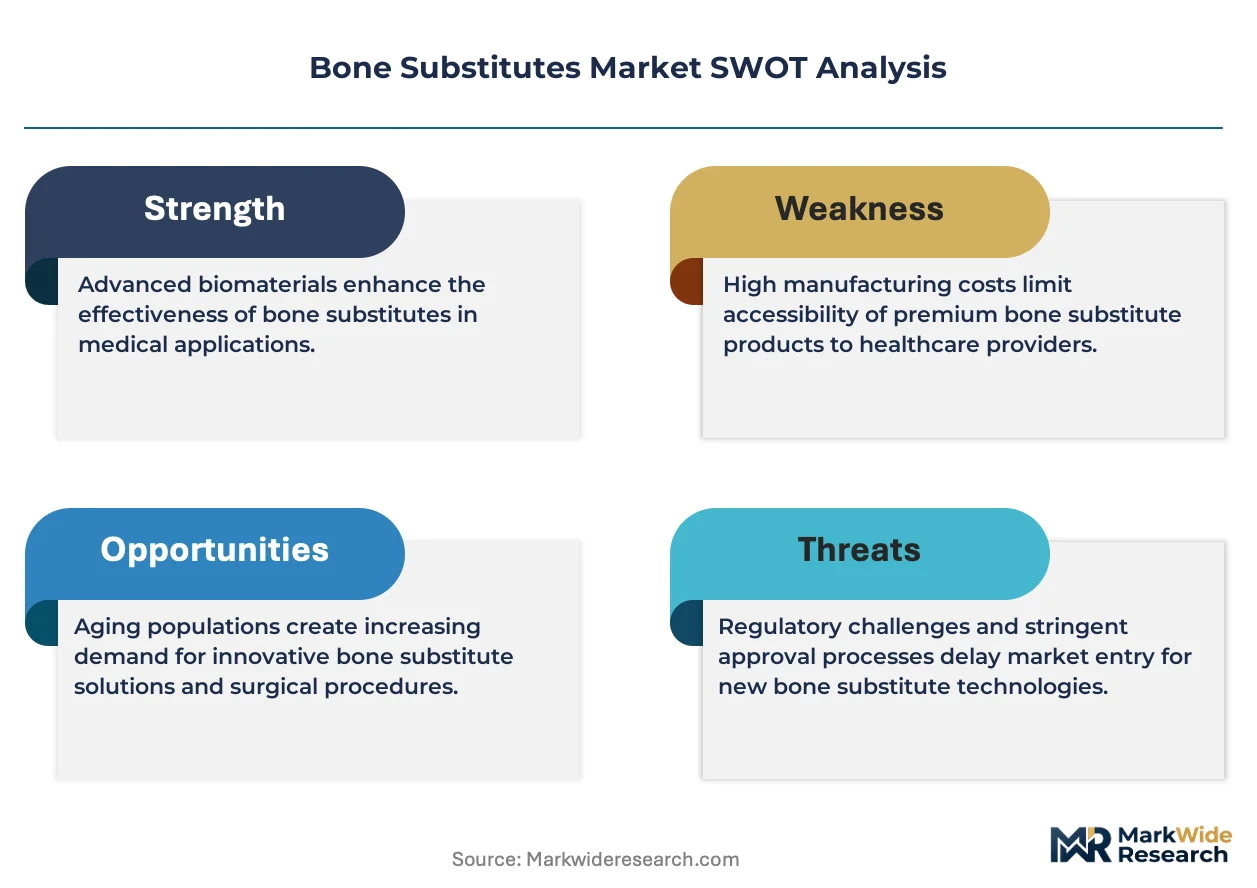
FDA 510(k) premarket notification and EMA Medical Device Regulation (MDR) classification impose distinct biocompatibility and clinical evidence thresholds that determine market access timelines for novel formulations. ISO 10993 biological evaluation standards govern material testing protocols, while the EU F-Gas Regulation indirectly affects processing methods for certain synthetic precursors. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA breakthrough device designation trends to calibrate regulatory investment against commercial launch schedules.
Market Dynamics
Orthopedic clinics are consolidating purchasing authority through integrated delivery networks, forcing manufacturers to bundle surgical training and graft handling services into core product contracts rather than monetizing them separately.
Growth Catalysts
- FDA 510(k) Pathway:The streamlined premarket notification process for bone void fillers accelerates commercialization timelines for ceramic and composite formulations in the United States.
- Revision Arthroplasty Volume:Germany's trauma surgery centers are expanding ceramic-based substitute adoption for joint reconstruction procedures, creating sustained demand pull.
- Synthetic Material Advancement:Hydroxyapatite and beta-tricalcium phosphate composites now match autograft performance in spinal fusion, reducing harvest-site morbidity concerns.
Market Restraints
- Notified Body Bottlenecks:EU MDR capacity constraints are extending certification timelines for novel bioactive glass formulations, delaying market entry by 12-18 months.
- Allograft Price Competition:Tissue bank networks in the United States are compressing pricing for demineralized bone matrix, squeezing synthetic substitute margins in trauma applications.
- Resorption Rate Mismatch:Current ceramic products exhibit unpredictable degradation profiles in load-bearing defects, limiting adoption in long-bone trauma.
Strategic Opportunities
- Patient-Specific Implants:3D-printed bone scaffolds with tunable porosity are opening premium segments in craniomaxillofacial reconstruction.
- India's Trauma Infrastructure:Government hospital procurement programs are creating first-mover advantages for ceramic granule suppliers in tier-2 cities.
- Biologics-Synthetic Convergence:Collagen-hydroxyapatite composites incorporating growth factors command pricing premiums in spine-specific delivery systems.
Industry Challenges
- ISO 10993 Testing Backlogs:Biological evaluation protocol complexity is stretching preclinical timelines for novel polymer matrices.
- Sales Force Reconfiguration:Bundled service contracts demand hybrid technical-commercial competencies that traditional orthopedic device representatives lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Substitutes Market |
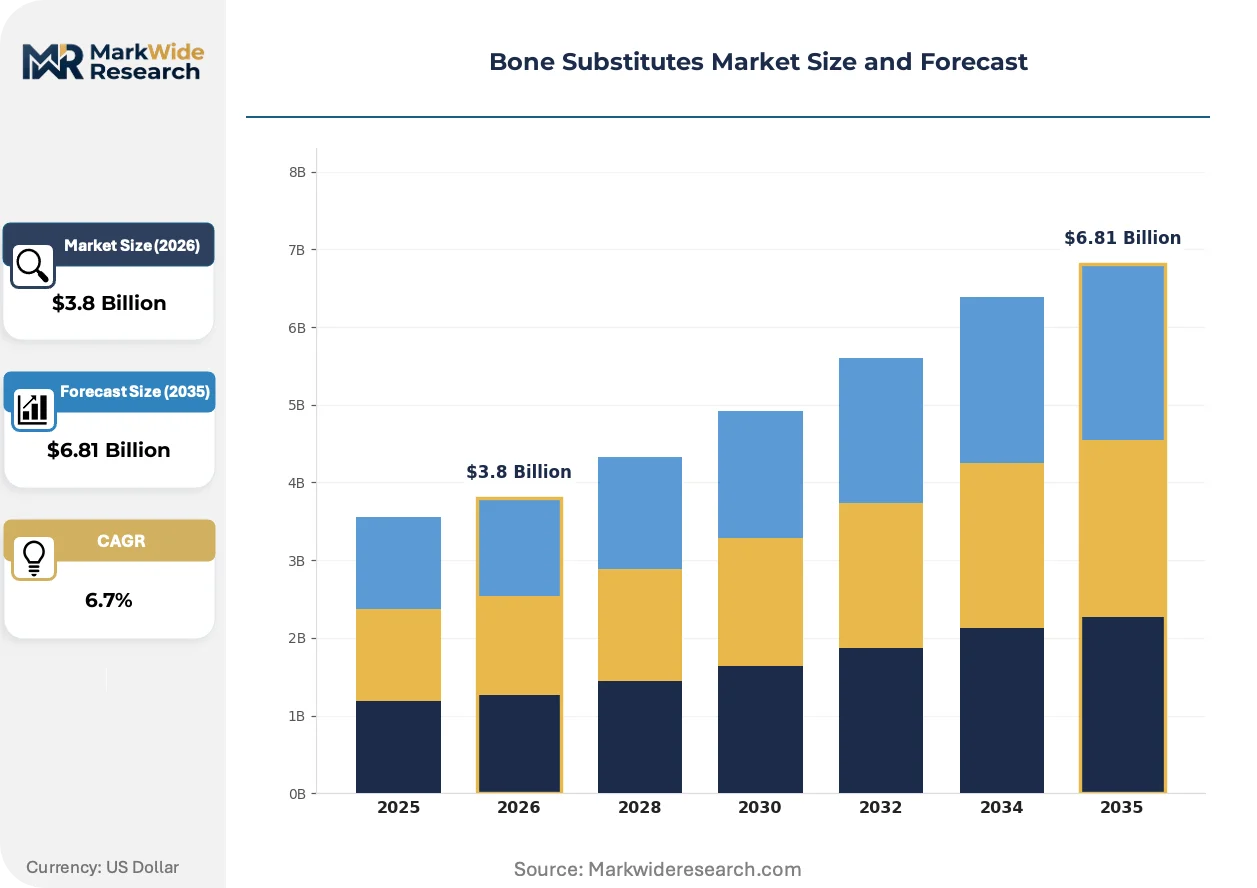
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramics, Polymers, Composites, Metals Application: Trauma Surgery, Orthopedic Surgery, Dental Procedures, Spine Surgery End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Dental Practices Delivery Mode: Injectable, Pre-packaged, Custom-fabricated, Granular |
| Companies Covered | Medtronic PLC, Stryker, Zimmer Biomet, DePuy Synthes Companies, Smith & Nephew plc, Bioventus, AlloSource, SeaSpine, Orthofix Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Substitutes Market Emerging Trajectories
Manufacturers are racing to develop resorbable composites with mechanical properties matching cortical bone, while regulatory bodies on both sides of the Atlantic tighten biocompatibility evidence requirements. These parallel pressures are compressing R&D cycles and reshaping competitive positioning.
3D-printed patient-specific scaffolds with architected porosity are rendering obsolete standardized granule formulations in craniomaxillofacial and pelvic reconstruction. Academic medical centers in the United States and Switzerland are adopting these platforms for complex defect cases. The technology is compressing operative time and reducing revision rates, forcing granule manufacturers to defend trauma and spinal fusion segments where customization offers limited advantage.
EU MDR Article 10 clinical evidence requirements are mandating prospective data collection for legacy ceramic products previously cleared under the Medical Device Directive. Manufacturers must now generate post-market clinical follow-up studies or risk certificate suspension. Spine applications face the steepest compliance burden, as notified bodies classify structural bone substitutes as Class III devices requiring systematic clinical evaluation.
Hospital procurement committees are consolidating vendor lists to three preferred suppliers per product category, eliminating fragmented purchasing across orthopedic, spine, and trauma service lines. Integrated delivery networks in the United States are driving this consolidation, replacing individual surgeon preference with standardized formularies. Germany's university hospitals are following suit, though academic resistance slows implementation in research-intensive centers.
Bone Substitutes Market Segmentation
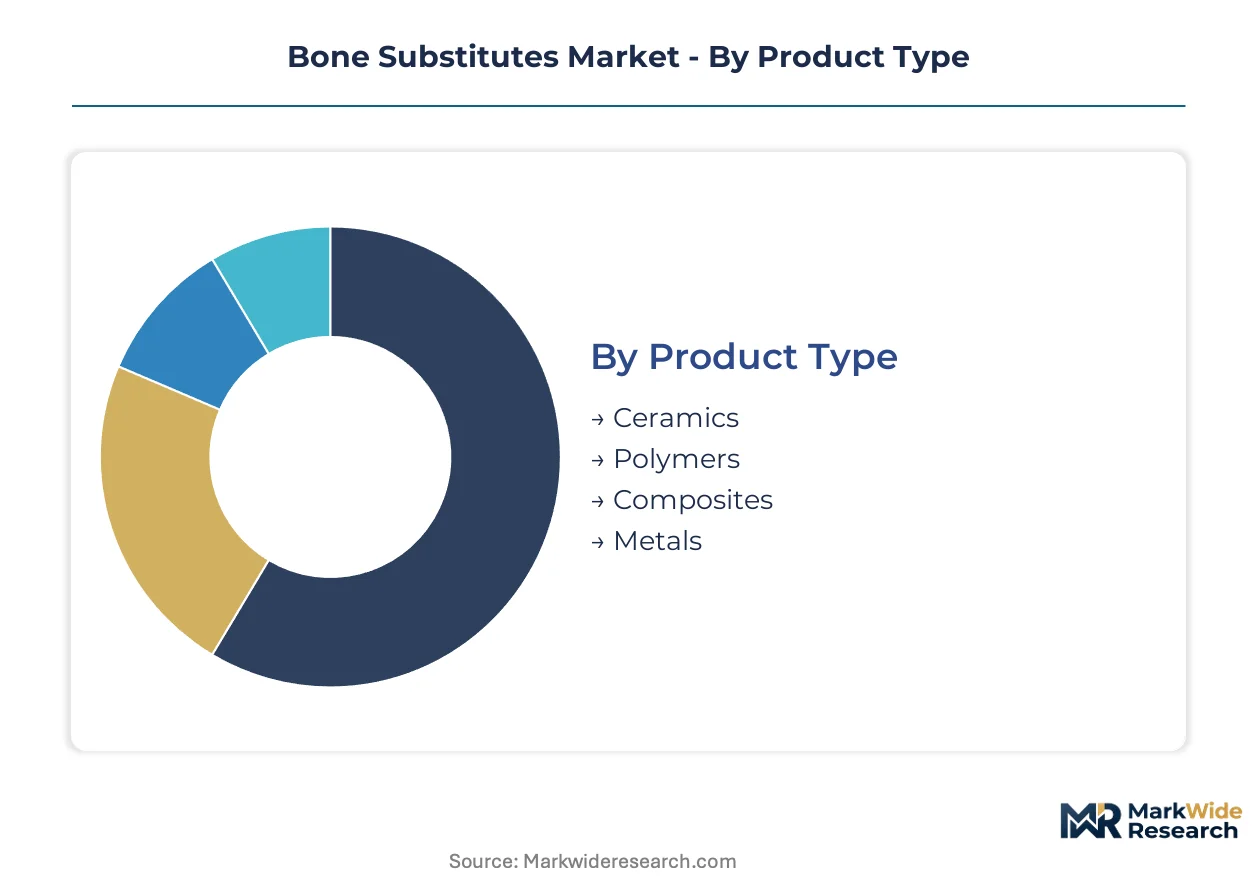
Bone substitutes demand fragments across material chemistry, surgical application, and care setting. Each segmentation axis reveals distinct procurement patterns and pricing power dynamics that shape manufacturer strategy.
Product Type:
Mature ceramic formulations anchor current volume, while emerging polymer and composite platforms attract R&D investment for tunable resorption profiles.
- Ceramics:Hydroxyapatite and beta-tricalcium phosphate formulations dominate spinal fusion and trauma void filling. German trauma surgery centers drive sustained procurement of ceramic granules for revision arthroplasty, though unpredictable degradation in load-bearing defects constrains long-bone adoption.
- Polymers:Resorbable synthetic matrices enable controlled degradation timelines matched to bone remodeling rates. Academic medical centers in Switzerland are piloting polymer-ceramic hybrids for craniomaxillofacial reconstruction, where tunable mechanical properties command pricing premiums.
- Composites:Collagen-hydroxyapatite blends with bioactive additives bridge osteoconductive scaffolding and osteoinductive signaling.
- Metals:Titanium and magnesium alloys serve permanent structural applications where load-bearing capacity exceeds resorbable material limits.
Ceramics retain volume leadership; composites hold the steepest expansion curve.
Application:
Cost tier stratification separates premium-priced spinal procedures from commoditized trauma repair, with dental and orthopedic applications occupying intermediate positions.
- Spine Surgery:Structural fusion applications generate the highest pricing per gram due to regulatory classification as Class III devices under EU MDR and demanding mechanical performance requirements. FDA 510(k) clearance pathways accelerate U.S. commercialization for ceramic and composite interbody spacers.
- Trauma Surgery:Void filling in acute fracture management competes primarily on procurement cost against demineralized bone matrix from U.S. tissue bank networks. Standardized granule formulations dominate, with limited differentiation beyond handling characteristics.
- Orthopedic Surgery:Joint reconstruction and revision arthroplasty applications favor ceramic-based substitutes for osseointegration with metallic implants.
- Dental Procedures:Ridge augmentation and sinus lift applications utilize smaller volumes with specialized handling requirements for intraoral placement.
Trauma surgery commands the largest procedure volume; spine surgery delivers the highest revenue per case.
End User:
Customer type determines service bundling requirements and sales force configuration, with integrated delivery networks consolidating purchasing authority across hospital systems.
- Hospitals:Academic medical centers in the United States and university hospitals in Germany drive adoption of patient-specific 3D-printed scaffolds for complex defect reconstruction. Procurement committees are narrowing vendor lists to three preferred suppliers per category, eliminating fragmented purchasing across service lines.
- Orthopedic Clinics:Ambulatory settings concentrate demand for injectable and pre-packaged formats that minimize preparation time. Bundled contracts now incorporate surgical training and graft handling services previously monetized separately.
- Ambulatory Surgical Centers:Cost-sensitive environments favor standardized granules with simplified delivery systems for spinal fusion and trauma procedures.
- Dental Practices:Specialized handling training requirements create stickiness with established supplier relationships for ridge augmentation products.
Hospitals absorb the majority of premium product volume; orthopedic clinics are gaining share fastest in outpatient migration.
Delivery Mode:
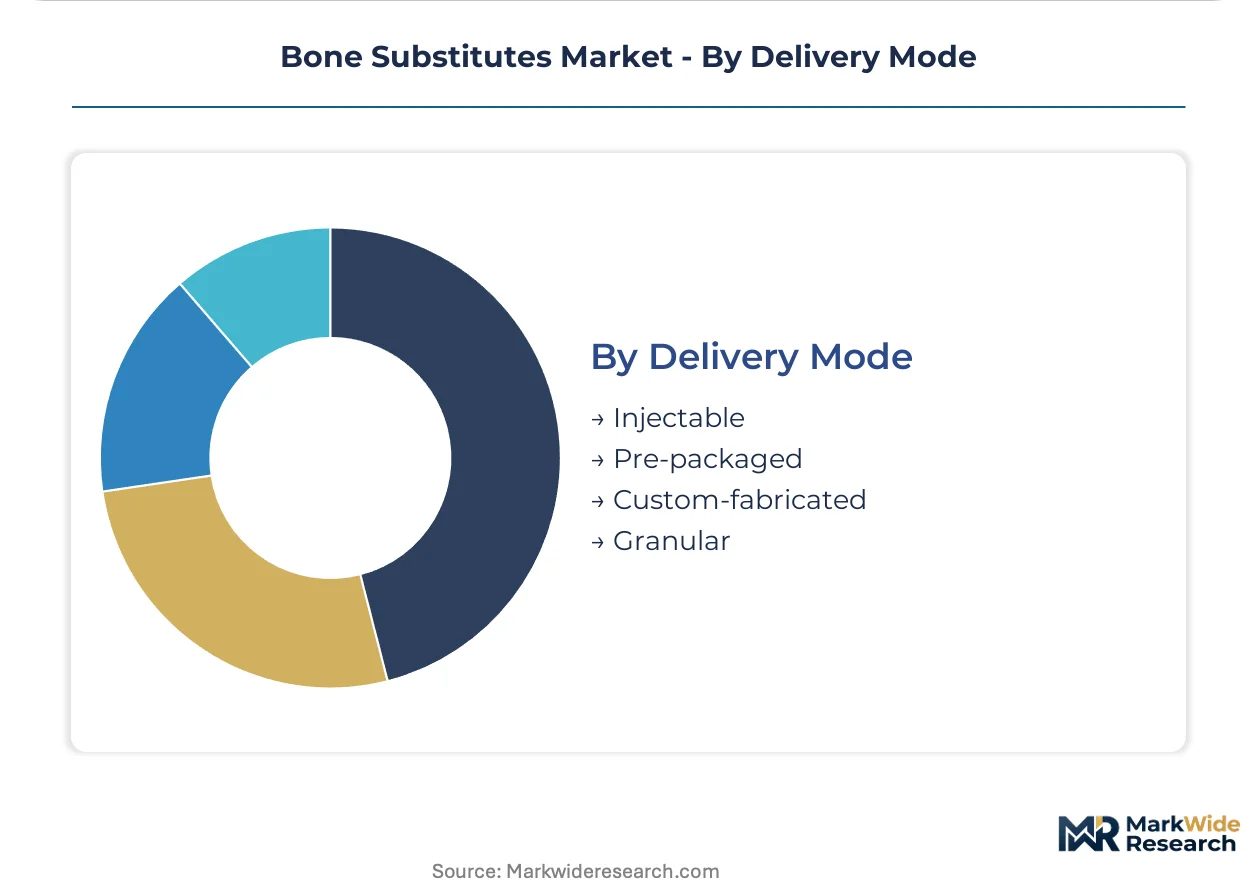
Supply concentration favors pre-packaged and granular formats with established manufacturing scale, while custom-fabricated platforms require capital-intensive production infrastructure.
- Pre-packaged:Sterile, ready-to-use configurations dominate high-volume trauma and spinal fusion applications. Manufacturing scale economies in the United States and Germany support cost-competitive positioning against allograft alternatives.
- Custom-fabricated:3D-printed patient-specific scaffolds with architected porosity are displacing standardized formulations in craniomaxillofacial and pelvic reconstruction. Swiss and U.S. academic centers are adopting these platforms for operative time compression and revision rate reduction.
- Injectable:Paste and putty formulations enable minimally invasive placement through small access corridors.
- Granular:Particulate formats offer surgeon-controlled packing density for irregular defect geometries.
Pre-packaged formats retain volume leadership; custom-fabricated delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trauma surgery procurement in Germany tolerates premium ceramic pricing, while United States hospital systems squeeze margins through consolidated vendor lists. Spine applications in Switzerland command the steepest premiums, with Indian tier-2 cities representing the most price-sensitive expansion frontier.
United States
Academic medical centers in Boston and the Research Triangle drive adoption of patient-specific 3D-printed scaffolds for complex pelvic reconstruction. FDA 510(k) clearance pathways accelerate commercialization timelines for ceramic interbody spacers, compressing regulatory investment cycles. Integrated delivery networks in Texas and California are narrowing vendor lists to three preferred suppliers per category, eliminating fragmented purchasing across orthopedic service lines.
Germany
University hospitals in Bavaria and North Rhine-Westphalia sustain ceramic granule demand for revision arthroplasty procedures, where osseointegration requirements favor hydroxyapatite formulations. EU MDR notified body bottlenecks are extending certification timelines for novel bioactive glass formulations by 12-18 months. The trauma surgery cluster around Berlin-Brandenburg is expanding ceramic-based substitute adoption for joint reconstruction, creating sustained demand pull.
Switzerland
Academic centers in Zurich and Geneva pilot polymer-ceramic hybrids for craniomaxillofacial reconstruction, where tunable mechanical properties command pricing premiums. Swissmedic classification aligns with EU MDR for structural bone substitutes, imposing Class III device requirements. The Basel pharmaceutical-industrial corridor is attracting biologics-synthetic convergence R&D, with collagen-hydroxyapatite composites incorporating growth factors.
India
Government hospital procurement programs in tier-2 cities such as Jaipur and Lucknow are creating first-mover advantages for ceramic granule suppliers. CDSCO medical device regulations are tightening biocompatibility evidence requirements, though timelines remain shorter than EU MDR pathways. The trauma infrastructure expansion in Maharashtra and Karnataka is standardizing procurement around pre-packaged formats that minimize surgical preparation time.
China
NMPA priority review pathways for breakthrough medical devices are accelerating market access for 3D-printed bone scaffolds in Shanghai and Beijing. Domestic manufacturers in the Yangtze River Delta are scaling production of hydroxyapatite granules for spinal fusion applications. Hospital procurement centralization under volume-based purchasing is compressing pricing for standardized ceramic formulations, favoring suppliers with captive manufacturing scale.
Bone Substitutes Market Vendor Landscape
Capability concentration sits with integrated orthopedic conglomerates; scale advantage sits with diversified medical technology platforms. The vendor base stratifies across three tiers: trauma-spine generalists with bundled service contracts, ceramic formulation specialists with deep surgeon training relationships, and biologics-synthetic hybrid developers targeting premium spine segments. Dominant competitive moves include backward integration into raw material processing and strategic partnerships with 3D printing platform providers.
Among diversified medical technology platforms, Medtronic PLC, Stryker, and Zimmer Biomet occupy positions that exemplify distinct strategic archetypes. Medtronic represents the biologics-synthetic convergence vector, anchoring its approach through spine-specific delivery systems. Stryker exemplifies the integrated trauma platform model, leveraging hospital purchasing consolidation to bundle surgical training into core contracts. Zimmer Biomet sits within the ceramic formulation specialist tier, with deep positioning in joint reconstruction materials. These three entities collectively illustrate how scale, specialization, and convergence strategies are partitioning competitive terrain.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker |
| Zimmer Biomet |
| DePuy Synthes Companies |
| Smith & Nephew plc |
| Bioventus |
| AlloSource |
| SeaSpine |
| Orthofix Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor connects German ceramic precursor suppliers to Swiss polymer formulators, with transport cost volatility amplifying price spreads between hydroxyapatite granule producers and downstream composite manufacturers. This logistics tension concentrates pricing power among integrated manufacturers with captive raw material processing, while forcing smaller compounders toward contract-based volume commitments that lock in margin protection.
Pricing Analysis
Long-term offtake contracts dominate procurement between ceramic precursor suppliers and major device manufacturers, insulating against hydroxyapatite price swings while spot purchasing persists for beta-tricalcium phosphate in trauma applications. Three-tier pricing structure across premium, standard, and economy levels separates spine-specific delivery systems from commoditized granules, with FDA 510(k) certification tier and surgical training bundling as primary differentiation drivers. Cost compression in trauma void fillers is intensifying because tissue bank networks are expanding demineralized bone matrix availability. Ambulatory surgical centers exhibit the highest price sensitivity; academic medical centers in Switzerland and the United States tolerate premium positioning for patient-specific scaffolds.
Supply Chain Analysis
Upstream feedstock production of synthetic hydroxyapatite and beta-tricalcium phosphate concentrates in Germany, the United States, and Japan, with Chinese manufacturers scaling ceramic precursor output for domestic spinal fusion demand. Formulation draws from pharmaceutical-grade calcium phosphate salts, collagen matrices sourced from bovine and porcine processing, and bioactive glass precursors subject to EU F-Gas Regulation processing constraints. Single-source vulnerability sits with notified body certification capacity for novel polymer matrices under EU MDR. Distribution runs through integrated delivery networks in the United States and hospital procurement committees in Germany that consolidate vendor lists to three preferred suppliers per category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone substitutes market is approaching a platform-economics inflection where interoperability between 3D printing hardware and biologics-synthetic formulation libraries will determine competitive survival. Ecosystem control now hinges on software-defined scaffold design platforms rather than standalone material patents.
For Market Incumbents: Build switching-cost moats by embedding surgical training and graft handling services into multi-year hospital system contracts that resist vendor consolidation. Backward integration into hydroxyapatite precursor synthesis secures margin protection against ceramic raw material price volatility. Capacity addition in India's tier-2 trauma infrastructure captures government procurement momentum before domestic manufacturers scale. R&D investment in tunable resorption polymer-ceramic hybrids defends against 3D-printed patient-specific scaffold displacement in craniomaxillofacial reconstruction.
For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 government hospital procurement programs where CDSCO regulatory timelines remain shorter than EU MDR pathways and ceramic granule standardization creates first-mover advantages. Target the biologics-synthetic convergence segment in Swiss and German academic centers, where collagen-hydroxyapatite composites with growth factor incorporation command pricing premiums underserved by incumbent trauma-spine generalists. Partner with 3D printing platform providers to bypass capital-intensive custom fabrication infrastructure and access architected porosity technology through licensing rather than in-house development.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core bone substitute assets amid orthopedic portfolio rationalization. Long-term viability in this market rests on regulatory navigation capability and surgeon training relationship depth rather than manufacturing scale alone. Acquisition candidates with EU MDR Article 10 clinical evidence packages for legacy ceramic products offer defensive positioning against notified body bottlenecks. Monitor FDA breakthrough device designation trends for 3D-printed scaffold platforms as the signal indicating platform-economics winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts in Texas and California consolidate purchasing authority across orthopedic service lines. |
| CE Marking Pathway | EU MDR notified body capacity constraints extend certification timelines for novel bioactive glass formulations. |
| Backward Integration | In-house production of hydroxyapatite precursors insulates German manufacturers from ceramic raw material cost volatility. |
| Software Companion Development | 3D-printed scaffold design platforms with surgeon-facing interfaces compress operative time in craniomaxillofacial reconstruction. |
| Reimbursement Strategy | CMS Medicare coding alignment for patient-specific implants determines commercial viability in U.S. academic medical centers. |
Methodological Framework
Desk research of FDA 510(k) filings, EMA MDR certification databases, and hospital procurement contract records preceded structured interviews with orthopedic surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Primary fieldwork with ceramic formulation specialists and polymer matrix developers in Germany, Switzerland, and the United States validated secondary data on resorption rate performance and degradation profile reliability. Bottom-up procedure volume estimates across spinal fusion, trauma surgery, and joint reconstruction applications were triangulated against top-down manufacturer revenue disclosures.
Assumptions held fixed include EU MDR notified body capacity constraints extending certification timelines and FDA 510(k) clearance pathways maintaining current review velocity for bone void fillers across the analysis window. The analytical framework modeled segmentation across material chemistry, surgical application, care setting, and delivery mode with regional regulatory cluster as an additional dimension. CAGRs were derived from procedure volume growth trajectories and pricing evolution in premium versus commoditized segments. Forecast inputs incorporated revision arthroplasty volume expansion in German trauma centers and outpatient migration trends in U.S. orthopedic clinics.
Sensitivities concentrate around notified body capacity resolution in Europe, NMPA priority review pathway expansion in China, and CDSCO regulatory tightening timelines in India. Forecasts reflect assumptions about ceramic granule standardization in trauma applications and 3D-printed scaffold adoption curves in craniomaxillofacial reconstruction. Material shifts in EU MDR classification interpretation or FDA breakthrough device designation criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomaterials
Middle East and Africa Orthopedic Biomaterial Market
Biomaterials
Global Medical Engineered Materials Market
Biomaterials
Nerve Repair Biomaterials Market
Biomaterials
Self-Healing Materials Market
Biomaterials
Global Biocompatible Materials Market
Biomaterials
Orthopedic Bone Defect Repair Materials Market
Biomaterials
Pulp Cells Market
Biomaterials
Bioceramics and Hydroxyapatite Market
Biomaterials
Global Extracellular Matrix Patches Market
Biomaterials
Biomimetic Peptides Market
Biomaterials
Global Bioactive Materials Market
Biomaterials
Calcium Phosphate Market
Biomaterials
Global Collagen and HA Based Biomaterial Market
Biomaterials
Global Bone Grafts and Substitutes Market
Biomaterials
Biomaterial Wound Dressing Market
Biomaterials
Global Biomaterials Market