
 Dental Amalgamators Market | 2026-2036
Dental Amalgamators Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Amalgamators Market Analytics
Market Dynamics
Dental clinics are reorganizing procurement priorities toward automated mixing systems as group practices and dental service organizations standardize equipment across multiple operatories. Ivoclar Vivadent leverages its integrated restorative materials portfolio to bundle amalgamator sales with alloy consumables. SDI Limited anchors its position through direct distribution in Asia-Pacific dental markets. 3M competes on the strength of its ergonomic digital control interfaces that reduce operator variability.
Product and Technology Landscape
A dental amalgamator is a motorized device that mechanically triturates dental alloy powder with mercury or alloy capsules to produce a homogeneous, plastic amalgam mass for restorative fillings, typically operating at controlled oscillation frequencies between 3,000 and 4,500 cycles per minute to achieve proper amalgamation without overtrituration. Automatic and digital amalgamators command the dominant share of product type revenue due to programmable consistency and reduced mercury exposure risk, while portable units represent the fastest-growing configuration for mobile dental outreach and field military dentistry. Electrical technology leads the technology segmentation with precise microprocessor-controlled timing, though ultrasonic amalgamation is gaining traction in research institute settings for experimental non-mercury alloy systems.
Regulatory Environment
The FDA Center for Devices and Radiological Health classifies dental amalgamators as Class II medical devices requiring 510(k) premarket notification, while the EU MDR mandates CE marking with enhanced clinical evaluation and post-market surveillance for electrical dental equipment. ISO 7488 specifies dimensional and performance requirements for amalgamators, directly influencing manufacturer design validation protocols and third-party testing expenditures. Stakeholders must monitor evolving mercury restriction policies and alloy composition standards to anticipate product line obsolescence and replacement technology timing.
Market Dynamics
Dental service organizations are consolidating procurement decisions across multi-site networks, replacing individual clinic purchasing with centralized equipment standardization that favors programmable amalgamator platforms over legacy mechanical units.
Growth Catalysts
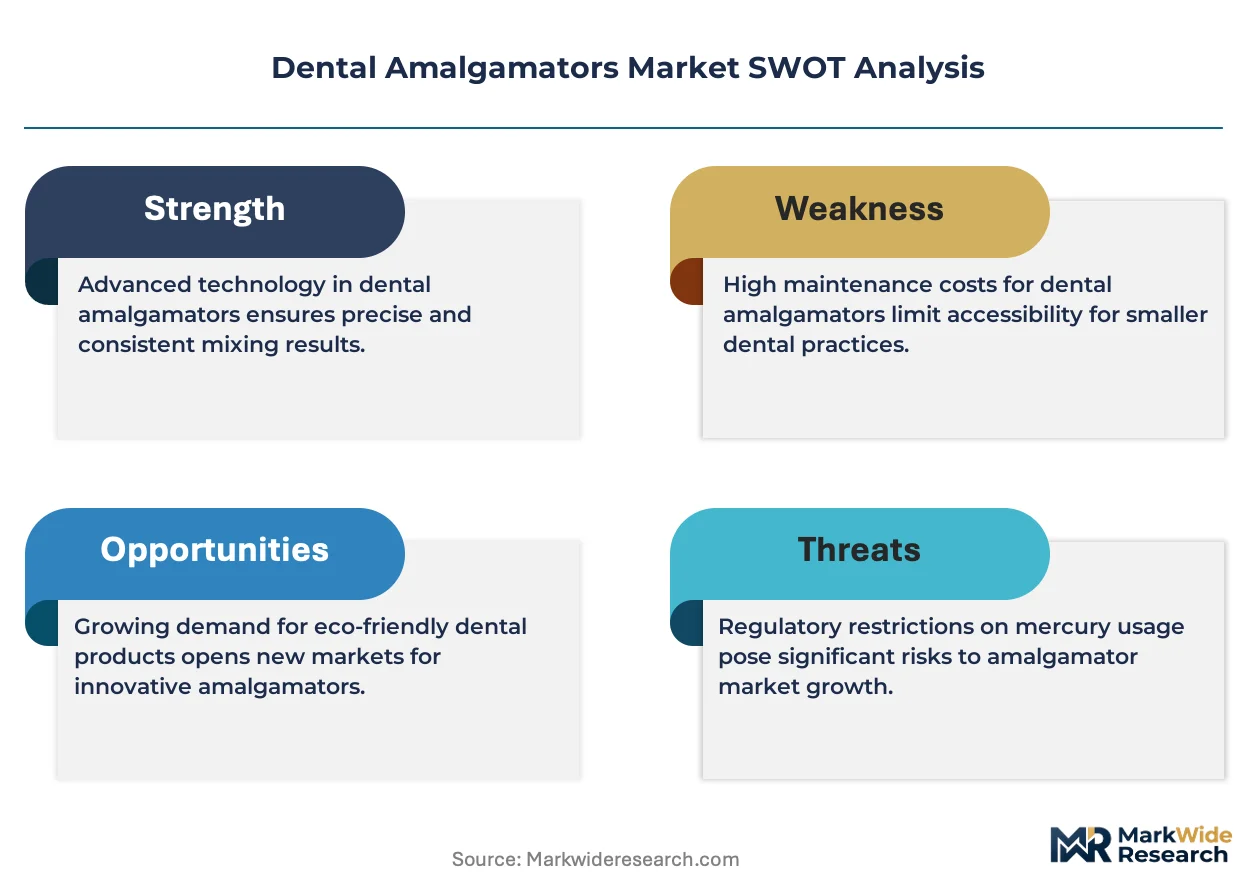
- EU MDR compliance deadlines:The Medical Device Regulation mandates enhanced electrical safety documentation and post-market surveillance, accelerating replacement of pre-2017 amalgamator inventories across European dental clinics.
- Mercury exposure protocols:Occupational health agencies in Germany and the United States enforce stricter workplace vapor limits, driving demand for closed-capsule automatic mixing systems that minimize operator contact.
- Alloy pre-dosed capsules:Pre-proportioned single-use capsules eliminate manual mercury dispensing errors and reduce waste, aligning with lean workflow designs in high-volume group practices.
Market Restraints
- Mercury input volatility:Primary mercury supply concentrates in Kyrgyzstan and China, exposing manufacturers to export restriction risks and price instability that compress margin predictability.
- Composite resin substitution:Tooth-colored restorative materials continue displacing amalgam in anterior applications and pediatric dentistry, narrowing the addressable procedure base for amalgamator-dependent workflows.
- ISO 7488 testing burden:Third-party validation of oscillation frequency consistency and dimensional tolerances adds fixed compliance costs that disadvantage smaller regional equipment suppliers.
Strategic Opportunities
- Rural India clinic expansion:Government health missions and private dental chains are penetrating tier-3 cities and semi-urban centers where portable amalgamators address unreliable electricity and mobile outreach needs.
- Ultrasonic-non-mercury convergence:Research institutes in Japan and Switzerland are piloting ultrasonic activation systems for gallium-based alloys, creating early-mover positioning for next-generation platform developers.
- Direct-to-clinic digital distribution:E-procurement portals and manufacturer-owned web channels bypass traditional dental dealer networks, capturing margin and capturing usage data for predictive maintenance services.
Industry Challenges
- Biomedical equipment technician scarcity:Complex microprocessor-controlled amalgamators require specialized calibration and repair skills that dental clinics struggle to source outside major metropolitan areas.
- Legacy analog integration:Older chairside units lack digital handshake protocols with practice management software, forcing hybrid workflow workarounds during gradual fleet replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Amalgamators Market |
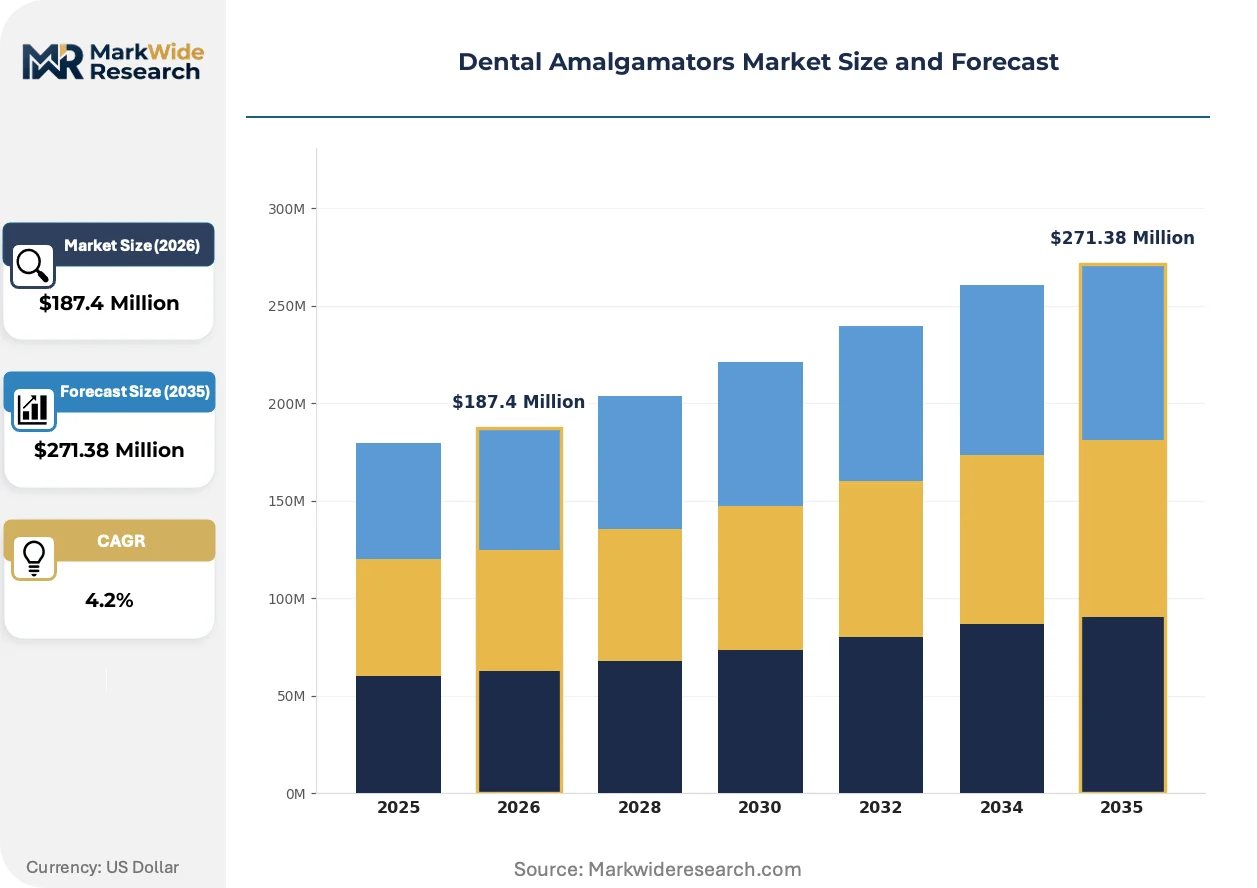
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Amalgamators, Manual Amalgamators, Portable Amalgamators, Digital Amalgamators End User: Dental Clinics, Dental Hospitals, Dental Laboratories, Research Institutes Technology: Electrical, Mechanical, Pneumatic, Ultrasonic Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Capacity |
| Companies Covered | Ivoclar Vivadent, Carlo de Giorgi SRL, Nuova GmbH, MHC TECHNOLOGY, SDI Limited, 3M, Renfert GmbH, Maosheng Medical Equipment Co Ltd, Best Dent Equipment Co Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Amalgamators Market Evolving Landscape
Amalgamator technology is bifurcating between premium digital platforms for consolidated group practices and ruggedized portable units for outreach dentistry, with regulatory pressure on mercury handling accelerating both upgrade paths simultaneously.
Touchscreen programmable interfaces with stored trituration protocols are fragmenting competitive differentiation away from mechanical reliability alone. Large dental service organizations in the United States and Germany specify these units to enforce consistency across fifty-plus operatories. The capability gap between premium digital and basic mechanical models is widening, compressing mid-tier vendor生存空间.
China's NMPA tightened electrical safety testing requirements for imported dental equipment in 2023, extending 510(k)-equivalent documentation timelines by four to six months. Domestic manufacturers with established GB standard compliance are capturing share previously held by European suppliers. The regulatory friction most impacts high-frequency trading companies without localized testing partnerships.
Buying committees at dental service organizations now bundle amalgamator procurement with multi-year alloy supply contracts, displacing independent equipment purchases. Traditional dental dealers lose attach revenue as manufacturers integrate consumables and devices into single-source agreements. This concentration is most visible in the United States, where Heartland Dental and Aspen Dental operating platforms standardize across hundreds of locations.
Dental Amalgamators Market Segmentation
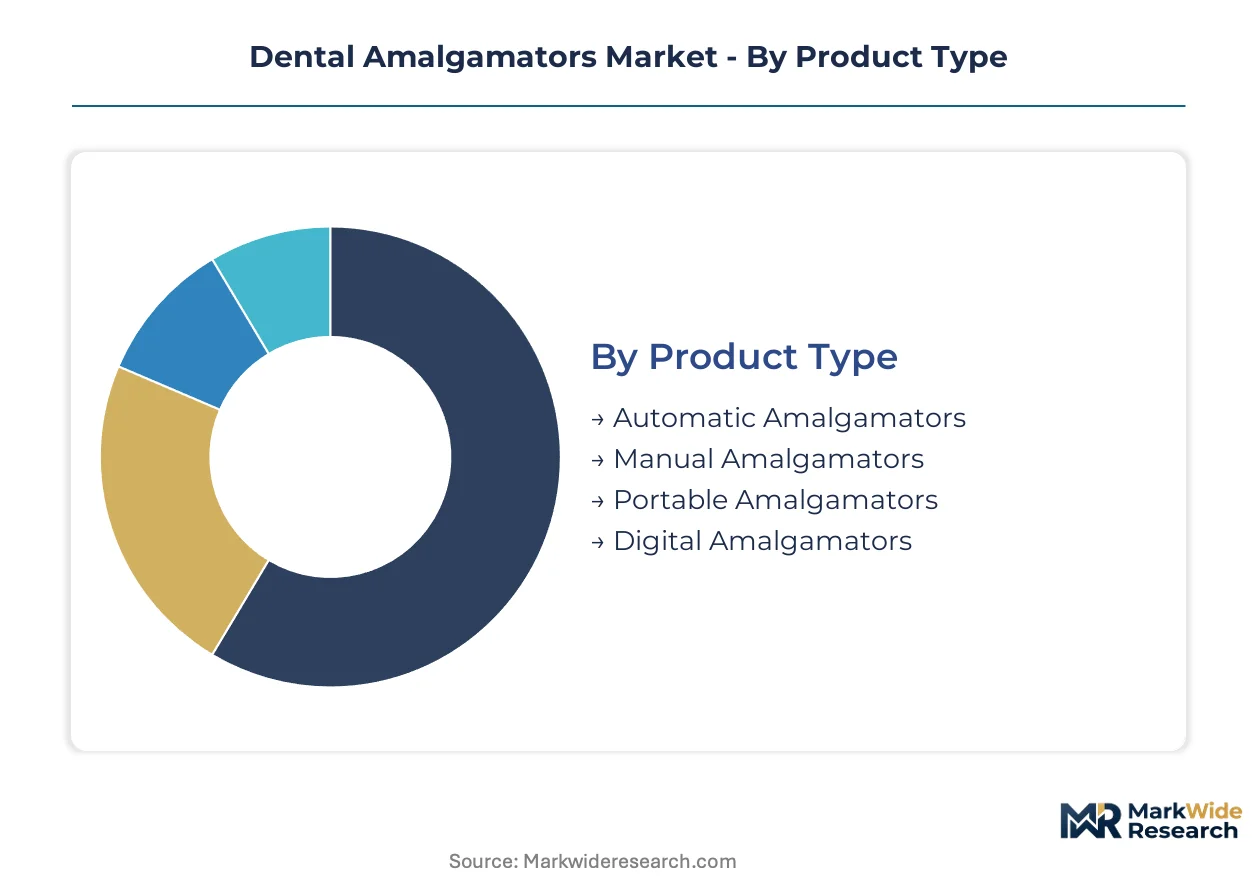
Dental amalgamator procurement varies sharply across clinic types and geographic settings, with product configuration decisions tightly coupled to mercury handling protocols, electricity reliability, and patient volume throughput. Segmentation reveals where premium digital platforms displace legacy units versus where ruggedized portable designs capture emerging demand.
Product Type:
Automatic and digital platforms dominate equipment exports from Germany and the United States, while portable configurations serve domestic markets with unreliable infrastructure or mobile outreach requirements.
- Automatic Amalgamators:These units employ closed-capsule systems with programmable oscillation cycles that eliminate operator variability in trituration timing. Demand concentrates in German and United States dental service organizations where standardized protocols across fifty-plus operatories justify premium procurement. EU MDR electrical safety documentation accelerates replacement of pre-2017 mechanical inventories.
- Digital Amalgamators:Microprocessor-controlled platforms store multiple trituration protocols accessible through touchscreen interfaces, enabling single-button operation for distinct alloy compositions. United States group practices specify these units to enforce consistency across multi-site networks while capturing usage data for predictive maintenance services.
- Manual Amalgamators:Hand-crank mechanical devices persist in cost-constrained settings and backup redundancy roles.
- Portable Amalgamators:Battery-powered ruggedized designs address tier-3 Indian clinics and military field dentistry where grid electricity is intermittent or absent.
Automatic amalgamators hold the largest share; momentum sits with portable configurations.
End User:
Procurement authority is shifting from individual practitioners to centralized buying committees, fragmenting vendor access patterns across customer types.
- Dental Clinics:Private solo and group practices generate the highest unit volume, with consolidation into dental service organizations replacing dispersed purchasing with standardized fleet deployment. United States platforms like Heartland Dental and Aspen Dental specify uniform equipment across hundreds of locations, bundling amalgamator procurement with multi-year alloy supply contracts.
- Dental Hospitals:Academic and public hospital dental departments require high-throughput units with validated maintenance records for regulatory inspection. German university hospitals anchor demand for premium digital platforms with integrated calibration documentation.
- Dental Laboratories:Commercial labs processing outsourced restoration work utilize medium-capacity units for batch consistency validation.
- Research Institutes:Experimental alloy development programs in Japan and Switzerland pilot ultrasonic activation systems for gallium-based mercury alternatives.
Dental clinics command the dominant procurement volume; research institutes are expanding most quickly as non-mercury alloy programs accelerate.
Technology:
Cost tier differentiation separates precision-controlled electrical platforms from mechanical alternatives, with ultrasonic systems occupying an emerging premium research niche.
- Electrical:Microprocessor-controlled timing circuits deliver oscillation frequencies between 3,000 and 4,500 cycles per minute with ±1% consistency, forming the technology backbone for automatic and digital product categories. FDA 510(k) premarket notification requirements and EU MDR CE marking mandates concentrate compliance investment in electrical platform development.
- Mechanical:Spring-motor or hand-crank systems without electronic components serve backup roles and price-sensitive replacement markets.
- Pneumatic:Compressed-air driven units address specific clinic infrastructure configurations in industrial dental settings.
- Ultrasonic:High-frequency vibration systems experimental for gallium-based and other non-mercury alloy activation, currently limited to research institute pilot programs.
Electrical technology captures the dominant revenue position; ultrasonic systems show the steepest expansion trajectory in experimental settings.
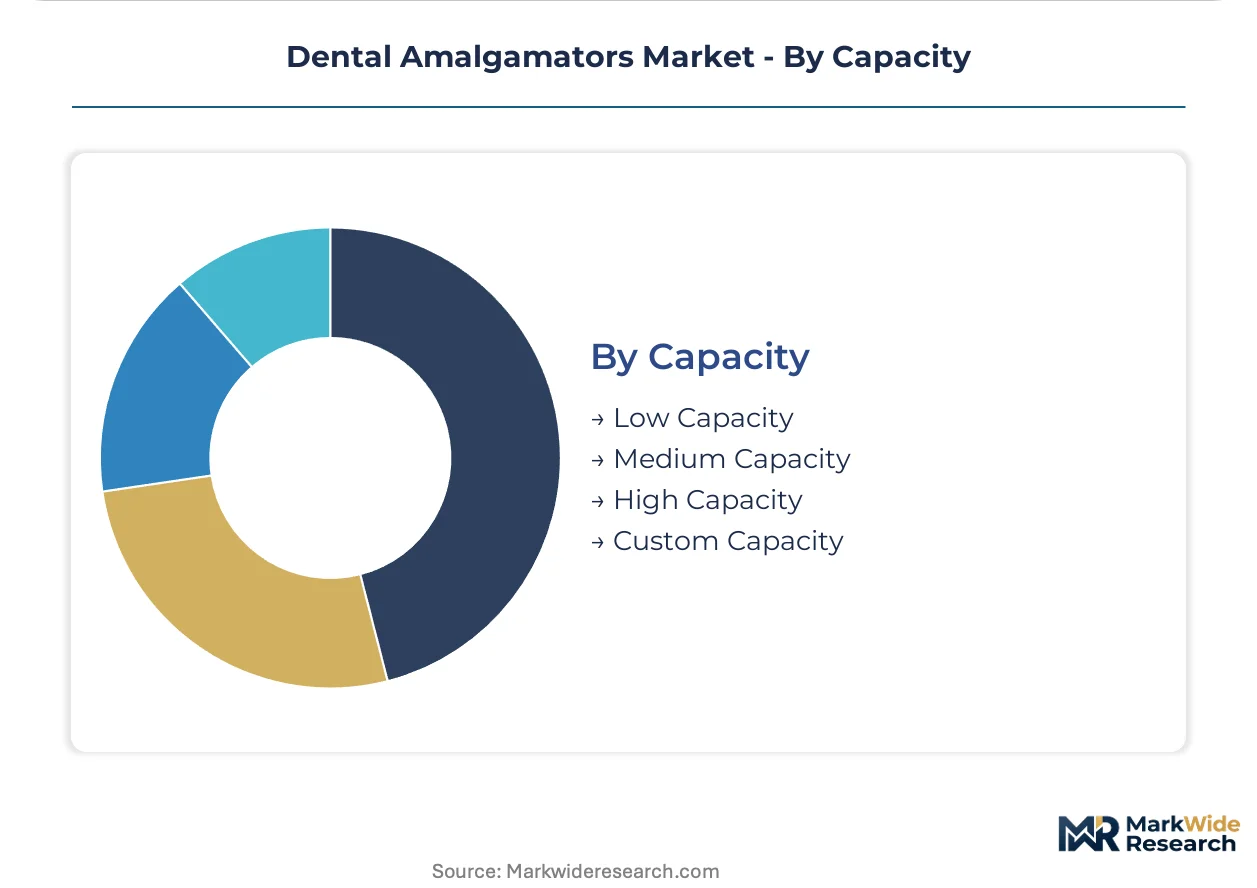
Capacity:
Volume tier alignment matches unit specifications to patient throughput and physical footprint constraints across clinic formats.
- High Capacity:Multi-capsule batch processing units serve dental hospitals and high-volume group practices with continuous operative schedules. German clinic chains deploy these configurations to minimize operator wait times during peak appointment blocks.
- Medium Capacity:Single-capsule units with rapid cycle turnaround dominate standard dental clinic operatories.
- Low Capacity:Compact designs address space-constrained satellite clinics and mobile outreach configurations.
- Custom Capacity:Modular units with adjustable capsule holders serve specialized research applications and military field dentistry with variable throughput requirements.
Medium capacity units represent the standard procurement choice; custom capacity configurations are gaining share fastest in mobile and research applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered dental amalgamators to United States group practices and Chinese distributors, establishing the dominant trade corridor in this medical device category. Equipment flows concentrate through Frankfurt logistics hubs before reaching consolidated dental service organizations across North American metropolitan markets.
United States
Dental service organizations like Heartland Dental and Aspen Dental drive procurement volume through centralized buying committees that standardize equipment across hundreds of operatories. FDA 510(k) premarket notification requirements filter out non-compliant imports, favoring established suppliers with regulatory documentation capabilities. Dallas and Phoenix anchor the largest clinic consolidation activity, with equipment replacement cycles accelerating as group practices retire legacy mechanical units.
Germany
University hospitals in Berlin and Munich specify premium digital platforms with integrated calibration documentation for regulatory inspection readiness. EU MDR compliance deadlines force retirement of pre-2017 amalgamator inventories, compressing replacement demand into a narrow window through 2026. The Stuttgart industrial corridor hosts precision motor and microprocessor suppliers that feed upstream into domestic equipment manufacturing.
China
NMPA tightened electrical safety testing requirements for imported dental equipment in 2023, extending documentation timelines by four to six months for European suppliers. Domestic manufacturers with established GB standard compliance capture share in tier-2 and tier-3 city clinic expansions. Shanghai distributors increasingly bypass traditional dealer networks through direct-to-clinic digital procurement portals.
India
Government health missions and private dental chains penetrate tier-3 cities and semi-urban centers where portable amalgamators address unreliable grid electricity. CDSCO medical device registration requirements concentrate import activity through Mumbai and Delhi customs zones with established testing laboratory relationships. Bangalore-based equipment assemblers source battery systems from local electronics suppliers for ruggedized mobile configurations.
Japan
Research institutes in Osaka and Tokyo pilot ultrasonic activation systems for gallium-based mercury alternatives, creating early demand for experimental platform development. PMDA consultation procedures for novel dental devices extend validation timelines, favoring domestic manufacturers with established quality management systems. The Nagoya manufacturing belt supplies precision vibration components for next-generation amalgamation technology.
Dental Amalgamators Market Competitive Landscape
Player mix skews toward integrated restorative materials suppliers and specialized dental equipment fabricators. Market structure concentrates around three to five dominant suppliers with established regulatory dossiers, while regional assemblers compete on price in emerging markets. Strategic archetypes separate bundled consumables-device suppliers from standalone equipment specialists and research-focused technology developers. Competitive moves center on multi-year alloy supply contract bundling and direct digital distribution channel establishment.
Among integrated materials suppliers, Ivoclar Vivadent and 3M exemplify the bundled portfolio archetype, leveraging consumables relationships to anchor equipment placement. SDI Limited occupies a position within Asia-Pacific direct distribution specialists, while Renfert GmbH and Nuova GmbH represent German precision engineering fabricators with established EU MDR compliance capabilities. These named entities illustrate how competitive positioning fragments across geographic specialization and vertical integration strategies rather than converging on uniform business models.
| Leading Market Players |
|---|
| Ivoclar Vivadent |
| Carlo de Giorgi SRL |
| Nuova GmbH |
| MHC TECHNOLOGY |
| SDI Limited |
| 3M |
| Renfert GmbH |
| Maosheng Medical Equipment Co Ltd |
| Best Dent Equipment Co Limited |
| Others |
Value Network & Pricing Analysis
EU MDR electrical safety documentation gates supplier qualification while simultaneously stratifying price tiers between compliant and non-compliant equipment portfolios. Manufacturers absorbing third-party ISO 7488 validation costs pass these through to premium digital platform pricing, compressing margins for regional assemblers lacking established regulatory dossiers.
Pricing Analysis
Current-generation digital amalgamators with touchscreen programmable interfaces command substantial premiums over prior-generation mechanical units, while next-generation ultrasonic platforms for experimental alloy systems occupy emerging ultra-premium positioning. Pricing stratifies across premium, standard, and economy tiers driven by certification level — FDA 510(k) premarket notification tier versus CE marking tier versus non-certified regional alternatives — and volume scale through dental service organization fleet contracts. Cost compression in mid-tier mechanical units is intensifying because Chinese domestic manufacturers with established GB standard compliance are capturing price-sensitive tier-2 and tier-3 city clinic demand. Solo practitioners and small group practices in semi-urban India exhibit highest price sensitivity, while United States dental service organizations like Heartland Dental and Aspen Dental demonstrate lowest sensitivity due to standardized procurement budgets and multi-year alloy bundling agreements.
Supply Chain Analysis
China and Germany anchor precision motor and microprocessor component fabrication for electrical amalgamator platforms, while the United States concentrates final assembly and regulatory documentation capabilities. Mercury sourcing draws from Kyrgyzstan and Chinese primary production, with alloy pre-dosed capsule manufacturing resting on Japanese and Swiss precision metalworking. Single-source vulnerability concentrates in mercury supply given export restriction risks from dominant producers. Distribution runs through Frankfurt logistics hubs for European-manufactured equipment reaching United States dental service organizations, with Shanghai distributors increasingly bypassing traditional dealer networks through direct-to-clinic digital procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate composite resin substitution eroding amalgam's addressable procedure base while defending equipment placement against emerging ultrasonic platform developers. The imperative centers on locking in consumables-device bundling before non-mercury alloy research programs reach commercial viability.
For Market Incumbents: Secure multi-year alloy supply contract bundling with dental service organizations to anchor equipment placement against standalone equipment specialists. Deepen backward integration into pre-dosed capsule manufacturing to capture consumables margin and create switching costs. FDA 510(k) premarket notification investment serves as the critical lever to filter out price-competitive regional entrants lacking regulatory documentation capabilities. For New Entrants and Emerging Players: Differentiate on ruggedized portable configurations for tier-3 Indian clinics and military field dentistry where grid electricity unreliability creates white-space demand. Target research institute pilot programs in Japan and Switzerland with ultrasonic activation systems for gallium-based mercury alternatives. Direct-to-clinic digital distribution bypassing traditional dealer networks offers the most penetrable go-to-market angle for margin capture and usage data accumulation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR compliance investment and ISO 7488 third-party validation requirements, favoring scaled incumbents with established regulatory dossiers over capital-constrained regional assemblers. Acquisition target archetype: German precision engineering fabricators with integrated restorative materials portfolios and established CE marking capabilities. The signal to watch is NMPA electrical safety testing timeline extensions for imported equipment, which accelerates domestic Chinese manufacturer share capture and compresses European supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR compliance deadlines compress replacement demand into narrow windows favoring prepared suppliers. |
| Hospital System Partnership | German university hospitals anchor premium digital platform demand with integrated calibration documentation requirements. |
| Software Companion Development | Touchscreen programmable interfaces with stored trituration protocols fragment competitive differentiation beyond mechanical reliability. |
| Backward Integration into Capsules | Pre-dosed single-use capsule manufacturing captures consumables margin and creates equipment switching costs. |
| Direct-to-Clinic Digital Distribution | Manufacturer-owned web channels bypass traditional dental dealer networks and capture usage data for predictive maintenance services. |
Research Methodology
Operator-level perspectives from dental clinic procurement managers, biomedical equipment technicians, dental service organization buying committee members, and alloy consumables sales directors anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) premarket notification filings, EU MDR technical documentation databases, NMPA import registration records, and ISO 7488 third-party test reports. Bottom-up equipment unit demand modeling and top-down restorative materials market sizing provided triangulation across the analysis window.
Sensitivity analysis around mercury restriction policy timing and dental service organization consolidation velocity informed scenario-weighted projections. Segmentation dimensions modeled span product type, end user category, technology generation, and capacity tier across geographic regulatory clusters. CAGRs derived from fitted growth curves applied to base-year market estimates, with dental clinic replacement cycle timing and alloy pre-dosed capsule adoption rates serving as key forecast inputs.
Material uncertainties — mercury export restriction implementation, composite resin substitution acceleration, and ultrasonic non-mercury alloy commercialization timing — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory compliance deadline adherence and dental service organization procurement centralization continuity. Recalibration cycles align with material shifts in EU MDR enforcement intensity and primary mercury supply geopolitics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Calipers Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Dental Hand Tools Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Dam Market
Dental Devices
Dental Impression System Market