
 Dental Rapid Prototyping Systems Market | 2026-2036
Dental Rapid Prototyping Systems Market Size, Share, and Industry Trends Forecast 2026-2036
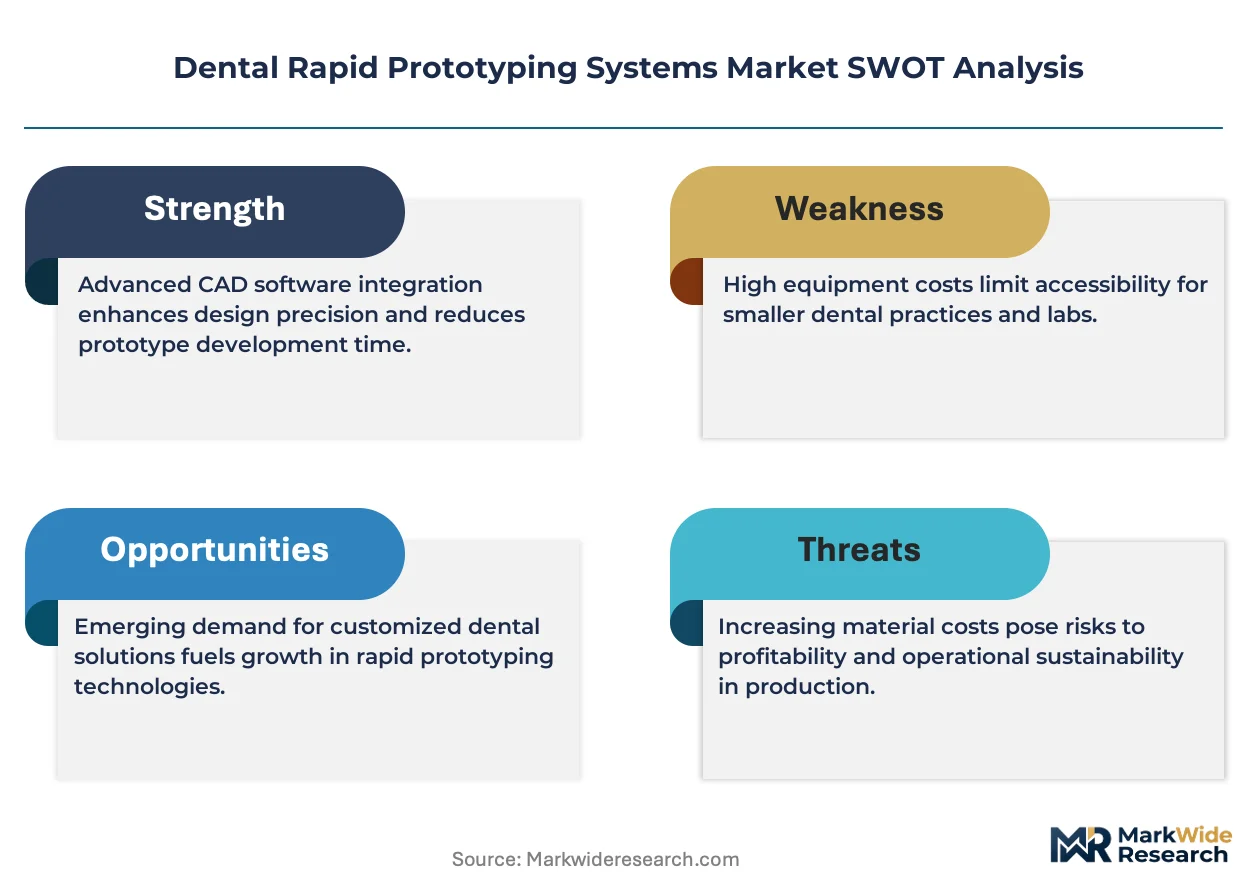
Dental Rapid Prototyping Systems Market Analysis
Subscription-based equipment leasing is tilting competitive dynamics toward mid-sized dental groups that previously lacked capital for in-house prototyping. Stratasys leverages its polymer expertise to anchor high-throughput production lines in commercial dental labs. SprintRay competes through tightly integrated resin-and-printer ecosystems that reduce calibration overhead for clinical users.
Dental rapid prototyping systems encompass additive manufacturing hardware, design software, and consumable materials that fabricate patient-specific dental devices from digital impressions. SLA and DLP technologies dominate crown-and-bridge applications due to micron-level accuracy and smooth surface finishes suitable for ceramic coating. FDM occupies a narrower niche in orthodontic model production where speed outweighs aesthetic demands. Dental labs remain the largest end-user segment, though clinic-based adoption is accelerating fastest as desktop unit costs decline and biocompatible material portfolios widen.
FDA 510(k) clearance requirements govern resin biocompatibility and printer validation for intraoral use, while ISO 13485 quality management standards shape supplier qualification for device manufacturers. The EU Medical Device Regulation imposes stricter clinical evidence thresholds on custom-made implant components, affecting export-oriented dental lab strategies. Stakeholders must monitor evolving material-specific regulatory precedents as chairside printing erodes the traditional lab-clinic boundary.
Market Dynamics
Chairside 3D printing adoption by dental clinics is collapsing the traditional lab-clinic boundary, forcing equipment suppliers to reconfigure service models and pricing structures around same-day workflow economics.
Growth Catalysts
- FDA 510(k) clearances:Accelerated approvals for biocompatible resins are streamlining clinical validation timelines and expanding printable device categories for intraoral use.
- SLA accuracy thresholds:Micron-level precision in crown-and-bridge applications is eliminating secondary finishing steps and reducing technician labor hours per unit.
- United States dental service organizations:Consolidated procurement by multi-site DSOs is standardizing equipment specifications and driving volume discounts for compatible resin ecosystems.
Market Restraints
- Photopolymer resin cost volatility:Specialized biocompatible formulations carry 3-5x premiums over industrial prototyping resins, compressing clinic margins on high-volume procedures.
- East Asian photopolymer supply concentration:Critical monomer feedstocks and photo-initiator chemicals cluster in China and South Korea, exposing buyers to trade policy disruptions.
- ISO 13485 certification timelines:Quality management system audits for chairside device manufacturing extend market entry by 12-18 months for new resin suppliers.
Strategic Opportunities
- India dental clinic penetration:Chairside adoption remains below 8% in tier-2 and tier-3 cities, creating first-mover positioning for localized resin distribution partnerships.
- AI-driven print parameter optimization:Machine learning convergence with DLP exposure engines is reducing calibration drift and failure rates for non-technical clinical staff.
- Subscription equipment leasing:Asset-light models are unlocking mid-sized dental groups previously excluded by capital barriers to in-house production.
Industry Challenges
- Digital dentistry workflow integration:Intraoral scanner-to-printer data interoperability remains fragmented across proprietary file formats, forcing clinics to maintain redundant software licenses.
- Biocompatibility certification backlog:FDA 510(k) review queues for novel resin chemistries are extending product launch windows beyond manufacturer cash runway projections.
- Post-processing labor bottlenecks:Manual resin washing and UV curing steps resist full automation, constraining true same-day throughput in high-volume practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Rapid Prototyping Systems Market |
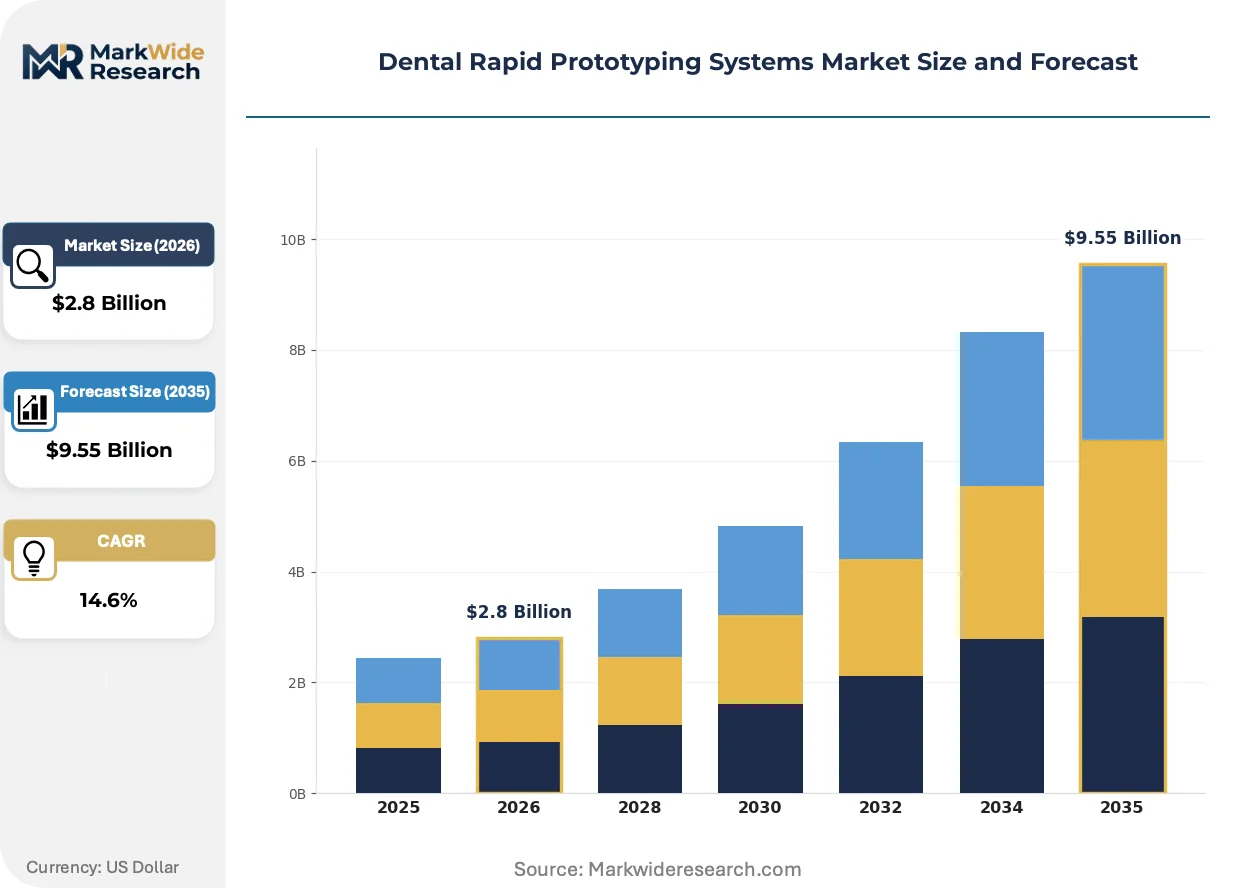
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printers, CAD Software, Materials, Post-Processing Equipment Technology: SLA, SLS, FDM, DLP End User: Dental Labs, Dental Clinics, Educational Institutions, Research Institutes Application: Crown & Bridge, Orthodontics, Implants, Surgical Guides |
| Companies Covered | Dentsply Sirona, Planmeca Oy, 3D Systems Corporation, Straumann Group, Rapid Shape GmbH, 3M, Stratasys, Formlabs, SprintRay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Rapid Prototyping Systems Market Emerging Trajectories
Digital workflow compression is eliminating traditional fabrication bottlenecks. Three developments are redefining how dental devices move from scan to chairside delivery.
Next-generation DLP projectors with 4K resolution and pixel-shifting algorithms are collapsing the accuracy gap between desktop units and industrial lab systems. Mid-sized dental groups in Germany and Japan are adopting these systems at replacement-cycle velocity, bypassing centralized lab networks for crown-and-bridge production. The structural consequence is margin compression for commercial dental laboratories serving routine restorative cases.
The EU Medical Device Regulation is tightening clinical evidence requirements for custom-made implant abutments and surgical guides. Export-oriented dental labs in Italy and Switzerland face expanded technical documentation burdens and notified body audit frequencies. Smaller labs are responding by narrowing product portfolios to exclude high-risk device categories or exiting EU markets entirely.
DSO procurement officers are consolidating vendor relationships around single-source resin-and-printer ecosystems. Equipment suppliers are responding with captive material lock-in strategies and predictive resin replenishment subscriptions. This concentration is most visible in the United States, where multi-site groups now represent the majority of new chairside unit placements.
Dental Rapid Prototyping Systems Market Segmentation
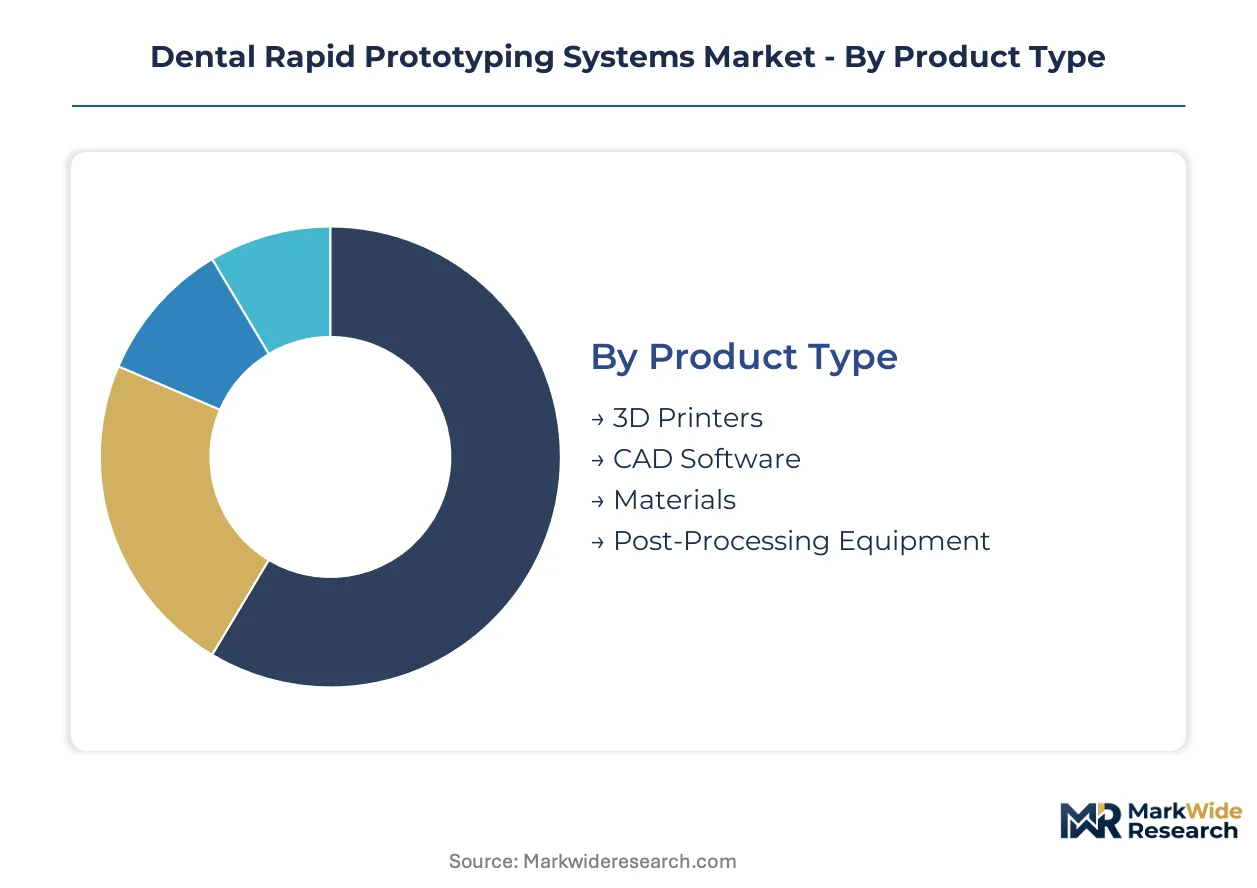
Segmentation reveals how after-sales service intensity varies dramatically across product categories in dental rapid prototyping. Equipment vendors calibrate field engineering teams, resin replenishment logistics, and software update cycles differently for each segment, creating distinct margin profiles and customer lock-in mechanisms.
Product Type:
After-sales service intensity peaks with hardware systems requiring calibration maintenance and resin compatibility management, while software and materials demand lighter touch but higher frequency engagement.
- 3D Printers:Hardware systems integrate light engines, resin vats, and motion platforms requiring quarterly calibration cycles and annual component replacement. Dental clinics in the United States generate concentrated demand for desktop units with embedded remote diagnostics that reduce field service visits.
- CAD Software:Design platforms with automated nesting algorithms and biocompatibility checking modules command recurring license fees. European dental labs prioritize cloud-native solutions with ISO 13485-compliant audit trails for implant component documentation.
- Materials:Photopolymer resins with FDA 510(k) clearance for intraoral use carry formulation-specific handling protocols.
- Post-Processing Equipment:Automated washing and curing stations reduce manual labor but require solvent replenishment and UV lamp replacement cycles.
By volume, Materials leads. By growth pace, 3D Printers is climbing the fastest.
Technology:
Cost tier separation between industrial lab systems and clinical desktop units determines technology selection, with accuracy specifications and throughput requirements driving the investment threshold.
- SLA:Laser-based stereolithography achieves sub-50-micron layer resolution through galvo mirror positioning systems. Crown-and-bridge production in German commercial labs relies on SLA for ceramic-coated restorations demanding flawless surface finishes.
- DLP:Digital light projection with 4K resolution and pixel-shifting algorithms collapses cost-per-unit economics for mid-sized dental groups. Japanese clinics are adopting DLP systems at replacement velocity for same-day crown delivery.
- SLS:Selective laser sintering of nylon powders serves orthodontic model production where mechanical durability outweighs aesthetic demands.
- FDM:Fused deposition modeling occupies a narrow niche in low-cost diagnostic model printing where speed constraints are minimal.
SLA dominates current installed base. DLP is expanding most quickly among new placements.
End User:
Customer type determines procurement complexity, with consolidated dental service organizations negotiating enterprise terms while individual clinics prioritize turnkey simplicity.
- Dental Labs:Commercial laboratories operate high-throughput production lines with dedicated technicians managing multi-printer fleets. Large labs in Italy and Switzerland are narrowing portfolios to exclude EU MDR high-risk device categories.
- Dental Clinics:Chairside adoption accelerates fastest as desktop unit costs decline below capital barriers for mid-sized groups. United States DSOs now represent the majority of new chairside placements through consolidated vendor relationships.
- Educational Institutions:Dental schools require training curricula alignment and bulk pricing for student laboratory courses.
- Research Institutes:Academic research centers prioritize experimental material compatibility and open parameter control.
Dental Labs retains volume leadership. Dental Clinics shows the steepest expansion trajectory.
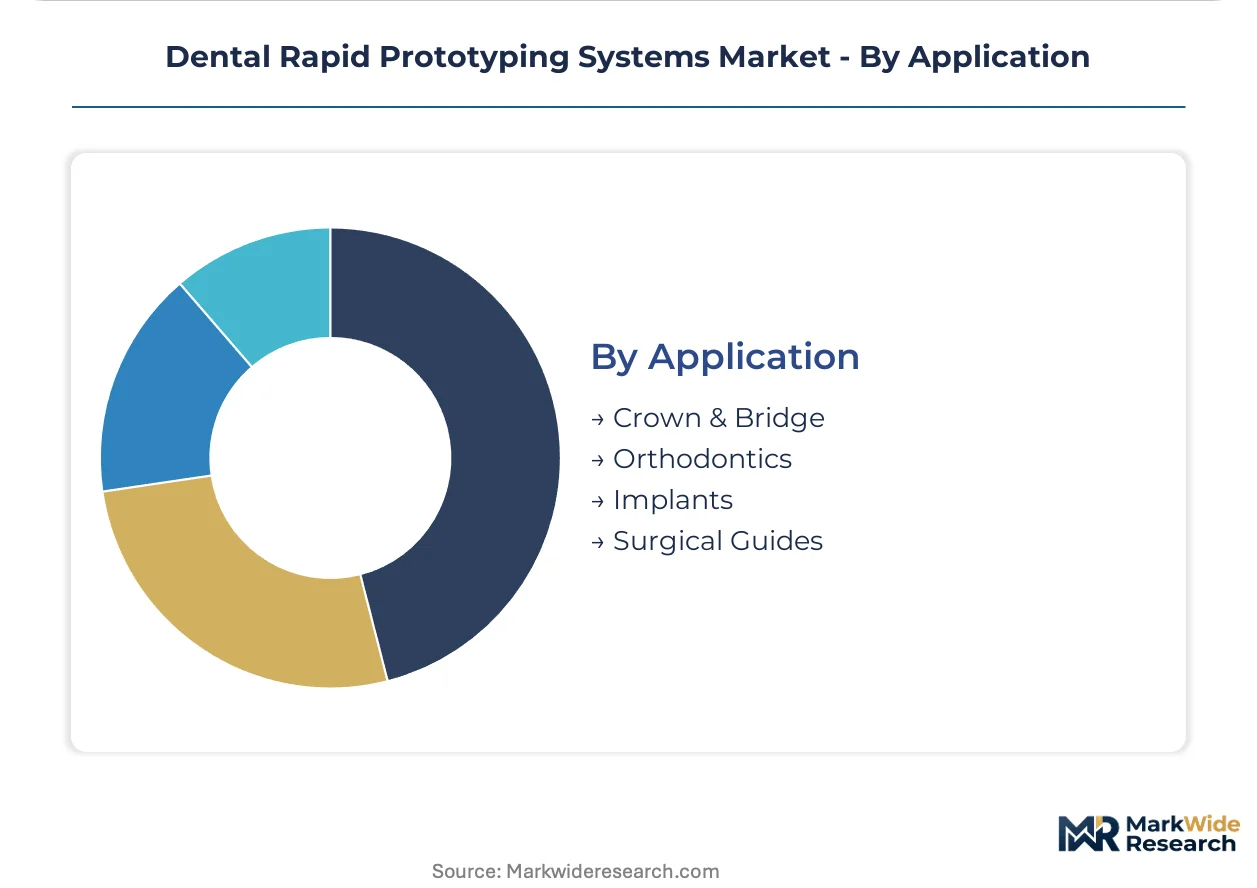
Application:
Application maturity varies by regulatory validation burden, with implant components facing stricter evidence thresholds than routine restorative work.
- Crown & Bridge:Routine restorative applications dominate current production volumes with established FDA 510(k) clearance pathways. Micron-level accuracy requirements eliminate secondary finishing steps and compress technician labor hours per unit.
- Implants:Custom abutments and surgical guides face tightened EU MDR clinical evidence requirements. Export-oriented labs respond by exiting high-risk categories or absorbing expanded technical documentation burdens.
- Orthodontics:Clear aligner model production favors speed over surface finish quality.
- Surgical Guides:Patient-specific drilling templates require sterilization validation and mechanical integrity certification.
Crown & Bridge leads by procedure volume. Implants is gaining share fastest as surgical planning software integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in dental rapid prototyping hardware and biocompatible resins favor net-importing markets with consolidated procurement channels, while manufacturing clusters concentrate in jurisdictions with precision optics and polymer chemistry expertise.
United States
Dental service organizations drive chairside unit placements through enterprise vendor contracts. FDA 510(k) clearances for intraoral resins establish the regulatory baseline for clinical adoption. The Dallas-Fort Worth metroplex anchors DSO headquarters and regional distribution hubs for same-day restoration workflows.
Germany
Commercial dental laboratories maintain SLA production lines for ceramic-coated crown-and-bridge applications. EU Medical Device Regulation compliance costs filter smaller labs from implant component markets. The Stuttgart region clusters precision optics suppliers feeding DLP projector manufacturers.
China
Domestic resin formulation capacity expands to reduce dependence on imported photopolymers. NMPA biocompatibility certifications lag FDA timelines, slowing chairside clinical adoption. Shenzhen manufacturers dominate desktop printer assembly for export markets.
Japan
Mid-sized dental groups adopt 4K DLP systems at replacement-cycle velocity for same-day workflows. METI industrial standards shape equipment interoperability requirements. The Nagoya industrial corridor concentrates motion control component suppliers for printer manufacturers.
India
Chairside penetration remains below eight percent in tier-2 and tier-3 cities, creating first-mover opportunities. CDSCO import regulations govern resin biocompatibility documentation for clinical use. Mumbai and Bengaluru dental equipment distributors build localized service networks for mid-sized clinic groups.
Dental Rapid Prototyping Systems Market Vendor Landscape
On the supply side, the industry is bifurcated between diversified dental conglomerates and specialized additive manufacturing pure-plays. Tier-one positions cluster around integrated resin-printer ecosystems and high-throughput lab systems. Two strategic archetypes dominate: polymer chemistry specialists leveraging material lock-in, and hardware-software integrators optimizing chairside workflow simplicity. Competitive moves concentrate on captive resin subscription models and predictive maintenance service contracts.
Within the diversified dental technology tier, Dentsply Sirona and Straumann Group exemplify equipment-to-implant integration strategies. Stratasys and 3D Systems occupy positions bridging industrial prototyping heritage with clinical application validation. SprintRay and Formlabs represent the specialized pure-play archetype, with SprintRay anchoring tightly coupled resin-printer ecosystems and Formlabs exemplifying desktop unit accessibility for mid-sized clinic adoption.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Planmeca Oy |
| 3D Systems Corporation |
| Straumann Group |
| Rapid Shape GmbH |
| 3M |
| Stratasys |
| Formlabs |
| SprintRay |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese photopolymer resin manufacturing is compressing supplier margins and triggering aggressive pricing postures across export markets, while FDA 510(k) certification premiums sustain price floors for clinical-grade formulations in the United States.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling. Cost compression in economy-tier desktop units is intensifying because Shenzhen assembly lines are absorbing margin erosion to maintain volume. Mid-sized dental groups in tier-2 cities exhibit highest price sensitivity, whereas United States DSOs prioritize ecosystem compatibility over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for photopolymer resin distributors. Critical monomer feedstocks and photo-initiator chemicals concentrate in China, South Korea, and Japan. Formulation depends on acrylate oligomers and specialty dyes that face single-source vulnerability from East Asian chemical conglomerates. Distribution runs through regional dental equipment distributors with localized service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) clearance velocity for biocompatible resins is compressing product launch windows, creating a high-growth disruption where first-mover certification advantages compound into durable ecosystem lock-in.
For Market Incumbents: Pre-empt resin-printer ecosystem fragmentation by anchoring captive material subscriptions before DSO procurement consolidation hardens around single-source vendors. Accelerate backward integration into photopolymer formulation to offset East Asian feedstock concentration risk. Defensive patent filings around AI-driven print parameter optimization will raise barriers against emerging DLP hardware entrants. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 and tier-3 dental clinic segments where chairside penetration sits below eight percent and localized resin distribution partnerships remain unclaimed. Target mid-sized clinic groups with turnkey calibration-free DLP systems bundled with predictive maintenance subscriptions. CDSCO import documentation assistance provides a differentiated go-to-market angle against incumbent direct sales models. For Investors and Strategic Acquirers: Capital is best deployed toward specialized additive manufacturing pure-plays with validated FDA 510(k) resin portfolios and embedded software workflows. Long-term viability across the projection horizon favors suppliers with polymer chemistry depth over hardware-only assemblers. Monitor FDA 510(k) review queue lengths as the inflection signal for cash runway stress among pre-revenue resin formulators.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed review timelines enable first-mover resin certification ahead of competitor filings. |
| Resin-Printer Ecosystem Integration | Tightly coupled hardware-material subscriptions reduce customer churn for DLP system vendors. |
| CDSCO Regulatory Partnership | Localized biocompatibility documentation unlocks chairside adoption in underserved Indian markets. |
| AI-Driven Print Parameter Development | Machine learning calibration reduces failure rates for non-technical clinical staff operators. |
| Predictive Resin Replenishment Service | Subscription logistics lock in recurring revenue from high-volume United States DSO accounts. |
Methodological Framework
Cross-validation between primary interviews with dental clinic operators, commercial laboratory technicians, and DSO procurement officers anchors the qualitative findings against secondary sources including FDA 510(k) clearance databases, CDSCO import registration records, and ISO 13485 audit disclosure filings. Bottom-up equipment shipment data from precision optics suppliers and top-down resin consumption estimates from photopolymer distributors were reconciled across the analysis window.
Calibration against historical adoption curves for chairside CAD/CAM systems shaped the projection framework. Segmentation dimensions modeled include technology type, end-user category, application maturity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted penetration rates applied to dental procedure volume baselines. Forecast inputs incorporated DSO consolidation trajectories and EU MDR compliance cost absorption curves for implant component manufacturers.
Stress conditions across FDA review queue durations, photopolymer monomer price volatility, and DSO vendor consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory precedent shifts or supply chain disruptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
South Africa Dental Devices Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Dental Suction Systems Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental Fittings Market
Dental Devices
Chile Dental Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
India Dental Devices Market
Dental Devices
Global Dental Lasers Market