
 China Aesthetic Devices Market | 2026-2036
China Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Aesthetic Devices Market Outlook
A shift from imported single-source procurement toward multi-source domestic supply is repositioning how Chinese aesthetic chains build their device portfolios. Sisram Medical anchors its position through captive manufacturing of laser and IPL platforms in Israel and China. Lumenis competes on technology leadership in fractional laser applications for skin resurfacing. Beijing Sincoheren Tech leverages cost-engineered radiofrequency systems to capture share in mid-tier beauty salons across second-tier cities.
China aesthetic devices encompass electromechanical and energy-based systems engineered to deliver controlled thermal, optical, or mechanical energy to dermal and subcutaneous tissue, typically operating at wavelengths between 532 nm and 10,600 nm or frequencies between 0.5 MHz and 40 MHz for tissue remodeling. These systems serve commercial purposes across clinics, hospitals, and beauty salons for procedures including hair removal, skin rejuvenation, and body contouring. Laser devices occupy the dominant revenue position due to higher average selling prices and established clinical efficacy in pigmentation and vascular applications. Radiofrequency devices represent the fastest-expanding category as Chinese manufacturers close the technology gap with Korean and Israeli counterparts at lower price points. Ultrasound devices concentrate margin pools in premium body contouring segments where NMPA Class III clearance creates regulatory moats.
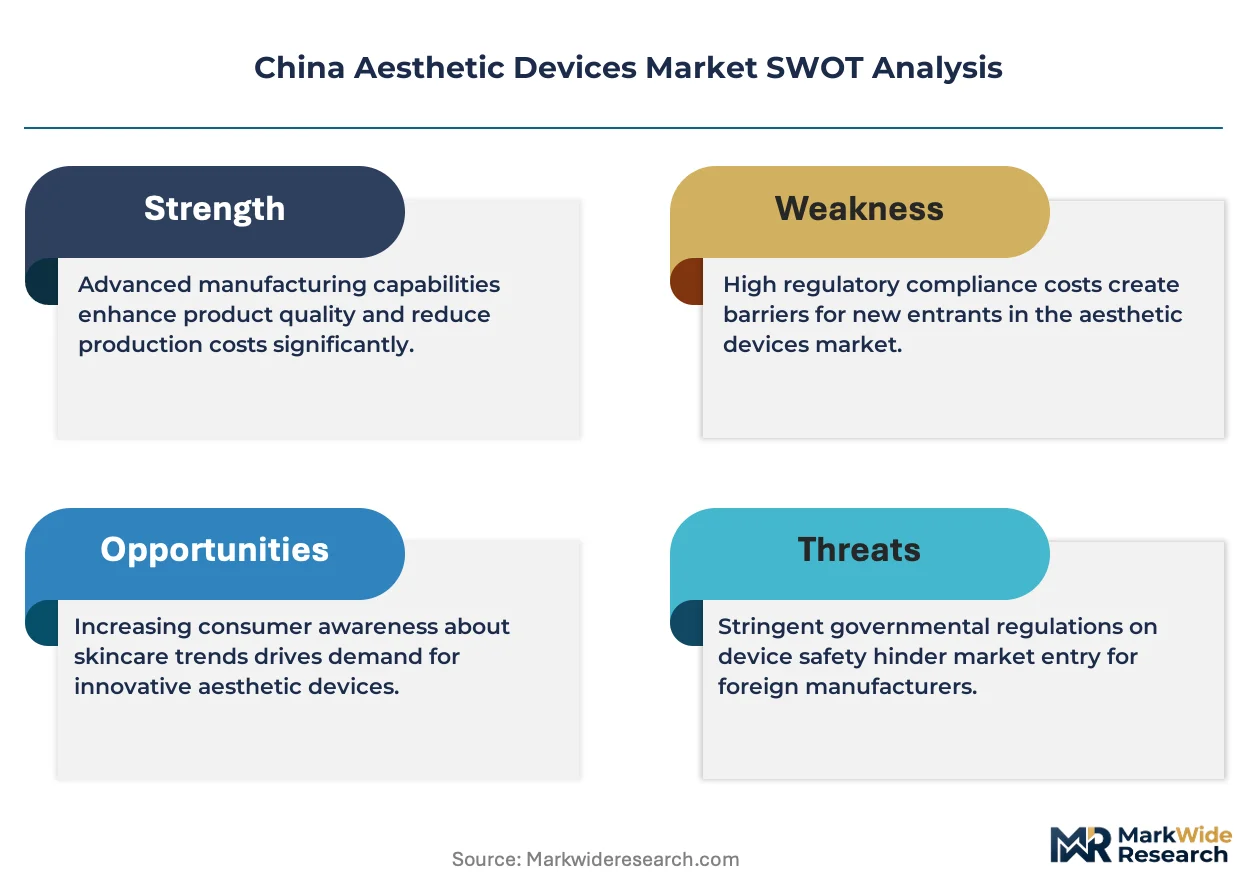
The National Medical Products Administration enforces Class II and Class III registration pathways that extend approval timelines to 18-36 months for energy-based devices, filtering out undercapitalized entrants. China's GB standards for medical electrical equipment, aligned with IEC 60601-1, mandate electromagnetic compatibility and biocompatibility testing that shapes product development budgets. The Ministry of Industry and Information Technology's dual carbon goals are pressuring manufacturers to redesign power electronics for reduced energy consumption. Stakeholders must monitor how provincial procurement consortia aggregate demand and whether NMPA accelerates priority review pathways for domestically innovated platforms.
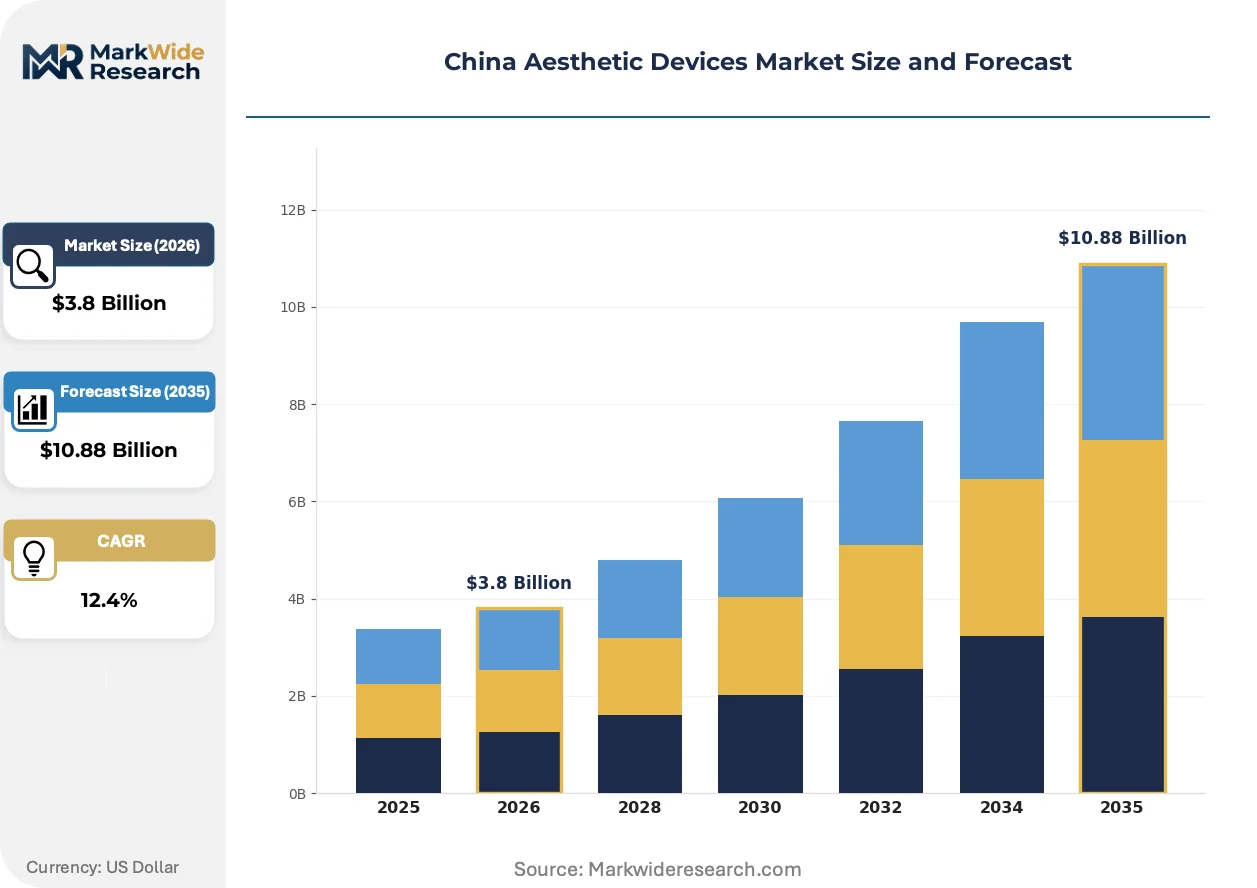
Market Dynamics
NMPA's tightened Class III registration pathways are compressing approval timelines and filtering out undercapitalized domestic manufacturers, forcing quality upgrades across laser and radiofrequency platform portfolios.
Growth Catalysts
- Dual carbon mandates:MIIT's energy efficiency targets are accelerating power electronics redesign in radiofrequency systems, creating first-mover advantages for compliant domestic manufacturers.
- Beauty salon expansion:Tier-two and tier-three cities are witnessing accelerated device procurement as chain operators professionalize service menus beyond traditional skincare.
- Non-invasive procedure preference:Consumer avoidance of surgical intervention is redirecting capital toward fractional laser and ultrasound body contouring platforms in premium clinic segments.
Market Restraints
- Optical component import dependency:High-power laser diodes and precision optics concentrate in Israeli and German supply chains, exposing domestic assemblers to currency and shipping volatility.
- Technical limitation in cooling systems:Contact cooling mechanisms for high-fluence applications remain patent-thick, constraining Chinese manufacturers to lower-power configurations.
- Regulatory friction from GB standard alignment:IEC 60601-1 electromagnetic compatibility testing requirements extend product development cycles and inflate certification budgets for mid-tier entrants.
Strategic Opportunities
- Underpenetrated central provinces:Hunan, Hubei, and Sichuan aesthetic chains operate with 40-60% lower device density per capita than Shanghai or Beijing, presenting whitespace for mid-priced radiofrequency deployment.
- Technology convergence:Combination platforms integrating laser with radiofrequency in single handpieces are capturing clinic preference by reducing capital footprint and treatment room turnover time.
- Direct-to-clinic distribution:Bypassing traditional medical device distributors through manufacturer-owned service networks is compressing margin leakage and improving calibration response times.
Industry Challenges
- Clinical application specialist scarcity:Qualified technicians for parameter optimization across multi-modality platforms command premium wages, constraining salon expansion plans in secondary cities.
- NMPA Class III certification timelines:Energy-based devices face 18-36 month approval windows that freeze product launch schedules and exhaust runway for venture-backed entrants.
- Legacy device integration complexity:New radiofrequency platforms must interface with existing clinic management software and patient record systems, inflating deployment costs and training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Aesthetic Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Ultrasound Devices, Radiofrequency Devices, Microdermabrasion Devices Application: Hair Removal, Skin Rejuvenation, Body Contouring, Acne Treatment End User: Clinics, Hospitals, Home Users, Beauty Salons Technology: Intense Pulsed Light, Fractional Laser, LED, Dermal Fillers |
| Companies Covered | Bausch Health Companies, Medytox, Lumenis, Merz Pharma, Beijing Sincoheren Tech, Candela Medical, Sisram Medical (Alma Lasers), Cutera, AbbVie (Allergan Aesthetics), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Aesthetic Devices Market Strategic Shifts
Device architecture is converging around multi-energy platforms while regulatory stringency and procurement professionalization reshape competitive positioning across tiered city markets.
Multi-wavelength laser systems are consolidating clinical workflow efficiency by enabling sequential pigmentation, vascular, and resurfacing treatments without device switching. Premium clinics in Shanghai and Beijing are standardizing on these platforms to maximize treatment room utilization. The technology is consolidating vendor relationships as single-source procurement displaces fragmented device fleets.
NMPA's accelerated priority review pathway for domestically innovated platforms is redirecting manufacturer R&D budgets toward novel cooling mechanisms and pulse modulation algorithms. Domestic applicants with substantive innovation dossiers now access compressed 12-18 month timelines versus standard 36-month tracks. Tier-one clinic procurement committees are adjusting supplier qualification criteria to favor NMPA innovation pathway certification.
Leasing and revenue-sharing arrangements are displacing outright capital purchase for mid-tier beauty salon operators. Device manufacturers now retain ownership and charge per-treatment fees, transferring utilization risk and obsolescence exposure from salon to supplier. This model concentrates in Guangdong and Zhejiang provinces where salon chain consolidation has created creditworthy counterparties for structured finance.
China Aesthetic Devices Market Segmentation
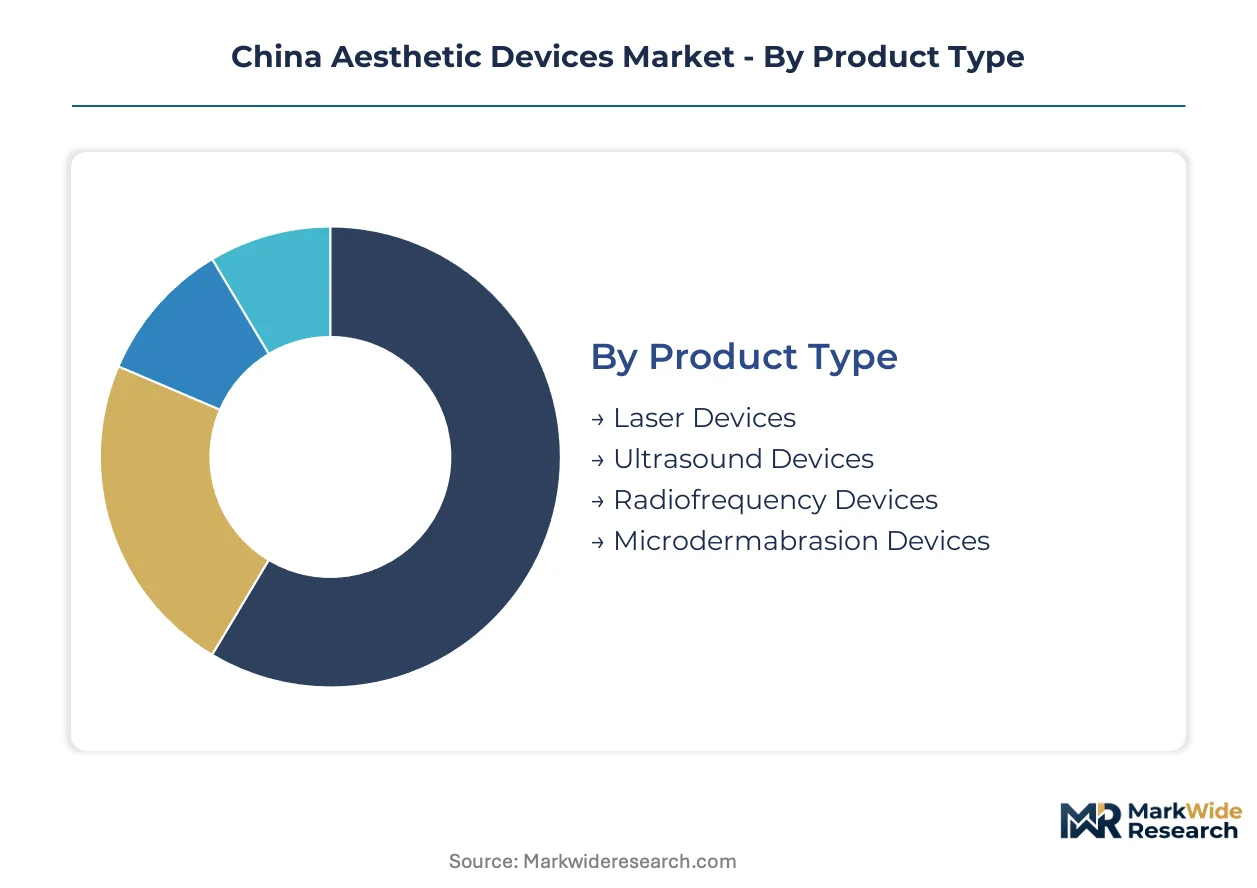
Device replacement cycles in China aesthetic practices are compressing as NMPA Class III registration timelines accelerate quality turnover. Procurement committees now evaluate segments through dual lenses of upgrade urgency and regulatory compliance rather than legacy brand loyalty.
Product Type:
Replacement urgency concentrates in energy-based platforms where optical component degradation and cooling system obsolescence trigger 5-7 year refresh cycles.
- Laser Devices:Solid-state and diode laser systems operating at 532-1064 nm wavelengths deliver precise thermal injury for pigmentation and vascular lesions. Shanghai and Beijing premium clinics prioritize these platforms for their established clinical efficacy and higher reimbursement positioning under NMPA oversight.
- Radiofrequency Devices:Capacitive and monopolar systems at 0.5-40 MHz frequencies generate dermal heating for collagen remodeling. Tier-two city beauty salons are capturing these devices as domestic manufacturers close technology gaps with Korean suppliers at 30-40% lower price points.
- Ultrasound Devices:High-intensity focused ultrasound systems concentrate margin pools in body contouring applications where NMPA Class III clearance creates regulatory barriers.
- Microdermabrasion Devices:Mechanical exfoliation systems serve entry-level salon segments with minimal regulatory burden and rapid technician training curves.
Laser Devices sits at the top of the volume ranking, with Radiofrequency Devices climbing the fastest.
Application:
Procedure economics reshape segment priority as clinics optimize revenue per treatment room hour.
- Hair Removal:Diode laser and IPL platforms target melanin in follicular structures for permanent reduction. Guangdong province salon chains are standardizing these systems as first procurement priority given high treatment frequency and predictable consumer demand.
- Skin Rejuvenation:Fractional laser and radiofrequency modalities address photodamage and rhytides through controlled thermal injury. Beijing aesthetic medicine centers are consolidating procurement around multi-wavelength platforms that sequentialize pigmentation, vascular, and resurfacing protocols.
- Body Contouring:Ultrasound and cryolipolysis systems target adipocyte reduction without surgical intervention.
- Acne Treatment:Blue light LED and photodynamic therapy platforms serve adolescent and young adult demographics with lower price sensitivity thresholds.
Hair Removal commands the largest installed base, though Skin Rejuvenation is gaining share fastest among premium clinic operators.
End User:
Capital deployment patterns diverge sharply across facility types as credit access and utilization risk tolerance vary.
- Clinics:Medical aesthetic institutions with licensed physicians command highest device ASPs and prioritize NMPA Class III clearance for liability protection. Shanghai private clinic groups are consolidating procurement through manufacturer-direct service networks to compress margin leakage.
- Beauty Salons:Non-medical facilities operate under lighter regulatory burden with Class II device restrictions. Zhejiang and Jiangsu province chains are accelerating professionalization through revenue-sharing arrangements that transfer obsolescence risk to suppliers.
- Hospitals:Public dermatology departments integrate aesthetic devices within broader medical service portfolios.
- Home Users:Consumer-grade IPL and LED devices serve maintenance between professional treatments.
Clinics anchor procurement volume, with Beauty Salons expanding most quickly through lease-to-own structures.
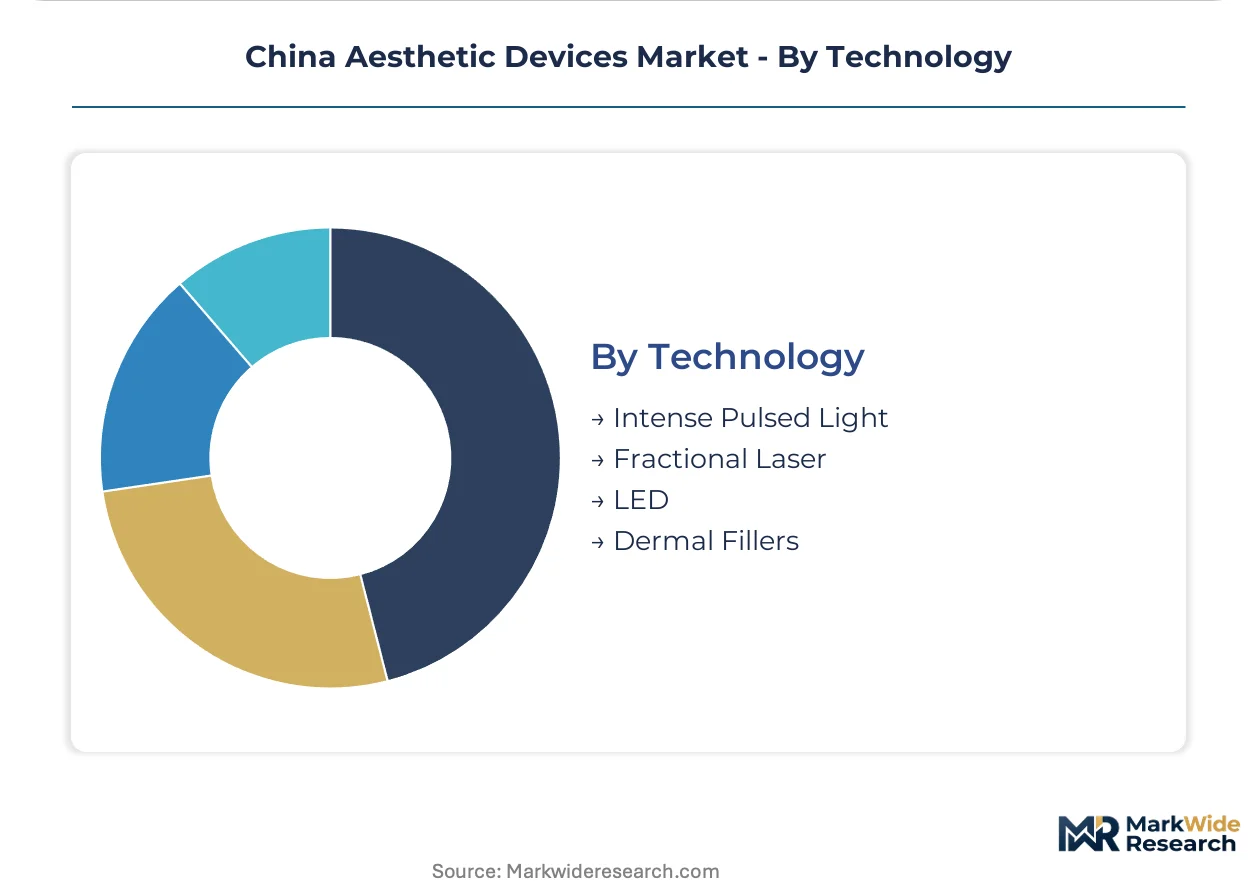
Technology:
Patent landscape maturity determines which platforms face commoditization pressure versus sustained margin protection.
- Fractional Laser:Ablative and non-ablative systems delivering microthermal zones for resurfacing with reduced downtime. Tier-one cities are standardizing on these platforms as clinical data accumulates for ethnic skin safety profiles under NMPA post-market surveillance.
- Intense Pulsed Light:Broadband filtered flashlamp systems address multiple chromophores through single handpiece configurations. Domestic manufacturers in Shenzhen are capturing mid-market share through cost-engineered power electronics compliant with MIIT dual carbon mandates.
- LED:Narrow-spectrum light-emitting diode arrays serve low-intensity applications with minimal thermal risk.
- Dermal Fillers:Injectable hyaluronic acid and collagen-stimulating formulations complement energy-based device protocols.
Intense Pulsed Light holds the broadest installed footprint, while Fractional Laser is climbing fastest on clinical efficacy differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors device procurement concentration, with Shanghai aesthetic chains driving multi-source domestic supply transitions. Provincial procurement consortia across central provinces are aggregating demand as tier-two cities professionalize service menus.
Shanghai
Premium clinic consolidation and manufacturer-direct service networks compress margin leakage for laser and radiofrequency platforms. NMPA Class III registration requirements filter procurement committees toward NMPA innovation pathway certification. Pudong and Huangpu districts concentrate device fleet expansions as consumer spending on non-invasive procedures accelerates.
Beijing
Private clinic groups standardize on multi-wavelength platforms for sequential pigmentation and resurfacing protocols. MIIT dual carbon mandates pressure power electronics redesign in radiofrequency systems. Chaoyang and Haidian districts host the densest aesthetic medicine center clusters with highest average selling prices.
Guangdong Province
Salon chain consolidation in Guangzhou and Shenzhen creates creditworthy counterparties for revenue-sharing arrangements. Provincial procurement consortia aggregate demand across Pearl River Delta cities. Shenzhen manufacturers capture mid-market share through cost-engineered IPL systems compliant with energy efficiency targets.
Zhejiang Province
Beauty salon professionalization accelerates through lease-to-own structures transferring obsolescence risk to suppliers. Hangzhou and Ningbo chains deploy radiofrequency devices as domestic manufacturers close technology gaps with Korean counterparts. Provincial regulators enforce GB standards alignment with IEC 60601-1 electromagnetic compatibility testing.
Sichuan-Chongqing
Chengdu aesthetic chains operate with 40-60% lower device density per capita than Shanghai, presenting whitespace for mid-priced radiofrequency deployment. Chongqing salon operators bypass traditional distributors through manufacturer-owned service networks. Western China expansion strategies concentrate on professionalizing service menus beyond traditional skincare.
China Aesthetic Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cost-engineered configurations for mid-market salon segments. Market structure consolidates around technology leadership in fractional laser applications and captive manufacturing of energy-based platforms. Three archetypes dominate: Israeli-Chinese hybrid manufacturers with dual-hemisphere production, German precision optics suppliers, and domestic cost-optimizers leveraging provincial procurement consortia. Competitive moves concentrate on direct-to-clinic distribution bypass and combination platform development integrating multiple energy modalities.
Within the hybrid manufacturing tier, Sisram Medical and Lumenis exemplify dual-hemisphere production strategies. Beijing Sincoheren Tech occupies a position among domestic cost-engineered specialists. These three anchors represent divergent responses to NMPA registration timelines: captive Israeli manufacturing, technology leadership in specific laser wavelengths, and aggressive pricing for tier-two city penetration.
| Leading Market Players |
|---|
| Bausch Health Companies |
| Medytox |
| Lumenis |
| Merz Pharma |
| Beijing Sincoheren Tech |
| Candela Medical |
| Sisram Medical (Alma Lasers) |
| Cutera |
| AbbVie (Allergan Aesthetics) |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between NMPA Class III medical devices and Class II salon equipment manifests in divergent pricing architectures and sourcing strategies across China's aesthetic device landscape. Premium clinics absorb 3-4x hardware premiums for Class III clearance while mid-tier operators exploit regulatory arbitrage through Class II procurement channels, fragmenting supplier qualification requirements and inventory management protocols.
Pricing Analysis
Input-cost pass-through from high-power laser diodes and precision optics drives ASP divergence between Israeli-German supply chains and domestic radiofrequency assemblers. Pricing stratifies across premium, standard, and economy tiers based on NMPA clearance grade and cooling system performance. Cost compression in mid-market radiofrequency segments intensifies as Shenzhen manufacturers scale monopolar platforms. Beauty salon chains exhibit highest price sensitivity, while private clinic groups prioritize liability protection over procurement economics.
Supply Chain Analysis
Dual-sourcing requirements from tier-one clinic procurement committees mandate qualified suppliers across both Israeli and Chinese manufacturing bases. High-power optical components draw from German and Israeli precision engineering, while power electronics and handpiece assemblies source from Shenzhen and Suzhou industrial clusters. Single-source vulnerability concentrates in fractional laser diode arrays protected by patent thickets. Distribution runs through manufacturer-owned service networks that bypass traditional medical device distributors in coastal provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA's accelerated priority review pathway for domestically innovated platforms compounds regulatory moats, positioning compliant manufacturers to capture premium clinic procurement committees as certification timelines compress.
For Market Incumbents: To counter emerging domestic radiofrequency specialists, deepen captive manufacturing control over laser diode supply chains and accelerate NMPA innovation dossier submissions. Prioritize direct-to-clinic distribution infrastructure in Yangtze River Delta clusters to compress margin leakage from traditional distributor networks. For New Entrants and Emerging Players: Capture whitespace in Sichuan-Chongqing and central province beauty salon chains operating with 40-60% lower device density per capita than Shanghai. Deploy revenue-sharing arrangements that transfer utilization risk and obsolescence exposure from salon operators, leveraging Zhejiang and Guangdong provincial procurement consortia for demand aggregation. For Investors and Strategic Acquirers: Consolidation pressure builds where NMPA Class III registration timelines exhaust venture-backed runway and filter undercapitalized entrants. Long-term viability centers on manufacturers with substantive innovation dossiers accessing compressed approval tracks. Monitor NMPA priority review pathway certification rates as the inflection signal for tier-one clinic procurement qualification.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Innovation Pathway Certification | Compressed 12-18 month timelines unlock tier-one clinic procurement qualification against 36-month standard tracks. |
| Dual-Hemisphere Manufacturing Footprint | Captive Israeli production of laser platforms insulates against MIIT dual carbon mandates and currency volatility. |
| Multi-Energy Platform Development | Laser-radiofrequency combination devices reduce capital footprint and treatment room turnover time for clinic operators. |
| Direct-to-Clinic Service Networks | Manufacturer-owned distribution compresses margin leakage and improves calibration response times in premium segments. |
| Revenue-Sharing Arrangement Scaling | Per-treatment fee structures transfer utilization risk to suppliers and accelerate salon chain professionalization. |
Study Parameters
Multiple input streams — clinician interviews, hospital purchasing committee consultations, manufacturer R&D director discussions, and GPO contracts analysis — were reconciled against NMPA registration databases, MIIT energy efficiency disclosures, and provincial procurement consortium records. Bottom-up device shipment data from tier-one and tier-two city clinics triangulated with top-down market sizing across laser, radiofrequency, ultrasound, and microdermabrasion platform categories.
Historical installation base trajectories cross-referenced against panel input from biomedical engineers and salon chain procurement heads shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include device technology, NMPA regulatory classification, end-user facility type, and regional city-tier penetration. CAGRs derived from weighted average of technology-specific replacement cycles and provincial expansion rates, incorporating optical component import dependency and cooling system patent landscape maturity as industry-specific modifiers.
Regulatory timeline acceleration, optical supply chain disruption, and salon chain creditworthiness deterioration are the dominant revision risks to modeled outputs. Deviation in NMPA priority review pathway throughput would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Fusion Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Auto Keratometer Market
Medical Devices
T-Piece Resuscitator Market
Medical Devices
Global Photomedicine Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
Actigraphy Sensors and Polysomnography Devices Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Implantable Drug Delivery Devices Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
South Korea Ultrasound Devices Market
Medical Devices
Enteral Feeding Devices Market