
 Injectable Bone Graft Substitutes Market | 2026-2036
Injectable Bone Graft Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Bone Graft Substitutes Market Analytics
Multi-source procurement for synthetic bone graft matrices is broadening as hospitals diversify supplier relationships beyond single-vendor contracts. Medtronic leverages its integrated spine portfolio to anchor hospital purchasing agreements across orthopedic service lines. Zimmer Biomet competes through specialized calcium phosphate formulations targeting dental implant applications. Stryker controls distribution networks that extend into ambulatory surgery centers, reinforcing channel presence without direct manufacturing claims.
Injectable bone graft substitutes are flowable, synthetic or biologically derived materials delivered percutaneously to fill osseous voids and stimulate osteoconduction or osteoinduction, typically comprising beta-tricalcium phosphate, demineralized bone matrix, or collagen carriers with setting times under fifteen minutes. Their primary commercial purpose centers on reducing donor site morbidity and operative time in minimally invasive orthopedic and maxillofacial procedures. Hydrogel and calcium phosphate segments capture dominant volume share due to established reimbursement codes and surgeon familiarity, while bioactive glass formulations represent the fastest-expanding margin pool owing to superior angiogenic properties and premium pricing. Application demand skews heavily toward spinal fusion, where injectable delivery reduces open procedure requirements, though sports medicine represents an emerging vector as arthroscopic bone void filling gains procedural traction.
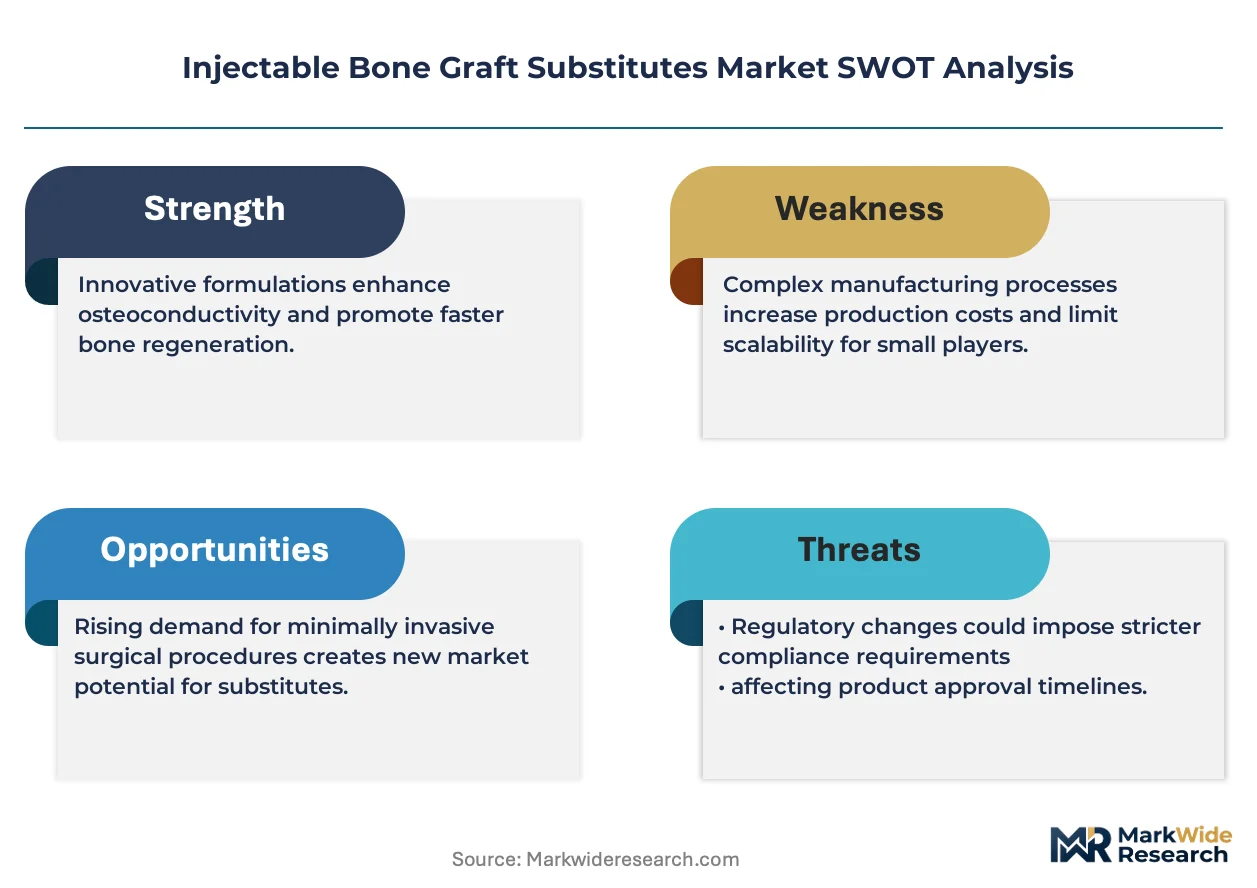
FDA 510(k) premarket notification requirements govern synthetic bone graft substitute commercialization in the United States, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking access across European markets. ISO 10993 biocompatibility testing standards further constrain material selection and validation protocols, effectively filtering smaller entrants from premium segments. Stakeholders must monitor evolving FDA guidance on combination product classification, particularly where bone graft substitutes incorporate antimicrobial or biological active components that trigger dual-jurisdiction review pathways.
Market Dynamics
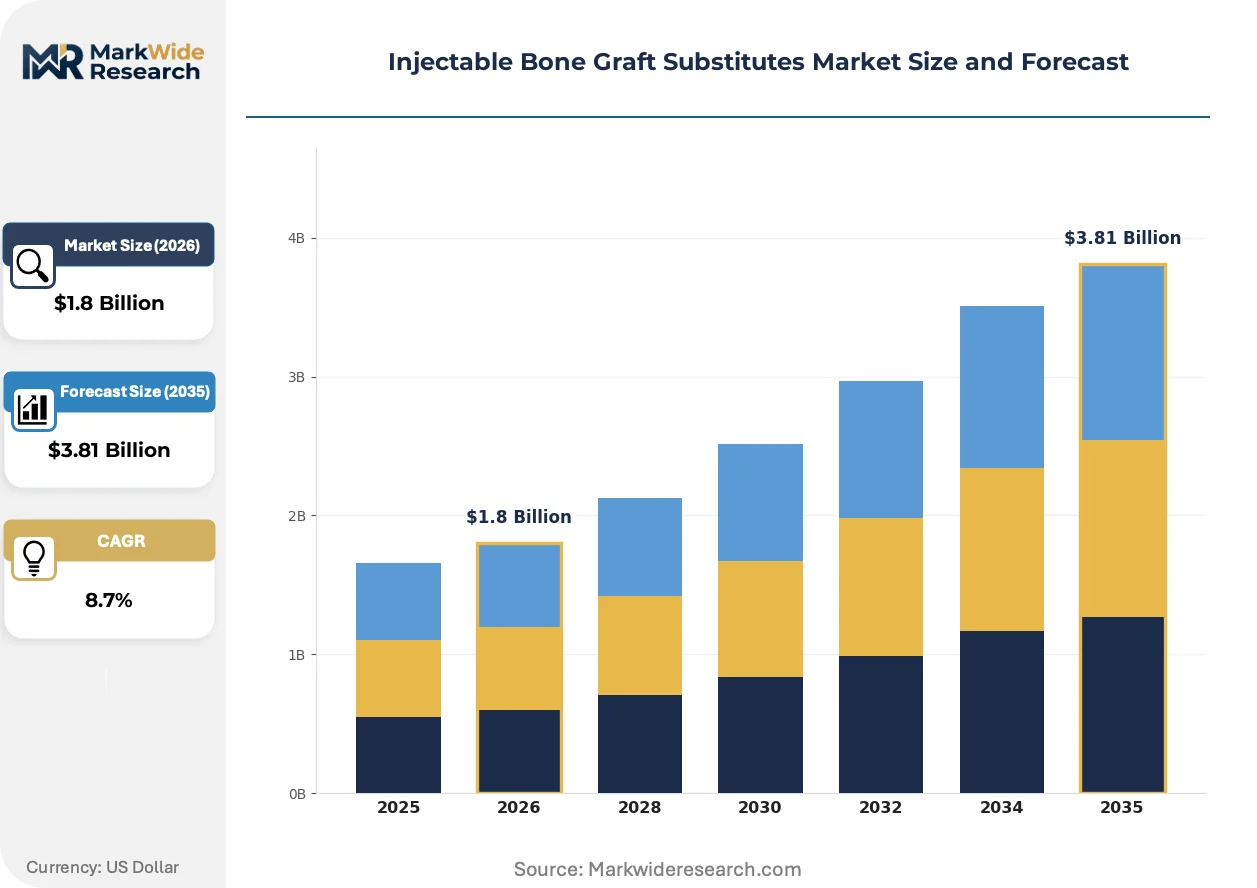
The Injectable Bone Graft Substitutes Market is compressing around minimally invasive delivery platforms as ambulatory surgical centers displace inpatient fusion procedures, forcing manufacturers to redesign viscosity profiles and setting kinetics for percutaneous deployment.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare and Medicaid Services has broadened procedural codes for outpatient spinal fusion, accelerating same-day discharge protocols that favor injectable formats over structural grafts requiring open exposure.
- Sports medicine arthroscopy:Orthopedic surgeons are adapting bone void fillers for arthroscopic delivery in tibial plateau and humeral head fractures, creating procedural volume beyond traditional spine applications.
- Beta-tricalcium phosphate:Synthetic ceramic formulations with tunable resorption rates are capturing preference from allograft-derived alternatives due to elimination of donor tissue screening costs and supply variability.
Market Restraints
- Raw material concentration:High-purity calcium phosphate precursors rely on phosphate rock processing concentrated in Morocco and China, exposing formulators to export quota volatility and freight cost spikes.
- Dual-jurisdiction review:FDA combination product classification for grafts incorporating antibiotics or growth factors triggers parallel Center for Drug Evaluation and Research review, extending clearance timelines by eighteen to thirty-six months.
- Structural allograft persistence:Load-bearing spinal applications continue specifying machined cortical bone for anterior column support, limiting injectable penetration to posterior non-structural fusion beds.
Strategic Opportunities
- Brazil's ANVISA pathway:Streamlined registration for Class III medical devices with prior FDA clearance is opening private hospital procurement in São Paulo and Rio de Janeiro corridors.
- Antimicrobial elution:Integration of gentamicin or vancomycin into calcium phosphate carriers addresses surgical site infection protocols without separate antibiotic bead placement.
- Direct-to-ASC distribution:Bypassing hospital materials management through specialized orthopedic distributor networks reduces consignment complexity and accelerates payment cycles.
Industry Challenges
- Bioengineer scarcity:Formulation scientists with dual expertise in ceramic processing and polymer rheology command premium compensation, constraining R&D expansion at mid-tier manufacturers.
- ISO 10993-6 validation:Extended implantation studies for new carrier matrices require twelve to twenty-four month timelines before 510(k) submission, compressing product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Bone Graft Substitutes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Calcium Phosphate, Collagen-based, Bioactive Glass Application: Orthopedic Surgery, Dental Implants, Spinal Fusion, Sports Medicine End User: Hospitals, Surgical Centers, Orthopedic Clinics, Dental Practices Delivery Mode: Syringe, Spray, Injectable Pellet, Bone Void Fillers |
| Companies Covered | Medtronic, Zimmer Biomet, Stryker, DePuy Synthes (Johnson & Johnson), SeaSpine, Wright Medical, Arthrex, Graftys, Xtant Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Bone Graft Substitutes Market Evolving Landscape
Product development is pivoting toward bioactive functionality as manufacturers compete on osteoinductive claims rather than passive void filling, with angiogenic stimulation emerging as the next performance threshold.
3D-printed patient-specific scaffolds are electrifying preoperative planning workflows in complex revision spine cases. Academic medical centers with integrated biomechanics labs are adopting these platforms for deformity correction planning. The technology is electrifying competitive positioning by collapsing the gap between templating and intraoperative execution, pressuring conventional injectable suppliers to demonstrate equivalent precision.
EU Medical Device Regulation's enhanced clinical evidence requirements are reshaping notified body engagement strategies. Manufacturers must now submit post-market surveillance plans with active comparator data rather than historical controls. Small-volume product lines face disproportionate compliance burden, accelerating portfolio rationalization toward high-margin formulations.
Hospital value analysis committees are consolidating vendor rosters to reduce SKU complexity in orthopedic service lines. Multi-hospital systems are awarding sole-source contracts spanning synthetic grafts, structural allografts, and biologics to integrated spine portfolios. This concentration is most visible in United States metropolitan markets where health system consolidation has created super-regional purchasing entities with substantial negotiation leverage.
Injectable Bone Graft Substitutes Market Segmentation
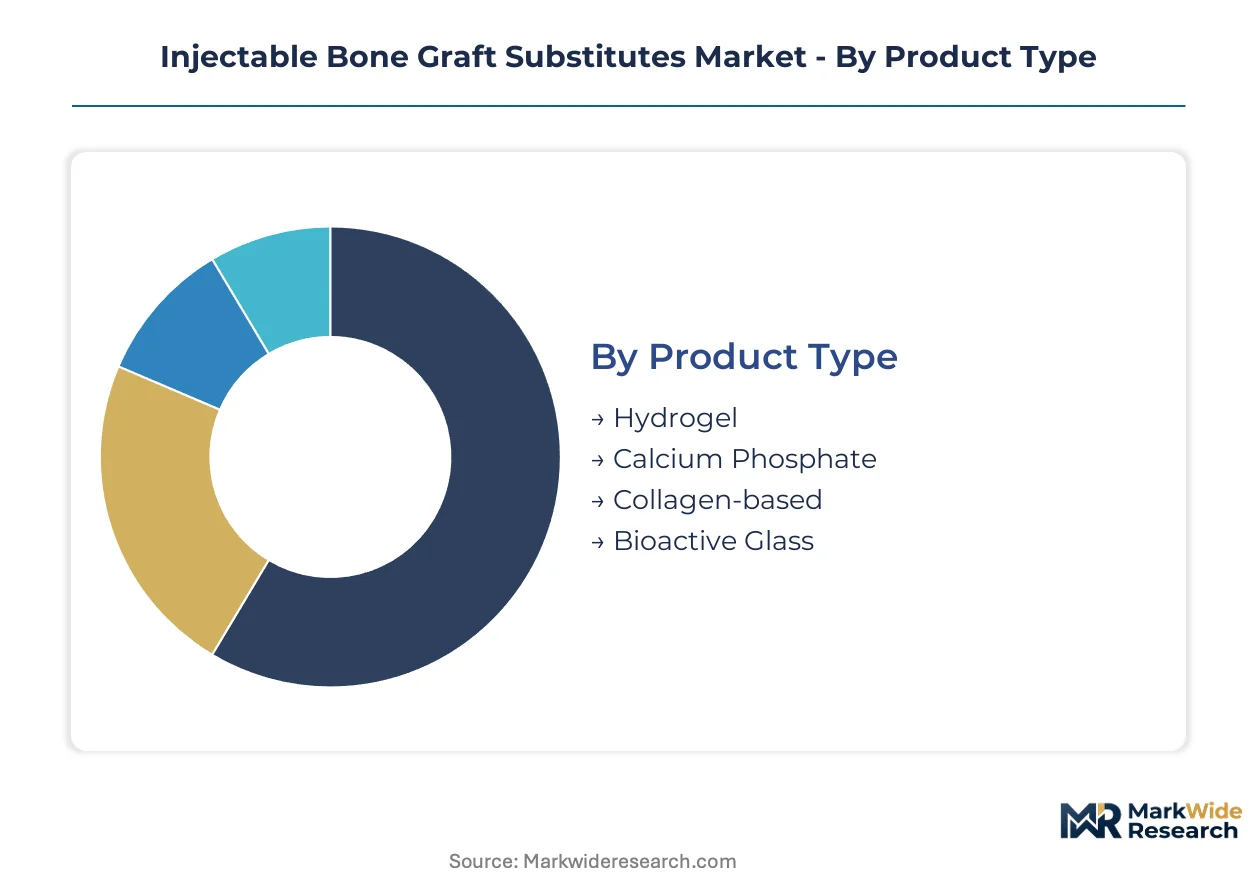
Injectable bone graft substitutes fragment across material chemistry, procedural setting, and delivery mechanism. Each axis carries distinct reimbursement implications and technical validation requirements that shape manufacturer portfolio priorities.
Product Type:
Material composition determines setting kinetics, osteoconductive performance, and regulatory classification pathways.
- Hydrogel:Cross-linked polymer matrices with tunable viscosity enable percutaneous delivery through narrow-gauge needles. Demand clusters in ambulatory surgical centers where rapid polymerization supports same-day discharge protocols.
- Calcium Phosphate:Beta-tricalcium phosphate and hydroxyapatite formulations dominate spinal fusion volume through established CPT reimbursement codes and surgeon familiarity with handling characteristics.
- Collagen-based:Demineralized bone matrix carriers provide osteoinductive signaling through native growth factor retention.
- Bioactive Glass:Silicate-based compositions release ionic dissolution products that stimulate angiogenesis and accelerate remodeling timelines.
Mature deployment sits with Calcium Phosphate. Newer deployment is concentrated in Bioactive Glass.
Application:
Procedural volume distributes unevenly across anatomical sites, with spine applications commanding premium pricing and sports medicine representing volume expansion frontiers.
- Spinal Fusion:Posterolateral and interbody applications drive the majority of injectable consumption, particularly at L4-L5 and L5-S1 levels where minimally invasive transforaminal approaches reduce open exposure requirements.
- Sports Medicine:Arthroscopic delivery to tibial plateau defects and humeral head fractures is climbing the fastest as orthopedic surgeons adapt flowable materials to joint-preserving procedures.
- Orthopedic Surgery:General trauma applications include calcaneal and distal radius void filling following fracture reduction.
- Dental Implants:Ridge augmentation and sinus lift procedures utilize putty-consistency formulations with resorption rates matched to implant osseointegration timelines.
Volume leadership resides with Spinal Fusion. Steepest expansion trajectory belongs to Sports Medicine.
End User:
Site-of-care economics reshape procurement patterns as procedural migration accelerates toward lower-acuity settings.
- Hospitals:Academic medical centers and community hospitals maintain bulk purchasing agreements for combination product portfolios spanning structural allografts and synthetic fillers.
- Surgical Centers:Medicare reimbursement expansion for outpatient spinal fusion has concentrated demand growth in Medicare-certified ASCs with dedicated orthopedic service lines.
- Orthopedic Clinics:Office-based bone marrow aspiration and concentration procedures create adjacent demand for point-of-care mixing systems.
- Dental Practices:Oral surgery groups with implantology specialization drive recurring procurement for smaller-volume collagen and mineralized putty SKUs.
Procurement scale peaks at Hospitals. Fastest account acquisition is occurring at Surgical Centers.
Delivery Mode:
Deployment mechanism selection depends on defect geometry, access route, and surgeon preference for material placement precision.
- Syringe:Pre-filled, single-use delivery systems dominate percutaneous spine applications where controlled extrusion through bone cannulas is required.
- Bone Void Fillers:Moldable putty formats permit manual contouring to irregular defect geometries in open orthopedic and craniomaxillofacial procedures.
- Spray:Aerosolized application systems coat exposed bone surfaces during arthroscopic or laparoscopic approaches where direct packing is impractical.
- Injectable Pellet:Pre-formed granules suspended in carrier gel enable precise volume delivery to contained defects with reduced extravasation risk.
Standard practice centers on Syringe delivery. Emerging adoption is shifting toward Spray systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity calcium phosphate precursor deposits in Morocco and China concentrate raw material sourcing for synthetic bone graft manufacturing, shaping regional production economics and supply security calculations for formulators worldwide.
United States
Ambulatory surgical centers in Texas and Florida drive procedural volume migration toward outpatient spinal fusion, with Medicare-certified facilities expanding dedicated orthopedic service lines. FDA 510(k) premarket notification requirements govern commercialization timelines, particularly for combination products incorporating antimicrobial agents. The Minneapolis-St. Paul corridor anchors major manufacturer headquarters and distribution infrastructure serving super-regional purchasing entities.
Germany
Academic medical centers in Bavaria and Baden-Württemberg pioneer 3D-printed patient-specific scaffold adoption for complex revision spine cases. EU Medical Device Regulation mandates notified body conformity assessment with enhanced clinical evidence requirements, reshaping post-market surveillance obligations. The Stuttgart industrial cluster concentrates precision ceramic processing capabilities serving orthopedic device supply chains.
China
Domestic manufacturers in Jiangsu and Zhejiang provinces scale beta-tricalcium phosphate production capacity to serve hospital procurement reform initiatives. NMPA regulatory pathways for Class III medical devices require in-country clinical trials, extending market entry timelines for foreign entrants. The Suzhou biomedical industrial park hosts formulation facilities targeting domestic spine surgery volume expansion.
Brazil
Private hospital groups in São Paulo and Rio de Janeiro corridors expand orthopedic procedure capacity amid streamlined ANVISA registration for devices with prior FDA clearance. The regulatory pathway reduction accelerates procurement negotiations with international suppliers. Campinas anchors regional distribution infrastructure serving southeastern Brazil's concentrated surgical volume.
Japan
Aging demographics in the Kanto region sustain demand for minimally invasive bone void filling procedures reducing recovery timelines. PMDA consultation procedures for regenerative medical products guide development timelines for advanced carrier matrices. The Osaka-Kobe manufacturing belt concentrates ceramic processing expertise serving domestic and Asia-Pacific orthopedic device markets.
Injectable Bone Graft Substitutes Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers expand from spine-centric offerings into sports medicine and dental applications. The vendor base concentrates around integrated orthopedic portfolios with hospital purchasing agreement leverage, supplemented by specialized ceramic formulators and regional distribution specialists. Three archetypes prevail: diversified spine conglomerates with cross-service-line contracts, focused synthetic graft developers with material science differentiation, and distribution-centric players controlling ambulatory surgery center channels. M&A activity and technology licensing arrangements represent the primary competitive vectors, with acquisition targets clustering around bioactive glass formulation capabilities and point-of-care mixing system platforms.
Within the diversified spine conglomerate tier, Medtronic, Zimmer Biomet, and Stryker exemplify positioning anchored by integrated orthopedic service line penetration. Medtronic represents the hospital purchasing agreement archetype, leveraging cross-product portfolio scale to secure sole-source contracts with super-regional health systems. Zimmer Biomet occupies a specialization position in calcium phosphate formulations with targeted dental and maxillofacial applications. Stryker exemplifies distribution network control, extending channel presence into ambulatory surgery centers without direct manufacturing claims concentration.
| Leading Market Players |
|---|
| Medtronic |
| Zimmer Biomet |
| Stryker |
| DePuy Synthes (Johnson & Johnson) |
| SeaSpine |
| Wright Medical |
| Arthrex |
| Graftys |
| Xtant Medical |
| Others |
Value Network & Pricing Analysis
Performance-grade divergence between bioactive glass formulations and commodity calcium phosphate matrices manifests in both pricing premiums and raw material sourcing strategies. Premium tiers command substantial markups through angiogenic claims and extended warranty coverage, while standard formulations compete on phosphate rock processing economics concentrated in North African and Asian supply corridors.
Pricing Analysis
Warranty bundling separates premium bioactive glass suppliers from unbundled commodity calcium phosphate vendors, with the former including extended clinical support and revision coverage. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993 certification depth and FDA 510(k) pathway complexity. Pricing pressure stems from hospital value analysis committee consolidation demanding volume discounts across orthopedic service lines. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement caps, while academic medical centers prioritize performance metrics over unit cost.
Supply Chain Analysis
ISO 10993-6 biocompatibility certification gates access to premium segments, filtering suppliers without twelve-to-twenty-four-month validation timelines. High-purity calcium phosphate precursors draw from phosphate rock processing concentrated in Morocco and China, with ceramic formulators in Germany and Japan completing value-add synthesis. Single-source vulnerability runs through Moroccan export quota volatility affecting beta-tricalcium phosphate feedstock. Distribution runs through specialized orthopedic distributor networks serving ambulatory surgery centers alongside hospital materials management consignment models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable bone graft substitute supply is tightening around qualified ceramic formulators with dual polymer-ceramic expertise, propping pricing power for validated manufacturers against commodity entrants lacking ISO 10993-6 implantation study completion.
For Market Incumbents: Extend formulation patent coverage into antimicrobial elution combinations before FDA combination product classification triggers parallel CDER review. Deepen backward integration into phosphate precursor processing to insulate margin structures from Moroccan export quota volatility. Secure sole-source contracts with super-regional health systems consolidating vendor rosters across synthetic grafts and structural allografts. For New Entrants and Emerging Players: Ambulatory surgical centers with dedicated orthopedic service lines represent the most penetrable buyer archetype, bypassing hospital value analysis committee complexity through direct distributor relationships. Brazil's ANVISA streamlined pathway for FDA-cleared devices opens private hospital procurement in São Paulo corridors without protracted in-country clinical trials. Point-of-care mixing systems for office-based bone marrow procedures offer white-space positioning outside established spine fusion competition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified spine conglomerates seeking bioactive glass formulation capabilities and point-of-care mixing platforms. Long-term viability favors manufacturers with validated ceramic-polymer dual expertise and established 510(k) clearance track records across multiple carrier matrices. Watch FDA guidance evolution on combination product classification as inflection signal for regulatory timeline risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Elution Integration | Addresses surgical site infection protocols through gentamicin-impregnated calcium phosphate carriers without separate antibiotic bead placement. |
| Direct-to-ASC Distribution Buildout | Bypasses hospital materials management consignment complexity through specialized orthopedic distributor networks accelerating payment cycles. |
| Bioactive Glass Formulation Acquisition | Captures premium pricing pools through angiogenic stimulation claims and superior remodeling timeline performance in spinal fusion. |
| ISO 10993-6 Validation Investment | Enables 510(k) submission for novel carrier matrices filtering smaller entrants from premium segments through extended implantation study requirements. |
| Brazil ANVISA Registration Pathway | Accelerates private hospital procurement negotiations in São Paulo and Rio de Janeiro corridors through streamlined Class III device registration. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR notified body conformity assessments, and hospital procurement contract filings, complemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ceramic formulation scientists. Secondary validation drew from CMS reimbursement code expansions, ISO 10993 biocompatibility standards documentation, and phosphate rock trade flow data. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations across material chemistry segments.
Cross-referencing historical clearance timeline patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry, procedural setting, delivery mechanism, and end-user site-of-care economics. CAGRs were derived from procedure volume migration trends weighted by reimbursement code expansion trajectories and raw material cost pass-through assumptions. Forecast inputs incorporated ambulatory surgical center certification growth rates and health system consolidation patterns affecting vendor roster concentration.
Revisions become necessary when FDA combination product guidance shifts trigger dual-jurisdiction review pathway expansion, or when Moroccan phosphate export restrictions disrupt beta-tricalcium phosphate precursor availability. Stakeholders should weight assumptions against their own operating context regarding ceramic processing capabilities and notified body engagement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Prosthetic Liners Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Global Cervical Total Disc Replacement (CTDR) Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
US External Counterpulsation Devices Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Alexandrite Gemstone Lasers Market