
 Africa Big Data Analytics in Energy Market | 2026-2036
Africa Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Big Data Analytics in Energy Market Analytics
South Africa's renewable build-out is reconfiguring how utilities ingest and act on generation data. IBM Corporation leverages its Watson platform to anchor predictive maintenance contracts with Eskom and independent power producers. Microsoft Corporation competes through Azure-based grid analytics that integrate with smart meter deployments across Cape Town and Johannesburg.
Africa Big Data Analytics in Energy encompasses the collection, processing, and algorithmic interpretation of multi-source energy data to optimize generation, distribution, and consumption decisions across the continent's fragmented infrastructure. The discipline applies machine learning models to time-series sensor feeds, satellite imagery, and market pricing signals with latency thresholds under 100 milliseconds for grid balancing applications. Predictive analytics leads solution type adoption as utilities prioritize failure prevention over historical reporting in markets where spare parts logistics stretch across vast territories. Deployment models skew toward hybrid cloud architectures where sensitive SCADA data remains on-premises while non-critical workloads migrate to regional cloud nodes in Nairobi, Lagos, and Cape Town.
South Africa's National Energy Regulator and Nigeria's Nigerian Electricity Regulatory Commission shape market access through grid code compliance mandates that require real-time data submission from generators above 10 MW. The African Union's Single Electricity Market framework and ISO 50001 energy management standards further condition procurement specifications for analytics platforms. Stakeholders must monitor how carbon accounting rules under the EU Carbon Border Adjustment Mechanism reshape demand for emissions-tracking analytics among African energy exporters.
Market Dynamics
East African utilities are consolidating SCADA data lakes to enable cross-border grid synchronization under the African Union's Single Electricity Market framework, forcing analytics vendors to architect real-time interoperability layers.
Growth Catalysts
- Grid Code Compliance Mandates:South Africa's National Energy Regulator and Nigeria's Nigerian Electricity Regulatory Commission require real-time data submission from generators above 10 MW, creating procurement pull for compliant analytics platforms.
- Reservoir Optimization Economics:Nigeria's upstream oil sector deploys advanced reservoir analytics to compress extraction costs and extend field life cycles.
- Predictive Maintenance Prioritization:Utilities across Kenya, Tanzania, and Uganda expand failure-prevention programs to reduce downtime where spare parts logistics span vast territories.
Market Restraints
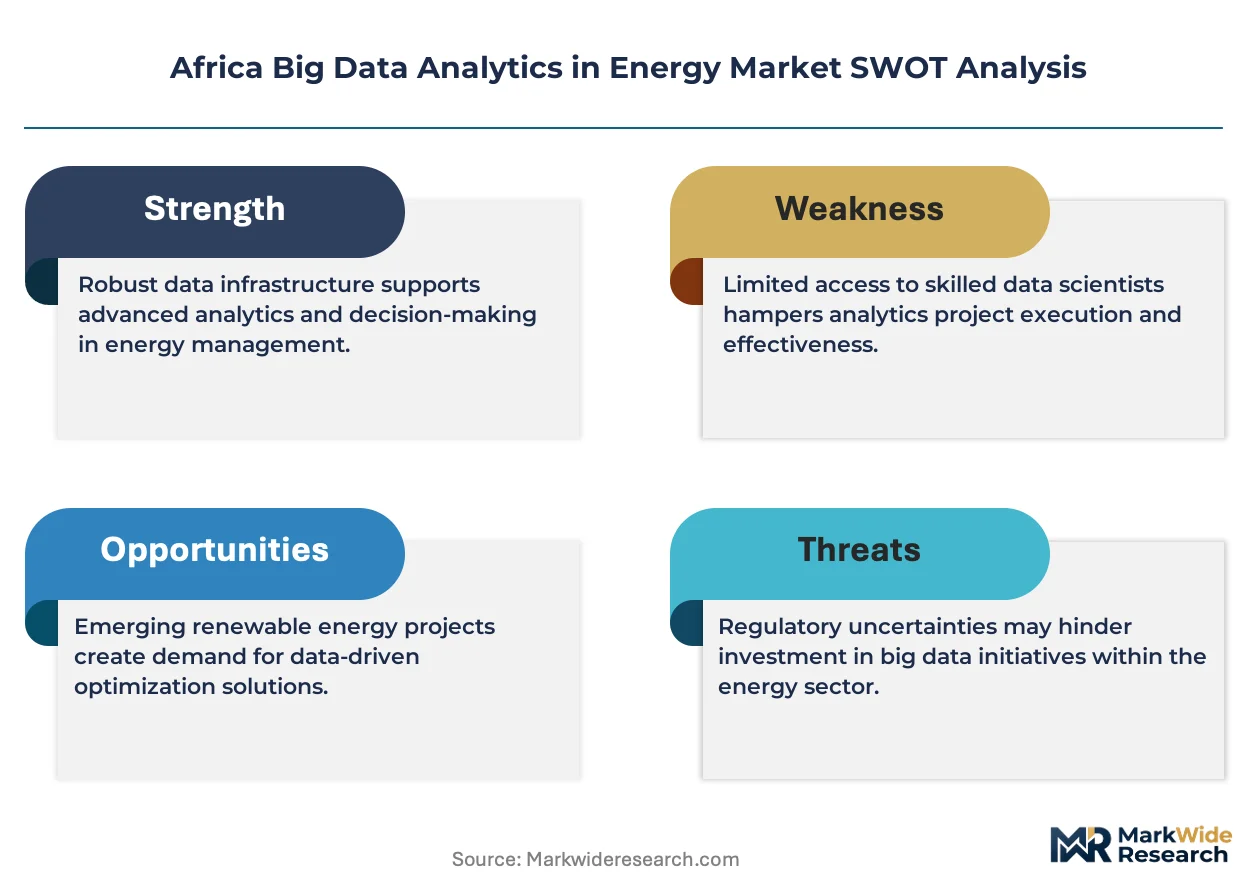
- Hybrid Cloud Infrastructure Costs:The requirement to maintain on-premises SCADA nodes while operating regional cloud instances in Nairobi, Lagos, and Cape Town doubles platform deployment expenditure.
- Latency Threshold Engineering:Grid balancing applications demand sub-100 millisecond data processing, constraining algorithmic complexity and vendor selection.
- Skills Concentration Geography:Data science talent clusters in Johannesburg, Lagos, and Nairobi, leaving secondary markets dependent on remote implementation support.
Strategic Opportunities
- Ethiopia's Generation Expansion:The Grand Ethiopian Renaissance Dam and associated transmission infrastructure create greenfield demand for generation forecasting and grid integration analytics.
- EU Carbon Border Adjustment Mechanism:African energy exporters require emissions-tracking analytics to maintain market access, opening compliance software verticals.
- Satellite Imagery Convergence:Fusion of remote sensing data with ground sensor networks enables predictive vegetation management for transmission line operators.
Industry Challenges
- Legacy System Integration Friction:Pre-digital substations and proprietary SCADA protocols resist API standardization, extending deployment timelines.
- Cybersecurity Certification Burden:ISO 27001 and NERC CIP-aligned security audits add six to nine months to utility procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Big Data Analytics in Energy Market |
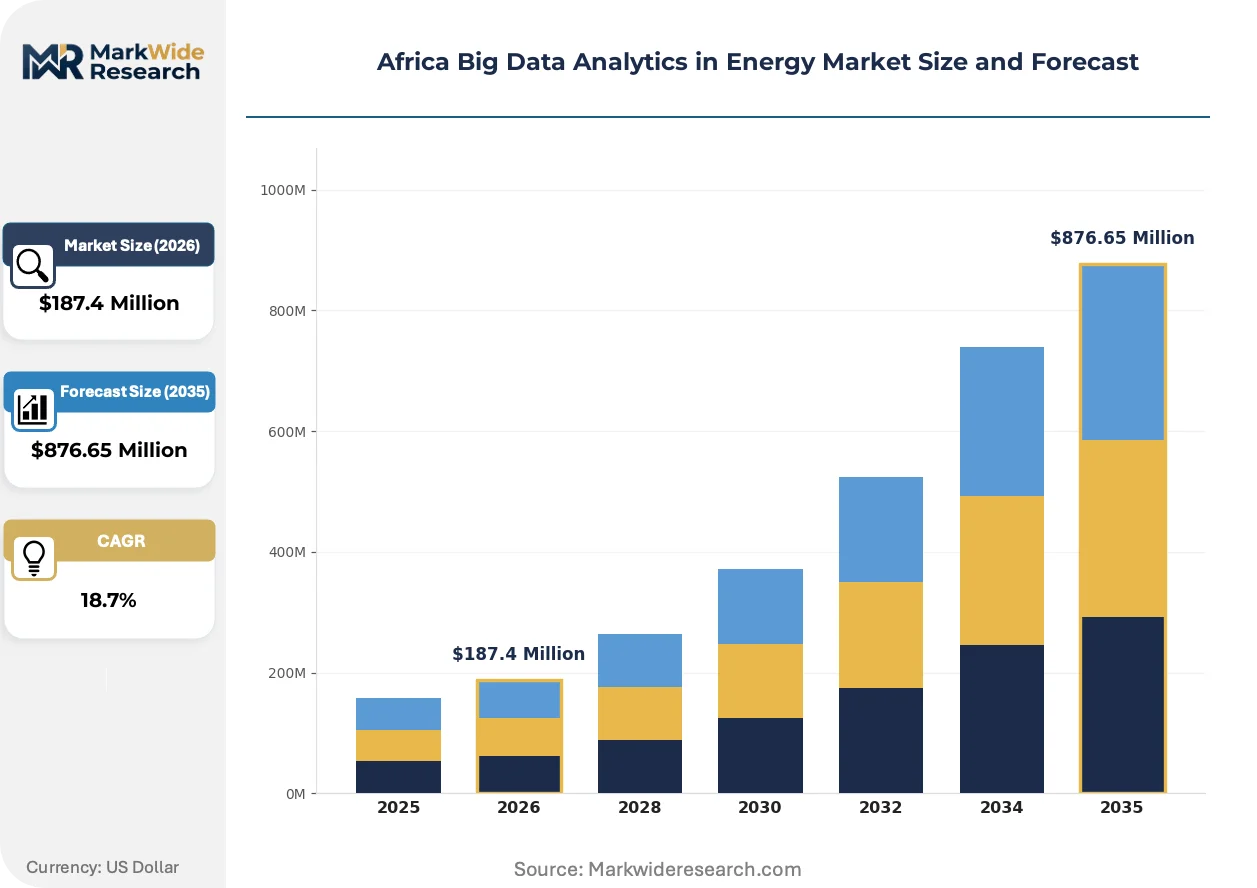
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Analytics, Descriptive Analytics, Prescriptive Analytics, Data Mining Industry Vertical: Renewable Energy, Oil & Gas, Utilities, Power Generation Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Energy Companies, Research Institutions, Government Agencies, Consulting Firms |
| Companies Covered | IBM Corporation, Microsoft Corporation, GE Vernova, Honeywell International, Accenture plc, Siemens Aktiengesellschaft, SAP SE, Dimension Data, MTN Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Big Data Analytics in Energy Market Evolving Landscape
Edge computing architectures are displacing centralized processing for time-critical grid applications, while machine learning model compression techniques enable deployment on resource-constrained hardware.
Digital twin technology is virtualizing physical generation and transmission assets across South African and Nigerian utilities. Eskom and independent power producers in the Renewable Energy Independent Power Producer Procurement Programme deploy virtual replicas for scenario testing and operational optimization. This virtualization is collapsing the traditional separation between planning and real-time operations teams.
South Africa's National Energy Regulator has tightened grid code data submission requirements, mandating standardized telemetry formats from all generators above 10 MW. The regulation forces platform migrations among legacy analytics vendors and opens procurement windows for compliant entrants. Independent power producers are responding by bundling analytics subscriptions into power purchase agreement negotiations.
Utility procurement departments are unbundling historical reporting modules from predictive analytics suites, contracting specialized vendors for algorithm development while retaining incumbent providers for visualization layers. This disaggregation is most visible in Cape Town and Johannesburg smart meter deployments, where municipalities separate data infrastructure from analytical application procurement. East African utilities are replicating this pattern to accelerate vendor diversification.
Africa Big Data Analytics in Energy Market Segmentation
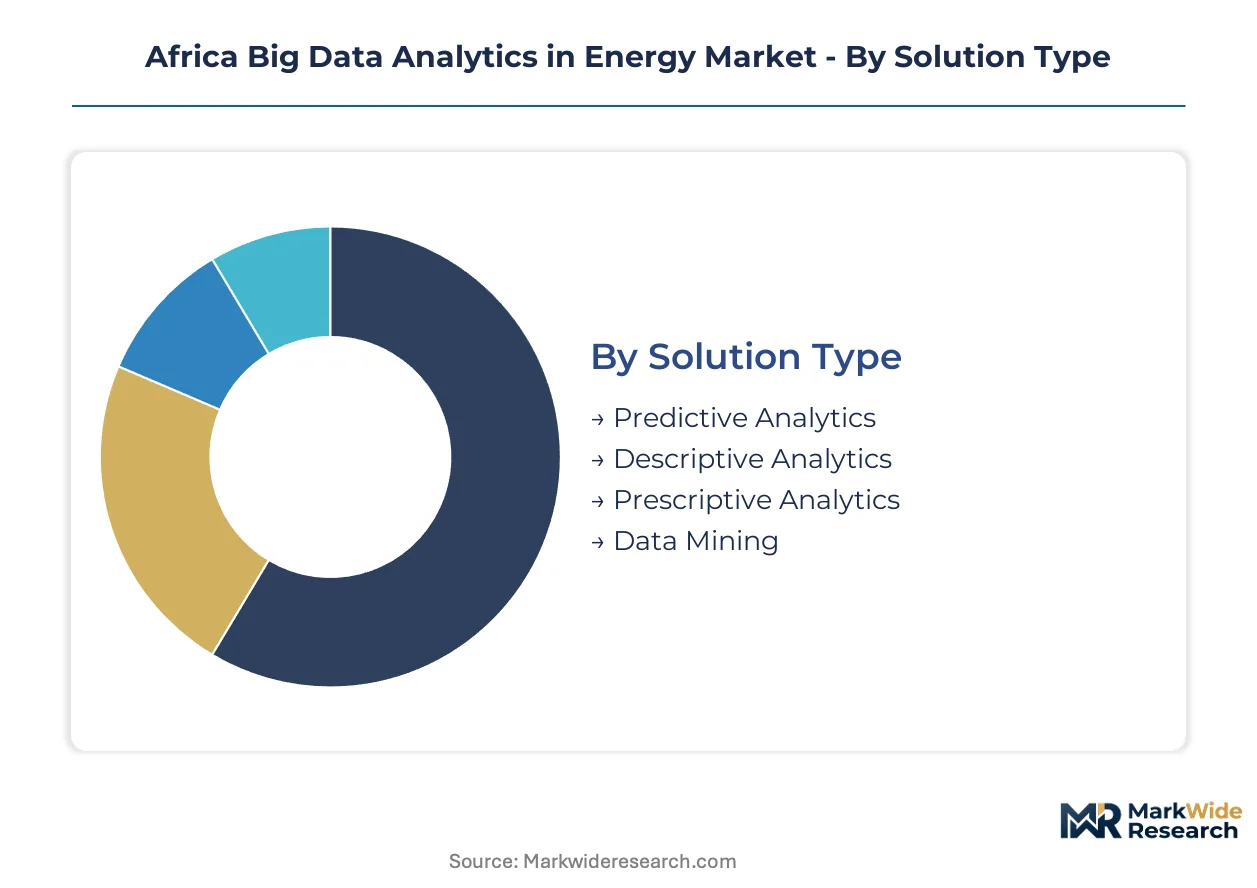
Segmentation in Africa's energy analytics market reveals how infrastructure constraints and regulatory mandates reshape procurement patterns across solution architectures and customer types. Understanding these divides exposes where platform investments concentrate and which deployment models align with data sovereignty requirements.
Solution Type:
The use-case spectrum stretches from failure prevention to strategic optimization, with each solution tier commanding distinct latency tolerances and integration complexity.
- Predictive Analytics:Machine learning models process time-series sensor feeds to forecast equipment failures before operational disruption. East African utilities in Kenya, Tanzania, and Uganda prioritize this capability to compress spare parts logistics cycles across vast territories. The dominant share belongs to Predictive Analytics, while Prescriptive Analytics is closing the gap fastest.
- Descriptive Analytics:Historical data aggregation and visualization tools that reconstruct past performance patterns for compliance reporting and operational review. Nigerian Electricity Regulatory Commission mandates drive procurement among legacy generators seeking grid code alignment.
- Prescriptive Analytics:Optimization engines that recommend specific operational adjustments based on scenario modeling. South African independent power producers in the Renewable Energy Independent Power Producer Procurement Programme deploy these for generation forecasting and market bidding.
- Data Mining:Pattern extraction from unstructured operational datasets including maintenance logs and satellite imagery. Transmission line operators apply this to vegetation management and corridor risk assessment.
Platform unbundling trends are separating predictive algorithm development from visualization layers, creating procurement flexibility across all four solution tiers.
Industry Vertical:
Regulatory pressure and asset digitization maturity create divergent spending velocities across Africa's fragmented energy infrastructure.
- Renewable Energy:Generation forecasting and grid integration analytics for variable output assets. South Africa's Renewable Energy Independent Power Producer Procurement Programme mandates real-time telemetry submission, forcing platform upgrades among wind and solar operators. The dominant share belongs to Oil & Gas, while Renewable Energy is expanding most quickly.
- Oil & Gas:Reservoir analytics and upstream optimization dominate Nigerian spending, with operators deploying advanced subsurface modeling to extend field life cycles and compress extraction economics.
- Utilities:Grid balancing and predictive maintenance applications serving distribution network operators. Eskom's SCADA consolidation programs anchor regional demand.
- Power Generation:Thermal plant optimization and emissions tracking for compliance with emerging carbon accounting frameworks including the EU Carbon Border Adjustment Mechanism.
Vertical specialization is accelerating as vendors develop pre-configured modules for hydroelectric, geothermal, and hybrid mini-grid configurations.
Deployment Model:
Data sovereignty requirements and latency thresholds fragment infrastructure decisions between edge, on-premises, and cloud architectures.
- Hybrid Cloud:Sensitive SCADA data remains on-premises while non-critical workloads migrate to regional cloud nodes in Nairobi, Lagos, and Cape Town. This architecture satisfies Nigeria's data localization preferences and South Africa's cybersecurity certification burdens. The dominant share belongs to Hybrid Cloud, while Public Cloud is gaining share fastest.
- Private Cloud:Dedicated infrastructure deployments for large utilities with consistent compute demands and strict isolation requirements.
- Public Cloud:Shared infrastructure serving research institutions and consulting firms with variable, burst-oriented processing needs.
- On-Premises:Legacy installations in pre-digital substations resisting API standardization, though migration pressure is mounting from grid code compliance deadlines.
Edge computing architectures are displacing centralized processing for time-critical grid balancing applications with sub-100 millisecond latency requirements.
End User:
Procurement authority and technical sophistication determine whether analytics platforms serve operational, regulatory, or advisory functions.
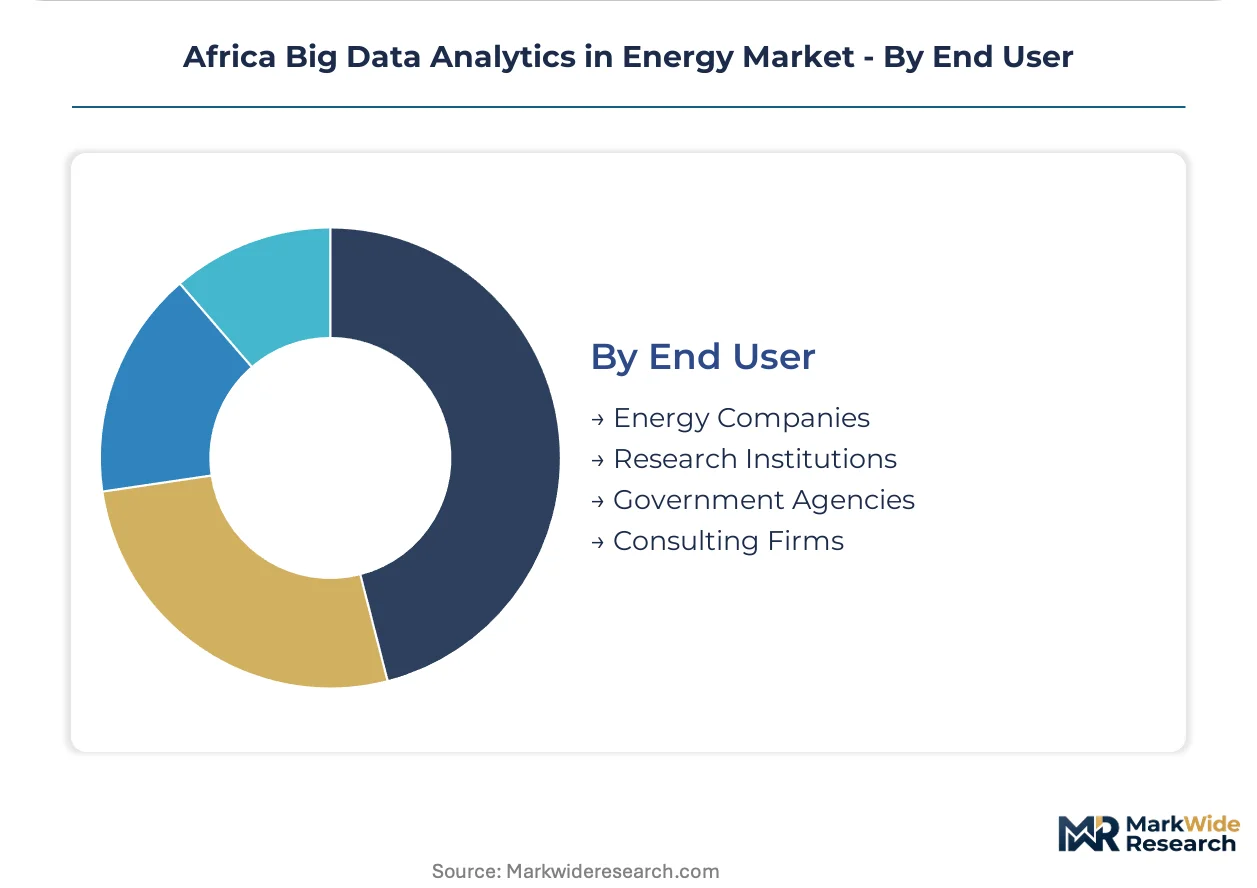
- Energy Companies:Integrated oil majors, independent power producers, and national utilities constitute the primary revenue base. South African and Nigerian operators lead in platform sophistication and contract value. The dominant share belongs to Energy Companies, while Government Agencies are climbing the fastest.
- Government Agencies:National regulators and the African Union's Single Electricity Market framework drive standardization mandates. Ethiopia's Grand Ethiopian Renaissance Dam authority represents emerging procurement authority.
- Research Institutions:Universities and technical centers developing localized algorithms for vegetation management, demand forecasting, and climate impact modeling.
- Consulting Firms:Implementation partners bridging skills concentration gaps in secondary markets remote from Johannesburg, Lagos, and Nairobi talent clusters.
Utility procurement departments are increasingly unbundling algorithm development from infrastructure management, expanding consulting firm and research institution participation in specialized workstreams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's National Energy Regulator anchors regulatory momentum across the continent, with grid code mandates cascading through Nigeria's Electricity Regulatory Commission and Kenya's Energy and Petroleum Regulatory Authority. Utility procurement cycles in these three markets set the tempo for vendor market entry and platform certification requirements.
South Africa
Eskom's SCADA consolidation programs drive predictive maintenance procurement, while independent power producers under the Renewable Energy Independent Power Producer Procurement Programme mandate real-time telemetry submission. Johannesburg and Cape Town host the continent's densest clusters of data science talent, with smart meter deployments accelerating municipal analytics adoption.
Nigeria
Upstream oil operators deploy reservoir analytics to compress extraction economics and extend field life cycles, anchored by compliance requirements from the Nigerian Electricity Regulatory Commission for generators above 10 MW. Lagos concentrates hybrid cloud infrastructure investment as operators balance data localization preferences with regional cloud node access.
Kenya
Kenya Power's predictive maintenance expansion targets grid downtime reduction where spare parts logistics span vast territories. The Energy and Petroleum Regulatory Authority's grid integration standards for geothermal and wind assets create procurement pull for generation forecasting platforms. Nairobi anchors East African cloud node infrastructure.
Ethiopia
The Grand Ethiopian Renaissance Dam authority generates greenfield demand for generation forecasting and cross-border grid synchronization analytics under the African Union's Single Electricity Market framework. Addis Ababa's emerging procurement authority is consolidating SCADA data lakes to enable regional power pool integration.
Uganda
Umeme Limited's distribution network investments prioritize failure-prevention analytics to manage infrastructure across dispersed geographies. The Electricity Regulatory Authority's renewable energy licensing conditions require real-time generation data submission from independent power producers. Kampala serves as a secondary skills hub supporting regional implementation.
Africa Big Data Analytics in Energy Market Competitive Landscape
Capability concentration sits with global technology conglomerates possessing AI platforms and utility sector expertise; scale advantage sits with regional systems integrators and telecommunications operators with existing infrastructure relationships. The market structure fragments across three tiers: multinational platform vendors, regional implementation partners, and niche algorithm specialists. Strategic moves center on hybrid cloud architecture partnerships and unbundling of algorithm development from infrastructure management.
Within the multinational platform tier, IBM Corporation and Microsoft Corporation exemplify divergent approaches to utility engagement. IBM leverages Watson platform capabilities to anchor predictive maintenance relationships with national utilities and independent power producers. Microsoft competes through Azure-based grid analytics integrated with municipal smart meter deployments. Siemens Aktiengesellschaft occupies a position bridging hardware automation heritage with software analytics expansion. Regional implementation strength concentrates among Johannesburg, Lagos, and Nairobi-based specialists who bridge skills concentration gaps in secondary markets.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| GE Vernova |
| Honeywell International |
| Accenture plc |
| Siemens Aktiengesellschaft |
| SAP SE |
| Dimension Data |
| MTN Group |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Johannesburg-based data science talent pools compresses pricing tier spreads between hybrid cloud deployments and forces supply chain configuration toward remote implementation models. This concentration dynamic simultaneously elevates platform subscription costs for East African utilities and extends vendor payment terms to offset skills logistics.
Pricing Analysis
Geographic price spreads between Lagos, Nairobi, and Cape Town cloud node deployments exceed those between on-premises and hybrid architectures. SaaS-tiered subscription models dominate, with price differentiation anchored in ISO 27001 certification tier and customization depth for legacy SCADA integration. Cost compression in the mid-market tier intensifies as regional systems integrators bundle implementation services at discounted rates. Government agencies exhibit highest price sensitivity due to procurement cycle rigidities, while integrated oil majors in Nigeria demonstrate lowest sensitivity given reservoir optimization ROI timelines.
Supply Chain Analysis
Extended payment terms from South African independent power producers to analytics vendors now stretch 90-120 days, reflecting supply-chain finance pressure from Eskom's procurement delays. Component sourcing draws from Ireland for edge computing hardware, India for software development labor, and South Africa for regional cloud infrastructure. Single-source vulnerability concentrates in NVIDIA GPU supply for machine learning workloads. Distribution runs through Johannesburg-based systems integrators with satellite offices in Lagos and Nairobi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of SCADA-certified data scientists across East Africa concentrates platform deployment capability in three cities, creating structural bottlenecks for nationwide utility rollouts. This scarcity rewards vendors who embed training programs within implementation contracts.
For Market Incumbents: Insulate market position by deepening vertical integration into edge computing hardware supply chains and accelerating ISO 27001 certification investments ahead of Nigerian Electricity Regulatory Commission deadline tightening. The threat of Microsoft Azure's municipal smart meter bundling requires defensive capability expansion in grid balancing analytics. Capacity addition in Nairobi cloud nodes represents the priority lever for East African retention. For New Entrants and Emerging Players: Ethiopia's Grand Ethiopian Renaissance Dam authority represents the most penetrable entry point among government agencies, with greenfield procurement unencumbered by legacy vendor relationships. Secondary East African utilities in Tanzania and Uganda offer white-space expansion where skills concentration gaps have slowed incumbent deployment. A consulting-led go-to-market angle, partnering with regional research institutions for algorithm localization, bypasses direct competition with IBM Watson's predictive maintenance incumbency. For Investors and Strategic Acquirers: South Africa's National Energy Regulator grid code tightening reshapes the acquisition landscape by devaluing non-compliant legacy analytics portfolios. Long-term viability centers on platforms with sub-100 millisecond latency engineering and hybrid cloud architecture flexibility. Acquisition target archetype: regional systems integrators with existing Eskom or NERC relationships but underdeveloped algorithm development capability. The signal to watch is procurement unbundling velocity in Cape Town and Johannesburg municipal smart meter programs.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Architecture Partnership | Enables Nigerian operators to satisfy data localization preferences while accessing regional compute. |
| Predictive Algorithm Unbundling | Separates machine learning development from visualization layers to accelerate vendor diversification. |
| Edge Computing Deployment | Addresses sub-100 millisecond latency requirements for grid balancing applications in Kenya. |
| SCADA Data Lake Consolidation | Supports African Union Single Electricity Market cross-border synchronization mandates. |
| ISO 27001 Certification Investment | Compresses six-to-nine month procurement cycle delays from security audit requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of utility planning officer interviews, IPP project developer discussions, EPC contractor assessments, and grid operator consultations. Secondary validation incorporated EIA generation data, IEA Africa energy outlooks, FERC-equivalent regulatory filings from South Africa's National Energy Regulator, and project development databases tracking renewable procurement programs. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure investment flows.
Forecast inputs span solution type adoption curves, deployment model migration rates, and vertical spending velocity across the projection horizon. Segmentation dimensions modeled include generation capacity tier, regulatory framework cluster, regional grid synchronization status, and fuel source mix. CAGRs derived from equipment procurement pipeline analysis and platform subscription renewal rates. Industry-specific inputs incorporated SCADA consolidation timelines and grid code compliance deadline schedules.
Practitioners should monitor NERC and NERSA regulatory amendment cycles, EU Carbon Border Adjustment Mechanism implementation phasing, and Ethiopian transmission infrastructure completion for early signals. Forecasts embed assumptions regarding skills concentration persistence and cloud node expansion cadence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
GCC Well Testing Services Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
China Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Digitalization Platform Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
Energy Intelligence Solutions Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Oil Condition Monitoring Market