
 Asia-Pacific Energy Storage Systems Market | 2026-2036
Asia-Pacific Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Energy Storage Systems Market Outlook
Aftermarket service revenue is tilting from cell replacement toward predictive analytics and performance guarantees. Contemporary Amperex Technology Co Ltd leverages its vertical integration into cathode materials to control cost structures across the supply chain. BYD anchors its position through captive demand from electric buses and passenger vehicles. LG Energy Solution competes on manufacturing scale, operating gigafactories in China and South Korea that feed regional utility tenders.
Energy storage systems encompass electrochemical, mechanical, and thermal devices that capture electrical energy for later discharge, with lithium-ion cells typically operating at nominal voltages between 3.2V and 3.7V per cell depending on cathode chemistry. These systems buffer intermittency from renewable generation and stabilize grid frequency through rapid charge-discharge cycles. Lithium-ion technology dominates installed capacity due to energy density advantages, though flow batteries gain traction in eight-to-twelve hour duration applications where cycling economics favor aqueous electrolyte architectures. Application demand clusters around renewable integration as solar and wind penetration rises, while frequency regulation contracts offer faster payback periods in markets with ancillary service markets. Delivery mode selection splits between centralized utility-scale installations and distributed commercial-industrial configurations behind the meter.
China's MIIT enforces GB standards for battery safety and recycling that dictate cell design and second-life protocols. Japan's METI and South Korea's MFDS coordinate on thermal runaway testing methodologies that shape product certification requirements for regional market access. Australia's CEA mandates grid connection standards that determine inverter and power conversion system specifications. Stakeholders must monitor how India's BIS certification timeline and China's evolving dual carbon enforcement mechanisms alter procurement lead times and supplier qualification criteria.
Market Dynamics
China's dual carbon enforcement mechanisms are compressing procurement timelines across the Asia-Pacific region, forcing developers to accelerate grid-scale storage deployments ahead of renewable commissioning deadlines. Japan's METI storage mandates and Australia's CEA grid codes are synchronizing technical specifications that reshape supplier qualification criteria.
Growth Catalysts
- Utility-scale solar pairing:Australia's grid-scale solar developers are bundling lithium-ion storage into power purchase agreements to firm intermittency and access frequency regulation revenue streams.
- Industrial microgrid deployments:India's manufacturing clusters are installing behind-the-meter battery systems to manage peak demand charges and backup critical production lines.
- METI storage mandates:Japan's Ministry of Economy, Trade and Industry requires grid operators to procure specified storage volumes, creating guaranteed offtake for four-hour duration systems.
Market Restraints
- Lithium carbonate price volatility:Cathode material costs swing with South American brine extraction volumes and Chinese refining capacity utilization, squeezing cell manufacturer margins.
- Cell supply concentration:Gigafactory output clusters in China's coastal provinces create single-source dependency risks for regional integrators outside mainland supply chains.
- Flow battery substitution:Aqueous vanadium systems capture eight-to-twelve hour duration tenders where cycling economics favor non-flammable electrolyte architectures over lithium-ion.
Strategic Opportunities
- Second-life automotive packs:Retired electric bus batteries from China's BYD fleets are reconditioning for stationary storage in Southeast Asian commercial installations at degraded capacity price points.
- Maritime port electrification:Singapore and Busan container terminals are piloting shore-power battery buffers to replace auxiliary diesel generators during vessel berthing.
- BIS certification acceleration:India's Bureau of Indian Standards is streamlining cell testing timelines for domestic assembly operations, shortening supplier qualification windows for local integrators.
Industry Challenges
- Thermal runaway containment engineering:System integrators must demonstrate NFPA 855-equivalent suppression protocols to satisfy Australia's CEA grid connection standards and China's GB safety mandates.
- Power conversion system interoperability:Inverter firmware compatibility gaps between Chinese and Korean battery management systems delay commissioning timelines for multi-vendor projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Energy Storage Systems Market |
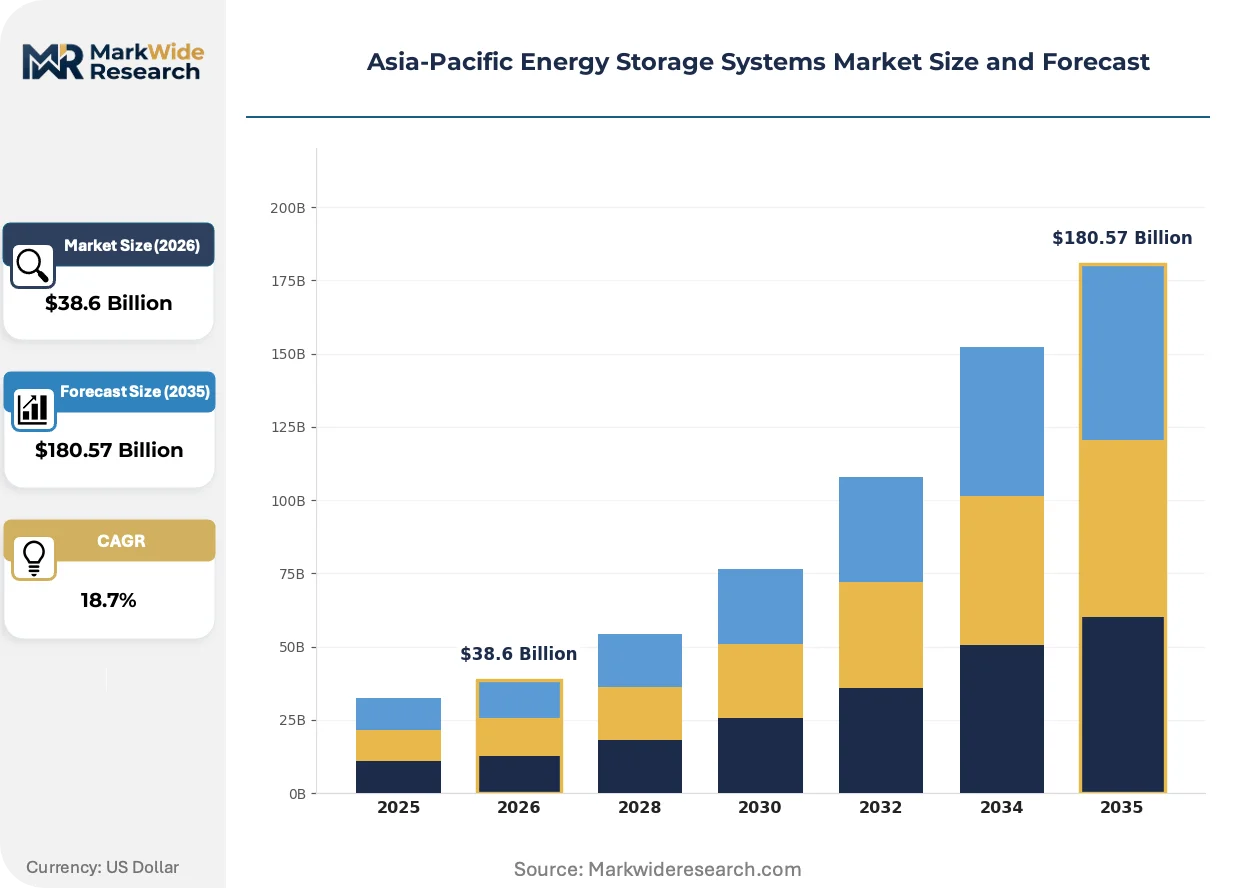
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $180.57 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
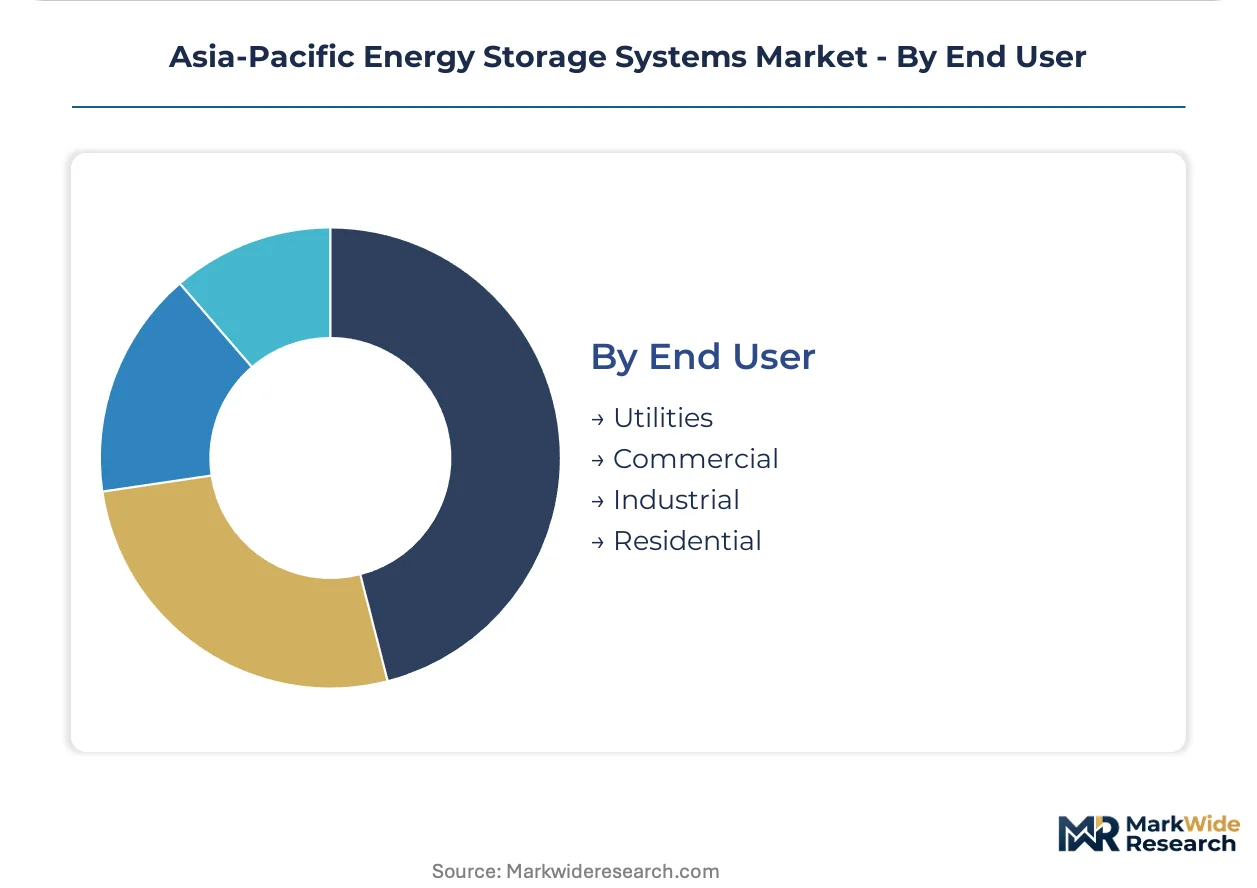
| Segmentation | Technology: Lithium-ion, Lead-acid, Flow Batteries, Sodium-sulfur Application: Renewable Integration, Frequency Regulation, Demand Response, Backup Power Delivery Mode: On-site, Off-site, Distributed, Centralized End User: Utilities, Commercial, Industrial, Residential |
| Companies Covered | Contemporary Amperex Technology Co Ltd, BYD, Tesla, LG Energy Solution, Samsung SDI, General Electric, Siemens, ABB, Panasonic Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Energy Storage Systems Market Strategic Shifts
Solid-state electrolyte development is disrupting conventional cell architectures across the Asia-Pacific region. Sodium-ion chemistry and hybrid thermal storage are gaining commercial traction as developers seek cost de-risking and safety differentiation.
Lithium iron phosphate cathode chemistry is migrating from electric vehicle traction packs into grid-scale stationary applications. Chinese utility developers are specifying LFP cells for four-hour duration tenders to capitalize on improved cycle life and thermal stability. This chemistry shift is compressing nickel-cobalt-manganese market share in utility procurement frameworks where safety certification weighs heavily.
China's MIIT is tightening GB standards for battery recycling and second-life traceability, requiring cell-level digital passports from production through end-of-life processing. Manufacturers must retrofit assembly lines for blockchain-enabled lifecycle tracking. Korean and Japanese exporters to China are restructuring supply chain documentation systems to satisfy these data architecture requirements.
Energy-as-a-service contracting is displacing capital purchase models in India's commercial-industrial segment. Third-party developers retain battery asset ownership and sell guaranteed peak-shaving outcomes to factory operators. This financing structure concentrates in Tamil Nadu and Gujarat textile clusters where working capital constraints block upfront storage investments.
Asia-Pacific Energy Storage Systems Market Segmentation
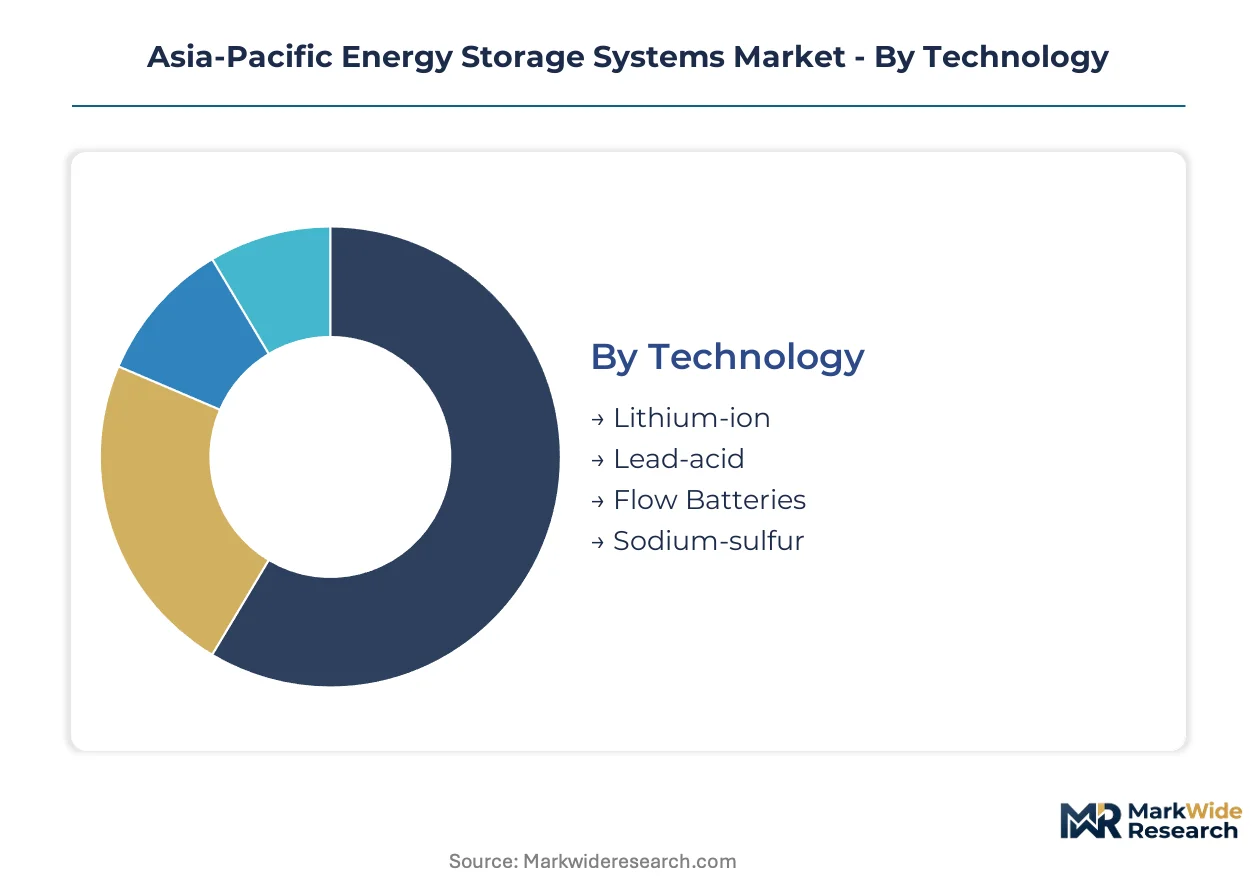
Segmentation in energy storage reveals how technology choices, application requirements, and delivery economics fragment procurement patterns across the Asia-Pacific region. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier positioning.
Technology:
After-sales service intensity varies sharply by chemistry type, with lithium-ion demanding thermal management protocols and flow batteries requiring electrolyte maintenance contracts.
- Lithium-ion:Lithium iron phosphate and nickel-cobalt-manganese chemistries dominate utility-scale tenders due to energy density advantages and established recycling infrastructure. Procurement concentrates in China's coastal manufacturing clusters where GB standards enforcement drives cell-level traceability requirements. Australia's grid-scale solar pairing and Japan's METI-mandated storage volumes anchor regional demand.
- Flow Batteries:Aqueous vanadium and zinc-bromine systems capture eight-to-twelve hour duration applications where cycling economics favor non-flammable electrolyte architectures. India's industrial microgrid developers specify flow batteries for textile cluster installations requiring daily deep discharge cycles.
- Lead-acid:Mature technology retains share in residential backup power segments across Southeast Asia where upfront cost sensitivity outweighs cycle life considerations.
- Sodium-sulfur:High-temperature ceramic electrolyte systems serve Japanese utility frequency regulation contracts requiring rapid response capabilities.
By volume, lithium-ion leads. By growth pace, flow batteries are expanding most quickly in long-duration tenders.
Application:
Cost tier stratification separates capital-intensive utility infrastructure from behind-the-meter commercial installations with faster payback requirements.
- Renewable Integration:Solar and wind pairing drives four-hour duration procurement specifications across Australian and Chinese utility frameworks. Developers bundle storage into power purchase agreements to firm intermittency and access ancillary service revenue streams.
- Frequency Regulation:Sub-second response requirements favor lithium-ion systems with high C-rate capabilities. Japan's METI mandates create guaranteed offtake for grid operators procuring specified storage volumes.
- Demand Response:Peak shaving applications concentrate in India's Tamil Nadu and Gujarat manufacturing clusters where third-party energy-as-a-service providers retain asset ownership.
- Backup Power:Critical load protection drives residential and commercial procurement across typhoon-exposed Philippine and Vietnamese markets.
By installed capacity, renewable integration leads. By contract velocity, frequency regulation is climbing the fastest.
Delivery Mode:
Customer type determines whether assets sit behind the meter or within transmission network boundaries, reshaping interconnection compliance obligations.
- Centralized:Utility-scale installations connect at transmission voltage levels and must satisfy Australia's CEA grid codes and China's GB safety mandates for thermal runaway containment.
- Distributed:Commercial-industrial systems behind the meter avoid transmission interconnection delays but face fragmented local permitting across Indian states.
- On-site:Containerized solutions predominate in maritime port electrification pilots at Singapore and Busan terminals replacing auxiliary diesel generators.
- Off-site:Virtual power plant aggregation models are emerging in South Korean demand response markets where MFDS-certified systems pool distributed capacity.
By project count, distributed leads. By capital deployment, centralized is gaining share fastest.
End User:
Supply concentration in Chinese gigafactories creates divergent procurement leverage between state-backed utilities and fragmented commercial buyers.
- Utilities:State grid operators in China and Japan drive volume procurement through centralized tenders with stringent supplier qualification criteria.
- Industrial:Manufacturing clusters specify microgrid configurations combining solar, storage, and backup generation to manage peak demand charges.
- Commercial:Office and retail installations favor energy-as-a-service contracting where developers shoulder upfront capital and sell guaranteed outcomes.
- Residential:Single-family and apartment deployments remain concentrated in premium segments across Australian and Japanese urban centers.
By revenue, utilities lead. By installation growth, industrial is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity divides procurement patterns sharply across the Asia-Pacific region. Chinese state-backed utilities negotiate volume-driven contracts with minimal cost sensitivity, while Indian textile manufacturers and Southeast Asian commercial buyers demand energy-as-a-service structures to eliminate upfront capital burdens.
China
Dual carbon enforcement mechanisms compress deployment timelines for grid-scale solar pairing projects. MIIT's GB standards for battery safety and recycling mandate cell-level digital passports from production through end-of-life. Yangtze River Delta manufacturing clusters retrofit assembly lines for blockchain-enabled lifecycle tracking to satisfy these data architecture requirements.
Japan
METI storage mandates create guaranteed offtake for four-hour duration systems serving grid operator procurement frameworks. Thermal runaway testing methodologies coordinated with South Korea's MFDS reshape product certification requirements. Kanto region frequency regulation contracts favor high C-rate lithium-ion capabilities for sub-second response requirements.
India
Tamil Nadu and Gujarat textile clusters drive behind-the-meter battery installations to manage peak demand charges and backup critical production lines. BIS certification timelines are streamlining for domestic assembly operations, shortening supplier qualification windows. Energy-as-a-service contracting concentrates ownership with third-party developers selling guaranteed peak-shaving outcomes.
Australia
Grid-scale solar developers bundle lithium-ion storage into power purchase agreements to firm intermittency and access frequency regulation revenue streams. CEA grid connection standards mandate NFPA 855-equivalent thermal runaway suppression protocols for utility-scale installations. New South Wales and Queensland transmission voltage projects anchor regional capital deployment.
South Korea
MFDS-certified systems pool distributed capacity through emerging virtual power plant aggregation models in demand response markets. Busan container terminals pilot shore-power battery buffers replacing auxiliary diesel generators during vessel berthing. Seoul Capital Area gigafactories feed regional utility tenders through manufacturing scale advantages.
Asia-Pacific Energy Storage Systems Market Competitive Environment
Vertically integrated cell manufacturers and specialized system integrators split the market between captive supply chain control and project-specific engineering capabilities. The vendor base concentrates around three strategic archetypes: cathode material owners leveraging backward integration, captive demand holders from automotive or bus fleets, and manufacturing scale operators running multi-gigawatt hour production lines. Competitive moves center on supply chain documentation restructuring for Chinese GB compliance and power conversion system interoperability investments to reduce multi-vendor commissioning delays.
Within the integrated-manufacturer tier, Contemporary Amperex Technology Co Ltd and BYD occupy positions shaped by their respective supply chain architectures. LG Energy Solution sits within the scale-driven archetype alongside Samsung SDI, both representing Korean fabrication capabilities. These three exemplify how geographic concentration in coastal Chinese provinces and Korean industrial corridors creates divergent qualification pathways for regional integrators.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co Ltd |
| BYD |
| Tesla |
| LG Energy Solution |
| Samsung SDI |
| General Electric |
| Siemens |
| ABB |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate price volatility from South American brine extraction swings determines both the compression of tier spreads between LFP and NCM cell offerings and the geographic clustering of cathode material refining capacity. Chinese gigafactory output concentration amplifies procurement leverage for state-backed utilities while squeezing margin buffers for regional integrators dependent on spot market cathode purchases.
Pricing Analysis
Aftermarket predictive analytics and performance guarantee contracts now drive lifetime value capture more than cell replacement revenue. Three-tier pricing structure across premium certified, standard utility-grade, and economy second-life tiers separates procurement frameworks by thermal runaway certification depth and cycle life warranties. Pricing pressure stems from aqueous vanadium flow battery substitution in eight-to-twelve hour duration tenders where cycling economics favor non-flammable architectures. Indian textile manufacturers exhibit highest price sensitivity and demand energy-as-a-service structures, while Chinese state grid operators negotiate volume contracts with minimal cost elasticity.
Supply Chain Analysis
Upstream spodumene concentrate from Australian hard-rock mines and Chilean-Argentine brine evaporation feeds Chinese refining corridors. Cathode precursor production draws from nickel laterite processing in Indonesia, cobalt hydroxide from the DRC, and lithium carbonate from South American salares. Single-source vulnerability concentrates in China's coastal gigafactory provinces where GB standards enforcement creates documentation chokepoints for Korean and Japanese exporters. Distribution runs through utility-scale EPC contractors for centralized projects and third-party energy-as-a-service platforms for behind-the-meter commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across application requirements, duration specifications, and certification tiers creates niche specialization opportunities. The shift from capital purchase to energy-as-a-service contracting in India's manufacturing clusters exemplifies how financing innovation opens entry points for non-integrated players.
For Market Incumbents: Harden thermal runaway containment engineering capabilities to satisfy Australia's CEA grid codes and China's evolving GB safety mandates. Expand backward integration into cathode material production to offset lithium carbonate price swings eroding cell margins. Lock multi-year offtake agreements with Australian solar developers bundling storage into power purchase agreements before METI-mandated volumes saturate Japanese procurement pipelines. For New Entrants and Emerging Players: Maritime port electrification pilots at Singapore and Busan container terminals represent the most penetrable entry point for shore-power battery buffer specialists lacking utility-scale track records. India's BIS certification streamlining for domestic assembly operations shortens supplier qualification windows for local integrators targeting Tamil Nadu textile clusters. Position around flow battery electrolyte maintenance contracts where incumbent lithium-ion players lack service infrastructure. For Investors and Strategic Acquirers: The market sits at a manufacturing capacity expansion phase that favors cathode material owners with upstream resource positions. Long-term viability hinges on exposure to four-hour duration utility tenders rather than frequency regulation saturation. Acquisition targets should demonstrate blockchain-enabled lifecycle tracking systems compliant with China's MIIT digital passport requirements. Monitor South Korean virtual power plant aggregation model adoption as inflection signal for distributed asset valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standards Compliance Investment | Blockchain-enabled cell-level traceability satisfies China's MIIT recycling mandates and unlocks market access. |
| Power Conversion System Interoperability | Firmware compatibility between Chinese BMS and Korean inverters reduces multi-vendor commissioning delays. |
| Second-Life Battery Reconditioning | Retired BYD electric bus packs from China feed Southeast Asian commercial installations at degraded capacity price points. |
| Energy-as-a-Service Platform Buildout | Third-party ownership models bypass working capital constraints blocking upfront storage investments in Indian manufacturing clusters. |
| Long-Duration Flow Battery Deployment | Aqueous vanadium systems capture eight-to-twelve hour tenders where lithium-ion cycling economics weaken. |
Study Parameters
Desk research of IEA storage deployment databases, FERC interconnection filings, and customs trade data preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork captured procurement timeline compression effects from China's dual carbon enforcement mechanisms and Japan's METI storage mandates. Secondary validation drew from CEA grid code documentation, BIS certification procedural updates, and MFDS thermal runaway testing protocols. Bottom-up project pipeline aggregation and top-down regulatory mandate quantification were cross-referenced for triangulation.
Assumptions held fixed include current lithium-ion cost curves and existing GB standards enforcement intensity, while variables included flow battery substitution rates and BIS certification acceleration timelines. The analytical framework segmented by technology chemistry, application duration, delivery mode voltage level, and end-user procurement leverage across the projection horizon. CAGRs were derived from regression against renewable penetration targets and ancillary service market depth. Forecast inputs incorporated METI-mandated storage volumes and Australia's solar pairing bundling trends.
Practitioners should monitor lithium carbonate spot price movements, BIS certification backlog clearance rates, and CEA thermal runaway protocol amendments for early signals of forecast revision. Cross-checking against IEA quarterly storage deployment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Energy Storage Battery for Microgrid Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Hydrogen-Bromine Flow Battery Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Energy Storage Software Market
Energy Storage
Solar Storage System Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market