
 Fuel Cell for Data Center Market | 2026-2036
Fuel Cell for Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell for Data Center Market Foresight
Multi-source fuel cell procurement is rebalancing how hyperscale operators secure resilient power. Bloom Energy leverages its solid oxide platform to anchor on-premises deployments for enterprise clients. Plug Power Inc. sustains hydrogen logistics integration that differentiates its offering from grid-dependent competitors. FuelCell Energy specializes in megawatt-scale carbonate systems that occupy the utility-interactive segment of the data center power stack.
A fuel cell for data center applications electrochemically converts hydrogen or natural gas-derived fuel into electricity through an ion-conducting membrane, typically operating at 45-60% electrical efficiency with usable waste heat for cooling absorption. Solid oxide fuel cells dominate the primary power segment due to their high efficiency and fuel flexibility, while proton exchange membrane systems lead backup power deployments where rapid cold-start capability matters. Modular data center deployments represent the fastest-growing installation category, as standardized fuel cell skids reduce engineering overhead and accelerate commissioning timelines for edge computing and colocation operators.
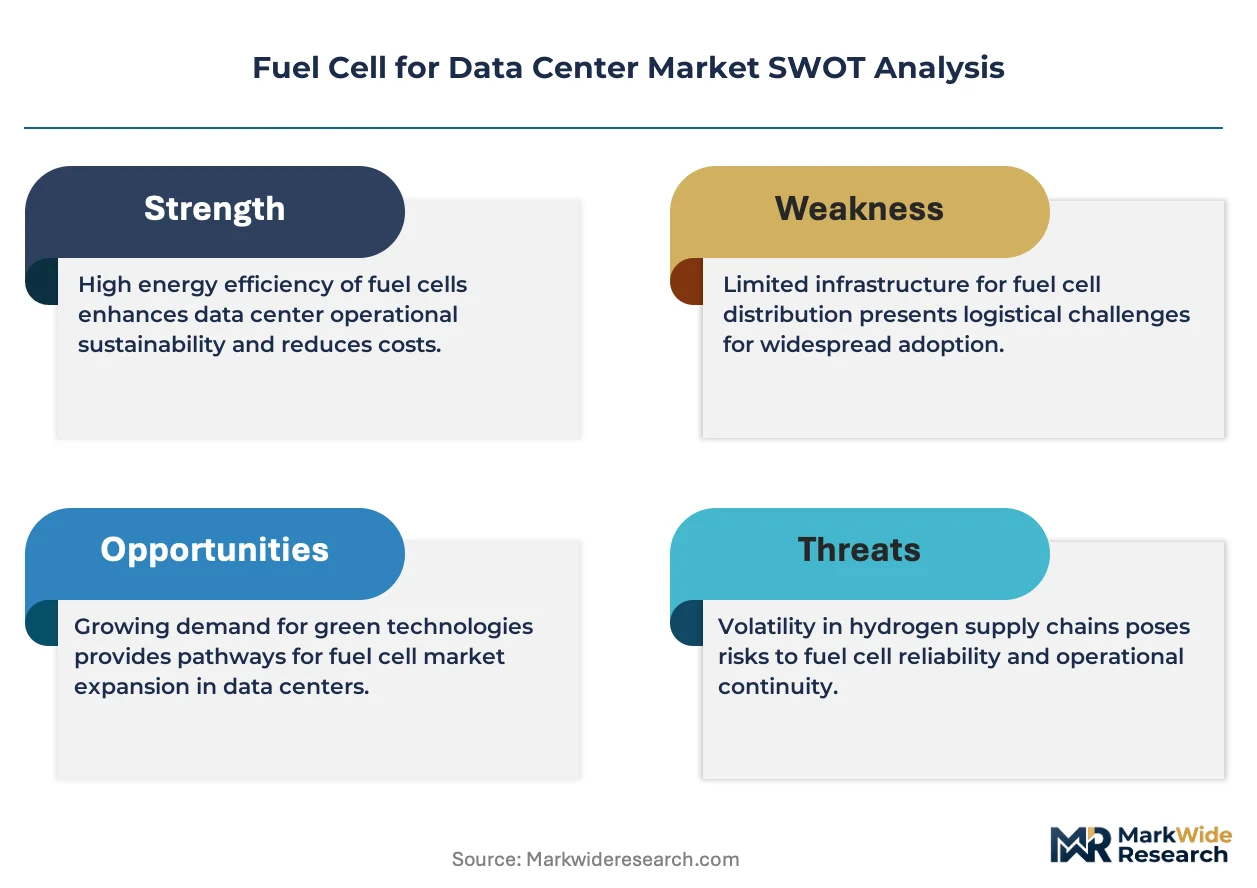
The US EPA and FERC shape project economics through emissions standards and interstate power market rules, while the EU Green Deal and F-Gas Regulation constrain fluorinated coolant use in fuel cell thermal management systems. California's CPUC and South Korea's METI both enforce renewable portfolio standards that credit fuel cell output toward clean energy procurement mandates. Stakeholders must monitor hydrogen supply cost curves and reformer efficiency benchmarks to determine whether on-site fuel production or pipeline delivery yields lower levelized cost of electricity for sustained operations.
Market Dynamics
Grid interconnection queues exceeding five years in Northern Virginia, Singapore, and Frankfurt are forcing hyperscale operators to deploy on-site fuel cells for baseload power rather than await utility infrastructure expansion.
Growth Catalysts
- US Inflation Reduction Act hydrogen production tax credits:The IRA's clean hydrogen incentives reduce levelized cost of electricity for on-site generation by up to 40 percent, making fuel cells cost-competitive with grid power in high-demand clusters.
- Solid oxide fuel cell efficiency gains:Electrical efficiency reaching 60 percent with combined heat and power recovery enables absorption cooling integration, cutting total facility energy consumption for thermal management.
- Northern Virginia data center concentration:Dominion Energy's moratorium on new substations in Loudoun County has compressed procurement timelines, accelerating fuel cell deployments for immediate capacity.
Market Restraints
- Platinum group metal cost volatility:Proton exchange membrane systems depend on iridium and platinum catalysts, with prices fluctuating 300 percent since 2020 and concentrating supply risk in South African and Russian mining operations.
- Hydrogen delivery infrastructure gaps:Pipeline hydrogen remains unavailable outside Gulf Coast industrial corridors, forcing data centers to absorb liquid hydrogen trucking costs or invest in on-site methane reforming.
- F-Gas Regulation thermal management constraints:The EU's phasedown of hydrofluorocarbon refrigerants limits coolant options for fuel cell waste heat recovery systems, complicating absorption chiller specification in European deployments.
Strategic Opportunities
- India's data center PLI scheme:Production-linked incentives for domestic manufacturing create localized supply chain advantages for fuel cell assembly serving Mumbai, Chennai, and Hyderabad hyperscale clusters.
- Modular skid standardization:Pre-engineered 250kW to 2MW fuel cell modules reduce commissioning timelines from 18 months to 6 months, opening edge computing and colocation segments previously excluded from custom installations.
- Singapore's carbon neutrality mandate:The city-state's prohibition on new diesel generators for backup power after 2025 creates exclusive market access for hydrogen fuel cells in a supply-constrained island geography.
Industry Challenges
- Electrolyzer technician scarcity:On-site hydrogen production requires specialized maintenance for PEM and alkaline electrolyzer stacks, with certified technicians concentrated in industrial hydrogen hubs and absent from most data center labor markets.
- Interconnection standardization delays:IEEE 1547 and UL 1741 certification timelines for utility-interactive fuel cells extend 14 to 22 months, compressing project returns and creating stranded asset risk before operational revenue begins.
- Reformer integration complexity:Natural gas-to-hydrogen reforming systems require custom engineering for each facility's gas pressure and sulfur content, preventing plug-and-play deployment at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell for Data Center Market |
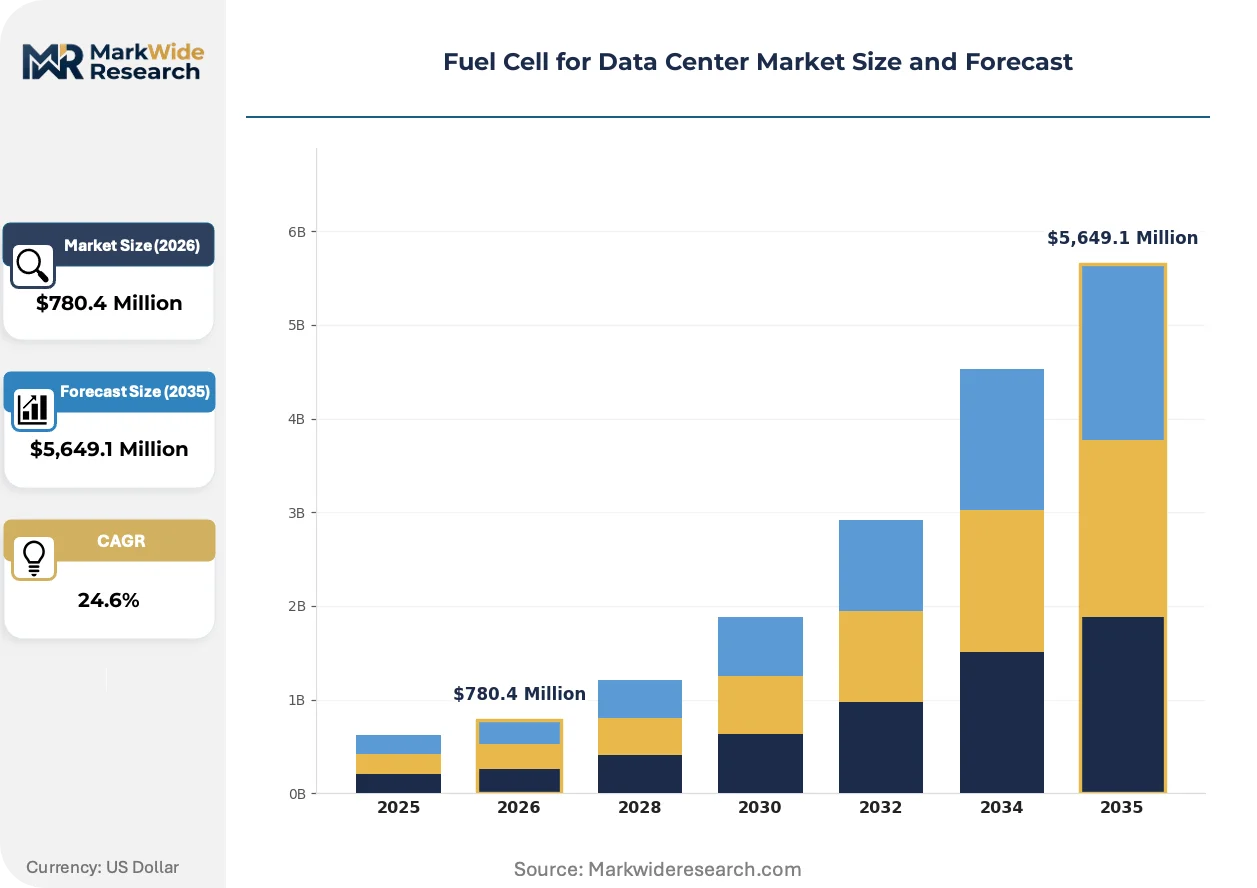
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $5,649.1 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Cell Type: Proton Exchange Membrane, Solid Oxide, Alkaline, Phosphoric Acid, Molten Carbonate Application: Backup Power, Primary Power, Remote Data Facilities, Edge Computing Hubs, High-Performance Computing End User Industry: Cloud Service Providers, Telecommunications, Financial Services, Media Servers, Government Data Centers Deployment Model: On-Premises, Colocation Facilities, Modular Data Centers, Hyperscale Data Centers |
| Companies Covered | Bloom Energy, Plug Power Inc., FuelCell Energy, Ballard Power Systems, Doosan Fuel Cell, SFC Energy AG, Panasonic Corporation, PowerCell Sweden AB, AFC Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell for Data Center Market Shifts & Advancements
Electrochemical power generation is fragmenting the data center energy stack as operators reject centralized utility dependency in favor of controllable on-site assets with predictable carbon intensity.
Solid oxide fuel cell technology is consolidating primary power architectures for hyperscale facilities. These high-temperature systems convert natural gas or biogas directly into electricity without external reforming, achieving 60 percent electrical efficiency. Amazon Web Services and Equinix are deploying multi-megawatt SOFC arrays in Virginia and California. This technology is consolidating the competitive position of vendors with mature ceramic manufacturing capabilities against PEM suppliers dependent on hydrogen logistics.
The EU F-Gas Regulation is reshaping thermal management specifications for European fuel cell deployments. The phasedown of hydrofluorocarbon refrigerants to 21 percent of baseline by 2030 forces absorption chiller manufacturers to specify natural refrigerants like ammonia or CO2 for waste heat recovery systems. German and Dutch data center operators are now requiring fuel cell suppliers to certify ammonia-based cooling integration, extending engineering cycles but locking in long-term compliance positions.
Power purchase agreement structures are fragmenting traditional procurement relationships. Hyperscale operators are unbundling fuel cell hardware from hydrogen supply contracts, signing separate 15-year power purchase agreements with project developers while retaining operational control over generation assets. This bifurcation is most visible in Northern Virginia, where Microsoft and Google have executed split-contract arrangements for fuel cell capacity without assuming hydrogen commodity price risk.
Fuel Cell for Data Center Market Segmentation
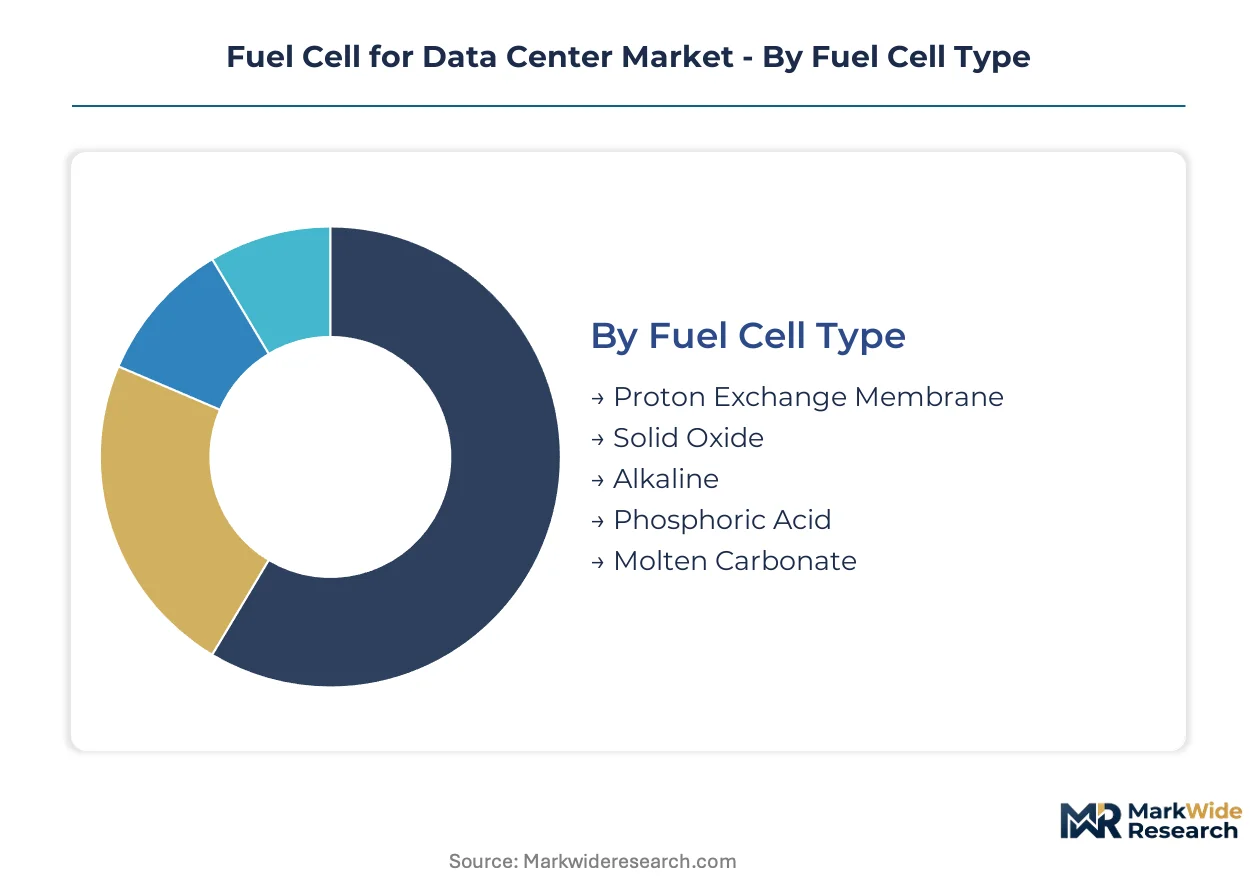
Fuel cell deployment strategies diverge sharply by operational scale and grid dependency. Segmentation reveals how technology selection, application priority, and facility architecture determine procurement economics across the data center power stack.
Fuel Cell Type:
Solid oxide systems command premium positioning through efficiency leadership, while proton exchange membrane variants dominate volume shipments for rapid-response applications.
- Solid Oxide:High-temperature ceramic electrochemical conversion achieves 60 percent electrical efficiency with direct natural gas or biogas input. AWS and Equinix deployments in Virginia and California concentrate demand where combined heat and power integration offsets thermal management costs.
- Proton Exchange Membrane:Polymer electrolyte membrane architecture enables sub-minute cold-start capability critical for backup power synchronization. Northern Virginia hyperscale operators specify PEM systems for grid-failure ride-through where diesel generator bans apply.
- Alkaline:Liquid electrolyte systems offer capital cost advantages for stationary baseload in industrial hydrogen corridors.
- Phosphoric Acid:Mature molten phosphoric acid electrolyte technology serves utility-scale distributed generation with proven 40,000-hour stack durability.
- Molten Carbonate:High-temperature carbonate salt electrolyte operates on carbonaceous fuels without external reforming, occupying megawatt-scale utility-interactive installations.
Today's leader: Solid Oxide. Tomorrow's challenger: Proton Exchange Membrane.
Application:
Primary power deployments absorb the majority of capital expenditure as operators abandon grid dependency, while backup power maintains faster deployment velocity.
- Primary Power:Continuous baseload generation displaces utility procurement through 24/7 on-site electrochemical conversion. Dominion Energy's Loudoun County substation moratorium forces cloud operators into fuel cell baseload for immediate capacity.
- Backup Power:Emergency generation provides ride-through during grid disturbances with sub-10-second response times. Singapore's prohibition on new diesel generators after 2025 creates exclusive market access for hydrogen fuel cells in island-constrained geographies.
- Remote Data Facilities:Off-grid installations in mining, defense, and research locations where transmission infrastructure is economically prohibitive.
- Edge Computing Hubs:Distributed low-latency nodes requiring sub-10MW localized generation without substation interconnection delays.
- High-Performance Computing:AI training clusters with synchronized power quality requirements and 99.999 percent uptime mandates.
Primary Power captures current investment concentration. Backup Power is climbing the fastest as regulatory diesel displacement accelerates.
End User Industry:
Cloud service providers drive specification standards through procurement scale, while financial services impose the most stringent reliability requirements.
- Cloud Service Providers:Hyperscale operators unbundle hardware from hydrogen supply through split-contract PPA structures. Microsoft and Google executed such arrangements in Northern Virginia without assuming commodity price risk.
- Telecommunications:5G edge infrastructure and submarine cable landing stations require resilient power for latency-sensitive traffic routing.
- Financial Services:Trading floors and clearing operations mandate sub-4ms failover with redundant fuel cell arrays.
- Media Servers:Content delivery networks prioritize power density for streaming infrastructure over efficiency optimization.
- Government Data Centers:Classified facilities and sovereign cloud deployments with domestic supply chain mandates and cyber-physical security requirements.
Cloud Service Providers set technology roadmaps. Government Data Centers are gaining share fastest through classified infrastructure modernization.
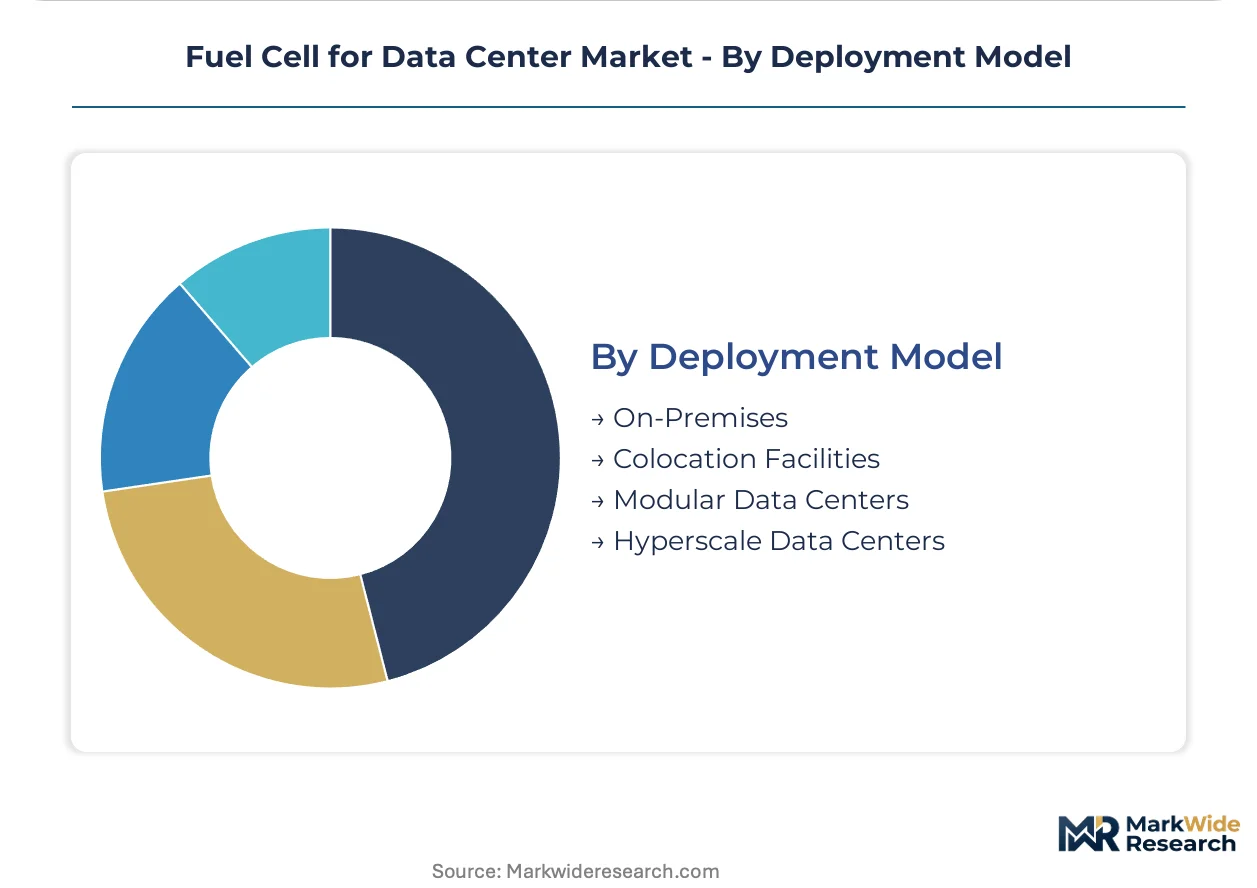
Deployment Model:
Hyperscale facilities concentrate megawatt-scale procurement, while modular architectures are expanding most quickly through standardized engineering.
- Hyperscale Data Centers:Single-tenant facilities exceeding 50MW capacity deploy multi-megawatt fuel cell arrays with dedicated electrical substations. Amazon Web Services solid oxide deployments exemplify this architecture.
- Modular Data Centers:Pre-engineered 250kW to 2MW skids reduce commissioning from 18 months to 6 months, opening edge and colocation segments previously excluded from custom installations.
- On-Premises:Enterprise-owned facilities with captive generation for mission-critical operations in financial and healthcare verticals.
- Colocation Facilities:Multi-tenant environments where fuel cells serve shared infrastructure with metered power distribution.
Hyperscale Data Centers anchor current revenue. Modular Data Centers represent the steepest expansion trajectory through deployment velocity advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's grid-constrained data center corridor commands immediate attention from fuel cell developers seeking baseload power contracts. Singapore's diesel generator ban and Germany's F-Gas Regulation are reshaping procurement patterns across three continents.
United States
Dominion Energy's Loudoun County substation moratorium and the Inflation Reduction Act's hydrogen tax credits are accelerating deployments. The EPA and FERC govern emissions standards and interstate market rules. Northern Virginia hosts the densest concentration of hyperscale fuel cell installations as AWS and Equinix bypass utility queues.
Germany
The EU F-Gas Regulation's hydrofluorocarbon phasedown and the EU Green Deal's carbon neutrality targets are forcing thermal management redesigns. ECHA oversees chemical compliance for coolant systems. Frankfurt's data center cluster faces refrigerant constraints that favor absorption chiller integration with high-temperature fuel cell systems.
Singapore
The city-state's prohibition on new diesel generators after 2025 and its carbon neutrality mandate are eliminating conventional backup options. The Energy Market Authority regulates distributed generation interconnection. Tuas and Jurong data center zones are contracting hydrogen fuel cell capacity for island-constrained resilience.
South Korea
METI's renewable portfolio standards credit fuel cell output toward clean energy mandates. The Green New Deal accelerates hydrogen economy investments. Seoul's metropolitan data center cluster and Busan's submarine cable landing stations are deploying molten carbonate systems for utility-interactive generation.
India
The Production-Linked Incentive scheme for domestic manufacturing and CEA grid codes are enabling localized supply chains. Mumbai's financial district data centers and Hyderabad's hyperscale campuses are evaluating modular fuel cell skids to bypass transmission infrastructure gaps.
Fuel Cell for Data Center Market Competitive Landscape
Global majors compete with regional champions across technology platforms and hydrogen logistics integration. The market structure consolidates around three vendor tiers: solid oxide specialists with ceramic manufacturing depth, proton exchange membrane suppliers with rapid-start capabilities, and carbonate system operators targeting utility-scale deployments. Strategic moves center on modular skid standardization and split-contract power purchase agreements that unbundle hardware from fuel supply.
Within the solid oxide tier, Bloom Energy exemplifies the on-premises deployment archetype for enterprise clients. Plug Power Inc. occupies a position emphasizing hydrogen logistics integration. FuelCell Energy anchors the megawatt-scale utility-interactive segment with carbonate platform specialization.
| Leading Market Players |
|---|
| Bloom Energy |
| Plug Power Inc. |
| FuelCell Energy |
| Ballard Power Systems |
| Doosan Fuel Cell |
| SFC Energy AG |
| Panasonic Corporation |
| PowerCell Sweden AB |
| AFC Energy |
| Others |
Supply & Pricing Matrix
Hyperscale cloud operators in Northern Virginia concentrate procurement volume, forcing contract structures that unbundle fuel cell hardware from hydrogen supply through split-contract power purchase agreements. This buyer concentration shifts pricing power toward volume-scaled deployments while penalizing small-lot custom engineering.
Pricing Analysis
Input-cost pass-through from platinum group metals and ceramic electrolyte materials dominates fuel cell pricing structures, with iridium and platinum catalyst volatility feeding directly into proton exchange membrane system quotes. Three-tier pricing structure across premium solid oxide, standard molten carbonate, and economy alkaline systems differentiates by electrical efficiency and fuel flexibility grades. Cost compression in PEM stacks is intensifying because South African and Russian mining concentration amplifies supply risk premiums. Colocation operators exhibit highest price sensitivity due to thin margins and shared infrastructure economics, while government data centers accept premium tiers for domestic supply chain mandates.
Supply Chain Analysis
Certification gating through IEEE 1547 and UL 1741 utility-interactive standards constrains vendor qualification, extending lead times for new market entrants. Ceramic electrolyte manufacturing concentrates in the United States, Japan, and South Korea, while platinum group metal refining feeds from South African and Russian operations. The supply chain draws from iridium catalysts, yttria-stabilized zirconia ceramics, and high-purity hydrogen or natural gas feedstocks. Single-source vulnerability in PGM mining operations amplifies price volatility exposure. Distribution runs through project developers and engineering-procurement-construction contractors for hyperscale deployments, with modular skid manufacturers serving edge computing direct.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuel cell deployment for data centers represents a stable compounder anchored by grid interconnection queues exceeding five years in critical clusters, ensuring sustained demand for on-site generation alternatives.
For Market Incumbents: Acquire electrolyzer technician training capabilities to address labor scarcity constraining on-site hydrogen production deployments. Consolidate position by securing long-term platinum group metal offtake agreements to neutralize catalyst cost volatility threatening PEM margins. Dominance by solid oxide specialists with ceramic manufacturing depth presents acquisition targets for technology portfolio expansion. For New Entrants and Emerging Players: The Inflation Reduction Act in the United States opens a window for project developers to capture hydrogen production tax credits without assuming fuel price risk. Modular skid standardization for 250kW to 2MW edge computing deployments offers the most penetrable white space, bypassing hyperscale procurement concentration. Target colocation operators in Northern Virginia and Singapore through pre-engineered systems with six-month commissioning timelines. For Investors and Strategic Acquirers: Cloud service providers are the most active acquirer in this space, unbundling hardware ownership from operational control through split-contract structures. Five-to-ten year viability rests on hydrogen supply cost curves converging with grid parity in high-demand clusters. Monitor electrolyzer technician certification pipeline expansion as the inflection signal for on-site production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Skid Standardization | Pre-engineered 250kW-2MW units cut commissioning timelines from 18 months to 6 months for edge operators. |
| Split-Contract Power Purchase Agreement | Microsoft and Google executed unbundled arrangements in Northern Virginia without hydrogen commodity price exposure. |
| Backward Integration into Ceramic Manufacturing | Solid oxide vendors securing yttria-stabilized zirconia supply neutralize Japanese and South Korean material concentration. |
| Electrolyzer Technician Certification Program | On-site hydrogen production scaling requires trained labor absent from most data center labor markets today. |
| Ammonia-Based Cooling Integration | German and Dutch operators now require F-Gas Regulation-compliant thermal management for European deployments. |
Research Methodology
Coverage spans the United States, Germany, Singapore, South Korea, and India, with primary inputs from each market informing demand calibration. The research combines structured interviews with data center facility engineers, utility interconnection planners, fuel cell procurement leads, and hydrogen supply specialists with secondary validation from FERC filings, EIA power plant databases, EPA emissions standards, and EU Green Deal implementation trackers. Bottom-up installation forecasts triangulate against top-down hyperscale capex disclosures and utility moratorium announcements.
Granularity-level modeling operates at fuel cell type, application priority, end-user industry, and deployment model dimensions, with regional regulatory framework overlays capturing IRA hydrogen credit eligibility and F-Gas Regulation thermal management constraints. CAGRs derive from installation volume trajectories across the projection horizon, with levelized cost of electricity sensitivity to hydrogen delivery infrastructure buildout and platinum group metal price scenarios. Forecast inputs include Dominion Energy substation queue timelines, Singapore diesel generator phaseout enforcement, and India's PLI scheme domestic manufacturing incentives.
Revisions become necessary when hydrogen pipeline infrastructure buildout accelerates beyond Gulf Coast corridors, altering on-site versus delivered fuel economics. Deviation in electrolyzer technician certification pipeline expansion would shift the outlook materially for primary power deployments dependent on sustained hydrogen supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuel Cell Technology
Portable Fuel Cells Market
Fuel Cell Technology
North America Fuel Cell Market
Fuel Cell Technology
Helium Recovery Systems Market
Fuel Cell Technology
Hydrogen Fuel Cells Market
Fuel Cell Technology
Microbial Fuel Cell Market
Fuel Cell Technology
Fuel Cells for Marine Vessels Market
Fuel Cell Technology
Global Planar Solid Oxide Fuel Cell Market
Fuel Cell Technology
Hydrogen Fuel Cell Drone Market
Fuel Cell Technology
Hydrogen Fueling Nozzle Market
Fuel Cell Technology
Aircraft Fuel Cell Market
Fuel Cell Technology
Asia-Pacific Direct Methanol Fuel Cell Market
Fuel Cell Technology
Germany Fuel Cell Market
Fuel Cell Technology
Fuel Vending Machines Market
Fuel Cell Technology
France Fuel Cell Market
Fuel Cell Technology
North America Fuel Cell Technology Market
Fuel Cell Technology
Fuel Cell Interconnectors Market