
 Sodium Sulfur (Nas) Battery for Energy Storage Market | 2026-2036
Sodium Sulfur (Nas) Battery for Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Sulfur (Nas) Battery for Energy Storage Market Insights
Lithium cobalt oxide is restructuring sodium sulfur battery economics as cathode material substitution gains traction in long-duration storage designs. NGK Insulators Ltd. dominates ceramic electrolyte manufacturing and anchors supply security for beta-alumina solid separators across Japanese utility installations. BASF SE leverages its materials science portfolio to compete in advanced sulfur cathode formulations. GE Energy positions its grid integration expertise to extend project development capabilities in North American utility markets.
Sodium sulfur batteries employ molten sodium anodes, sulfur cathodes, and beta-alumina ceramic electrolytes operating at elevated temperatures to achieve high energy density and cycle stability for stationary discharge applications. The technology primarily serves grid-scale energy shifting, renewable firming, and industrial backup power where discharge duration exceeds four hours. Module Systems command premium positioning due to thermal management complexity and integration engineering requirements, while Grid Storage applications lead volume uptake as utilities seek alternatives to lithium-ion procurement bottlenecks. Liquid Electrolyte configurations remain the dominant technology segment given their commercial maturity, though Solid-State variants attract R&D investment for temperature reduction pathways.
Japan's METI efficiency standards and China's GB standards for electrochemical energy storage shape product certification requirements and market access protocols for sodium sulfur deployments. The EU Green Deal and F-Gas Regulation indirectly influence chemistry selection by penalizing fluorinated cooling systems in competing lithium-ion configurations. Stakeholders must monitor ceramic electrolyte yield rates and molten salt containment reliability as determinants of total cost of ownership against emerging iron-air and vanadium flow alternatives.
Market Dynamics
Lithium supply constraints are redirecting utility procurement toward long-duration chemistries, with sodium sulfur batteries capturing grid-scale tenders previously reserved for lithium-ion systems across Asia-Pacific markets.
Growth Catalysts
- Feed-in tariff reforms:Japan's METI restructuring of renewable energy pricing mechanisms favors eight-hour-plus storage durations, creating procurement slots where NaS technology outcompetes shorter-duration alternatives.
- Dual carbon mandates:China's national carbon neutrality targets under MEE directives are accelerating provincial utility procurement of non-lithium stationary storage for renewable firming applications.
- Ceramic electrolyte yield improvements:Manufacturing process refinements in beta-alumina solid separator production are compressing unit costs and extending operational lifecycles for molten salt configurations.
Market Restraints
- Temperature maintenance burden:The 300-350°C operating range demands continuous thermal energy input, elevating parasitic load and total cost of ownership against ambient-temperature alternatives.
- Single-source ceramic supply:Beta-alumina electrolyte manufacturing concentrates in Japanese specialized ceramics producers, creating geopolitical exposure for non-domestic project developers.
- Vanadium flow competition:Decoupled power-energy scaling in aqueous flow batteries is capturing utility tenders requiring 10+ hour discharge durations with lower fire risk profiles.
Strategic Opportunities
- Industrial microgrid expansion:Chemical processing and semiconductor fabrication facilities in South Korea are deploying NaS systems for islanded reliability where power quality requirements exceed lithium-ion capabilities.
- Iron-air chemistry convergence:Hybrid system architectures combining sodium sulfur rapid response with iron-air multi-day storage are emerging in pilot configurations for seasonal shifting applications.
- Green hydrogen co-location:Electrolyzer facilities requiring 24/7 renewable power contracts are specifying NaS buffers to manage intermittency without diesel backup.
Industry Challenges
- Molten salt containment engineering:Seal integrity over 15-year operational lifecycles requires specialized metallurgy expertise that remains scarce outside established Japanese installation teams.
- GB standard certification timelines:China's electrochemical storage safety protocols impose extended testing periods for imported beta-alumina modules, delaying project commissioning.
- Legacy SCADA integration:Utility control systems designed around lithium-ion voltage profiles demand custom interface development for NaS electrochemical characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Sulfur (Nas) Battery for Energy Storage Market |
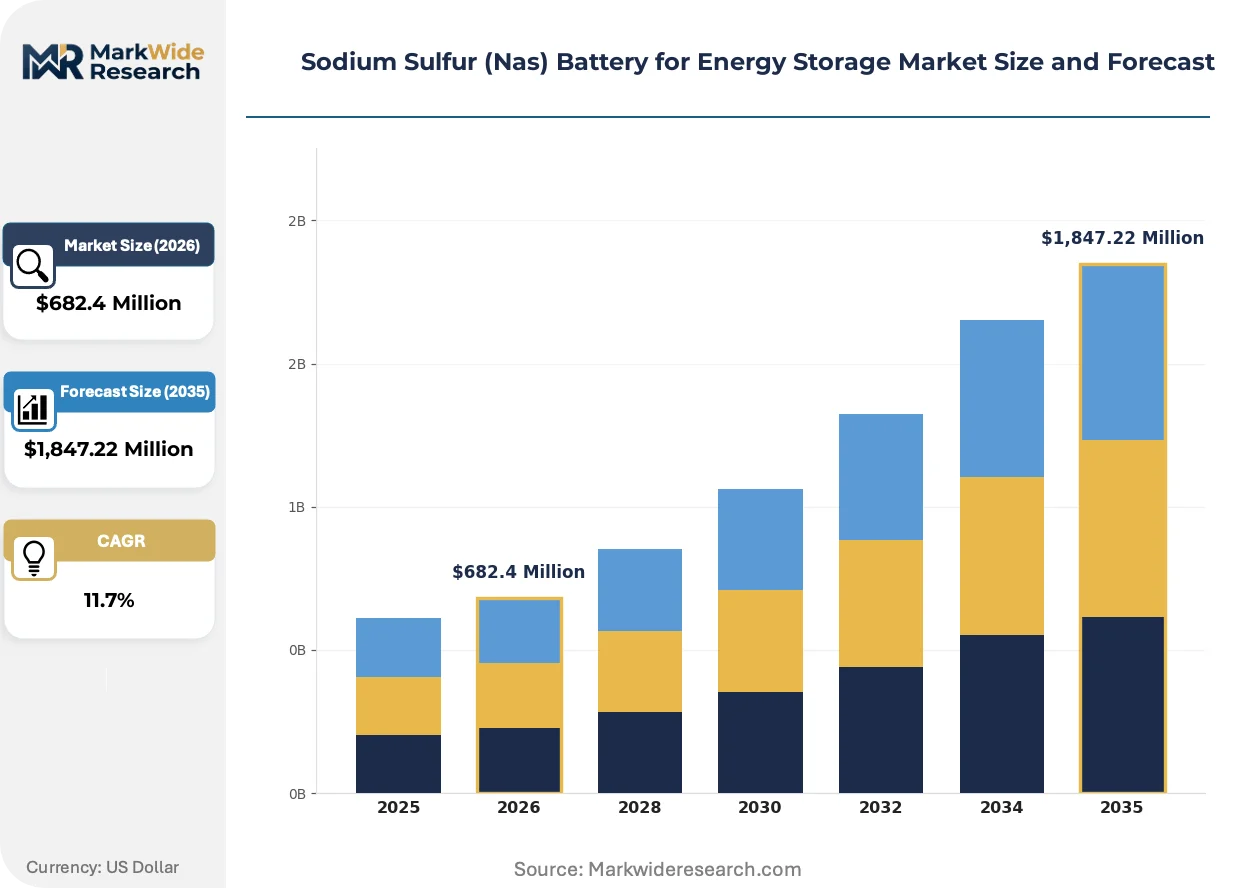
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,847.22 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Module Systems, Energy Storage Systems Application: Grid Storage, Renewable Energy Integration, Backup Power, Industrial Applications End User: Utilities, Commercial, Industrial, Residential Technology: Liquid Electrolyte, Solid-State, Hybrid Systems, Reversible Batteries |
| Companies Covered | NGK Insulators Ltd., GE Energy, BASF SE, Tokyo Electric Power Company Holdings, Eagle Picher Technologies, FIAMM Group, HiNa Battery Technology Co., KEMET Electronics Corporation, Ceramatec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Sulfur (Nas) Battery for Energy Storage Market Trends and Innovations
Solid-state electrolyte architectures and modular thermal management systems are compressing the operational envelope of molten sodium technologies, while procurement criteria across Asian utilities increasingly prioritize duration-specific chemistry selection over brand recognition.
Solid-state beta-alumina electrolyte configurations are overtaking liquid electrolyte legacy designs in next-generation utility tenders. Korean power generators specify solid-state variants for coastal installations where thermal cycling resilience outweighs first-cost considerations. The technology is overtaking conventional molten salt systems in procurement evaluations where 20-year asset life assumptions dominate net present value calculations.
China's GB/T 36276 electrochemical energy storage safety standards are mandating enhanced thermal runaway containment protocols that favor ceramic-separator chemistries. The regulation compresses lithium-ion deployment options in densely populated grid zones while creating certification pathways for sodium sulfur systems with inherent fire suppression characteristics. Japanese and South Korean developers are aligning product roadmaps to GB standard testing regimes to maintain market access.
Duration-based procurement auctions are fragmenting the stationary storage supply base by discharge hour requirements. Chinese provincial grid operators now separate 4-hour, 8-hour, and 12-hour tender categories, with NaS systems capturing the upper duration bands where lithium-ion economics degrade. The shift is most visible in Shandong and Jiangsu provinces where renewable curtailment penalties have steepened the value of multi-shift storage assets.
Sodium Sulfur (Nas) Battery for Energy Storage Market Segmentation
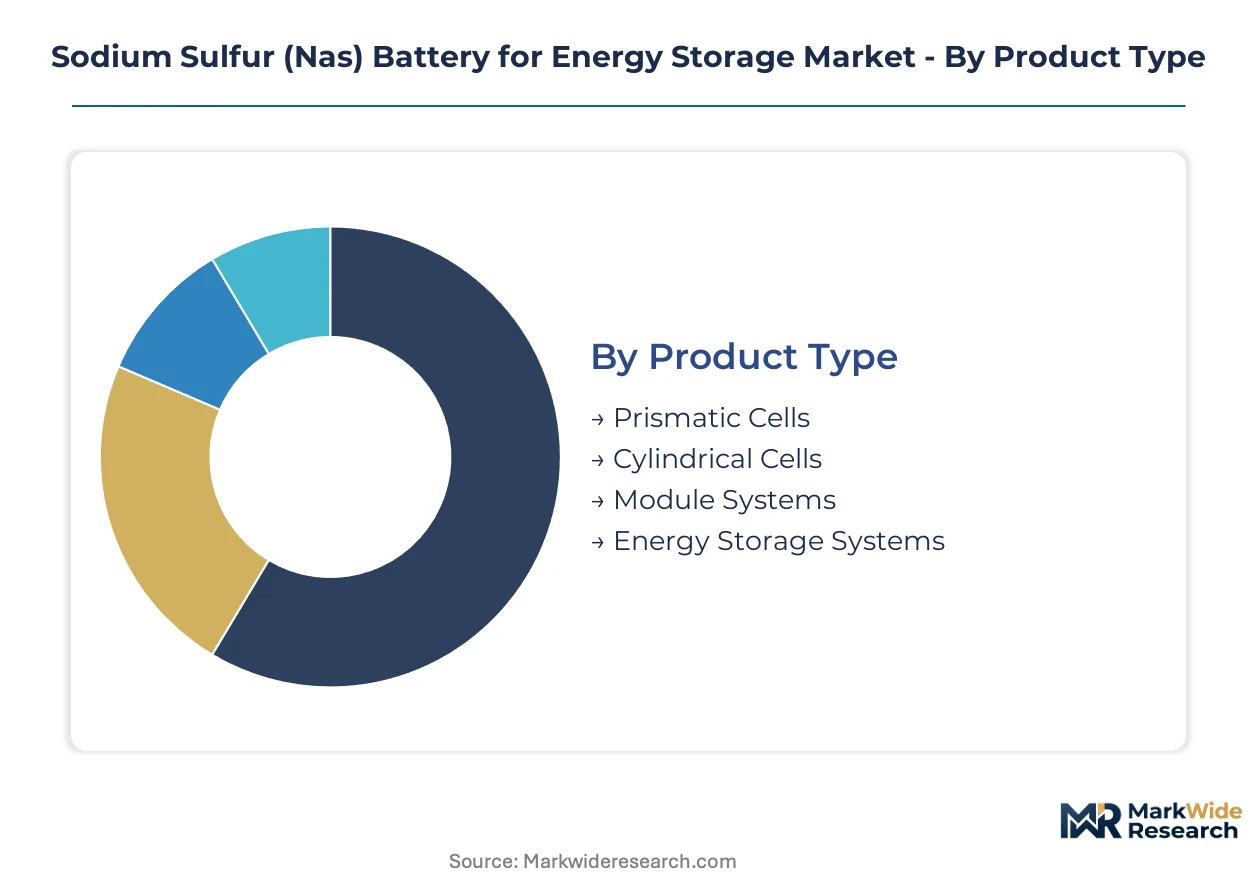
Sodium sulfur battery market dynamics vary sharply across deployment configurations and operational requirements. Product architecture and thermal management specifications determine suitability for grid-scale versus distributed applications, while end-user procurement criteria increasingly prioritize discharge duration over energy density metrics.
Product Type:
Supply concentration in beta-alumina ceramic manufacturing favors integrated system providers over component specialists in current procurement cycles.
- Prismatic Cells:Rectangular cell geometry enables dense packing configurations for containerized utility installations. Demand concentrates in Japanese utility tenders where space constraints at urban substations favor volumetric efficiency over cylindrical alternatives.
- Cylindrical Cells:Tubular beta-alumina electrolyte geometry dominates legacy manufacturing infrastructure. South Korean industrial microgrids specify cylindrical formats for thermal cycling resilience in coastal humidity environments.
- Module Systems:Pre-integrated thermal management and power conditioning units command premium positioning in procurement evaluations.
- Energy Storage Systems:Turnkey containerized solutions with auxiliary heating systems serve Chinese provincial grid operators seeking rapid deployment timelines.
Today's leader: Module Systems. Tomorrow's challenger: Energy Storage Systems.
Application:
Cost tier differentiation separates multi-hour duration applications from shorter-cycle alternatives in utility procurement frameworks.
- Grid Storage:Bulk energy shifting and frequency regulation services dominate deployment volumes across Asia-Pacific transmission networks. China's Shandong and Jiangsu provincial operators specify NaS systems for 8-hour discharge tenders where lithium-ion degradation economics fail.
- Renewable Energy Integration:Solar and wind firming applications require cycling resilience beyond lithium-ion operational envelopes. Japanese FIT reform structures create procurement slots for NaS buffers managing photovoltaic output variability.
- Backup Power:Critical load protection for semiconductor fabrication and chemical processing facilities drives South Korean industrial uptake.
- Industrial Applications:Islanded reliability configurations serve manufacturing complexes requiring power quality beyond grid standards.
Grid Storage commands current deployment volumes. Renewable Energy Integration exhibits the steepest expansion trajectory as curtailment penalties intensify.
End User:
Customer type determines procurement scale and contract structure across diverging operational requirements.
- Utilities:Transmission and distribution operators anchor procurement volumes through centralized tender mechanisms. China's State Grid and Southern Power Grid specify NaS systems for renewable firming mandates under MEE dual carbon directives.
- Commercial:Data center and logistics facility operators seek backup alternatives to diesel generation for ESG compliance.
- Industrial:Chemical processing and semiconductor fabrication facilities in South Korea deploy islanded configurations where power quality requirements exceed lithium-ion capabilities.
- Residential:Single-building deployments remain negligible due to thermal management complexity and footprint constraints.
Utilities dominate procurement volumes. Industrial end users are gaining share fastest as manufacturing reshoring intensifies reliability requirements.
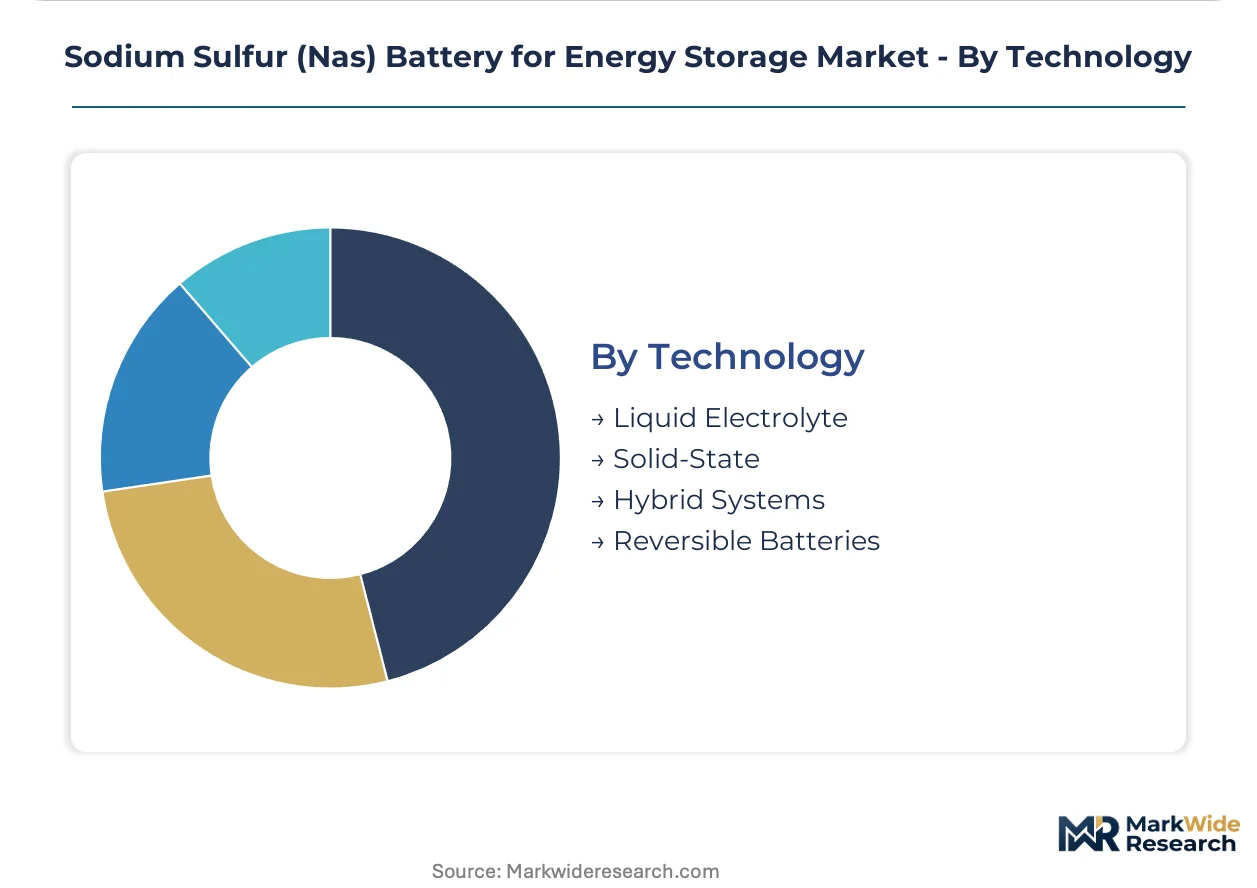
Technology:
Technology maturity curves separate commercially proven configurations from developmental architectures in procurement risk assessments.
- Liquid Electrolyte:Molten sodium-sulfur chemistry with beta-alumina solid separators represents the commercial baseline. Japanese utility installations rely on liquid electrolyte designs with 15-year operational track records for cycle stability verification.
- Solid-State:Advanced beta-alumina architectures with reduced operating temperature targets attract R&D investment for parasitic load reduction. Korean coastal installations specify solid-state variants where thermal cycling resilience outweighs first-cost premiums.
- Hybrid Systems:Combined sodium sulfur and lithium-ion configurations optimize response speed with duration economics.
- Reversible Batteries:Bidirectional power-to-gas integration concepts remain pre-commercial for seasonal storage applications.
Liquid Electrolyte retains procurement dominance. Solid-State represents the primary technology challenger as ceramic yield improvements compress cost premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's beta-alumina manufacturing clusters anchor global sodium sulfur battery production capacity, with ceramic electrolyte supply chains concentrating in Nagoya and Yokkaichi industrial zones. Utility procurement across Asia-Pacific markets is redirecting investment flows as lithium supply constraints intensify. Regulatory frameworks in China, Japan, and South Korea are reshaping certification requirements for long-duration storage deployments.
China
Provincial grid operators in Shandong and Jiangsu are tendering eight-hour-plus storage capacity under MEE dual carbon directives. GB/T 36276 electrochemical safety standards mandate enhanced thermal containment protocols that favor ceramic-separator chemistries over lithium-ion alternatives. State Grid Corporation specifications for renewable firming are accelerating beta-alumina module imports from Japanese suppliers.
Japan
METI feed-in tariff reforms are restructuring procurement slots to favor discharge durations exceeding eight hours. JIS standards for stationary storage systems shape product certification timelines for domestic and imported beta-alumina configurations. Yokkaichi ceramic manufacturing complexes supply solid electrolyte separators to utility-scale installations across the Kansai and Chubu regions.
South Korea
Industrial microgrids serving semiconductor fabrication facilities in the Seoul Capital Area are specifying sodium sulfur systems for islanded reliability. Korea Electric Power Corporation procurement frameworks prioritize thermal cycling resilience in coastal humidity environments. Busan-Ulsan manufacturing corridors are emerging as deployment hubs for chemical processing backup power applications.
United States
FERC Order 2222 implementation is enabling distributed energy resource aggregation for wholesale market participation. IRA production tax credits are shifting project economics toward domestically manufactured storage components. California Independent System Operator capacity markets are creating procurement pathways for long-duration alternatives to lithium-ion procurement bottlenecks.
Germany
EU Green Deal carbon neutrality targets are accelerating utility procurement of non-lithium stationary storage for renewable integration. F-Gas Regulation penalties on fluorinated cooling systems are disadvantaging competing lithium-ion configurations in densely populated grid zones. North Rhine-Westphalia industrial clusters are piloting sodium sulfur buffers for chemical processing reliability applications.
Sodium Sulfur (Nas) Battery for Energy Storage Market Competitive Landscape
Capacity expansion dominates the current landscape as established ceramic manufacturers scale beta-alumina electrolyte output to meet utility tender volumes. The vendor base concentrates around integrated system providers with captive ceramic supply capabilities, while component specialists struggle to secure separator allocations. Two strategic archetypes define positioning: Japanese ceramic-electrolyte incumbents with fifteen-year operational track records, and diversified materials conglomerates leveraging sulfur cathode chemistry expertise. Technology licensing and geographic expansion represent the dominant competitive moves as non-Asian developers seek to localize supply chains.
Among Japanese specialists, NGK Insulators Ltd. exemplifies the ceramic-electrolyte incumbent archetype through its Nagoya-based manufacturing infrastructure. BASF SE represents the materials science conglomerate positioning, leveraging Ludwigshafen chemical processing capabilities for advanced cathode formulations. GE Energy occupies the grid integration tier, drawing on Schenectady power systems expertise for utility-scale project development. These three anchors demonstrate how competitive positioning stratifies across electrolyte manufacturing, materials chemistry, and systems integration capabilities.
| Leading Market Players |
|---|
| NGK Insulators Ltd. |
| GE Energy |
| BASF SE |
| Tokyo Electric Power Company Holdings |
| Eagle Picher Technologies |
| FIAMM Group |
| HiNa Battery Technology Co. |
| KEMET Electronics Corporation |
| Ceramatec Inc. |
| Others |
Pricing and Supply Chain Analysis
China's GB/T 36276 thermal containment mandates are forcing utility procurement toward ceramic-separator chemistries, compelling supply chains to redirect beta-alumina capacity from legacy industrial applications and compressing margins across liquid electrolyte configurations.
Pricing Analysis
Input-cost pass-through from beta-alumina ceramic manufacturing dominates module pricing structures. Three-tier pricing stratifies across premium solid-state variants, standard liquid electrolyte systems, and economy refurbished units differentiated by thermal cycling certification and residual lifecycle guarantees. Pricing pressure intensifies downward as Korean coastal installations drive volume tenders with extended warranty requirements. Industrial microgrid buyers exhibit highest price sensitivity due to capex constraints, while Chinese provincial grid operators prioritize lifecycle cost over first-cost procurement.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale procurement from State Grid Corporation and Korea Electric Power Corporation, bypassing distribution intermediaries for containerized system deliveries. Manufacturing concentrates in Japan's Nagoya-Yokkaichi ceramic corridors, South Korea's Busan-Ulsan chemical processing zones, and China's Jiangsu battery assembly hubs. Raw material dependencies center on high-purity alumina feedstock, molten sodium metallurgy, and sulfur cathode precursors. Single-source vulnerability in beta-alumina solid separator production creates geopolitical exposure for non-Japanese project developers. Distribution runs through integrated system providers with captive electrolyte manufacturing rather than component specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sodium sulfur battery market functions as a stable compounder anchored by Asia-Pacific utility procurement mandates under dual carbon directives and feed-in tariff reforms that institutionalize long-duration storage demand.
For Market Incumbents: To counter vanadium flow battery capture of 10+ hour utility tenders, deepen backward integration into beta-alumina ceramic manufacturing and secure exclusive sulfur cathode supply agreements with Korean petrochemical complexes. Prioritize GB standard certification investment to maintain Chinese market access against emerging domestic ceramic producers. For New Entrants and Emerging Players: Launch via industrial microgrid EPC partnerships targeting South Korean semiconductor fabrication facilities where power quality requirements exceed lithium-ion capabilities. White-space opportunities concentrate in California ISO capacity markets under FERC Order 2222 aggregation frameworks and German chemical processing reliability applications penalizing fluorinated cooling systems. Position around hybrid sodium sulfur-iron-air system integration for seasonal shifting pilots. For Investors and Strategic Acquirers: Asymmetric upside sits with materials science conglomerates possessing captive sulfur chemistry expertise and grid integration capabilities. Long-term viability frames around 5-10 year utility asset replacement cycles and ceramic electrolyte yield improvement trajectories. Target acquisition archetypes include specialized beta-alumina manufacturers with Nagoya-adjacent production infrastructure. Monitor ceramic separator yield rate disclosures as the primary inflection signal for cost compression viability against iron-air alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beta-Alumina Manufacturing | NGK Insulators' Nagoya ceramic corridors anchor supply security for Japanese utility installations. |
| GB Standard Certification Investment | China's electrochemical safety protocols create market access barriers for non-compliant imported modules. |
| Hybrid System Architecture Development | Combined sodium sulfur-iron-air configurations address seasonal shifting requirements in Shandong provincial tenders. |
| Industrial Microgrid EPC Partnerships | South Korean semiconductor fabrication facilities specify NaS buffers for islanded reliability beyond grid standards. |
| Coastal Installation Thermal Resilience Programs | Busan-Ulsan humidity environments drive solid-state variant specifications with premium positioning. |
Research Methodology
Coverage spans Asia-Pacific, North America, and European markets, with primary inputs from each region's utility planning officers, EPC contractors, ceramic manufacturing technical directors, and grid operator procurement leads. Secondary validation draws from METI regulatory filings, FERC Order 2222 implementation records, GB standard certification databases, and IEA stationary storage deployment trackers. Bottom-up project pipeline analysis triangulates against top-down utility capex forecasts.
Rate-of-change decomposition separates volume growth from pricing trajectory across the projection horizon. Segmentation dimensions modeled include product architecture, discharge duration tier, end-user procurement scale, and regional regulatory framework. CAGRs derive from utility tender volume extrapolation, ceramic electrolyte yield improvement curves, and molten salt containment lifecycle cost amortization schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ceramic supply disruption scenarios and vanadium flow battery cost breakthrough conditions. Projections reflect assumptions regarding GB standard certification timelines, feed-in tariff duration structures, and beta-alumina manufacturing scale-up feasibility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Compressed Air Energy Storage (CAES) Market
Energy Storage
Supercapacitor Market
Energy Storage
Double Layer Super-Capacitor Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
Energy Storage Software Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Residential Solar Energy Storage Market
Energy Storage
Solar Storage System Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Water Electrolysis Machine Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Lead Acid Battery for Energy Storage Market