
 Global Corrosion Resistant Alloys Market | 2026-2036
Global Corrosion Resistant Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corrosion Resistant Alloys Market Intelligence
Multi-source procurement for high-performance nickel alloys is hardening across oilfield equipment supply chains. Sandvik AB leverages its precision tube manufacturing network to sustain European aerospace demand. Special Metals Corporation anchors North American supply through its integrated melting and forging operations. Thyssenkrupp AG competes on scale in stainless steel clad plate for chemical processing vessels.
Corrosion resistant alloys are metallic materials engineered with chromium, nickel, molybdenum, or titanium additions exceeding standard grades, manufactured through vacuum induction melting and electroslag remelting to achieve uniform chemistry and minimal inclusions for service in chloride-bearing, acidic, or high-temperature environments. Stainless steel dominates volume across water treatment and food processing infrastructure where cost sensitivity limits exotic material uptake. Nickel alloys command premium positioning in oilfield equipment and chemical processing applications requiring resistance to hydrogen sulfide stress cracking and sulfuric acid attack. Titanium alloys occupy the fastest-growing tier in marine equipment desalination systems where weight reduction and seawater immunity justify higher unit economics.
EPA emissions standards and OSHA process safety mandates in the US tighten alloy specification requirements for refinery and petrochemical construction. REACH substance restrictions and the EU F-Gas Regulation in Europe drive substitution toward low-cobalt and fluorine-free corrosion protection systems. NORSOK M-001 and ISO 15156 material qualification standards govern North Sea and international oilfield alloy selection. Stakeholders must monitor regulatory divergence between jurisdictions to avoid certification gaps that fragment procurement strategies.
Market Dynamics
Sour gas field development in the US Gulf Coast and North Sea is hardening demand for hydrogen sulfide-resistant nickel alloys, while REACH and EPA emissions mandates are fragmenting material certification pathways across jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases is forcing chemical processors toward corrosion-resistant alloy heat exchangers as alternatives to refrigeration-dependent systems.
- Offshore oilfield expansion:Deepwater projects in Brazil's pre-salt basins and West African fields are specifying nickel-based alloys for riser and manifold applications.
- Desalination infrastructure buildout:Titanium alloy uptake is accelerating in Saudi Arabia and UAE reverse osmosis plants where seawater corrosion immunity reduces maintenance cycles.
Market Restraints
- Nickel price volatility:London Metal Exchange nickel contract swings distort long-term alloy procurement contracts and compress fabricator margins.
- Supply concentration:Vacuum induction melting capacity clusters in Western Europe and Japan, creating single-source vulnerability for critical aerospace grades.
- Technical substitution:Fiber-reinforced polymer composites are displacing titanium in select marine structural applications where weight reduction outweighs metallic fatigue resistance.
Strategic Opportunities
- India's petrochemical corridor:Dahej and Hazira industrial zones lack localized high-performance alloy supply, creating import substitution potential for certified producers.
- Hydrogen economy infrastructure:Electrolyzer stack manufacturers require nickel alloys resistant to high-purity hydrogen embrittlement at elevated pressures.
- Carbon border adjustment mechanism:EU CBAM implementation favors low-carbon-intensity alloy production routes, advantaging scrap-based electric arc melting operations.
Industry Challenges
- ESR operator scarcity:Qualified electroslag remelting technicians are concentrated among retiring workforces in Germany and Japan.
- NORSOK M-001 qualification timelines:North Sea project alloy certification cycles extend 18-24 months, compressing project execution windows.
- Legacy system integration:Digital twin adoption in chemical processing requires retrofitting corrosion monitoring onto existing alloy vessel installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corrosion Resistant Alloys Market |
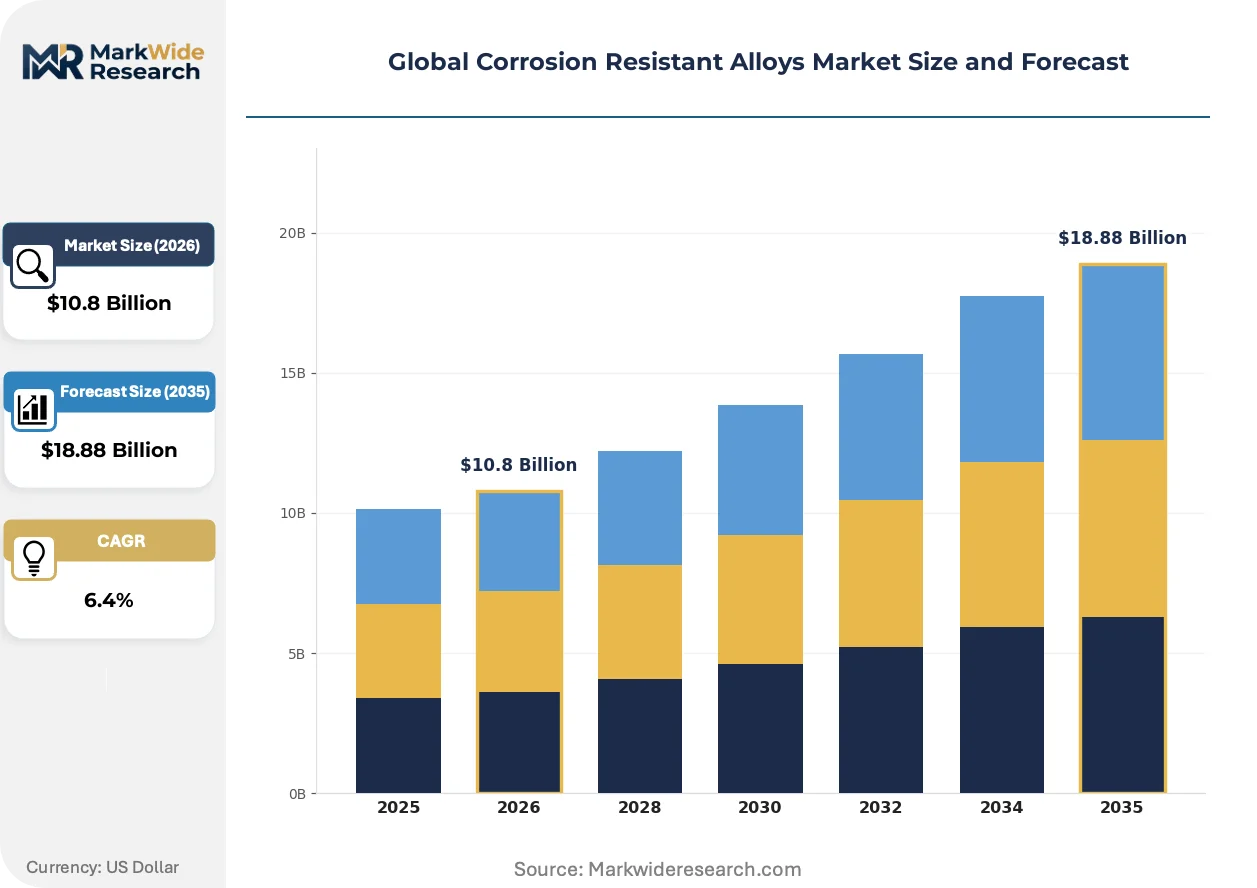
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Nickel Alloys, Titanium Alloys, Copper Alloys, Aluminum Alloys Application: Chemical Processing, Marine Equipment, Oilfield Equipment, Power Generation, Water Treatment Technology: Cladding, Thermal Spray, Electroplating, Anodizing, Laser Surface Treatment End User Industry: Petrochemical Plants, Pulp & Paper, Aerospace Manufacturing, Food & Beverage Processing, Electronics Fabrication |
| Companies Covered | Nippon Steel Corporation, Outokumpu Oyj, Carpenter Technology Corporation, Thyssenkrupp AG, Special Metals Corporation, Haynes International Inc., Sandvik AB, ArcelorMittal, Allegheny Technologies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corrosion Resistant Alloys Market Strategic Shifts & Innovations
Additive manufacturing of complex nickel alloy geometries is collapsing lead times for oilfield components. Regulatory divergence between EPA and REACH frameworks is fragmenting material specifications. Procurement centralization among supermajors is compressing supplier bases.
Directed energy deposition of Inconel 625 is consolidating repair and replacement markets for offshore riser components. Oilfield equipment fabricators in Houston and Aberdeen are adopting wire-arc additive systems to bypass forging lead times. This capability is compressing the competitive advantage of traditional integrated melting-forging operations.
EPA's tightened refinery emissions standards under the Clean Air Act are mandating upgraded alloy specifications for fluid catalytic cracking units. US Gulf Coast petrochemical operators must specify higher chromium-nickel grades to withstand elevated chlorine and sulfur exposure. Fabricators are stockpiling certified plate inventory ahead of enforcement deadlines.
Supermajor procurement departments are consolidating supplier panels from twelve to four qualified sources per alloy grade. This concentration is displacing regional distributors in favor of mill-direct relationships with volume commitments. The shift is most visible in Norwegian North Sea projects where Equinor and Aker BP have harmonized approved manufacturer lists.
Global Corrosion Resistant Alloys Market Segmentation
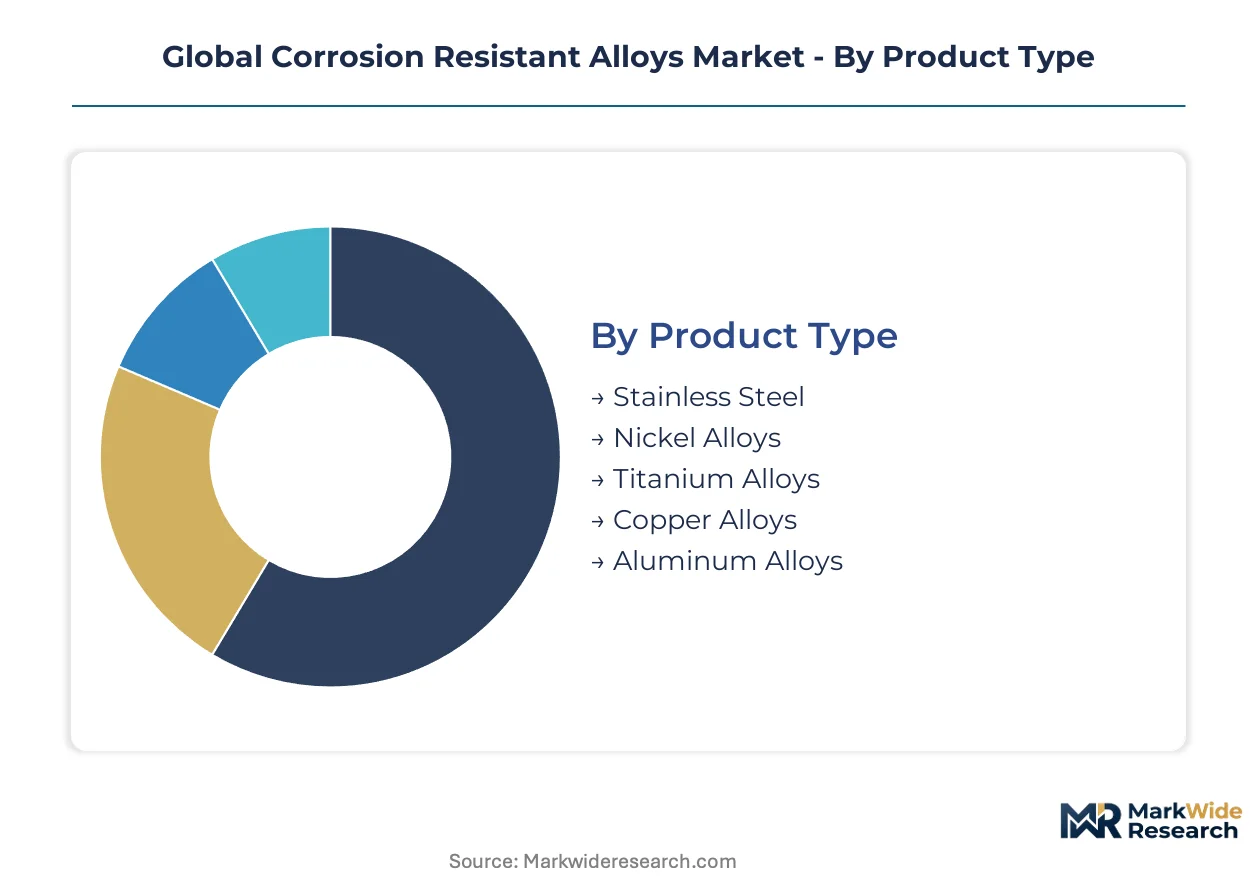
Corrosion resistant alloys serve radically different performance requirements across sour gas fields, desalination plants, and chemical processing vessels. Procurement specifications diverge sharply by application severity, driving distinct metallurgical strategies and supplier relationships.
Product Type:
Cost tolerance and corrosion severity separate buyers into distinct metallurgical tiers, from commodity stainless to exotic titanium systems.
- Stainless Steel:Chromium-nickel-iron alloys with 10.5% minimum chromium content provide baseline corrosion resistance for chloride-bearing environments. Water treatment infrastructure in Saudi Arabia and food processing equipment across Germany specify 316L and duplex grades where cost sensitivity constrains exotic material uptake.
- Nickel Alloys:Vacuum-melted grades such as Inconel 625 and Hastelloy C-276 resist hydrogen sulfide stress cracking in sour service. Deepwater riser procurement from Houston to Aberdeen concentrates demand for these alloys as NORSOK M-001 qualification requirements harden.
- Titanium Alloys:Seawater-immune Ti-6Al-4V dominates UAE and Saudi desalination membrane housings where weight reduction and maintenance avoidance justify premium unit economics.
- Copper Alloys:Naval brass and cupronickel serve heat exchanger tubing in marine condensers and power plant cooling systems.
- Aluminum Alloys:Anodized 5xxx and 6xxx series provide atmospheric corrosion protection for architectural and transportation applications.
Stainless steel leads volumes today; titanium alloys are gaining share fastest.
Application:
Environmental severity and regulatory exposure dictate alloy grade selection across end-use environments.
- Chemical Processing:Sulfuric acid and chlorine dioxide exposure in US Gulf Coast petrochemical corridors drives specification of high-molybdenum nickel alloys. EPA refinery emissions mandates under the Clean Air Act are accelerating upgrades to chromium-nickel grades for fluid catalytic cracking units.
- Oilfield Equipment:Hydrogen sulfide partial pressures above 0.05 psi in Brazil's pre-salt basins mandate Inconel 625 for riser and manifold components. NORSOK M-001 and ISO 15156 qualification cycles extend procurement timelines to 18-24 months.
- Marine Equipment:Seawater corrosion immunity requirements in desalination and offshore platform applications concentrate titanium demand in the Middle East and Southeast Asia.
- Power Generation:Flue gas desulfurization systems and nuclear steam generator tubing specify nickel alloys for high-temperature oxidation resistance.
- Water Treatment:Chlorination-resistant duplex stainless serves municipal infrastructure where cost constraints limit exotic alloy adoption.
Chemical processing anchors current demand; oilfield equipment is climbing the fastest.
Technology:
Surface modification intensity and substrate compatibility determine technology selection for cost-sensitive versus performance-critical applications.
- Cladding:Explosive bonding and roll-bonding of nickel alloy layers onto carbon steel substrates reduce material costs for large chemical vessel fabrication. Thyssenkrupp AG competes on scale in clad plate supply for European process industries.
- Thermal Spray:High-velocity oxy-fuel deposition of Inconel and Hastelloy powders repairs worn components and extends service life in abrasive-corrosive environments.
- Electroplating:Nickel and chromium electrodeposition provides thin-film protection for electronics and decorative applications with minimal substrate cost impact.
- Anodizing:Electrochemical oxide growth on aluminum creates wear-resistant, dielectric surfaces for aerospace and consumer electronics.
- Laser Surface Treatment:Directed energy deposition and laser cladding enable complex geometry repair and additive manufacturing of nickel alloy components for oilfield equipment.
Cladding dominates tonnage today; laser surface treatment is expanding most quickly.
End User Industry:
Regulatory stringency and process safety exposure separate buyers into certification-intensive versus commodity procurement patterns.
- Petrochemical Plants:Fluid catalytic cracking units and hydroprocessing reactors in the US Gulf Coast and Rotterdam-Antwerp corridor specify NORSOK-qualified nickel alloys. REACH and EPA emissions mandates are fragmenting material certification pathways.
- Aerospace Manufacturing:Vacuum induction melted and electroslag remelted superalloys for turbine engines require aerospace-grade certification from Western European and Japanese melting capacity.
- Pulp & Paper:Chlorine dioxide bleaching equipment and digesters specify duplex stainless and titanium for aggressive chemical exposure.
- Food & Beverage Processing:304 and 316L stainless grades dominate dairy and brewing equipment where FDA and EFSA hygiene standards govern surface finish requirements.
- Electronics Fabrication:High-purity copper and nickel plating serve semiconductor manufacturing and printed circuit board production.
Petrochemical plants lead alloy consumption today; aerospace manufacturing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with lower compliance costs as REACH and EPA mandates fragment certification pathways. Vacuum induction melting capacity concentrates in Germany and Japan, creating arbitrage opportunities for Indian and Middle Eastern fabricators sourcing certified feedstock.
United States
Deepwater projects in the Gulf of Mexico and pre-salt basin developments drive procurement of hydrogen sulfide-resistant nickel alloys. EPA refinery emissions standards under the Clean Air Act mandate upgraded chromium-nickel grades for fluid catalytic cracking units. Houston anchors North American demand as Equinor and Chevron consolidate approved manufacturer lists for riser components.
Germany
Electroslag remelting expertise concentrates in aging workforces across the Ruhr industrial corridor, constraining aerospace-grade superalloy output. ECHA REACH substance restrictions accelerate substitution toward low-cobalt corrosion protection systems. Thyssenkrupp AG exploits scale advantages in clad plate supply for Rotterdam-Antwerp chemical processing corridors.
Japan
Titanium alloy demand from desalination membrane manufacturers in Saudi Arabia and the UAE flows through Japanese melting operations. METI industrial standards govern vacuum induction melted grades for turbine engine applications. Nagoya and Kobe house concentrated aerospace certification capacity serving global superalloy procurement.
India
Dahej and Hazira petrochemical zones lack localized high-performance alloy supply, forcing reliance on European and Japanese mill-direct relationships. BIS certification requirements for pressure vessel materials extend procurement timelines. Gujarat's industrial corridor attracts import substitution investment as domestic fabricators seek NORSOK M-001 qualification.
Saudi Arabia
Reverse osmosis plant construction in Jubail and Yanbu drives titanium alloy uptake for seawater-immune membrane housings. SFDA and MOHAP standards for desalination infrastructure tighten material traceability requirements. The Eastern Province concentrates demand as ACWA Power and SWCC expand membrane capacity.
Global Corrosion Resistant Alloys Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing capabilities and hydrogen economy positioning. The vendor base stratifies across integrated melting-forging operations, precision tube specialists, and clad plate fabricators. Three archetypes dominate: Western European mill-direct suppliers with NORSOK qualification, Japanese titanium alloy specialists with aerospace certification, and Indian fabricators exploiting cost arbitrage on imported feedstock. Competitive moves concentrate on mill-direct procurement consolidation and wire-arc additive manufacturing adoption.
Among integrated European producers, Thyssenkrupp AG and Outokumpu Oyj exemplify scale-driven positioning in stainless and clad plate supply. Sandvik AB anchors the precision manufacturing tier with tube and wire capabilities. Special Metals Corporation represents North American vertical integration through captive melting and forging operations. These three entities occupy distinct competitive spaces without direct overlap in core product lines.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| Outokumpu Oyj |
| Carpenter Technology Corporation |
| Thyssenkrupp AG |
| Special Metals Corporation |
| Haynes International Inc. |
| Sandvik AB |
| ArcelorMittal |
| Allegheny Technologies Incorporated |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up distributors across the US Gulf Coast and Rotterdam-Antwerp corridor have consolidated regional stainless and nickel alloy inventory positions, tightening working capital discipline and compressing channel margins for smaller fabricators. This ownership concentration reinforces mill-direct procurement trends among supermajors while fragmenting price discovery for mid-tier chemical processors.
Pricing Analysis
Distributor margin compression defines channel economics as mill-direct relationships displace regional stockists. Pricing stratifies across NORSOK-qualified premium grades, standard commercial specifications, and economy-tier commodity stainless. Price differentiation centers on certification level and volume scale. Cost compression in standard grades intensifies because nickel price volatility distorts long-term contract negotiations. Municipal water treatment buyers exhibit highest price sensitivity; aerospace turbine OEMs show least.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for mill-direct and distributor-served segments. Geographic supply concentration rests in Germany, Japan, and the United States for vacuum induction melting capacity. Raw material dependencies draw from Indonesian nickel laterite, South African chromium, and Russian titanium sponge. Single-source vulnerability in electroslag remelting expertise constrains aerospace-grade output. Distribution runs through certified stockist networks for NORSOK-qualified material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in corrosion resistant alloys stems from additive manufacturing adoption collapsing lead times for complex geometries, enabling premium pricing for rapid-turn oilfield components.
For Market Incumbents: Deepen backward integration into vacuum induction melting capacity to secure feedstock against nickel price volatility. Expand NORSOK M-001 qualification portfolios to defend against wire-arc additive manufacturing entrants. Prioritize captive electroslag remelting capability before technician scarcity hardens in Germany and Japan. For New Entrants and Emerging Players: Launch via wire-arc additive manufacturing service bureaus targeting Houston and Aberdeen oilfield equipment repair markets. India's Dahej and Hazira petrochemical zones offer import substitution white space for certified nickel alloy supply. Pursue hydrogen economy electrolyzer stack partnerships as qualification pathways mature. For Investors and Strategic Acquirers: Oilfield services conglomerates represent the most active acquirer in this space, seeking additive manufacturing capabilities to bypass forging bottlenecks. Five-to-ten year viability favors producers with low-carbon electric arc melting routes advantaged under EU CBAM. Monitor hydrogen infrastructure procurement timelines as inflection signal for nickel alloy demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Wire-Arc Additive Manufacturing Adoption | Houston fabricators bypass forging lead times for Inconel 625 riser components. |
| NORSOK M-001 Qualification Expansion | Equinor and Aker BP harmonized approved manufacturer lists compress supplier panels. |
| Low-Carbon Melting Route Investment | EU CBAM implementation favors scrap-based electric arc operations in Germany. |
| Hydrogen Economy Electrolyzer Partnerships | Electrolyzer stack manufacturers require nickel alloys resistant to hydrogen embrittlement. |
| India Import Substitution Capacity | Dahej and Hazira zones lack localized high-performance alloy supply for petrochemical buildout. |
Research Approach
Bottom-up oilfield equipment and chemical processing modeling reconciled against top-down vacuum induction melting capacity tracking forms the analytical core. Primary interviews with procurement directors at supermajors, plant managers at US Gulf Coast refineries, technical directors at aerospace tier-1 suppliers, and distribution channel heads in Rotterdam and Singapore combined with secondary validation. Secondary sources include customs and trade data, NORSOK M-001 qualification registries, SEC 10-K filings from listed producers, and ECHA REACH substance restriction updates.
Input-output matrices map alloy grade demand by application severity against melting and forging capacity by geography. Segmentation dimensions modeled include product metallurgy tier, end-use industry, certification requirement level, regional regulatory cluster, and procurement channel structure. CAGRs derive from elasticity-adjusted demand projections cross-referenced against supply-side capacity constraints. Nickel price volatility scenarios and hydrogen infrastructure deployment curves inform sensitivity analysis.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained nickel price volatility or accelerated REACH substance restrictions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Nickel Alloy Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Polyphenylene Ether (PPE) Alloy Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Titanium Alloys Market
Advanced Alloys
Quenched and Tempered Steel Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Global Quartz Countertops Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Global Shape Memory Materials Market
Advanced Alloys
Iron Gallium Alloy (Galfenol) Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Tungsten Titanium Carbide Market