
 Japan Architectural Coatings Market | 2026-2036
Japan Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Architectural Coatings Market Foresight
Aftermarket service revenue from color-matching and touch-up programs is narrowing as manufacturers bundle digital tools with base product sales. Nippon Paint Holdings Co., Ltd. leverages its extensive dealer network to control last-mile distribution in prefectural markets. Kansai Paint Co., Ltd. anchors its position through deep relationships with regional construction consortia. Jotun Japan Ltd. specializes in premium marine-grade formulations repurposed for coastal architectural applications.
Japan architectural coatings comprise resin-based protective and decorative films applied to building substrates, typically formulated with acrylic, polyurethane, or epoxy binders at solids contents ranging from thirty to sixty percent by volume, designed to resist moisture, UV degradation, and salt-air corrosion in coastal environments. Interior coatings command stable replacement demand from the country's substantial existing housing stock, while exterior coatings face accelerated upgrade cycles as municipalities tighten aesthetic maintenance codes for commercial facades. Acrylic technology dominates volume production due to its balance of weatherability and application versatility, though polyurethane formulations capture premium positioning in high-performance specifications.
METI administers Japan's Industrial Standardization Act, which governs JIS-compliant coating performance benchmarks, while the Ministry of the Environment enforces VOC emission regulations that constrain solvent-based formulation availability. The Act on Promoting Green Procurement mandates public building projects specify environmentally graded materials, redirecting contractor purchasing toward certified low-emission products. Stakeholders must monitor pending revisions to building energy codes that could mandate reflective or insulating coating layers on new commercial structures.
Market Dynamics
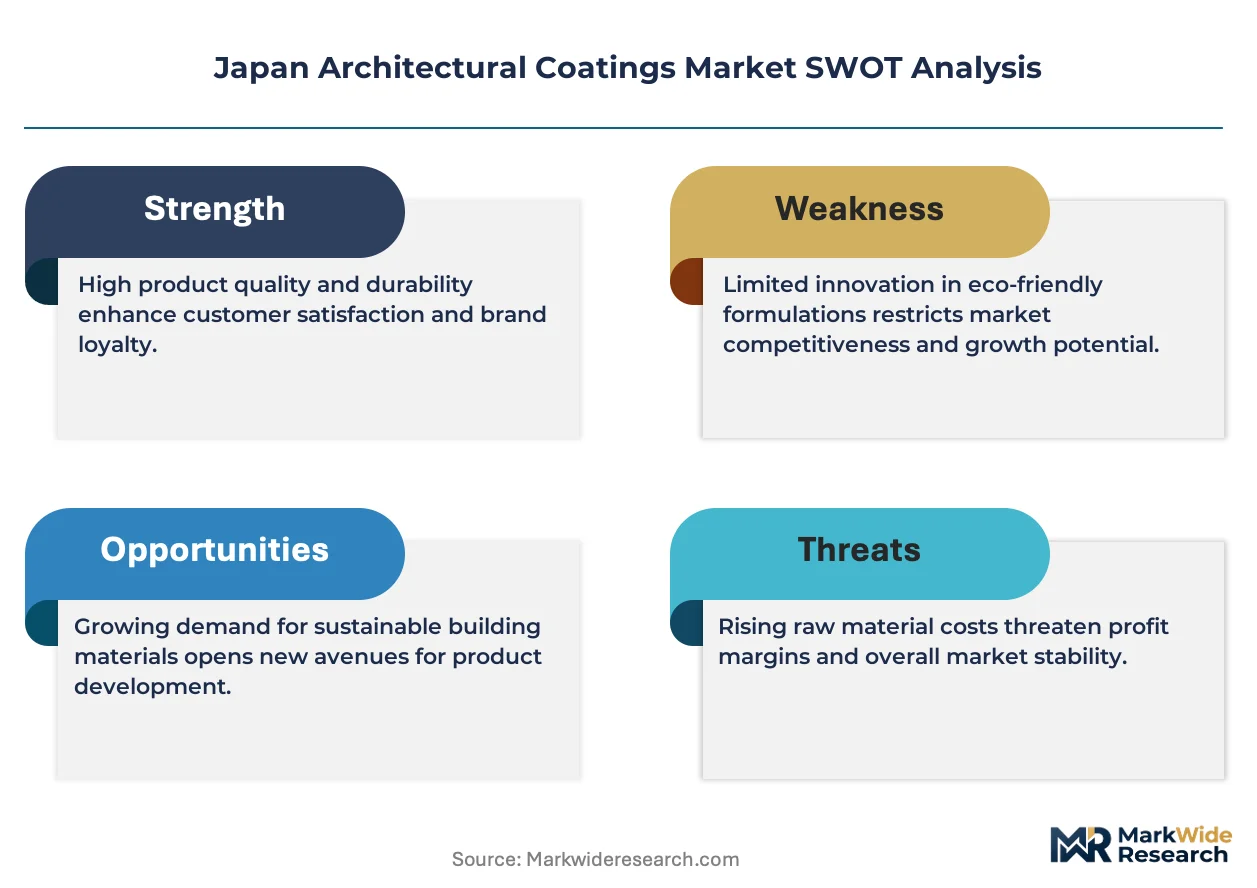
Japan's architectural coatings sector confronts a structural squeeze between METI-enforced VOC limits and the physical reality of four million aging wooden homes demanding cyclical refinishing. The collision of tightening environmental standards with accelerated replacement cycles is compressing formulation timelines and forcing raw material substitutions at scale.
Growth Catalysts
- Act on Promoting Green Procurement:Public building mandates redirect contractor purchasing toward certified low-emission products, expanding addressable market for compliant suppliers.
- Greater Tokyo Area commercial redevelopment:Olympic legacy infrastructure and ongoing urban densification sustain premium coating consumption in high-specification applications.
- Acrylic binder technology:Improved weatherability at reduced solvent loadings enables formulators to meet JIS performance benchmarks while satisfying Ministry of the Environment emission ceilings.
Market Restraints
- Titanium dioxide input volatility:Pigment cost swings compress margin stability for mid-tier producers lacking captive supply arrangements.
- Solvent-based formulation attrition:Regulatory phase-outs strand legacy production assets and force accelerated R&D amortization.
- Regional construction consortia concentration:Kansai and Chubu prefectural buying pools limit price negotiation leverage for independent distributors.
Strategic Opportunities
- Reflective coating layers:Pending METI revisions to building energy codes may mandate solar-reflective specifications on new commercial structures, opening premium specification tiers.
- Digital color-matching platforms:Touch-up program digitization enables manufacturers to capture aftermarket service revenue previously ceded to independent painters.
- Coastal corrosion protection:Salt-air degradation patterns in Kyushu and Shikoku island prefectures create demand for marine-grade formulation repurposing.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in low-VOC acrylic-urethane hybrids is concentrating at established producers, constraining new entrant capability building.
- JIS certification timelines:Extended laboratory testing protocols delay product launch windows and tie up working capital in pre-revenue inventory.
- Dealer network integration:Last-mile distribution control requires substantial IT infrastructure investment to synchronize inventory with prefectural demand patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Architectural Coatings Market |
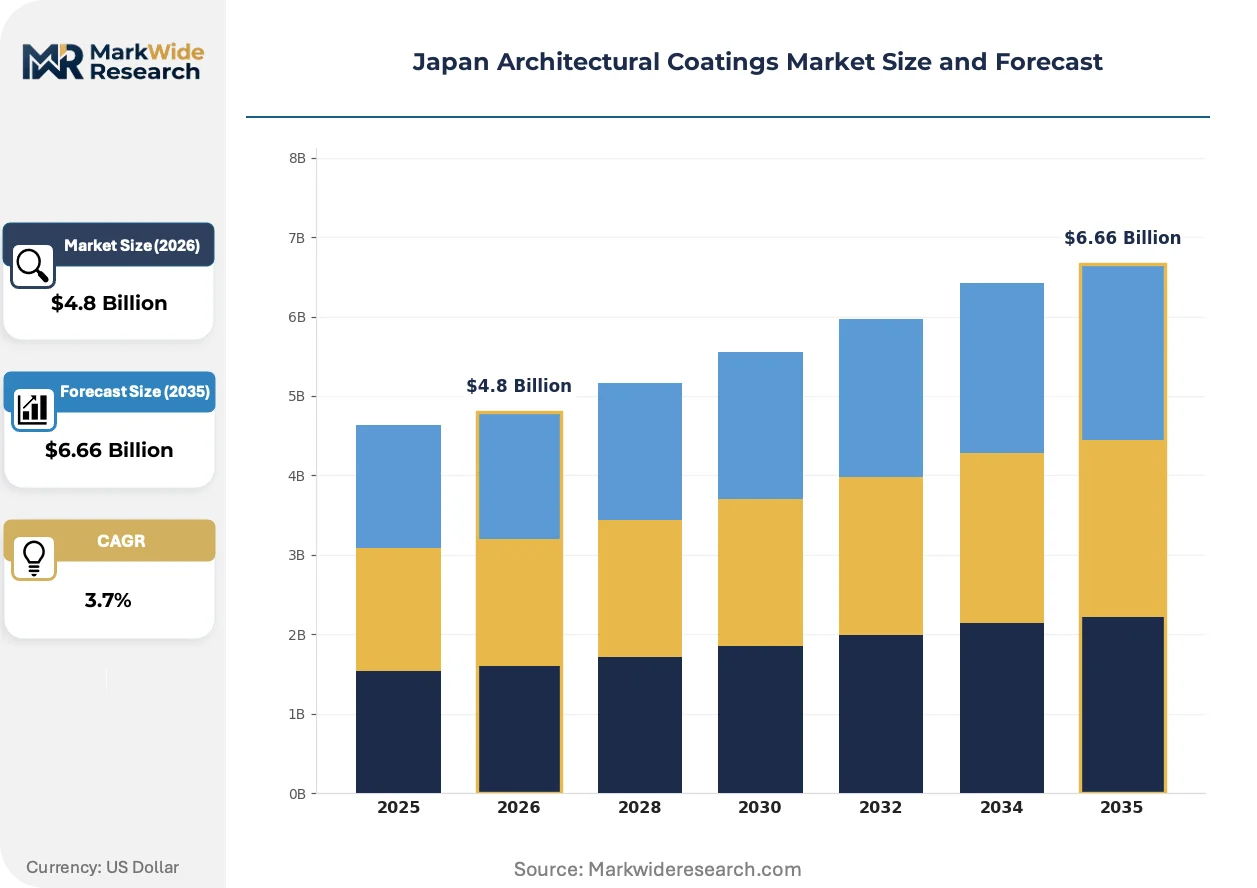
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Coatings, Exterior Coatings, Primers, Sealers Application: Residential Buildings, Commercial Buildings, Industrial Facilities, Infrastructure Projects Technology: Acrylic, Polyurethane, Polyester, Epoxy End User: Contractors, Architects, Homeowners, Property Managers |
| Companies Covered | Nippon Paint Holdings Co., Ltd., Kansai Paint Co., Ltd., Jotun Japan Ltd., Sherwin-Williams Japan, Daikin Industries, Ltd., Asahi Kasei Corporation, Toshiba Chemical Co., Ltd., Chugoku Marine Paints, Ltd., Sumitomo Chemical Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Architectural Coatings Market Shifts & Advancements
Waterborne polyurethane-acrylic hybrids are compressing the performance gap between conventional solvent systems and environmental compliance, while digital specification tools reconfigure how architects and contractors select coating systems. These shifts are redrawing competitive boundaries between formulation specialists and integrated building material suppliers.
Photocatalytic titanium dioxide surface treatments that accelerate self-cleaning through UV activation are rendering obsolete scheduled maintenance contracts for commercial facade coatings. Municipalities in Osaka and Yokohama are specifying these systems for publicly visible structures. The technology is compressing the traditional seven-to-ten-year refinishing cycle toward fifteen-year intervals, threatening aftermarket touch-up revenue pools.
METI's pending amendments to the Industrial Standardization Act will tighten JIS K 5660 performance benchmarks for exterior wall coatings, mandating accelerated weathering test protocols. Manufacturers must recertify existing product lines under compressed timelines. High-rise commercial specifications in Tokyo's 23 wards face the most immediate compliance pressure, driving preemptive formulation upgrades ahead of formal adoption.
Prefectural housing maintenance cooperatives are consolidating purchasing through centralized digital procurement platforms, displacing traditional dealer relationships in rural Tohoku and Hokkaido markets. These cooperatives negotiate volume contracts directly with manufacturers, extracting price concessions that independent distributors cannot match. The shift is most visible in Hokkaido's aging single-family housing stock, where replacement demand concentrates among price-sensitive owner-occupiers.
Japan Architectural Coatings Market Segmentation
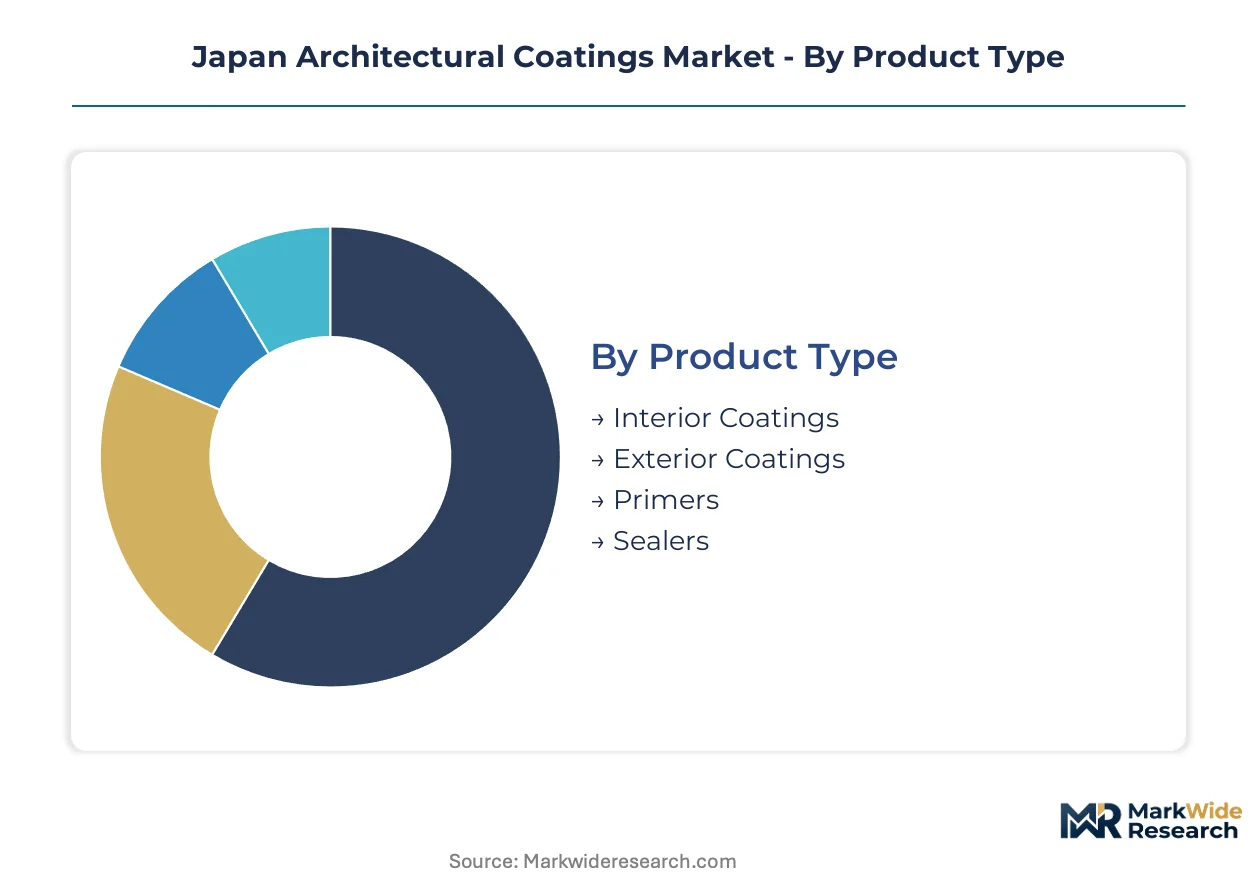
Segmentation in Japan's architectural coatings market reveals divergent replacement rhythms and specification hierarchies. Cycle times vary dramatically across product categories, with some segments demanding annual touch-ups while others sustain fifteen-year performance guarantees.
Product Type:
Exterior coatings command the longest replacement cycles due to JIS weatherability benchmarks, while interior finishes turn over fastest in high-traffic commercial environments. Cycle compression is most acute where aesthetic maintenance codes intersect with aging housing stock.
- Interior Coatings:Waterborne acrylic formulations dominate volume production for residential walls and ceilings, balancing low-VOC compliance with application ease. Demand concentrates in Tokyo's 23 wards and Osaka's central districts, where condominium renovation cycles average five to seven years. METI's green procurement mandates accelerate specification shifts toward certified low-emission systems in public housing refurbishments.
- Exterior Coatings:Elastomeric acrylic-urethane hybrids resist salt-air corrosion in coastal prefectures while meeting Ministry of the Environment emission ceilings. Greater Tokyo Area commercial redevelopment sustains premium consumption, with Olympic legacy infrastructure requiring high-specification facade protection. Photocatalytic titanium dioxide variants are compressing traditional refinishing intervals.
- Primers:Alkali-resistant acrylic sealers penetrate porous concrete substrates in Hokkaido's aging wooden housing stock.
- Sealers:Penetrating siloxane formulations protect masonry facades in Kyushu's humid subtropical climate zones.
Interior coatings dominate installed base. Exterior coatings are where expansion concentrates.
Application:
Cost tier differentiation separates specification-grade systems from commodity alternatives. Premium positioning concentrates where building codes mandate performance guarantees.
- Residential Buildings:Cyclical refinishing of Japan's four million aging wooden homes sustains steady replacement demand. Prefectural housing cooperatives in Tohoku and Hokkaido consolidate purchasing through digital platforms, extracting manufacturer-direct pricing unavailable to independent distributors.
- Commercial Buildings:High-rise specifications in Tokyo's central wards face immediate JIS K 5660 recertification pressure under pending METI amendments. Municipal aesthetic maintenance codes accelerate upgrade cycles for facade systems.
- Industrial Facilities:Epoxy-urethane hybrids protect manufacturing infrastructure in Chubu prefecture's automotive and electronics clusters.
- Infrastructure Projects:Marine-grade formulations repurposed from shipbuilding applications guard bridges and coastal installations in Shikoku island prefectures.
Residential applications anchor volume throughput. Commercial specifications are climbing the fastest.
Technology:
Technology selection tracks the tension between JIS performance benchmarks and Ministry of the Environment VOC ceilings. Binder chemistry determines compliance positioning.
- Acrylic:Dominates volume production through balanced weatherability and reduced solvent loadings that satisfy emission regulations. Formulators leverage improved resin technology to meet JIS benchmarks without legacy solvent dependence.
- Polyurethane:Captures premium positioning in high-performance commercial specifications requiring abrasion resistance and chemical tolerance. Concentrated expertise in low-VOC acrylic-urethane hybrids is concentrating at established producers.
- Polyester:Powder formulations serve industrial metal finishing in Kansai manufacturing corridors.
- Epoxy:Two-component systems anchor protective coatings for infrastructure and industrial floor applications.
Acrylic technology dominates installed base. Polyurethane hybrids are gaining share fastest.
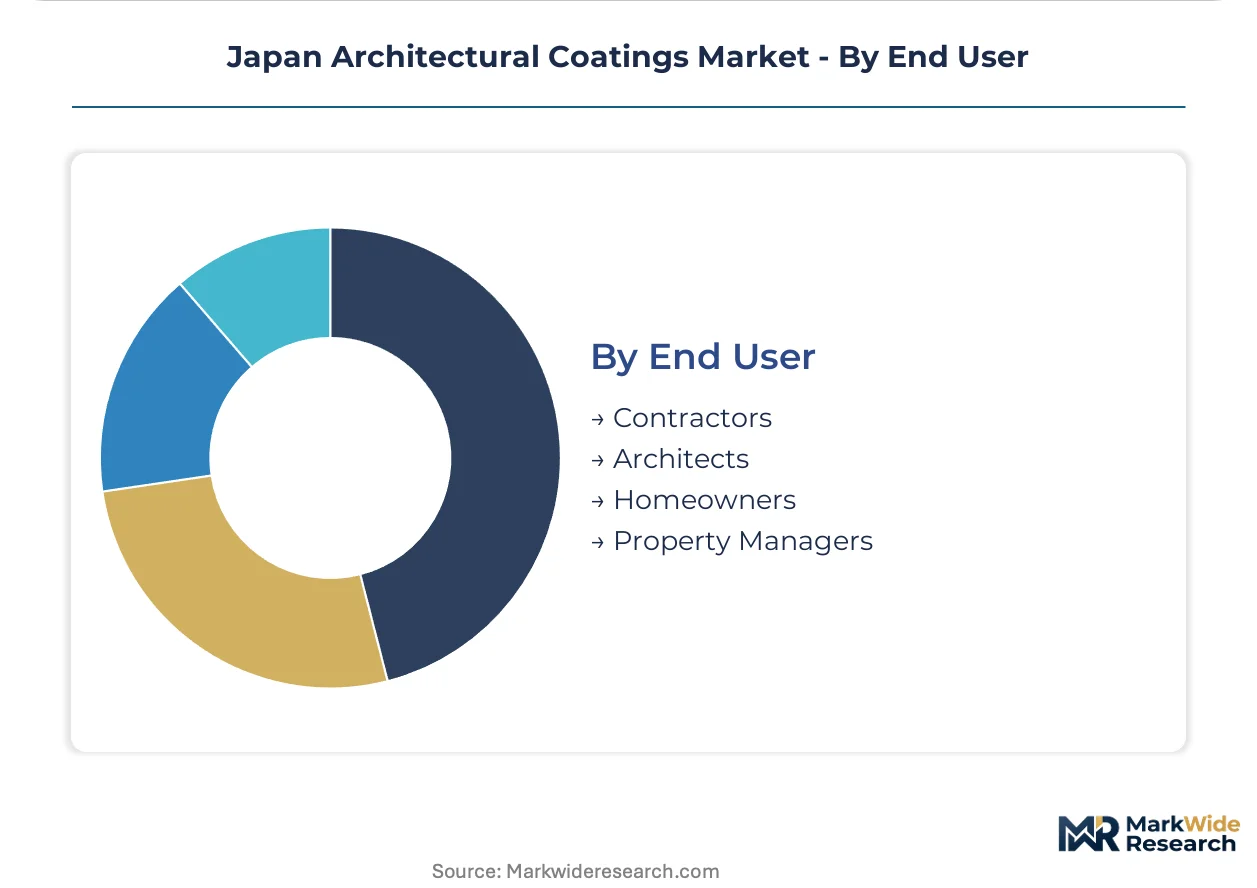
End User:
Customer type determines procurement channel and specification authority. Professional intermediaries control premium segments while price-sensitive owner-occupiers drive commodity volume.
- Contractors:Regional construction consortia in Kansai and Chubu prefectures negotiate volume contracts that limit distributor leverage. These buying pools prioritize JIS-certified systems that satisfy public project mandates.
- Architects:Digital specification tools reconfigure coating selection for high-visibility commercial projects in Tokyo and Yokohama. Photocatalytic self-cleaning systems are rendering obsolete scheduled maintenance contracts.
- Homeowners:Aging single-family stock in rural prefectures generates price-sensitive replacement demand through cooperative purchasing platforms.
- Property Managers:Portfolio-scale procurement for multi-unit residential complexes concentrates in Greater Tokyo Area urban densification zones.
Contractors control specification flow. Architect influence is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Japan's prefectural markets diverge sharply between coastal corrosion zones and inland metropolitan refinishing cycles. The Greater Tokyo Area drives premium specification volume while Kyushu and Shikoku island prefectures prioritize salt-air protection formulations.
Kanto/Tokyo
Olympic legacy infrastructure and commercial high-rise redevelopment sustain premium coating consumption across Tokyo's 23 wards. METI's pending amendments to JIS K 5660 accelerate recertification timelines for exterior wall systems. Digital specification tools are reconfiguring architect procurement patterns in Yokohama's waterfront districts.
Kansai/Osaka
Municipal aesthetic maintenance codes in Osaka and Kobe compress facade upgrade cycles for commercial properties. Photocatalytic titanium dioxide systems are rendering obsolete scheduled maintenance contracts on publicly visible structures. Regional construction consortia negotiate volume contracts that limit independent distributor leverage.
Chubu/Nagoya
Automotive and electronics manufacturing clusters in Aichi Prefecture generate steady industrial facility coating demand. Prefectural buying pools concentrate procurement authority among regional construction consortia. Epoxy-urethane hybrids protect manufacturing infrastructure against chemical exposure and abrasion.
Kyushu
Salt-air corrosion patterns in Fukuoka and Kagoshima prefectures create specialized demand for marine-grade formulation repurposing. Humid subtropical climate zones drive penetrating siloxane sealer specifications for masonry protection. Aging wooden housing stock in rural areas sustains cyclical refinishing demand through cooperative purchasing platforms.
Hokkaido
Aging single-family housing stock generates price-sensitive replacement demand concentrated among owner-occupiers. Prefectural housing maintenance cooperatives consolidate purchasing through centralized digital procurement platforms, displacing traditional dealer relationships. Alkali-resistant acrylic sealers penetrate porous concrete substrates in cold-climate construction.
Japan Architectural Coatings Market Competitive Landscape
Capability concentration sits with established Japanese formulators possessing JIS certification expertise; scale advantage sits with integrated chemical conglomerates with captive resin supply. The market structure tilts toward consolidation at the premium specification tier while mid-volume segments fragment across regional distributors. Two strategic archetypes dominate: formulation specialists with deep regulatory compliance capabilities, and diversified material suppliers leveraging backward integration into binder chemistry. Competitive moves center on dealer network digitization and preemptive formulation upgrades ahead of METI standard revisions.
Among Japan-based coating specialists, Nippon Paint Holdings Co., Ltd. and Kansai Paint Co., Ltd. occupy positions anchored by extensive distribution infrastructure and regional construction relationships. Jotun Japan Ltd. represents the foreign specialist archetype, repurposing marine-grade expertise for coastal architectural applications. These three companies exemplify how regulatory compliance capability and last-mile control determine competitive positioning in a market where METI-enforced standards and Ministry of the Environment emission ceilings constrain formulation flexibility.
| Leading Market Players |
|---|
| Nippon Paint Holdings Co., Ltd. |
| Kansai Paint Co., Ltd. |
| Jotun Japan Ltd. |
| Sherwin-Williams Japan |
| Daikin Industries, Ltd. |
| Asahi Kasei Corporation |
| Toshiba Chemical Co., Ltd. |
| Chugoku Marine Paints, Ltd. |
| Sumitomo Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
The Osaka-Kobe freight corridor channels titanium dioxide shipments from Chinese pigment producers to Kansai formulation plants, with logistics cost swings amplifying margin compression for mid-tier manufacturers lacking captive supply arrangements. This transport artery feeds directly into pricing stratification across premium JIS-certified systems, standard commercial specifications, and economy-grade rural refinish products.
Pricing Analysis
Long-term offtake contracts dominate procurement between regional construction consortia and established formulators, locking in volume commitments that insulate against titanium dioxide spot market volatility. Three-tier pricing structure across premium, standard, and economy levels reflects JIS certification grade and after-sales technical support bundling. Cost compression in the economy tier is intensifying because prefectural housing cooperatives extract manufacturer-direct pricing through centralized digital platforms. Homeowner owner-occupiers in rural Hokkaido and Tohoku exhibit highest price sensitivity, while Tokyo commercial developers accept premium positioning for accelerated recertification compliance.
Supply Chain Analysis
Toll manufacturing concentration rests with Nippon Paint and Kansai Paint integrated facilities across Aichi, Osaka, and Kanagawa prefectures, supplemented by regional blending operations serving prefectural distribution networks. Raw material sourcing draws from Chinese titanium dioxide producers, South Korean acrylic resin suppliers, and domestic urethane intermediate manufacturers. Single-source vulnerability concentrates in marine-grade aliphatic isocyanates imported from limited European suppliers. Distribution runs through manufacturer-controlled dealer networks synchronized to prefectural demand patterns via proprietary inventory management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's architectural coatings sector sits at an inflection where METI's pending JIS K 5660 amendments will forcibly retire legacy formulations, compressing competitive advantage toward preemptive compliance investment. This regulatory compression creates asymmetric returns for capability-rich incumbents while raising barriers for resource-constrained challengers.
For Market Incumbents: Harden JIS certification pipelines through accelerated laboratory testing protocols that preempt formal adoption timelines. Deepen backward integration into acrylic resin production to offset titanium dioxide cost volatility and secure formulation flexibility for low-VOC hybrid development. Channel control investments in rural Hokkaido digital procurement platforms will defend against cooperative purchasing disintermediation. For New Entrants and Emerging Players: Kyushu island prefectures present underpenetrated white space where salt-air corrosion specialization commands premium positioning unavailable to generic interior-focused competitors. Coastal commercial facade specifications in Fukuoka and Kagoshima reward marine-grade formulation repurposing expertise. Partner with regional maintenance cooperatives on performance-guaranteed service contracts rather than commodity product sales. For Investors and Strategic Acquirers: Regional formulators possessing dormant JIS certification capabilities and underutilized blending capacity in Chubu prefecture represent consolidation targets for platform roll-up strategies. Watch for METI announcement timing on JIS K 5660 amendment finalization as the inflection signal triggering preemptive acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | Captive supply secures formulation flexibility against titanium dioxide volatility and METI compliance timelines. |
| Digital Color-Matching Platform Launch | Touch-up program digitization recaptures aftermarket revenue ceded to independent painter networks. |
| Photocatalytic Titanium Dioxide Certification | Self-cleaning specifications in Osaka and Yokohama municipal contracts compress competitor refinishing cycles. |
| Prefectural Cooperative Direct Contracting | Manufacturer-direct pricing agreements with Hokkaido housing maintenance cooperatives displace traditional dealer relationships. |
| Marine-Grade Formulation Repurposing | Jotun-derived coastal corrosion expertise opens Kyushu and Shikoku specification tiers inaccessible to inland competitors. |
Research Methodology
A spread of perspectives from formulation chemists at established producers, procurement leads at regional construction consortia, prefectural housing cooperative managers, and METI standards officials converged on the working assumptions underlying demand projections. These primary insights were validated against customs trade data for titanium dioxide and acrylic resin imports, JIS certification registry filings, Ministry of the Environment VOC emission compliance reports, and prefectural construction permit databases. Bottom-up volume estimates from prefectural coating consumption patterns were triangulated against top-down market sizing from resin production statistics.
Demand-supply-balance modeling across the analysis window incorporated segment-level replacement cycle assumptions, regulatory compliance cost pass-through elasticities, and raw material input cost trajectories. Segmentation dimensions included product type, application category, binder technology, and end-user procurement channel, with additional granularity on JIS certification tier and prefectural climate zone. CAGRs were derived from regression analysis of historical volume trends adjusted for regulatory inflection impacts. Forecast inputs specifically incorporated METI amendment probability-weighted timing scenarios and cooperative purchasing platform penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive preemptive certification moves by mid-tier regional formulators or accelerated cooperative consolidation would shift outcomes beyond modeled ranges. Quarterly review of JIS K 5660 amendment progress, titanium dioxide import price indices, and prefectural digital procurement platform membership growth is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
PACVD-Based Coatings Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market
Coatings
North America Powder Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
High Performance Epoxy Coating Market
Coatings
Conductive Coatings Market
Coatings
Electrically Conductive Coating Market
Coatings
Global Diamond Coatings Market
Coatings
China Marine Coatings Market
Coatings
Transportation Coating Market
Coatings
Acrylic Protective Coating Market
Coatings
Global Floor Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Bio-Based Coatings Market