
 Iron Gallium Alloy (Galfenol) Market | 2026-2036
Iron Gallium Alloy (Galfenol) Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Gallium Alloy (Galfenol) Market Insights
Aftermarket sensor calibration revenue is fragmenting across regional service networks as original equipment manufacturers cede maintenance contracts to third-party specialists. TdVib, LLC leverages its magnetostrictive testing infrastructure to dominate North American refurbishment channels. ETREMA Products, Inc. anchors defense-sector supply relationships through in-house crystal growth capabilities. TDK Corporation competes in high-volume actuator segments by extending its ferrite manufacturing scale into galfenol sheet production.
Iron gallium alloy is a magnetostrictive material typically composed of iron with gallium additions ranging from fifteen to twenty-nine atomic percent, exhibiting strain responses up to four hundred parts per million under moderate magnetic fields and enabling direct mechanical-to-electrical energy transduction without piezoelectric ceramics. Cast iron variants sustain premium pricing in structural load-bearing applications where fatigue resistance outweighs formability requirements. Energy harvesting deployments represent the fastest-growing application segment as industrial IoT networks adopt wireless sensor nodes powered by ambient vibration. Aerospace end users occupy the highest-margin tier, demanding wrought iron forms with certified grain orientation for flight-critical actuation systems.
FAA airworthiness directives and DoD magnetostrictive material specifications constrain foreign-sourced galfenol access for US defense and aviation applications. EPA hazardous waste protocols govern gallium recovery from spent alloy, raising processing costs for domestic refiners. Stakeholders must monitor evolving export control classifications for strategic magnetostrictive materials while positioning captive gallium supply agreements ahead of regulatory tightening.
Market Dynamics
The US Department of Defense's magnetostrictive material sourcing directives are compressing procurement timelines for domestic galfenol producers while simultaneously locking out foreign alloy suppliers from defense-critical supply chains.
Growth Catalysts
- DoD Magnetostrictive Directives:Pentagon procurement rules now mandate domestic provenance for flight-critical actuation alloys, channeling federal R&D contracts toward US-based crystal growth facilities.
- Industrial IoT Vibration Harvesting:Wireless sensor networks in manufacturing plants deploy galfenol energy harvesters to eliminate battery maintenance in hard-to-access machinery monitoring points.
- Precision Engineering Corridor Concentration:Germany's Baden-Württemberg automation cluster sources certified wrought galfenol for robotic force-feedback systems requiring mechanical resilience beyond piezoelectric limits.
Market Restraints
- Gallium Supply Concentration:Primary gallium refining capacity clusters in China, exposing Western alloy producers to export restriction risk and price volatility in feedstock procurement.
- EPA Hazardous Waste Recovery:Spent galfenol processing triggers Resource Conservation and Recovery Act hazardous waste protocols, elevating end-of-life costs above competing magnetostrictive materials.
- Terfenol-D Substitution Threat:Terbium-iron-dysprosium alloys retain performance advantages in high-strain actuation, limiting galfenol penetration in premium aerospace displacement applications.
Strategic Opportunities
- Medical Robotics Miniaturization:Surgical robot manufacturers in Switzerland specify micro-scale galfenol actuators for haptic feedback instruments where electromagnetic interference must be minimized.
- EU Critical Raw Materials Act:Brussels' strategic autonomy framework designates gallium as a priority raw material, unlocking project financing for European primary refining and alloy production capacity.
- Digital Twin Convergence:Integration of magnetostrictive sensor arrays with physics-based simulation platforms enables predictive maintenance contracts for rotating machinery in offshore wind installations.
Industry Challenges
- Single-Crystal Growth Talent Scarcity:Bridgman and Czochralski crystal growth expertise concentrates in legacy defense contractors, constraining workforce availability for commercial-scale expansion.
- FAA Airworthiness Certification Timelines:Flight-critical galfenol components require extensive fatigue testing under FAA Part 25 protocols, extending product qualification cycles beyond typical commercial development windows.
- Legacy System Integration Complexity:Existing hydraulic and electromagnetic actuation architectures in industrial automation resist retrofit, forcing galfenol suppliers to engineer drop-in mechanical compatibility modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Gallium Alloy (Galfenol) Market |
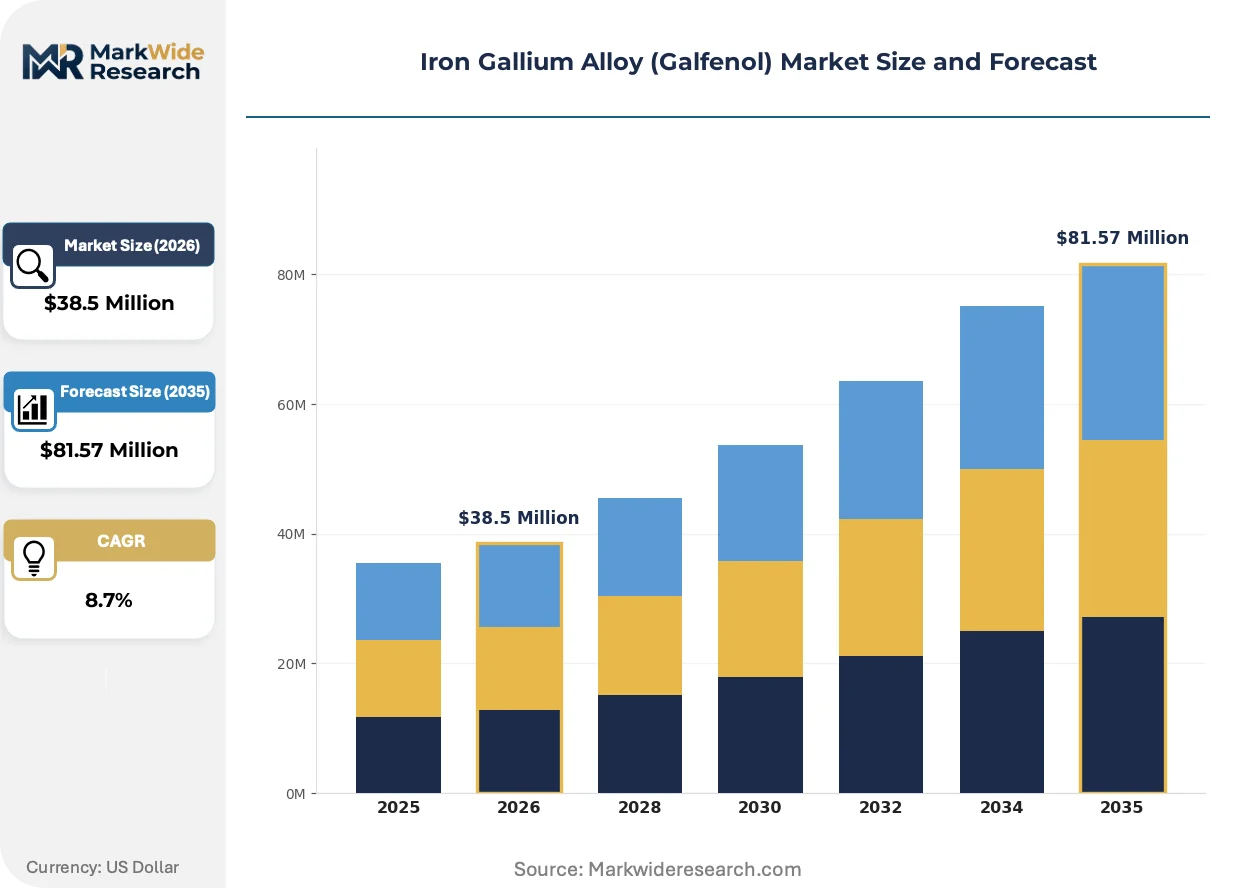
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $81.57 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron, Wrought Iron, Powdered Iron, Composite Iron Application: Sensors, Actuators, Energy Harvesting, Structural Applications End User: Aerospace, Automotive, Robotics, Consumer Electronics Form: Bars, Sheets, Coils, Powders |
| Companies Covered | TdVib, LLC, American Elements, Suzhou A-one Special Alloy, Beijing Goodwill Metal, Suzhou Xunshi, ETREMA Products, Inc., TDK Corporation, Advanced Magnetostrictive Materials, Magnetostrictive Systems Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Gallium Alloy (Galfenol) Market Trends and Innovations
Magnetostrictive material science is converging with additive manufacturing and closed-loop control systems, compressing the traditional boundaries between raw alloy supply and finished actuator assembly.
Directionally solidified galfenol is migrating from defense-aerospace procurement channels into industrial automation. Automotive tier-one suppliers now pilot wrought galfenol torque sensors for electric power steering feedback. This migration from exotic to mainstream specification is collapsing the traditional premium pricing tier for standard-grade alloy forms.
REACH authorization requirements for gallium compounds are tightening substance registration obligations for EU-based processors. The European Chemicals Agency's 2024 dossier updates now classify certain gallium precursors as substances of very high concern. German precision component manufacturers are responding by accelerating captive recycling investments to reduce virgin material dependency.
Aftermarket service unbundling is fragmenting maintenance revenue across third-party calibration specialists. Original equipment manufacturers now cede long-term sensor refurbishment contracts to regional service networks with localized magnetostrictive testing capabilities. This behavioral shift is most pronounced in North American industrial automation, where facility managers prioritize uptime guarantees over single-source vendor relationships.
Iron Gallium Alloy (Galfenol) Market Segmentation
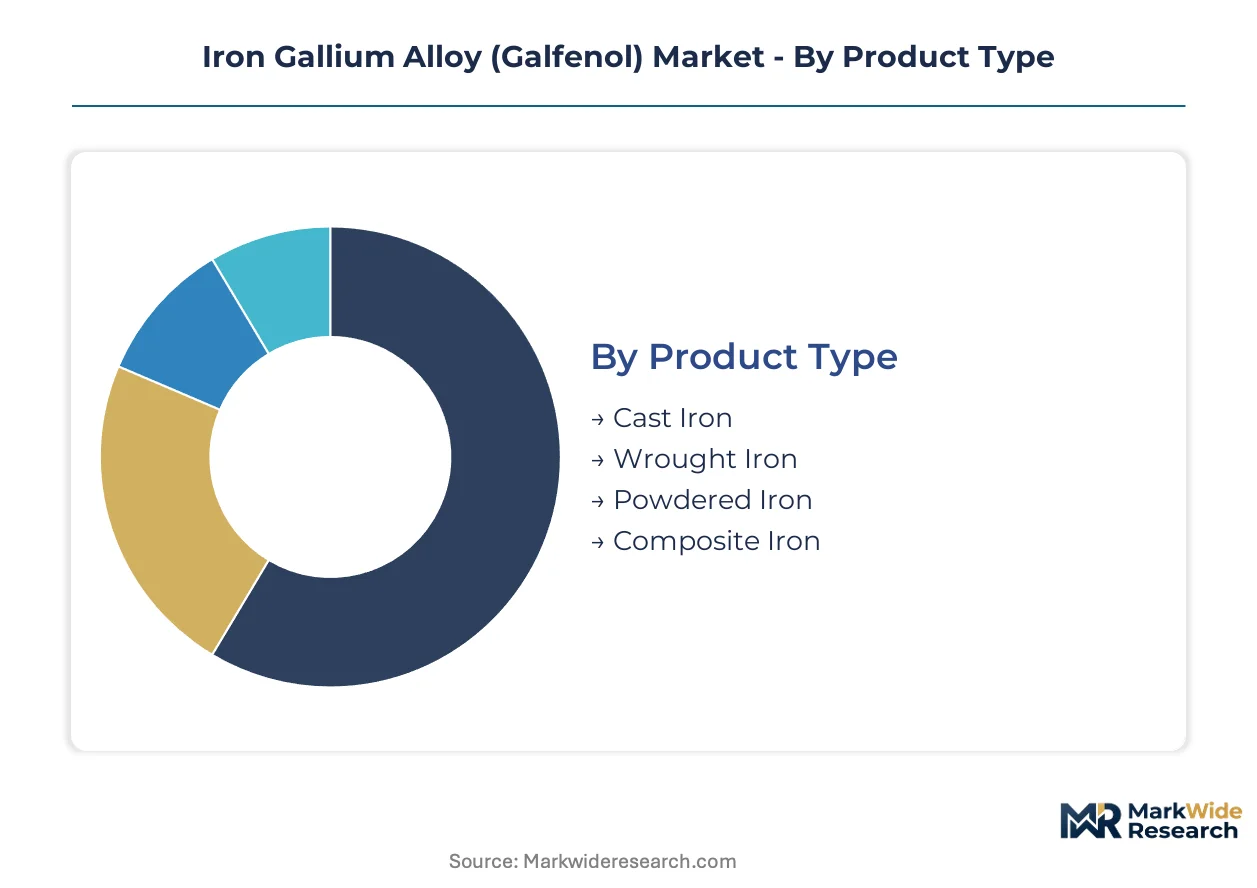
Galfenol's magnetostrictive properties create divergent service intensity profiles across product forms and end-use specifications. Aftermarket calibration demands concentrate in aerospace and precision robotics segments where sensor drift tolerance tightens with application criticality.
Product Type:
Service contract penetration varies sharply by metallurgical form, with wrought and cast variants commanding divergent refurbishment economics.
- Wrought Iron:Directionally solidified wrought galfenol delivers certified grain orientation for flight-critical actuation systems. FAA Part 25 fatigue protocols in the United States and EASA CS-25 requirements in Germany sustain premium aftermarket service contracts for wrought forms in commercial aviation.
- Cast Iron:Cast variants tolerate higher gallium content variance while sustaining structural load-bearing performance. Foundries in Japan's precision casting corridor supply cast galfenol for industrial automation bases where fatigue resistance outweighs formability requirements.
- Powdered Iron:Atomized powder feedstocks enable additive manufacturing of complex magnetostrictive geometries.
- Composite Iron:Polymer-matrix galfenol laminates reduce eddy current losses in high-frequency actuation.
By volume, cast iron leads. By growth pace, wrought iron is ahead.
Application:
Application selection dictates procurement channel structure, with defense-direct and industrial-distributor routes serving distinct specification tolerances.
- Sensors:Galfenol strain sensors convert mechanical deformation into electrical signals without piezoelectric ceramics' temperature drift limitations. Swiss surgical robot manufacturers specify micro-scale galfenol torque sensors for haptic feedback instruments where electromagnetic interference must be minimized.
- Actuators:Solid-state actuation eliminates hydraulic fluid maintenance in precision positioning systems. Germany's Baden-Württemberg automation cluster sources certified wrought galfenol for robotic force-feedback systems requiring mechanical resilience beyond piezoelectric displacement limits.
- Energy Harvesting:Ambient vibration transduction powers wireless sensor nodes in hard-to-access machinery monitoring points.
- Structural Applications:Load-bearing magnetostrictive elements integrate sensing and structural functions.
Actuators dominate current revenue. Energy harvesting shows the steepest expansion trajectory.
End User:
End-user concentration determines specification tiering, with defense and medical applications isolating supply relationships from price-driven competition.
- Aerospace:Flight-critical components demand wrought forms with certified grain orientation and full material traceability. FAA airworthiness directives and DoD magnetostrictive material specifications constrain foreign-sourced galfenol access for United States defense and aviation applications.
- Robotics:Collaborative robot manufacturers prioritize galfenol's mechanical resilience for force-limited human-robot interaction. Switzerland's medical robotics miniaturization segment specifies micro-scale actuators where electromagnetic compatibility certification exceeds standard industrial requirements.
- Automotive:Electric power steering feedback systems pilot wrought galfenol torque sensors at tier-one suppliers.
- Consumer Electronics:Miniature haptic actuators compete with piezoelectric alternatives on cost.
Aerospace commands the highest margins. Robotics is climbing the fastest.
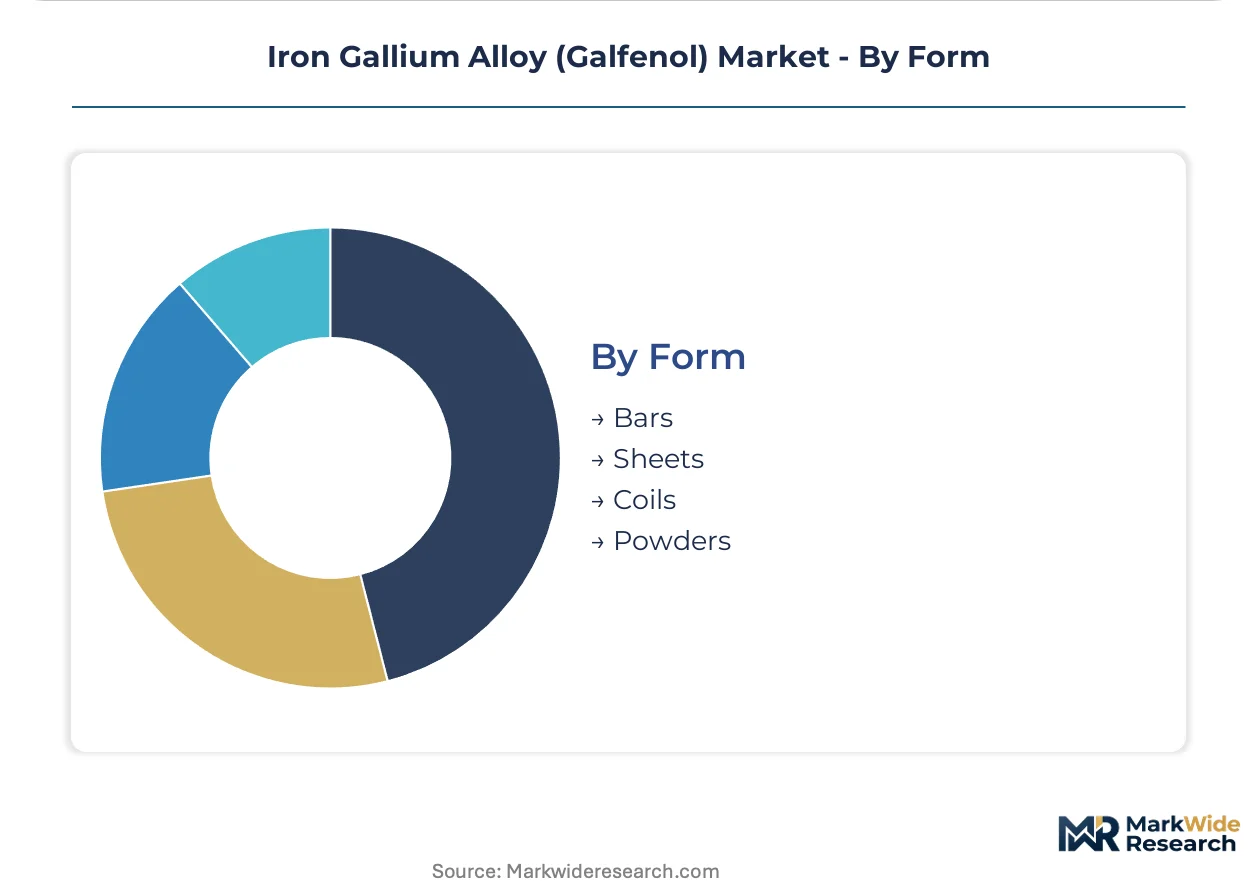
Form:
Physical form factors align with downstream fabrication methods, from machined components to thin-film deposition processes.
- Sheets:Rolled sheet galfenol enables stamped laminations for high-frequency magnetic circuits. TDK Corporation extends ferrite manufacturing scale into galfenol sheet production for high-volume actuator segments.
- Bars:Round and rectangular bars feed CNC machining centers for precision actuator components.
- Coils:Continuous strip coil formats support automated winding of magnetostrictive transducers.
- Powders:Gas-atomized powders serve metal injection molding and additive manufacturing feedstocks.
Sheets lead in volume throughput. Bars retain the tightest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Aerospace buyers in the United States absorb premium wrought-grade premiums without volume compression, while industrial automation purchasers in China and Southeast Asia prioritize cast-grade cost efficiency over certified grain orientation.
United States
Defense procurement directives and FAA airworthiness certification sustain premium-tier demand for wrought galfenol in flight-critical actuation systems. The Department of Defense's magnetostrictive material sourcing rules now mandate domestic provenance for Pentagon contracts, channeling federal R&D toward US-based crystal growth facilities. Research Triangle Park in North Carolina hosts specialized testing infrastructure serving both military aviation and medical robotics qualification protocols.
Germany
Baden-Württemberg's precision engineering corridor sources certified wrought galfenol for robotic force-feedback systems requiring mechanical resilience beyond piezoelectric displacement limits. REACH authorization requirements for gallium compounds are tightening substance registration obligations for EU-based processors, accelerating captive recycling investments among Stuttgart-area component manufacturers. The European Chemicals Agency's 2024 dossier updates now classify certain gallium precursors as substances of very high concern.
Japan
Precision casting foundries in the Nagoya-Tokyo industrial belt supply cast galfenol for industrial automation bases where fatigue resistance outweighs formability requirements. METI's critical raw materials strategy designates gallium as a priority substance, unlocking project financing for domestic refining and alloy production capacity. Osaka-based metalworking clusters are piloting wrought galfenol torque sensors for electric power steering feedback at automotive tier-one suppliers.
Switzerland
Swiss surgical robot manufacturers specify micro-scale galfenol actuators for haptic feedback instruments where electromagnetic interference must be minimized. Swissmedic certification requirements for active implantable devices extend to magnetostrictive components in medical robotics, creating regulatory moats around Zurich-Geneva precision engineering networks. The country's pharmaceutical equipment supply chain is integrating galfenol strain sensors for force-controlled drug delivery mechanisms.
China
Primary gallium refining capacity concentrates in Chinese smelters, exposing Western alloy producers to export restriction risk and feedstock price volatility. The country's national mineral resources regulator has tightened export licensing for strategic raw materials including high-purity gallium metal. Shenzhen and Suzhou industrial zones host downstream alloy fabricators serving domestic robotics and consumer electronics actuator demand at scale-driven price points.
Iron Gallium Alloy (Galfenol) Market Competitive Landscape
Defense-anchored specialists and diversified materials conglomerates split the market along specification-tier lines. The vendor base concentrates around three strategic archetypes: crystal growth specialists with Bridgman and Czochralski expertise, ferrite-scale manufacturers extending magnetostrictive sheet production, and regional alloy traders serving cost-sensitive industrial automation. Dominant competitive moves include backward integration into captive gallium supply agreements and technology licensing partnerships bridging defense-aerospace and commercial-industrial market segments.
Within the defense-specialist tier, TdVib, LLC and ETREMA Products, Inc. occupy positions defined by magnetostrictive testing infrastructure and in-house crystal growth capabilities respectively. TDK Corporation represents the scale-driven archetype, extending ferrite manufacturing scale into galfenol sheet production for high-volume actuator segments. American Elements exemplifies the diversified materials supplier model, leveraging rare earth and specialty metal distribution networks to serve research and industrial qualification volumes.
| Leading Market Players |
|---|
| TdVib, LLC |
| American Elements |
| Suzhou A-one Special Alloy |
| Beijing Goodwill Metal |
| Suzhou Xunshi |
| ETREMA Products, Inc. |
| TDK Corporation |
| Advanced Magnetostrictive Materials |
| Magnetostrictive Systems Research |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Chinese primary gallium refining is compressing Western alloy producers' feedstock procurement flexibility while simultaneously elevating spot-price volatility for crystal growth facilities in the United States and Germany. This utilization squeeze forces domestic producers to absorb cost pass-throughs or surrender margin, reshaping contract structures across defense-aerospace and industrial automation tiers.
Pricing Analysis
Aftermarket sensor calibration contracts now generate lifetime value exceeding original equipment sales for precision-tier suppliers serving FAA-certified aerospace applications. Three-tier pricing structure across premium, standard, and economy levels separates directionally solidified wrought forms with grain orientation certification from cast variants and powder feedstocks. Cost compression in standard-grade sheet production is intensifying because TDK Corporation's ferrite-scale manufacturing extension collapses volume premiums. Industrial automation purchasers in China's Shenzhen corridor exhibit highest price sensitivity, while Swiss surgical robotics manufacturers absorb premium wrought-grade multiples without volume compression.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for Western galfenol producers dependent on high-purity gallium metal feedstocks. Primary refining capacity clusters in Chinese smelters, with downstream alloy fabrication drawing from Japanese precision casting foundries and German crystal growth facilities. Single-source vulnerability concentrates in Beijing's export licensing regime for strategic raw materials. Distribution runs through defense-direct procurement channels for flight-critical specifications and industrial-distributor networks for automation-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German precision engineering clusters and US defense procurement offices, fragmenting pricing leverage across tiered supplier bases. This consolidation forces alloy producers to choose between margin sacrifice and volume exclusion.
For Market Incumbents: Build regulatory certification moats by accelerating FAA Part 25 and EASA CS-25 qualification timelines for wrought forms before Terfenol-D substitution threats penetrate aerospace displacement applications. Anchor backward integration into captive gallium supply agreements with Australian or Canadian mining ventures to escape Chinese export restriction risk. Channel R&D investment toward single-crystal growth automation to offset Bridgman and Czochralski talent scarcity constraining commercial-scale expansion. For New Entrants and Emerging Players: Medical robotics miniaturization in Switzerland represents the most penetrable entry point, where Swissmedic certification requirements create regulatory moats isolating Zurich-Geneva precision engineering networks from price-driven competition. EU Critical Raw Materials Act project financing for gallium refining capacity offers second-mover advantage in European primary production. Pursue technology licensing partnerships with legacy defense contractors holding crystal growth expertise to bridge defense-aerospace and commercial-industrial market segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across single-crystal growth facilities as automation equipment and cleanroom infrastructure requirements escalate. Five-to-ten year viability favors acquisition targets with in-house Bridgman or Czochralski capabilities rather than toll-processing dependencies. Monitor EPA hazardous waste protocol enforcement intensity as the inflection signal for domestic refining cost structures versus offshore alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gallium Supply Agreement | Insulates Western alloy producers from Chinese export licensing volatility and spot-price spikes. |
| Single-Crystal Growth Automation | Offsets talent scarcity in Bridgman and Czochralski expertise concentrated in legacy defense contractors. |
| Medical Robotics Certification Pathway | Swissmedic compliance for active implantable devices creates premium pricing isolation from industrial tiers. |
| EU Critical Raw Materials Act Alignment | Unlocks Brussels project financing for gallium refining and alloy production capacity expansion. |
| Aftermarket Service Network Unbundling | Captures sensor calibration revenue as OEMs cede maintenance contracts to third-party specialists. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with crystal growth facility managers, defense procurement officers at the Pentagon and its prime contractors, precision robotics engineers in Baden-Württemberg and Switzerland, and aftermarket service technicians at regional calibration networks. Secondary validation drew from FAA airworthiness directive filings, EPA hazardous waste protocol updates, ECHA REACH authorization dossiers, and customs trade data tracking gallium metal flows. Bottom-up alloy production estimates and top-down end-use demand aggregation were triangulated to resolve segmentation discrepancies.
Calibration against historical capacity utilization rates and procurement contract award patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include metallurgical form, application function, end-user industry, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting of disclosed contract values and volume offtake commitments. Industry-specific forecast inputs incorporated METI critical raw materials strategy implementation timelines and EU strategic autonomy framework disbursement schedules.
Practitioners should monitor Beijing's export licensing enforcement intensity and ECHA substance of very high concern reclassifications for early signals of feedstock cost inflection. Forecasts reflect assumptions about defense procurement directive continuity and FAA certification timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Sintered Steel Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
North America Braze Alloys Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Chromium Carbide Overlay Plate Market