
 Glass Fiber Reinforced Polymer Market | 2026-2036
Glass Fiber Reinforced Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Fiber Reinforced Polymer Market Analysis
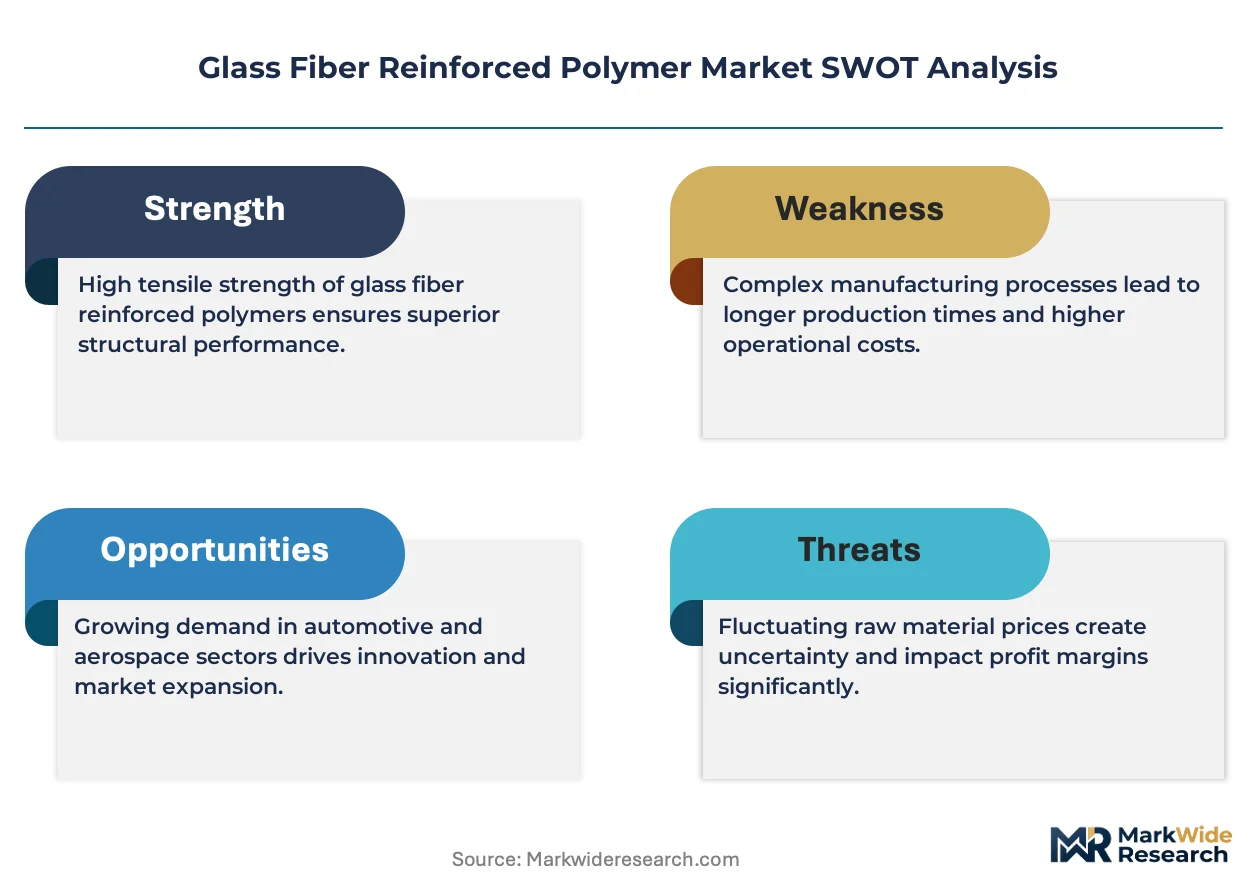
E-glass to S-glass specification migration is unwinding across wind blade and aerospace supply chains. Owens Corning leverages its mineral wool and glass fiber integration to control raw material cost volatility. China Jushi Co. Ltd anchors global roving supply through capacity concentration in Zhejiang province. Hexcel Corporation specializes in aerospace-grade prepreg formulations with elevated modulus targets.
Glass fiber reinforced polymer consists of continuous or chopped glass filaments embedded within a thermosetting or thermoplastic resin matrix, typically achieving fiber volume fractions of 30-70% depending on manufacturing process and end-use structural requirement. The composite delivers high strength-to-weight ratio, corrosion resistance, and electromagnetic transparency for infrastructure, transportation, and energy applications. Prepreg formats command premium positioning in aerospace and wind energy segments where autoclave consolidation ensures void-free laminates. Thermoplastic technology represents the fastest-expanding processing category as recyclability mandates from automotive OEMs reshape material selection criteria. Pultrusion maintains mature, high-volume economics in construction profiles and electrical insulation components where dimensional tolerance requirements are less stringent.
REACH compliance in Europe governs styrene emissions from unsaturated polyester resins, compelling reformulation investments across laminates and molding compounds segments. EPA air toxics standards in the United States shape open-mold fabrication economics and accelerate closed-mold process adoption. China's GB standards for fiber-reinforced plastics establish domestic certification barriers for imported construction materials. Stakeholders must track regulatory divergence between thermoset and thermoplastic pathways as carbon accounting frameworks mature.
Market Dynamics
Thermoplastic composite adoption is compressing manufacturing cycle times across automotive and aerospace supply chains, forcing resin formulators and fabricators to retool capacity toward melt-processable systems.
Growth Catalysts
- Automotive OEM recyclability mandates:European Union end-of-life vehicle directives and corporate carbon neutrality targets are mandating thermoplastic composites that enable material recovery and closed-loop reprocessing.
- REACH styrene emission controls:ECHA enforcement on unsaturated polyester resin emissions is accelerating closed-mold process investment across European laminates and marine fabrication.
- China eastern coastal manufacturing clusters:Concentrated wind blade and electrical insulation production in Zhejiang and Jiangsu provinces is pulling high-volume roving supply into integrated regional supply chains.
Market Restraints
- Raw material cost volatility:Boron-free E-glass and high-modulus S-glass filament feedstocks face energy-linked price swings tied to natural gas and electricity benchmarks.
- Zhejiang province capacity concentration:Global roving supply dependence on a single Chinese coastal region creates geographic risk exposure for wind energy and construction profile manufacturers.
- Thermoset curing limitations:Epoxy and vinyl ester systems require extended autoclave or oven cycles that constrain throughput against thermoplastic alternatives.
Strategic Opportunities
- India infrastructure build-out:National highway expansion and smart city programs are creating first-wave demand for corrosion-resistant GFRP rebar and utility poles outside traditional Western markets.
- Electrification thermal management:Battery enclosure and electric motor housing applications are opening high-temperature thermoplastic composite specifications previously served by metals.
- EU F-Gas Regulation material substitution:Refrigeration and HVAC OEMs are qualifying lower-global-warming-potential resin systems to replace polyurethane foam in insulated panel applications.
Industry Challenges
- Autoclave operator certification gaps:Void-free aerospace prepreg consolidation requires specialized technician training that outpaces vocational program output in multiple manufacturing regions.
- Multi-material joining complexity:Hybrid structures combining GFRP with aluminum or carbon fiber demand adhesive and mechanical fastening expertise that legacy metal fabrication shops lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Fiber Reinforced Polymer Market |
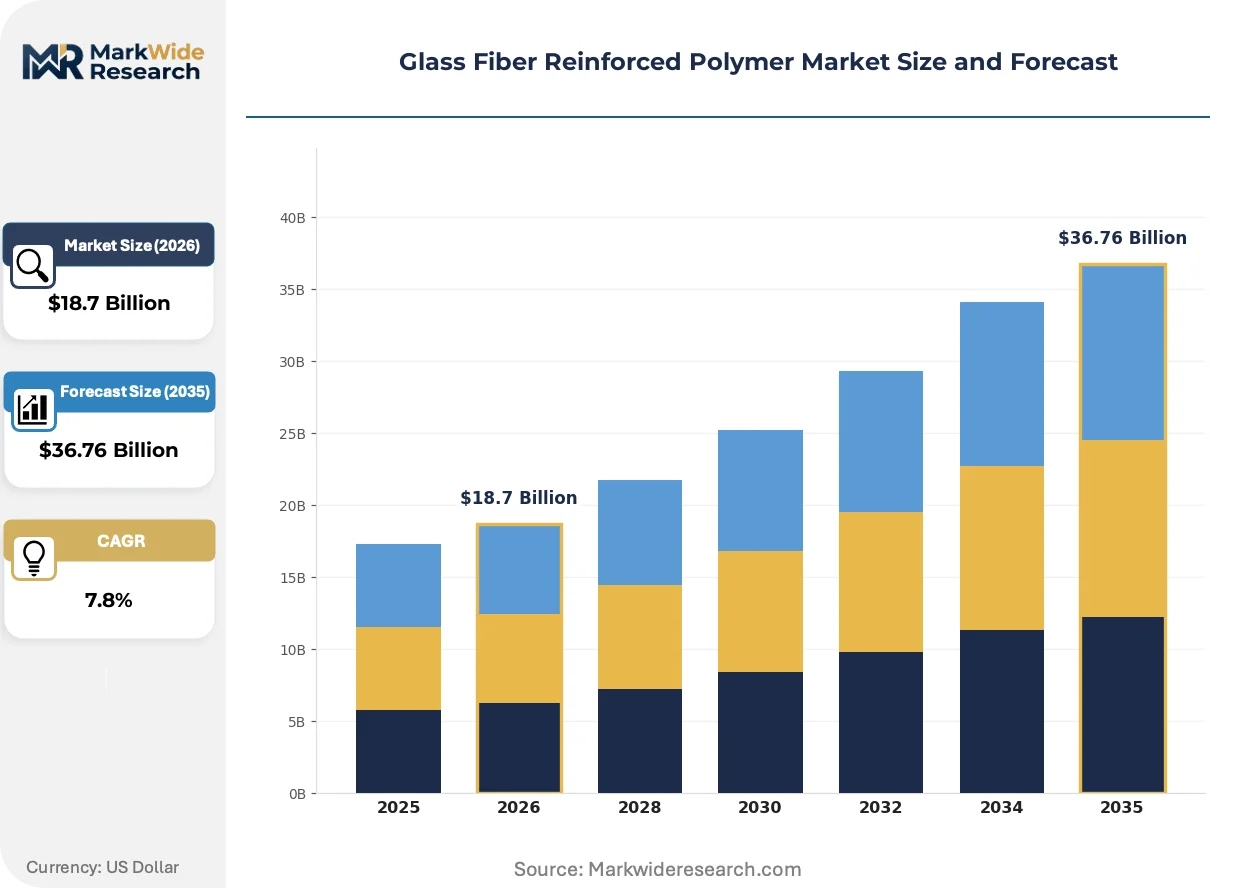
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepreg, Laminates, Rolls, Molding Compounds End User: Aerospace, Automotive Parts, Construction Materials, Consumer Goods Technology: Thermosetting, Thermoplastic, Resin Transfer Molding, Pultrusion Application: Wind Energy, Marine, Electrical Insulation, Infrastructure |
| Companies Covered | Hexcel Corporation, Advanced Composites Inc, Owens Corning, Saint-Gobain S.A, Celanese Corporation, China Jushi Co. Ltd, BASF SE, Mitsubishi Chemical Corporation, Johns Manville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Fiber Reinforced Polymer Market Emerging Trajectories
Material-process convergence is collapsing traditional boundaries between thermoset and thermoplastic supply chains, with automation and sustainability metrics now dictating format selection ahead of pure performance specifications.
Commingled glass-thermoplastic fiber formats are miniaturizing preform handling and heating stages. Automotive Tier 1 suppliers are adopting these stampable sheet systems for bumper beams and underbody shields. The technology is miniaturizing capital equipment footprints and enabling cell-based manufacturing layouts that bypass centralized autoclave operations.
EPA air toxics standards for open-mold styrene emissions are compelling fabrication migration toward resin transfer molding and vacuum infusion processes. Closed-mold equipment investments are rising fastest among US boat builders and corrosion-resistant tank manufacturers. California and Gulf Coast fabricators face the steepest compliance timelines, with some converting entirely to vacuum-assisted techniques.
Direct long-fiber thermoplastic pellet feeding is altering compounding economics for injection molders serving appliance and power tool housings. Compounders are bypassing traditional roving chopping and pre-compounding steps, feeding continuous glass directly into twin-screw extruders at OEM molding sites. This pattern is most visible among German and Japanese appliance manufacturers seeking to internalize material cost control.
Glass Fiber Reinforced Polymer Market Segmentation
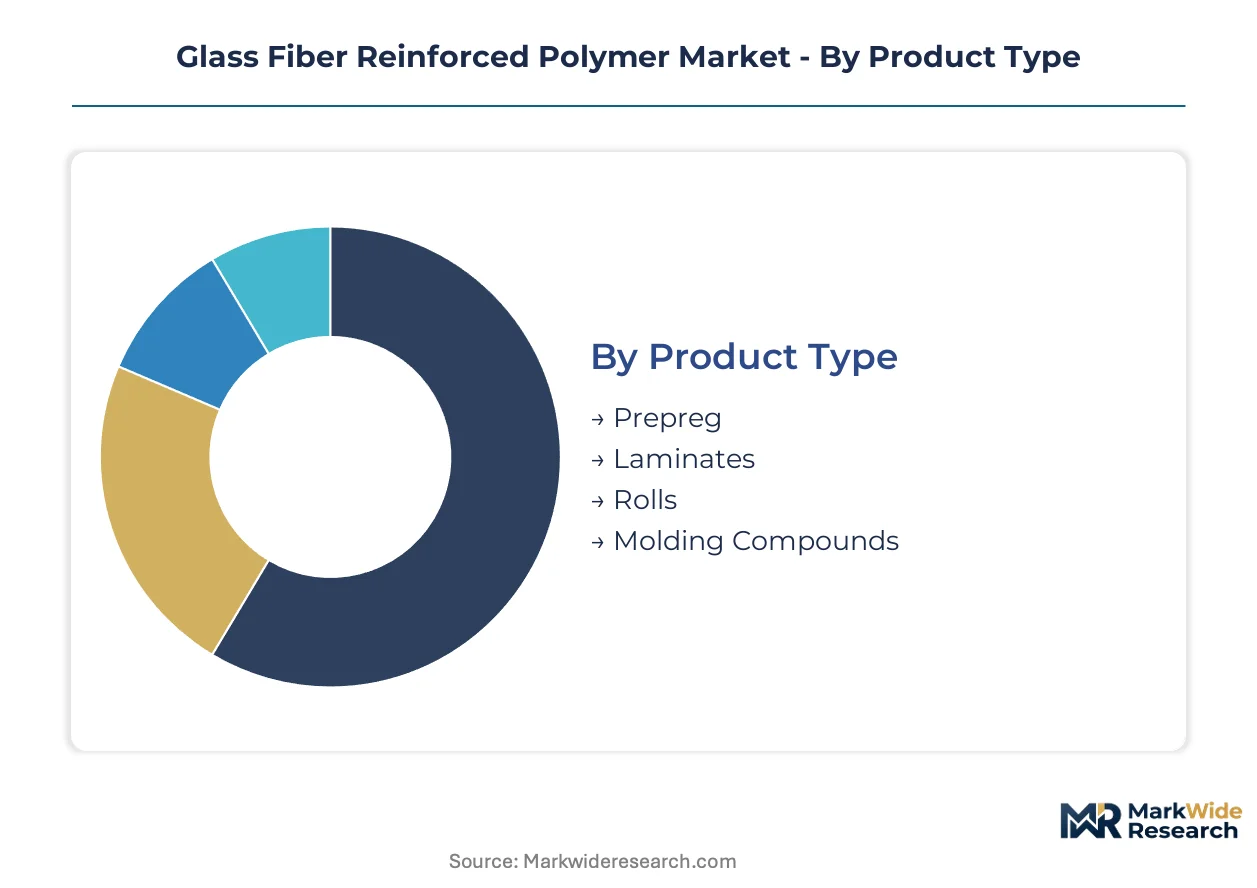
Glass fiber reinforced polymer formats diverge sharply in processing economics and performance certification. Aerospace and wind energy procurement teams specify distinct material hierarchies that reshape margin distribution across supply chains.
Product Type:
Margin pools concentrate in formats requiring autoclave consolidation and void-free certification, where technical barriers protect pricing power.
- Prepreg:Pre-impregnated unidirectional or woven glass fabrics with catalyzed resin systems achieve fiber volume fractions of 55-65%. Wind blade manufacturers in China's eastern coastal clusters specify heavy-tow formats up to 1,200 gsm for spar cap infusion, while aerospace tier suppliers demand narrow-width aerospace-grade rolls for autoclave processing.
- Laminates:Cured sheet stock delivered in standard thicknesses from 0.5mm to 25mm serves electrical insulation and corrosion-resistant equipment fabrication. Marine OEMs in the US Gulf Coast specify vinyl ester laminates for hull construction, navigating EPA air toxics standards through closed-mold adoption.
- Rolls:Continuous roving and chopped strand mat formats feed high-volume pultrusion and spray-up operations.
- Molding Compounds:Bulk molding compound and sheet molding compound deliver rapid compression molding cycles for automotive and appliance housings.
The dominant share belongs to Laminates, while Prepreg is closing the gap fastest.
End User:
Application pull varies by durability requirement and regulatory exposure, with infrastructure and transportation presenting contrasting volume-margin tradeoffs.
- Aerospace:Primary and secondary structural applications demand elevated modulus specifications and flame-smoke-toxicity certification. Boeing and Airbus tier suppliers consolidate procurement through qualified prepreg formats, with thermoplastic composite adoption accelerating for ducting and interior panels.
- Automotive Parts:Underbody shields, bumper beams, and battery enclosures drive direct long-fiber thermoplastic specifications. German and Japanese OEMs are internalizing compounding operations to capture material cost control.
- Construction Materials:Rebar, grating, and utility poles exploit corrosion resistance in coastal and chemically aggressive environments.
- Consumer Goods:Appliance housings and power tool bodies prioritize surface finish and dimensional stability in injection-molded formats.
Construction Materials commands the largest volume position, though Automotive Parts is expanding most quickly.
Technology:
Processing category selection determines capital intensity, cycle time, and recyclability profile, creating divergent competitive moats.
- Thermosetting:Epoxy, polyester, and vinyl ester systems dominate established infrastructure and marine fabrication. REACH styrene emission controls in Europe are compressing open-mold economics and accelerating vacuum infusion adoption among laminators.
- Thermoplastic:Polyamide, polypropylene, and PEEK matrix systems enable melt reprocessing and end-of-life recovery. Automotive OEM recyclability mandates are pulling capacity investment toward stampable sheet and direct pellet feeding technologies.
- Resin Transfer Molding:Closed-mold infusion delivers dimensional precision for complex geometries in boat hulls and wind blade roots.
- Pultrusion:Continuous profile production achieves lowest-unit-cost economics for structural shapes and electrical insulation components.
Thermosetting retains the dominant installed base, while Thermoplastic is gaining share fastest.
Application:
End-use specifications range from commodity electrical grades to aerospace structural qualifications, fragmenting supplier positioning.
- Wind Energy:Blade spar caps, shells, and root inserts demand heavy-tow unidirectional prepreg and infusion-compatible fabrics. Zhejiang and Jiangsu province manufacturing clusters anchor global demand concentration, with integrated roving-to-blade supply chains compressing logistics costs.
- Marine:Hull laminates, decks, and superstructures balance weight reduction against impact resistance and osmotic blistering resistance. US boat builders face steep EPA compliance timelines, converting vacuum-assisted processes at accelerated rates.
- Electrical Insulation:Transformer bushings, switchgear housings, and cable trays exploit dielectric strength and tracking resistance.
- Infrastructure:Bridge decks, retaining walls, and seismic retrofits deploy GFRP rebar and strengthening systems for corrosion immunity.
Wind Energy holds the leading demand position, with Infrastructure expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in glass fiber reinforced polymer materials tilt heavily toward net-exporting manufacturing clusters, with import dependency concentrated in regions lacking integrated roving-to-fabrication supply chains. Energy cost differentials and regulatory stringency reshape regional competitiveness.
China
Wind blade and electrical insulation demand concentrates in Zhejiang and Jiangsu provinces. GB standards for fiber-reinforced plastics establish certification barriers that favor domestic producers over imported construction materials. The Yangtze River Delta anchors global roving supply through captive glass furnace operations serving integrated blade manufacturing.
United States
EPA air toxics standards for open-mold styrene emissions accelerate closed-mold process adoption among Gulf Coast boat builders and corrosion-resistant tank fabricators. Aerospace tier suppliers in Washington and California states consolidate procurement through qualified prepreg formats. The Southeast attracts pultrusion capacity serving electrical infrastructure replacement cycles.
Germany
REACH styrene emission controls enforced by ECHA compress open-mold economics and drive vacuum infusion investment across laminators serving marine and industrial equipment segments. Automotive OEMs in Bavaria and Baden-Württemberg internalize direct long-fiber thermoplastic compounding for battery enclosures and underbody shields.
India
National highway expansion and smart city programs create first-wave demand for corrosion-resistant GFRP rebar and utility poles. The central bank's infrastructure financing priorities channel capital toward durable materials in coastal and chemically aggressive environments. Gujarat and Maharashtra states host emerging fabrication clusters serving domestic civil engineering procurement.
Japan
METI industrial policy supports thermoplastic composite development for automotive lightweighting and electrification thermal management. Appliance manufacturers in the Kansai region adopt direct long-fiber pellet feeding to internalize material cost control. JIS standards govern electrical insulation grades for transformer and switchgear applications.
Glass Fiber Reinforced Polymer Market Vendor Landscape
Listed leaders compete with private specialists across resin formulation and fabrication technology dimensions. The vendor base separates into consolidated glass fiber producers, diversified chemical conglomerates, and focused composite fabricators. Three archetypes dominate: integrated mineral-to-fiber operators, aerospace-grade prepreg specialists, and automotive-focused thermoplastic compounders. Capacity expansion and backward integration into raw material supply represent the primary competitive moves.
Among integrated fiber producers, Owens Corning and China Jushi Co. Ltd exemplify scale-driven archetypes with captive glass melting and roving operations. Hexcel Corporation occupies a position within the aerospace-grade prepreg tier, serving qualification-intensive structural applications. These three entities represent distinct strategic postures: mineral integration, regional supply chain anchoring, and premium specification focus.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Advanced Composites Inc |
| Owens Corning |
| Saint-Gobain S.A |
| Celanese Corporation |
| China Jushi Co. Ltd |
| BASF SE |
| Mitsubishi Chemical Corporation |
| Johns Manville |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between wind blade manufacturers and Zhejiang-based roving suppliers lock in both supply access and price visibility across multi-year procurement cycles, insulating buyers from energy-linked borosilicate glass feedstock volatility while constraining spot market liquidity for smaller fabricators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Aerospace-grade prepreg formats with autoclave consolidation and void-free certification command substantial premiums over pultruded construction profiles, while volume scale and fiber modulus specifications drive further differentiation. Pricing pressure stems from thermoplastic composite displacement of thermoset laminates in automotive applications, compressing margins among polyester resin compounders. Tier 1 automotive suppliers exhibit lowest price sensitivity due to internalized compounding operations, whereas small-scale marine fabricators face acute cost compression from EPA compliance investments.
Supply Chain Analysis
Inventory cycles for heavy-tow unidirectional roving stretch across ocean freight and customs clearance stages, extending lead times for European and North American wind blade manufacturers dependent on Chinese supply. Production concentrates in China, Germany, and the United States, with raw material flows drawing from boron-free E-glass furnace operations, epoxy resin formulation plants, and thermoplastic polymer compounding facilities. Single-source vulnerability pervades the Zhejiang-Jiangsu corridor, where integrated roving-to-blade supply chains dominate global capacity. Distribution runs through qualified supplier programs for aerospace tiers and spot procurement for construction profile distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic composite interoperability with existing automotive stamping infrastructure is collapsing traditional material qualification barriers, creating platform-economics dynamics where resin formulators and Tier 1 suppliers co-develop specifications that lock out non-integrated competitors.
For Market Incumbents: Secure backward integration into high-modulus S-glass filament production to defend margin position against Owens Corning's mineral wool integration advantages. Accelerate closed-mold vacuum infusion capacity in US Gulf Coast and European laminator networks before EPA and ECHA enforcement timelines harden. Certification investment in flame-smoke-toxicity standards for aerospace interior panels represents a critical defensive moat against thermoplastic composite entrants. For New Entrants and Emerging Players: Aerospace-grade prepreg qualification fast-tracks through delegated production authority agreements with established Tier 2 fabricators offer the most penetrable entry path against Hexcel's incumbent lock-in. Target India's emerging GFRP rebar fabrication clusters in Gujarat and Maharashtra, where domestic GB standard certification barriers favor local production partnerships over import competition. Direct long-fiber thermoplastic pellet feeding technology licensing to Japanese appliance manufacturers provides a capital-light go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap thermoplastic compounders with automotive OEM qualification and in-house polymerization capabilities, as recyclability mandates reshape material selection criteria across the projection horizon. Long-term viability hinges on exposure to electrification thermal management applications and battery enclosure specifications previously served by aluminum castings. Watch for inflection signals in India infrastructure financing disbursement rates and central bank priority sector lending allocations to civil engineering procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Melting | Captive borosilicate supply insulates Owens Corning and China Jushi from natural gas price volatility. |
| Closed-Mold Process Conversion | Vacuum infusion adoption among US Gulf Coast boat builders navigates EPA air toxics compliance timelines. |
| Thermoplastic Composite Qualification | Automotive OEM recyclability mandates in Europe pull capacity investment from German compounders. |
| Regional Capacity Expansion in India | Gujarat fabrication clusters capture first-wave demand from national highway and smart city programs. |
| Aerospace Prepreg Certification Investment | Flame-smoke-toxicity standards protect pricing power in Boeing and Airbus tier supplier networks. |
Methodological Framework
Cross-validation between primary interviews with wind blade procurement directors, automotive Tier 1 supplier engineers, and epoxy resin formulator technical leads anchors the qualitative findings against secondary validation from customs trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed composite producers. Bottom-up segment sizing triangulates against top-down macroeconomic elasticity estimates for industrial materials demand.
Sensitivity analysis around energy cost trajectories and regulatory enforcement timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include resin matrix type, fiber specification grade, manufacturing process technology, end-use application, and regional production cluster. CAGRs derive from elasticity-adjusted volume projections and value-per-unit trends informed by thermoplastic composite substitution rates and aerospace qualification backlogs.
The analysis sits within stated boundaries; outcomes outside sustained EMEA F-Gas Regulation enforcement, continued Chinese coastal manufacturing cluster concentration, and stable automotive lightweighting investment levels would require recalibration. Forecasts reflect documented assumptions around raw material cost pass-through mechanisms and OEM qualification cycle durations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Dry-Molded Fibre Market
Fibers
Global Nylon Monofilament Market
Fibers
Artificial Muscle Fibers Market
Fibers
High Performance Fibers for Defense Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Global Metal Fiber Market
Fibers
Ceramic Fiber Market
Fibers
Global Bicomponent Fiber Market
Fibers
Fiberglass Cloth Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Short Fiber Thermoplastics Market
Fibers
Fiberglass Sunscreen Market
Fibers
Viscose Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Carbon Fiber Filament Market
Fibers
PAN-Based Carbon Fibers Market