
 Medium Entropy Alloys Market | 2026-2036
Medium Entropy Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Medium Entropy Alloys Market Foresight
Multi-source procurement for critical raw materials is rebalancing toward qualified domestic suppliers across the medium entropy alloys value chain. Carpenter Technology Corporation leverages its vacuum induction melting capacity to anchor North American supply security for defense-grade compositions. VDM Metals competes through integrated powder metallurgy capabilities that sustain European aerospace qualification pipelines. QuesTek Innovations LLC differentiates via computational materials design platforms that accelerate alloy development cycles without traditional trial-and-error metallurgy.
Medium entropy alloys occupy a compositional space between conventional stainless steels and complex high-entropy systems, typically containing three to four principal elements in equiatomic or near-equiatomic ratios between 5% and 35% each, with total configurational entropy ranging from 1.0R to 1.5R. These alloys deliver superior strength-to-weight ratios and cryogenic toughness for structural applications where conventional materials face performance ceilings. Nickel-based grades dominate current aerospace procurement due to established oxidation resistance at elevated temperatures, while titanium-based variants represent the fastest-expanding product category for marine engineering applications demanding seawater corrosion immunity. The corrosion resistant grade segment captures concentrated margin pools as offshore infrastructure operators specify extended service-life alloys for subsea components.
The U.S. FAA and the EU EASA impose stringent airworthiness certification protocols that shape alloy qualification timelines and testing documentation burdens for aerospace suppliers. Japan's METI coordinates national research consortia advancing JIS-standardized medium entropy alloy specifications for domestic manufacturing competitiveness. China's SAMR enforces GB standards for structural materials deployed in civil infrastructure, creating divergent compliance pathways for multinational producers. Stakeholders must monitor how fragmented certification regimes between the U.S., Europe, and Asia reshape capital allocation for new melting capacity and whether harmonized international standards emerge to reduce redundant qualification costs.
Market Dynamics
Airworthiness certification timelines for nickel-based turbine alloys are compressing procurement cycles as aerospace OEMs pre-qualify domestic melting capacity ahead of FAA and EASA documentation requirements.
Growth Catalysts
- Defense procurement mandates:Pentagon sourcing directives prioritize qualified domestic suppliers for strategic materials, accelerating vacuum induction melting investments in U.S. specialty alloy facilities.
- REACH chemical traceability:ECHA compliance frameworks force material documentation upgrades across European aerospace supply chains, filtering out non-compliant secondary producers.
- Cryogenic toughness specifications:LNG infrastructure operators specify medium entropy alloys for liquefaction train components, creating pull-through demand from marine engineering procurement offices.
Market Restraints
- High-purity nickel volatility:London Metal Exchange pricing swings for Class 1 cathode feedstock compress margin predictability for alloy producers locked into long-term aerospace contracts.
- Electrode supply concentration:Premium vacuum arc remelting electrode manufacturing clusters in Germany and Japan create single-source vulnerability for North American turbine blade forgers.
- Substitute superalloy competition:Single-crystal nickel superalloys with established 30-year service databases block medium entropy alloy penetration in hot-section rotating components.
Strategic Opportunities
- India defense indigenization:Ministry of Defence production-linked incentive schemes for aerospace materials create entry pathways for qualified foreign alloy producers establishing local melting partnerships.
- Additive manufacturing convergence:Powder bed fusion platforms for titanium-based medium entropy alloys enable topology-optimized subsea manifold components without conventional forging minimums.
- EU Green Deal material circularity:Scrap segregation and re-melting certification protocols favor closed-loop producers with integrated vacuum induction and electroslag remelting capabilities.
Industry Challenges
- Computational metallurgy talent scarcity:Alloy design firms compete for PhD-level CALPHAD modelers capable of predicting multi-component phase stability across temperature ranges.
- Dual certification timeline compression:Simaneous FAA and EASA qualification for new compositions demands parallel documentation streams that strain quality assurance departments.
- Legacy heat treatment integration:Existing solution annealing and aging furnaces require retrofitted atmosphere control systems to handle oxygen-sensitive refractory metal additions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medium Entropy Alloys Market |
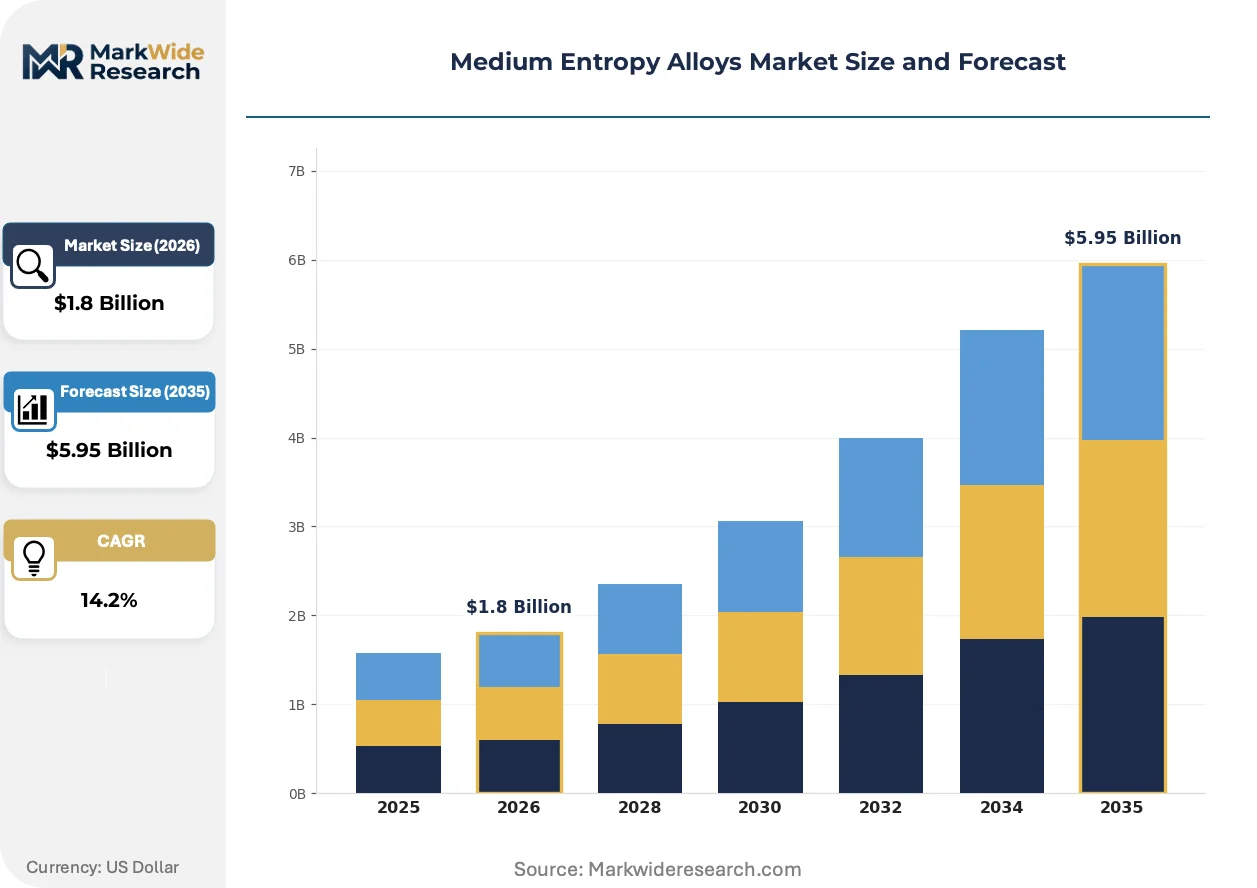
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper-based, Nickel-based, Iron-based, Titanium-based Application: Aerospace, Automotive Components, Structural Materials, Marine Engineering Grade: High Strength, High Ductility, Corrosion Resistant, Heat Resistant End User: Manufacturers, Research Institutions, Aerospace Companies, Defense Sector |
| Companies Covered | Carpenter Technology Corporation, ATI Specialty Alloys and Components, VDM Metals, Sandvik AB, Haynes International, Inc., Hitachi Metals, Ltd., QuesTek Innovations LLC, Osaka Titanium Technologies Co., Ltd., Nippon Yakin Kogyo Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medium Entropy Alloys Market Shifts & Advancements
Computational alloy design platforms are compressing development timelines from decade-long empirical cycles to predictive phase stability modeling, while regulatory documentation requirements simultaneously lengthen commercialization pathways.
Integrated computational materials engineering (ICME) frameworks are integrating density functional theory calculations with CALPHAD thermodynamic databases to predict precipitation kinetics in quaternary nickel-cobalt-chromium systems. Aerospace materials engineers at tier-one turbine suppliers adopt these tools for rapid screening of oxidation-resistant compositions. The technology is integrating formerly siloed experimental workflows into unified digital thread environments that compress alloy qualification schedules.
EASA's evolving Part 21J design organization approval requirements for novel materials are mandating expanded mechanical property datasets beyond traditional MMPDS statistical bases. European turbine OEMs must now submit extended fatigue crack growth documentation for medium entropy alloy substitutions in rotating hardware. Hot-section component categories face the steepest compliance burdens as regulators demand service-environment corrosion data matching existing superalloy archives.
Long-term offtake contracting is displacing spot procurement for critical raw materials as aerospace tier suppliers seek cathode feedstock price predictability. Defense prime contractors consolidate vendor bases to dual-source qualified domestic melters rather than maintaining fragmented global supplier panels. This behavioral shift concentrates most visibly in U.S. turbine blade forging operations where national security sourcing directives override traditional cost-minimization procurement logic.
Medium Entropy Alloys Market Segmentation
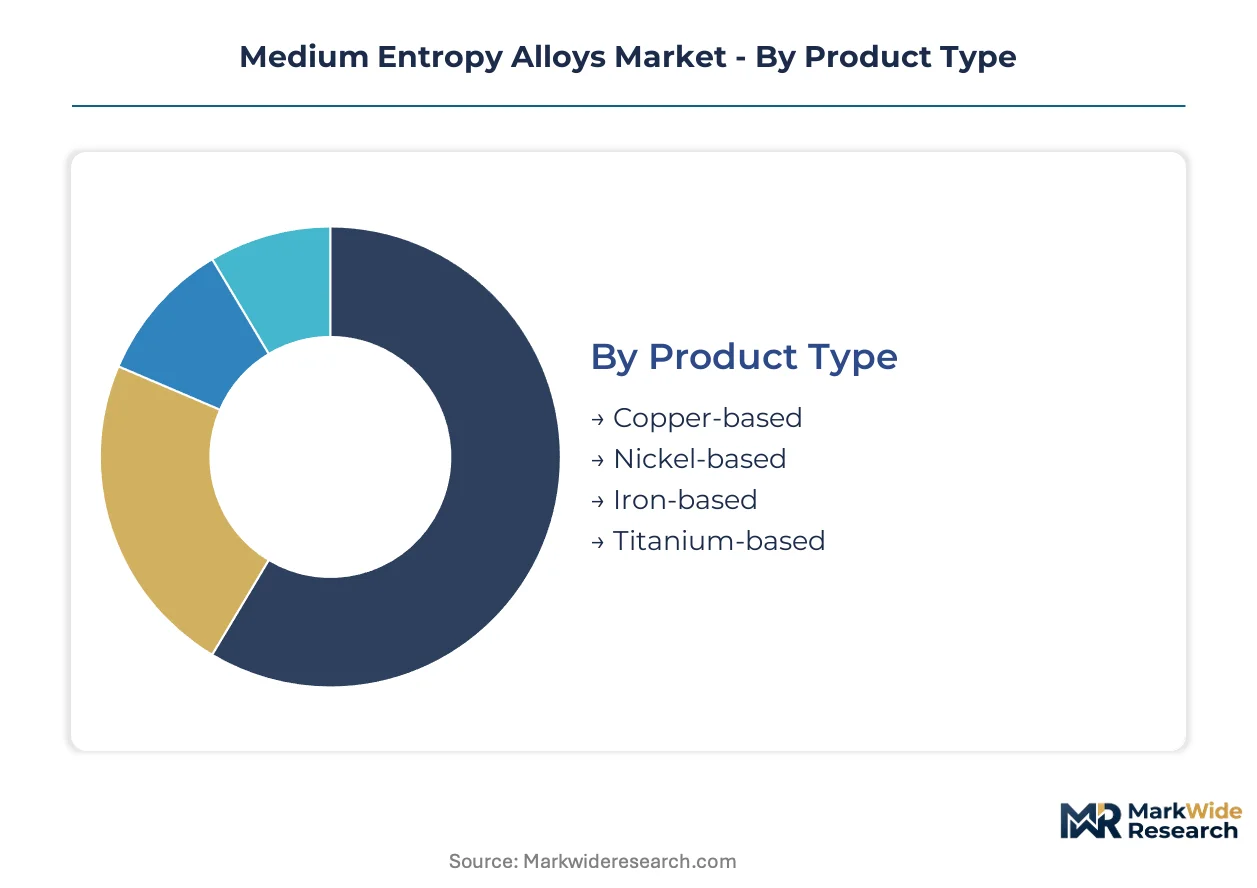
Medium entropy alloys span a narrow compositional bandwidth between conventional alloys and high-entropy systems, making specification discipline critical for procurement decisions. Segmentation by elemental base, mechanical grade, and end-use certification tier determines qualification timelines and margin structures across defense and commercial supply chains.
Product Type:
Nickel-based formulations anchor aerospace turbine qualification pipelines through established oxidation resistance databases, while titanium-based variants penetrate marine environments demanding seawater immunity.
- Nickel-based:Quaternary Ni-Co-Cr-Mo systems dominate hot-section rotating components where FAA and EASA airworthiness protocols demand extensive creep-rupture documentation. Demand concentrates in U.S. and German aerospace forging operations sourcing vacuum induction melted feedstock for defense prime contractors.
- Titanium-based:Ti-Zr-Hf-Nb compositions deliver alpha-beta phase stability for subsea manifold hardware facing chloride-induced cracking. Marine engineering procurement offices in Norway and Japan specify these grades for LNG liquefaction train components requiring cryogenic toughness.
- Copper-based:Cu-Ni-Zn-Al systems target electrical contact applications where thermal conductivity must coexist with wear resistance.
- Iron-based:Fe-Mn-Cr-Si alloys offer cost-advantaged structural alternatives where corrosion specifications permit reduced refractory metal content.
Mature deployment sits with nickel-based grades holding three decades of service data. Newer deployment is concentrated in titanium-based variants gaining share fastest in offshore infrastructure specifications.
Application:
End-use segmentation separates qualification-intensive rotating hardware from structural components facing less severe documentation burdens.
- Aerospace:Turbine blade and combustor liner applications impose dual FAA-EASA certification requirements that extend commercialization timelines. U.S. and French OEMs pre-qualify domestic melting capacity to compress procurement cycles for next-generation engine programs.
- Marine Engineering:Subsea production systems and desalination infrastructure specify corrosion-resistant grades with 25-year service life guarantees. Operators in the North Sea and Gulf of Mexico drive specification development for cathodic protection compatibility.
- Automotive Components:Exhaust valve and turbocharger hardware trials focus on cost-reduced iron-based formulations.
- Structural Materials:Civil infrastructure applications face GB standard compliance in China and Eurocode alignment in EU member states.
Established volume concentrates in aerospace procurement with locked-in superalloy substitution timelines. Emerging volume is accelerating in marine engineering where legacy stainless steel specifications face performance ceiling pressures.
Grade:
Mechanical property segmentation determines pricing tier and heat treatment complexity, with corrosion-resistant grades commanding premium margins for extended service-life contracts.
- Corrosion Resistant:Molybdenum-modified compositions achieve pitting resistance equivalent numbers exceeding 40 for seawater exposure. Offshore infrastructure operators in Brazil and Australia specify these grades for subsea Christmas tree components.
- Heat Resistant:Gamma-prime strengthened nickel systems maintain tensile strength above 800 MPa at 650°C for turbine disk applications. U.S. defense procurement mandates prioritize qualified domestic suppliers for these strategic grades.
- High Strength:Work-hardened variants target armor plate and ballistic protection where hardness-to-toughness ratios dominate specification.
- High Ductility:Metastable beta-titanium formulations enable cold-forming of complex marine hardware without intermediate annealing.
Specification maturity clusters in heat-resistant grades with established MMPDS statistical bases. Fastest specification evolution is occurring in corrosion-resistant grades as offshore operators extend design life targets.
End User:
Customer type segmentation separates volume procurement by defense primes from experimental volumes by research consortia advancing next-generation compositions.
- Defense Sector:Pentagon sourcing directives mandate qualified domestic melting for nickel-based turbine alloys, consolidating vendor panels to dual-source configurations. U.S. and UK defense procurement offices coordinate qualification data sharing to reduce redundant testing.
- Aerospace Companies:Tier-one turbine OEMs operate integrated materials engineering departments that conduct parallel FAA-EASA documentation streams. Safran and Rolls-Royce maintain proprietary alloy specifications beyond public MMPDS datasets.
- Research Institutions:National laboratories and university consortia advance CALPHAD-modelled compositions through small-batch arc melting.
- Manufacturers:Forging houses and additive manufacturing service bureaus source certified powder and electrode feedstock.
Procurement scale concentrates with defense sector and aerospace company buyers locking in multi-year offtake agreements. Experimental volume flows through research institutions advancing JIS and GB standardized specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity nickel feedstock from Canadian mining operations anchors North American supply security for defense-grade alloy production. German vacuum induction melting clusters anchor European aerospace qualification pipelines. Japanese titanium sponge production underpins marine engineering specifications across Pacific Rim infrastructure projects.
United States
Pentagon sourcing directives prioritize qualified domestic suppliers for strategic nickel-based turbine alloys. FAA airworthiness certification frameworks impose extensive creep-rupture documentation requirements on aerospace suppliers. Carpenter Technology Corporation operates vacuum induction melting capacity in Pennsylvania to anchor defense procurement security.
Germany
VDM Metals anchors European supply chains through integrated powder metallurgy capabilities serving aerospace qualification pipelines. EU REACH chemical traceability mandates force material documentation upgrades across specialty alloy supply chains. The Ruhr industrial cluster concentrates vacuum arc remelting electrode manufacturing for turbine blade forgers.
Japan
METI coordinates national research consortia advancing JIS-standardized medium entropy alloy specifications for domestic manufacturing competitiveness. Osaka Titanium Technologies and Nippon Yakin Kogyo operate integrated titanium sponge-to-alloy production in the Kansai region. LNG infrastructure operators in Nagoya specify cryogenic-toughness grades for liquefaction train components.
China
SAMR enforces GB standards for structural materials deployed in civil infrastructure, creating divergent compliance pathways for multinational producers. State-owned steel groups invest in vacuum induction melting capacity for aerospace substitution programs. The Yangtze River Delta concentrates research consortia advancing computational alloy design platforms.
India
Ministry of Defence production-linked incentive schemes for aerospace materials create entry pathways for qualified foreign alloy producers establishing local melting partnerships. BIS certification requirements shape domestic specification development for structural grades. The Pune-Bengaluru aerospace corridor attracts joint venture proposals from specialty alloy producers.
Medium Entropy Alloys Market Competitive Landscape
Capacity expansion dominates the current landscape as specialty alloy producers invest in vacuum induction melting to capture defense procurement security. The vendor base concentrates around three strategic tiers: integrated primary melters with captive feedstock, powder metallurgy specialists serving additive manufacturing, and computational design firms accelerating alloy development cycles. Technology licensing agreements and strategic partnerships constitute the dominant competitive moves as firms seek to compress dual FAA-EASA qualification timelines.
Among U.S.-based integrated producers, Carpenter Technology Corporation and ATI Specialty Alloys and Components exemplify the vacuum induction melting archetype anchoring defense-grade supply security. VDM Metals represents the European powder metallurgy specialist tier competing through integrated capabilities that sustain aerospace qualification pipelines. QuesTek Innovations LLC occupies the computational design niche, differentiating via predictive phase stability platforms that accelerate alloy development without traditional empirical cycles.
| Leading Market Players |
|---|
| Carpenter Technology Corporation |
| ATI Specialty Alloys and Components |
| VDM Metals |
| Sandvik AB |
| Haynes International, Inc. |
| Hitachi Metals, Ltd. |
| QuesTek Innovations LLC |
| Osaka Titanium Technologies Co., Ltd. |
| Nippon Yakin Kogyo Co., Ltd. |
| Others |
Supply & Pricing Matrix
CALPHAD modeling talent concentration in the Yangtze River Delta and Pittsburgh corridors widens pricing-tier spreads between computational-design-enabled premium grades and commodity-melted standard alloys. Labor-cost differentials between these specialized metallurgy clusters and conventional stainless steel producing regions translate into three-tier pricing structure across premium, standard, and economy levels for medium entropy alloy procurement.
Pricing Analysis
Extended fatigue crack growth documentation bundled into aerospace-grade contracts commands 40-60% premiums over unbundled commercial-grade offerings lacking FAA-EASA certification support. Price differentiation rests on dual-certification status and vacuum induction melting provenance, with defense prime contractors showing lowest price sensitivity due to Pentagon sourcing mandates. Cost compression in standard-grade nickel-based feedstock is intensifying because London Metal Exchange volatility compresses margin predictability for long-term aerospace contracts. Spot-market buyers in automotive trial programs exhibit highest price sensitivity, forcing iron-based formulation substitutions.
Supply Chain Analysis
Freight costs for vacuum arc remelting electrodes from Ruhr cluster to North American turbine blade forgers add 8-12% landed cost premiums versus domestic German consumption. Geographic supply concentrates in Germany, the United States, and Japan for premium melting capacity, while China expands vacuum induction installations for civil infrastructure grades. Raw material dependencies draw from Canadian Class 1 nickel cathode, Japanese titanium sponge, and German high-purity cobalt. Single-source vulnerability clusters in premium electrode manufacturing. Distribution runs through qualified domestic melter networks mandated by defense procurement security protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum induction melting capacity scarcity across qualified domestic suppliers props pricing power for incumbent producers with captive Pennsylvania and Ruhr-based facilities. This supply-constrained structure rewards early certification investments and penalizes spot-market sourcing strategies.
For Market Incumbents: Cement dual-source vendor relationships with defense primes through parallel FAA-EASA documentation streams that lock out emerging computational-design competitors. Add vacuum arc remelting capacity in Germany to capture EU Green Deal circularity premiums while substituting single-crystal superalloy incumbents face thirty-year service data advantages in hot-section rotating components. Channel control through integrated powder metallurgy capabilities sustains aerospace qualification pipeline dominance.
For New Entrants and Emerging Players: Capture marine engineering procurement offices in Norway and Japan specifying titanium-based variants for LNG liquefaction train components where legacy stainless steel specifications face performance ceiling pressures. India's Ministry of Defence production-linked incentive schemes offer the most penetrable entry pathway through local melting joint ventures with Pune-Bengaluru aerospace corridor partners. Lead with additive manufacturing powder certification to bypass conventional forging minimums and compress qualification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with computational alloy design platforms given EASA Part 21J evolving requirements that lengthen commercialization pathways and reward predictive phase stability capabilities. Long-term viability favors firms integrating density functional theory with CALPHAD databases over commodity melters facing nickel feedstock volatility. Watch for harmonized international standards emergence as the inflection signal reducing redundant qualification costs and consolidating vendor panels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Nickel Feedstock | Captures Canadian mining corridor supply security for defense-grade alloy production. |
| Dual FAA-EASA Certification Investment | Compresses procurement cycles for tier-one turbine OEMs pre-qualifying domestic melting capacity. |
| Computational Materials Engineering Platform Development | Accelerates alloy development cycles without decade-long empirical metallurgy traditions. |
| Local Melting Partnership in India | Accesses Ministry of Defence production-linked incentive schemes for aerospace materials indigenization. |
| Integrated Powder Metallurgy Capability Expansion | Sustains European aerospace qualification pipelines through additive manufacturing convergence. |
Research Methodology
Document review covered EASA Part 21J design organization approval requirements, FAA airworthiness certification frameworks, EU REACH chemical traceability mandates, and JIS-standardized medium entropy alloy specifications, complemented by interviews with vacuum induction melting plant managers, aerospace tier-one procurement directors, defense prime contractor materials engineers, and CALPHAD modeling specialists. Secondary validation drew from SEC 10-K filings of specialty alloy producers, customs trade data for high-purity nickel cathode flows, and MMPDS mechanical property statistical bases. Bottom-up alloy-grade demand modeling triangulated against top-down aerospace and marine engineering capital expenditure projections.
Segmentation outputs across nickel-based, titanium-based, copper-based, and iron-based formulations were modeled over the projection horizon through analysis window spanning the full forecast period. CAGRs derived from correlated drivers including defense procurement mandate intensity, LNG infrastructure investment cycles, and computational metallurgy adoption curves. Industry-specific inputs incorporated vacuum induction melting capacity expansion schedules, dual-certification timeline compression rates, and additive manufacturing powder qualification pipeline data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to harmonized international standards emergence, London Metal Exchange nickel volatility, and computational metallurgy talent migration patterns. Forecasts reflect assumptions regarding Pentagon sourcing directive continuity, EASA documentation burden evolution, and REACH compliance framework stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Europe Green Steel Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
High Temperature Alloys Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Chromium Carbide Overlay Plate Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Green Steel Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Prepreg Market