
 Polyphenylene Ether (PPE) Alloy Market | 2026-2036
Polyphenylene Ether (PPE) Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenylene Ether (PPE) Alloy Market Analysis
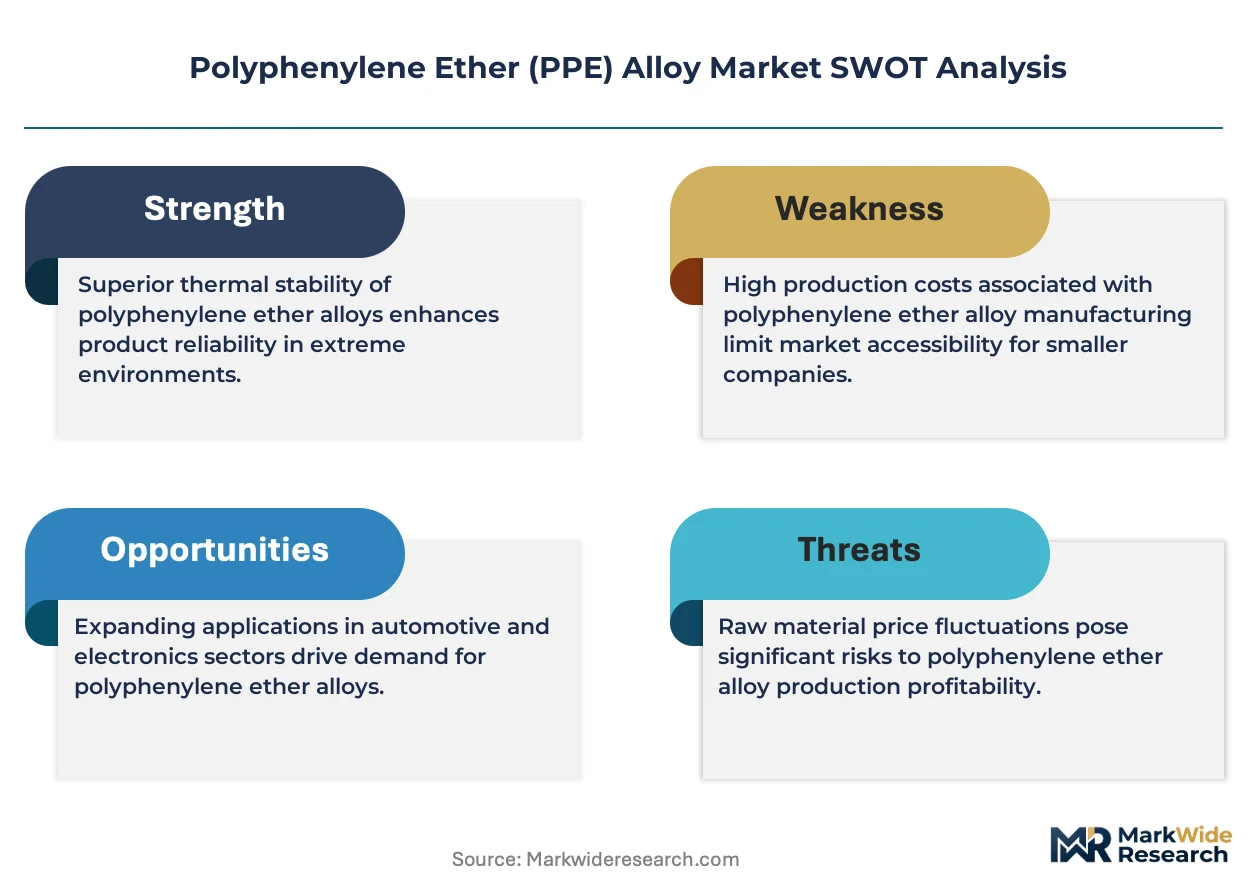
High-heat deflection requirements in electric vehicle battery enclosures is tilting formulation priorities toward glass-filled PPE alloys with enhanced thermal conductivity. SABIC leverages its vertically integrated resin portfolio to anchor supply contracts with tier-one automotive suppliers across North America and Asia. Asahi Kasei Corporation sustains technology leadership through proprietary graft-modification processes that improve compatibility with polyamide matrices. Mitsubishi Engineering-Plastics Corporation specializes in thin-wall molding grades that compete directly with conventional polyesters in connector applications.
Polyphenylene ether alloys combine the inherent flame resistance and low moisture absorption of PPE resin with the processability of polystyrene, polyamide, or polyolefin partners, typically achieving heat deflection temperatures between 80°C and 170°C depending on composition. These materials primarily serve industries requiring dimensional stability under thermal load combined with electrical insulation. Blends dominate current volume owing to established supply chains and broad injection molding compatibility, while compounds capture expanding margin pools as OEMs specify custom filler packages for electromagnetic shielding. Automotive Components represents the fastest-growing application dimension as under-hood electrification multiplies connector and housing unit volumes per vehicle platform.
REACH restrictions on halogenated flame retardants and EPA assessments of persistent organic pollutants are redirecting R&D investment toward phosphorus-based and metal hydroxide systems compatible with PPE chemistry. China's GB standards for passenger vehicle fire safety and MIIT mandates for new energy vehicle material traceability compound compliance complexity for multinational suppliers. Stakeholders must monitor regulatory divergence between EU chemical hazard classifications and Asia-Pacific performance-based standards when configuring regional product portfolios.
Market Dynamics
Automotive electrification is compressing thermal management specifications for battery enclosures, forcing material suppliers to reformulate PPE alloys for higher heat deflection temperatures while maintaining flame resistance and dimensional stability under electrical load.
Growth Catalysts
- China's dual carbon goals:Beijing's 2030 carbon peak mandate accelerates new energy vehicle production, multiplying demand for lightweight, thermally stable battery housings that PPE alloys uniquely satisfy.
- REACH halogen restrictions:ECHA's phased limitations on brominated flame retardants redirect electronics manufacturers toward phosphorus-stabilized PPE formulations with comparable fire safety ratings.
- Connector miniaturization:Thin-wall molding grades enable 0.3mm wall thickness in high-density electrical connectors, displacing conventional polyesters in telecommunications infrastructure.
Market Restraints
- Feedstock concentration:Purified 2,6-dimethylphenol monomer supply concentrates among three Asian chemical conglomerates, creating price volatility exposure for Western compounders.
- Processing temperature windows:PPE's high melt viscosity requires specialized twin-screw extrusion equipment, limiting toll compounding options for mid-scale processors.
- Polyamide competition:PA66 and PA6 grades with glass fiber reinforcement offer comparable heat deflection at lower raw material cost in non-electrical applications.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for domestic EV component manufacturing create first-mover positioning for PPE alloy suppliers establishing compounding capacity near Chennai and Pune.
- 5G base station deployment:Massive MIMO antenna housings require electromagnetic shielding grades that PPE-carbon fiber compounds deliver at 40% lower weight than aluminum die castings.
- EU battery passport mandates:CSRD-aligned material traceability requirements favor PPE alloys with established supply chain documentation over commodity engineering plastics.
Industry Challenges
- Color matching complexity:PPE's inherent amber tint complicates custom coloration for consumer electronics housings, requiring extended formulation cycles and specialized pigment packages.
- Moisture conditioning protocols:Pre-drying to 0.02% moisture content demands nitrogen-purged desiccant systems that smaller molders lack, restricting addressable customer base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenylene Ether (PPE) Alloy Market |
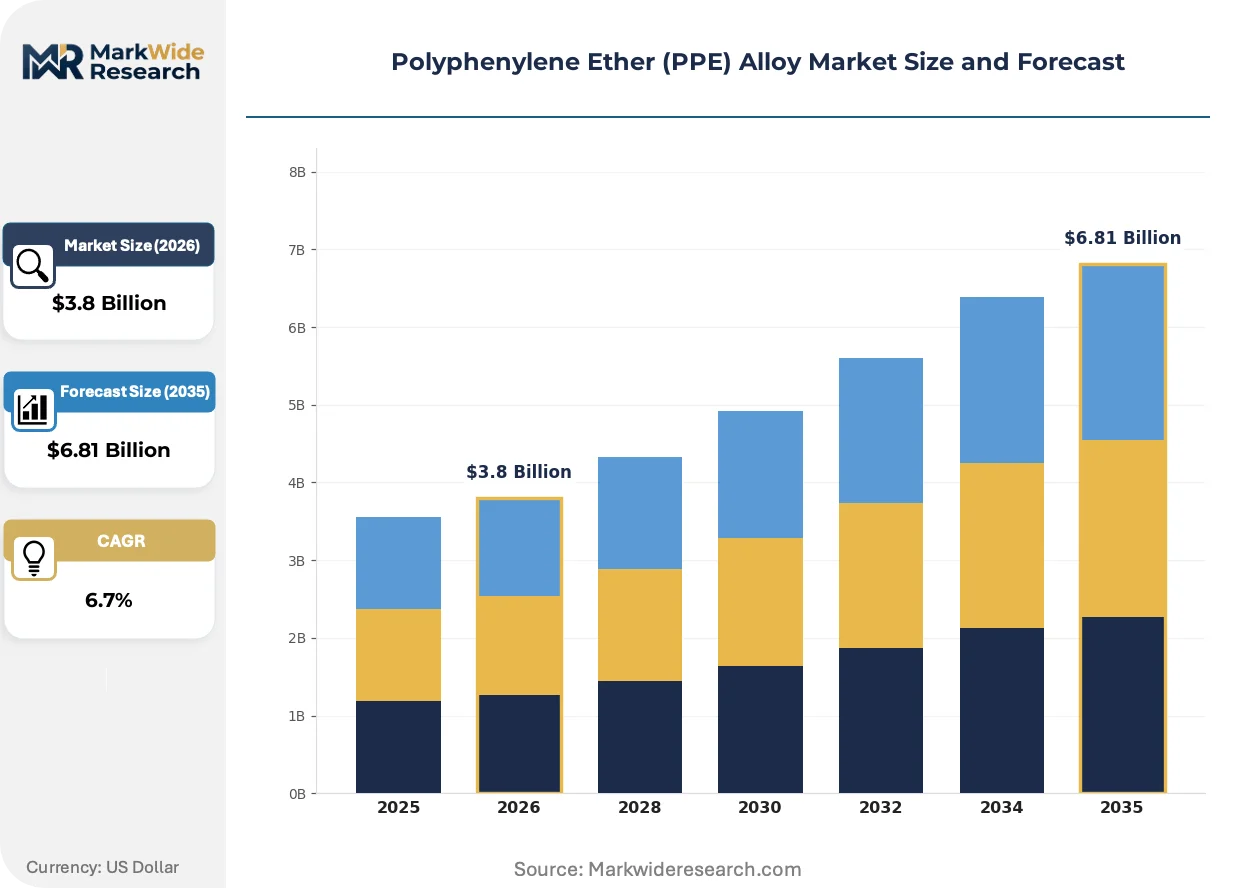
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
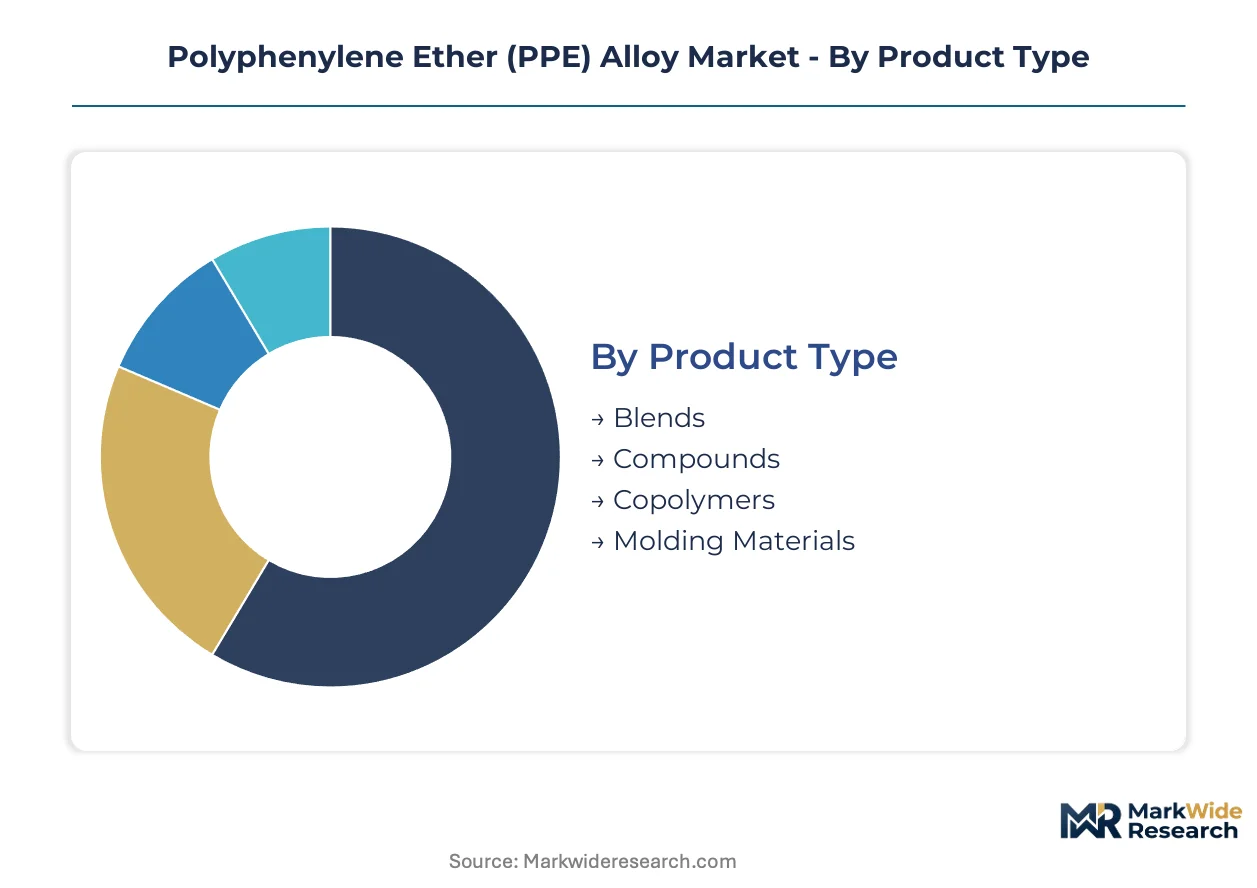
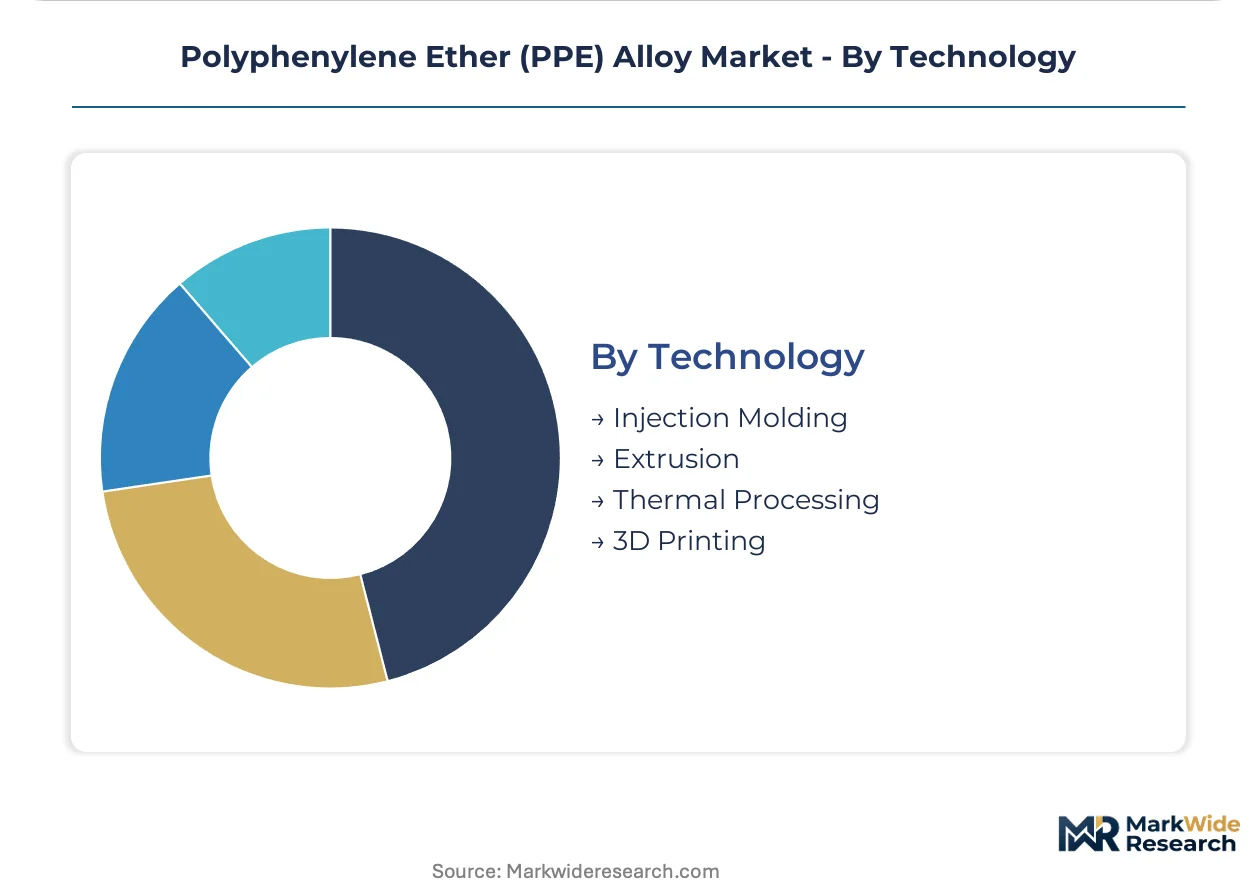
| Segmentation | Product Type: Blends, Compounds, Copolymers, Molding Materials Application: Electronics, Automotive Components, Industrial Machinery, Consumer Goods End User: Manufacturers, OEMs, Suppliers, Distributors Technology: Injection Molding, Extrusion, Thermal Processing, 3D Printing |
| Companies Covered | SABIC, Asahi Kasei Corporation, Mitsubishi Engineering-Plastics Corporation, Sumitomo Chemical, Mitsui Chemicals, Inc, LG Chem, RTP Company, LyondellBasell, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenylene Ether (PPE) Alloy Market Emerging Trajectories
Material science convergence with digital manufacturing is collapsing traditional formulation-to-production timelines, enabling lot-size-one customization previously uneconomical for engineering thermoplastics.
Real-time rheology monitoring during twin-screw compounding is digitizing quality assurance protocols. Automotive tier-one suppliers in Germany and Japan now specify continuous viscosity profiling rather than batch certificate testing. This compression of validation cycles allows just-in-time formulation adjustments that reduce scrap rates and accelerate new grade qualification.
REACH restrictions on persistent organic pollutants are forcing reformulation of legacy halogenated systems. Compounders must validate phosphorus-nitrogen synergists and metal hydroxide packages without sacrificing UL94 V-0 ratings at sub-1.6mm thickness. European appliance manufacturers are absorbing 8-12 month requalification delays as they transition existing product platforms.
Consolidated procurement by automotive electrification platforms is disintermediating traditional distribution channels. Battery OEMs in South Korea and China now contract directly with resin compounders for annual volume commitments, bypassing regional distributors. This channel compression rewards compounders with captive compounding assets and technical service capabilities in manufacturing corridor proximity.
Polyphenylene Ether (PPE) Alloy Market Segmentation
PPE alloy formulations diverge sharply in technical service requirements and qualification protocols. Each segment demands distinct compounding expertise and regulatory documentation, creating specialized vendor ecosystems that resist commoditization.
Product Type:
After-sales service intensity varies dramatically across product categories, with custom compounds requiring sustained technical support while commodity blends operate through distributor self-service models.
- Blends:Physical combinations of PPE with polystyrene or polyamide achieve heat deflection temperatures of 80°C to 140°C through established twin-screw extrusion. Automotive under-hood connectors in Stuttgart and Detroit manufacturing corridors concentrate demand for these cost-optimized formulations as OEMs balance thermal performance against material cost targets.
- Compounds:Engineered formulations incorporate glass fiber, carbon fiber, or mineral fillers to achieve heat deflection above 170°C and electromagnetic shielding properties. Battery enclosure manufacturers in South Korea and China specify these grades for electric vehicle platforms, driving formulation partnerships that extend through vehicle platform lifecycles.
- Copolymers:Chemically bonded architectures graft PPE onto polyamide backbones for enhanced phase compatibility.
- Molding Materials:Pre-optimized pellets with narrow viscosity windows target thin-wall electronics housings.
Blends hold the largest share; momentum sits with compounds.
Application:
Application-driven segmentation reveals diverging margin structures, with automotive electrification commanding premium pricing against commoditized consumer electronics volumes.
- Electronics:Connector housings and circuit breaker components exploit PPE's inherent flame resistance and dimensional stability under electrical load. Server rack manufacturers in Taiwan and telecommunications infrastructure deployers in Germany specify these grades for 5G equipment, though REACH halogen restrictions force ongoing reformulation cycles.
- Automotive Components:Battery enclosures, thermal management modules, and high-voltage connectors absorb the steepest expansion trajectory as electrification multiplies plastic content per vehicle. Chinese GB fire safety standards and MIIT material traceability mandates compound qualification complexity for multinational suppliers serving this segment.
- Industrial Machinery:Pump housings and valve components leverage chemical resistance in process equipment.
- Consumer Goods:Appliance housings compete primarily on cost against polypropylene and ABS alternatives.
Electronics retains volume leadership; automotive components is climbing the fastest.
End User:
Customer-type segmentation exposes channel compression dynamics, with direct compounder relationships displacing traditional distribution for high-specification applications.
- Manufacturers:Tier-one automotive suppliers and electronics contract manufacturers in East Asian manufacturing corridors around Shanghai and Seoul dominate procurement volume. These entities specify custom filler packages and demand captive compounding assets within 500-kilometer radius for just-in-time delivery.
- OEMs:Battery platform operators in South Korea and China now contract directly with resin compounders, bypassing regional distributors entirely. Annual volume commitments with technical service integration characterize these relationships.
- Suppliers:Tier-two and tier-three component fabricators rely on distributor inventory programs.
- Distributors:Regional stocking points serve mid-scale processors lacking nitrogen-purged desiccant systems for moisture conditioning.
Manufacturers command the greatest volume; OEMs are gaining share fastest through channel compression.
Technology:
Process technology segmentation tracks equipment specialization barriers, with injection molding accessibility contrasting against extrusion and additive manufacturing constraints.
- Injection Molding:Dominant forming method for connector housings and battery enclosures accommodates PPE's high melt viscosity through specialized screw designs and mold temperature control. Thin-wall capabilities down to 0.3mm wall thickness enable telecommunications infrastructure miniaturization.
- Extrusion:Profile and sheet production for industrial equipment housings requires precise temperature window control.
- Thermal Processing:Annealing and stress-relief protocols stabilize dimensions for precision electrical components.
- 3D Printing:Emerging filament and powder bed fusion methods for prototyping and low-volume tooling.
Injection molding holds the largest share; 3D printing shows the steepest expansion trajectory from minimal base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports specialized PPE compounds to battery manufacturers in Germany and the United States, establishing the dominant trade corridor for high-heat deflection grades serving electric vehicle platforms.
China
Beijing's dual carbon goals and MIIT mandates for new energy vehicle material traceability accelerate domestic PPE alloy consumption. GB standards for passenger vehicle fire safety compound compliance requirements for multinational suppliers. Manufacturing corridors around Shanghai concentrate electronics and automotive OEM procurement, with compounders establishing captive assets within 500-kilometer radius for just-in-time delivery.
South Korea
Battery OEMs in Seoul and Busan contract directly with resin compounders for annual volume commitments, bypassing traditional distribution channels entirely. The country's national industrial regulator enforces strict material documentation protocols under CSRD-aligned traceability frameworks. Daegu-Gyeongbuk hosts specialized compounding facilities serving Hyundai-Kia electrification platforms with custom filler packages.
Germany
REACH restrictions on halogenated flame retardants redirect electronics manufacturers toward phosphorus-stabilized PPE formulations. ECHA's phased limitations force 8-12 month requalification cycles for appliance manufacturers transitioning existing product platforms. Stuttgart manufacturing corridors concentrate automotive under-hood connector demand as OEMs balance thermal performance against material cost targets.
United States
EPA assessments of persistent organic pollutants reshape R&D investment toward metal hydroxide systems compatible with PPE chemistry. NHTSA safety protocols for electric vehicle battery enclosures drive specification of glass-filled grades with enhanced thermal conductivity. Detroit-area tier-one suppliers anchor North American demand for cost-optimized blend formulations.
Japan
METI industrial standards for telecommunications infrastructure miniaturization enable 0.3mm wall thickness specifications in high-density electrical connectors. JIS certification requirements for flame resistance maintain technical barriers for imported compounds. Nagoya and Osaka manufacturing clusters specialize in thin-wall molding grades competing directly with conventional polyesters.
Polyphenylene Ether (PPE) Alloy Market Vendor Landscape
On the supply side, the industry is consolidating around compounders with captive resin production and technical service integration. Three Asian chemical conglomerates control purified 2,6-dimethylphenol monomer supply, creating tiered access to feedstock. Strategic archetypes include vertically integrated resin-to-compound operators, specialty graft-modification specialists, and regional toll compounders with distribution partnerships. Dominant competitive moves encompass backward integration into monomer production and geographic expansion through technical service centers in manufacturing corridor proximity.
Within the integrated-resin tier, SABIC and Asahi Kasei Corporation exemplify compounders leveraging upstream control over polymerization assets. Among engineering-plastics specialists, Mitsubishi Engineering-Plastics Corporation occupies a position emphasizing thin-wall molding expertise. These three entities anchor the premium formulation segment where qualification cycles extend through vehicle platform lifecycles and electromagnetic shielding specifications command pricing differentiation.
| Leading Market Players |
|---|
| SABIC |
| Asahi Kasei Corporation |
| Mitsubishi Engineering-Plastics Corporation |
| Sumitomo Chemical |
| Mitsui Chemicals, Inc |
| LG Chem |
| RTP Company |
| LyondellBasell |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Undercapacity in South Korean monomer production facilities is tightening feedstock availability and tilting supplier behavior toward long-term contract anchoring rather than spot-market participation. This utilization dynamic compresses pricing flexibility for Western compounders while rewarding Asian integrated producers with captive resin assets.
Pricing Analysis
Glass-filled compound grades command substantial premiums over unfilled blend formulations, with next-generation electromagnetic shielding variants priced above legacy flame-retardant tiers. Pricing stratifies across premium, standard, and economy tiers based on filler loading levels and UL94 certification grades. Cost compression in standard blends is intensifying because polyamide alternatives erode share in non-electrical automotive applications. Tier-two automotive suppliers exhibit highest price sensitivity, while battery OEMs in Seoul and Shanghai absorb premium positioning for traceability-assured compounds.
Supply Chain Analysis
Export-control scrutiny on advanced polymer synthesis equipment limits technology transfer to emerging compounders in India and Southeast Asia. Purified 2,6-dimethylphenol monomer supply concentrates in China, Japan, and South Korea, drawing from specialized phenol derivatives and methylation catalysts. Single-source vulnerability runs through the three Asian chemical conglomerates controlling upstream polymerization. Distribution runs through direct compounder relationships with tier-one automotive suppliers, displacing traditional regional distributors in high-specification segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and formulation partnerships are expanding faster than commodity resin volumes, creating durable recurring-revenue streams that compound annually with platform lifecycle extensions.
For Market Incumbents: Pre-empt polyamide displacement in automotive under-hood applications by accelerating phosphorus-based flame-retardant qualification cycles ahead of REACH enforcement deadlines. Backward integration into monomer production anchors margin control against feedstock volatility from Asian suppliers. Captive compounding assets within 500-kilometer radius of Shanghai and Stuttgart manufacturing corridors lock in just-in-time delivery commitments with electrification platforms. For New Entrants and Emerging Players: Build out toll-compounding capacity near Chennai and Pune to capture PLI scheme incentives for domestic EV component manufacturing in India. Thin-wall molding grades for 5G telecommunications infrastructure present the most penetrable white-space target, with qualification cycles shorter than automotive battery enclosures. Lead with electromagnetic shielding compounds for massive MIMO antenna housings, leveraging 40% weight savings against aluminum die castings as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with integrated technical service teams embedded in customer R&D facilities. Long-term viability over the next decade hinges on formulation partnership durability extending through vehicle platform lifecycles. Acquisition targets should prioritize graft-modification specialists with proprietary polyamide compatibility processes. Watch for MIIT mandates on material traceability tightening to EU-equivalent standards as the inflection signal for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | SABIC and Asahi Kasei anchor margin control against Asian feedstock volatility through captive polymerization assets. |
| Technical Service Center Expansion | Proximity compounding within 500-kilometer radius of Shanghai and Seoul satisfies just-in-time delivery requirements from battery OEMs. |
| Phosphorus-Based Flame Retardant Reformulation | ECHA REACH restrictions on brominated systems force 8-12 month requalification cycles that favor prepared compounders. |
| Electromagnetic Shielding Grade Development | PPE-carbon fiber compounds capture massive MIMO antenna housing specifications from 5G infrastructure deployers in Germany and Japan. |
| Direct OEM Contracting Bypass | Channel compression with Hyundai-Kia and Chinese battery platforms displaces distributor intermediaries in high-volume segments. |
Methodological Framework
Desk research of customs trade databases, chemical industry association filings, and regulatory submission precedents preceded structured interviews with PPE compounder technical directors, automotive tier-one procurement managers, and polymer distribution channel partners. Primary fieldwork validated formulation trends and qualification timelines against secondary sources including SEC 10-K disclosures from integrated resin producers and ECHA REACH restriction impact assessments. Bottom-up volume estimates from end-use application sizing triangulated against top-down market value reconstructions.
Fixed assumptions across the modeling period held automotive electrification penetration rates and regulatory phase-in schedules at announced trajectories while varying raw material cost inputs and regional capacity utilization rates. Segmentation dimensions modeled encompass product type hierarchy, application vertical, end-user channel archetype, and regional production cluster concentration. CAGRs derived from logistic curve fitting to observed adoption patterns in prior engineering thermoplastic transitions, with electric vehicle platform content-per-vehicle multiples and 5G infrastructure deployment schedules as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed chemical conglomerates would shift outcomes substantially. Material shifts in MIIT traceability mandate enforcement stringency or ECHA halogen restriction acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Global Metal Foams Market
Advanced Alloys
Aramid Prepreg Market
Advanced Alloys
India Shape Memory Alloy Market
Advanced Alloys
Nitinol Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
Magnesium Alloys Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Soft Magnetic Material for Electric Vehicle Market
Advanced Alloys
Global Aluminum Silicon Carbide (Alsic) Market
Advanced Alloys
Cermet Market
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Prepreg Market
Advanced Alloys
High Temperature Alloys Market