
 Europe Choline Chloride Market | 2026-2036
Europe Choline Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Choline Chloride Market Insights
EU F-Gas Regulation is hardening the cost-of-entry calculus for choline chloride producers serving refrigerant-adjacent industrial grades, forcing capital retooling across manufacturing networks. BASF SE leverages its Ludwigshafen integrated chemical complex to sustain captive trimethylamine supply for choline synthesis. Kemin Industries, Inc. anchors its European position through Antwerp-region distribution hubs serving Benelux feed compounders.
Europe choline chloride is a quaternary ammonium salt synthesized via trimethylamine hydrochloridation, typically supplied at 50-60% aqueous concentration or 70-75% dry powder for feed and industrial applications. The compound functions primarily as a methyl-group donor in animal metabolism and as a clay-stabilizing agent in oilfield drilling fluids. Feed-grade formulations dominate volume flows across the region, while pharmaceutical-grade specifications command concentrated margin pools due to stringent EMA impurity thresholds. Aquaculture applications represent the fastest-expanding demand channel, particularly in Norwegian and Scottish salmonid nutrition programs where choline requirements exceed terrestrial livestock thresholds.
EFSA evaluates choline additive safety for food-producing species, while REACH governs industrial-grade chemical registration and downstream-use communication across EU member states. The EU Green Deal's farm-to-fork targets are compressing synthetic additive tolerance levels, redirecting formulation investment toward purity-optimized grades. Stakeholders must monitor the interplay between ECHA substance evaluation timelines and FEFAC procurement standards to anticipate specification shifts before they cascade through contract structures.
Market Dynamics
EU F-Gas Regulation is forcing capital retooling across manufacturing networks, hardening the cost-of-entry calculus for choline chloride producers serving refrigerant-adjacent industrial grades. BASF SE leverages its Ludwigshafen integrated chemical complex to sustain captive trimethylamine supply for choline synthesis.
Growth Catalysts
- EFSA feed-additive evaluations:Tighter safety thresholds for food-producing species are accelerating reformulation toward purity-optimized grades across poultry and swine operations.
- Aquaculture nutrition programs:Norwegian and Scottish salmonid producers are expanding choline inclusion rates beyond terrestrial livestock thresholds.
- REACH registration compliance:Industrial-grade chemical registration is streamlining downstream-use communication and consolidating supplier bases.
Market Restraints
- Trimethylamine supply concentration:Captive production at major integrated chemical complexes limits third-party access to critical feedstock.
- F-Gas Regulation capital burden:Refrigerant-adjacent industrial grade producers face elevated retooling costs for process emissions compliance.
- Vegetable-based methyl donor substitutes:Betaine and methionine formulations are displacing choline in certain ruminant applications.
Strategic Opportunities
- Benelux distribution hub expansion:Antwerp-region logistics infrastructure offers consolidation points for compound feed manufacturers.
- EMA pharmaceutical-grade certification:Impurity thresholds for human applications command concentrated margin pools above feed-grade specifications.
- EU Green Deal farm-to-fork alignment:Synthetic additive tolerance compression redirects investment toward bio-based synthesis pathways.
Industry Challenges
- ECHA substance evaluation timeline uncertainty:REACH re-evaluation schedules create specification volatility that cascades through multi-year contract structures.
- Compound feed formulation expertise scarcity:Precision nutrition modeling for aquaculture species requires specialized metabolizable energy calculation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Choline Chloride Market |
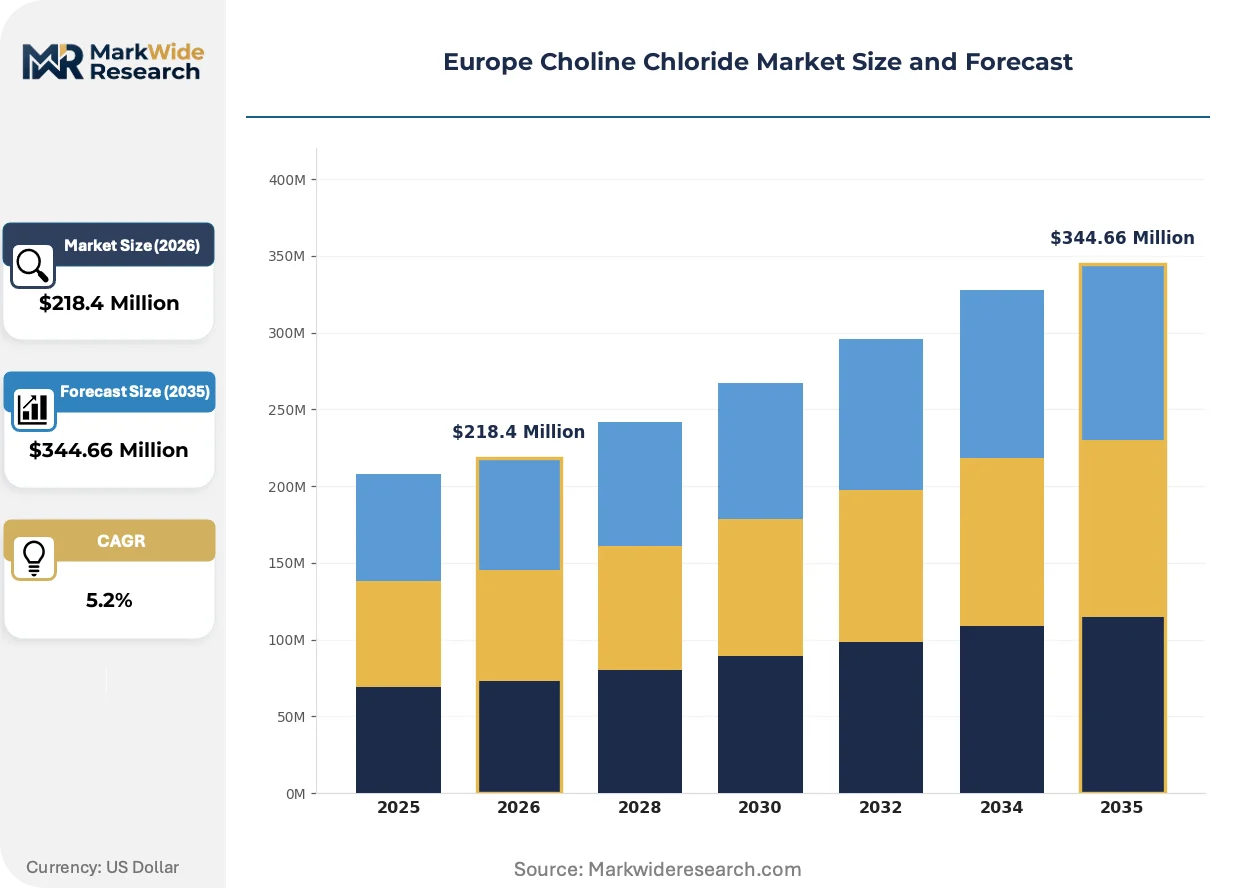
| Market Size in 2026 | $218.4 Million |
| Market Size in 2035 | $344.66 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Grade, Industrial Grade, Food Grade, Pharmaceutical Grade Application: Poultry Nutrition, Swine Nutrition, Pet Food, Aquaculture Packaging Type: Bags, Drums, Totes, Bulk End User: Agriculture, Food Industry, Pharmaceuticals, Animal Feed Manufacturers |
| Companies Covered | Kemin Industries, Inc., Nuproxa Switzerland Ltd., BASF SE, Pestell Nutrition Inc., Nouryon, Merck KGAA, Balchem Corporation, Algry Quimica S.L., Eastman Chemical Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Choline Chloride Market Trends and Innovations
Continuous flow reactor technology is automating batch process economics across European choline synthesis operations. German and Dutch producers are retrofitting legacy trimethylamine hydrochloridation trains to capture yield efficiency gains.
Microencapsulation technology for dry powder choline chloride is automating stability extension in premix formulations. French and Spanish feed compounders are adopting lipid-coated variants to reduce hygroscopic degradation during storage. The structural consequence is compressing working capital requirements for distributors handling high-humidity logistics corridors.
EU Green Deal farm-to-fork targets are compressing synthetic additive tolerance levels across member state feed regulations. EFSA safety re-evaluations for food-producing species are triggering reformulation investment cycles. Aquaculture nutrition programs in Norway and Scotland are responding fastest due to higher baseline choline inclusion rates.
Consolidated procurement through compound feed manufacturing clusters is displacing spot-market purchasing for choline chloride volumes. German, French, and Dutch buyers are negotiating multi-year framework agreements with purity-tiered pricing. This pattern concentrates supplier relationship investment in the Benelux distribution corridor.
Europe Choline Chloride Market Segmentation
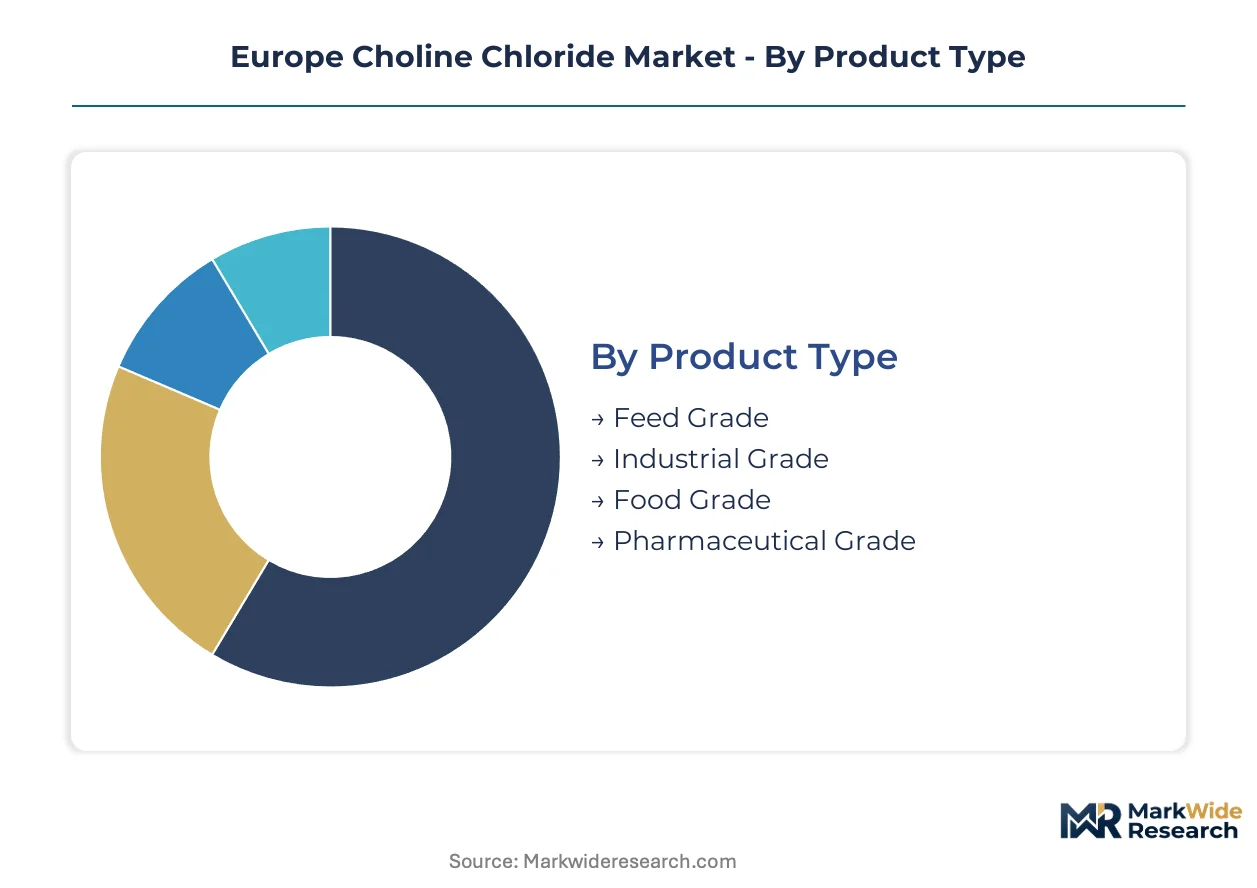
Choline chloride purchasing decisions across Europe diverge sharply by purity tier and end-use compliance burden. Specification requirements from EFSA, EMA, and REACH create distinct procurement workflows that segment supplier relationships and pricing structures.
Product Type:
Buyers prioritize purity certification tiers that align with downstream regulatory exposure and liability thresholds.
- Feed Grade:Formulated at 50-60% aqueous concentration or 70-75% dry powder for compound feed integration. German, French, and Dutch poultry and swine operations drive volume procurement through FEFAC-aligned specifications.
- Pharmaceutical Grade:Manufactured to EMA impurity thresholds for human therapeutic applications. This segment commands concentrated margin pools due to batch certification requirements and limited qualified supplier bases.
- Industrial Grade:Deployed as clay-stabilizing agents in oilfield drilling fluids. EU F-Gas Regulation compliance costs are compressing margins for refrigerant-adjacent specifications.
- Food Grade:Applied as nutritional fortifiers in processed foods. EFSA additive safety evaluations govern inclusion rate ceilings across member state food codes.
Feed grade leads on scale; pharmaceutical grade leads on momentum.
Application:
Species-specific metabolizable energy modeling determines inclusion rate precision and supplier technical service requirements.
- Aquaculture:Norwegian and Scottish salmonid producers exceed terrestrial livestock choline thresholds. Marine species nutrition programs represent the steepest expansion trajectory within European animal feed applications.
- Poultry Nutrition:Broiler and layer operations across Spain, Poland, and Italy standardize choline premix inclusion. EFSA feed-additive re-evaluations are accelerating purity-optimized grade adoption.
- Swine Nutrition:Sow and piglet formulations in Denmark and the Netherlands integrate choline for methyl donor support. Betaine substitution pressure is strongest in this segment.
- Pet Food:Premium companion animal nutrition in France and Germany incorporates choline for cognitive function positioning. Regulatory oversight remains lighter than food-producing species categories.
Poultry nutrition leads on scale; aquaculture leads on momentum.
Packaging Type:
Logistics infrastructure and compound feed manufacturing plant configurations dictate format selection across procurement contracts.
- Bulk:Tanker delivery to large-scale compound feed manufacturing clusters in Germany and the Netherlands. This format minimizes handling costs for high-volume poultry and swine operations.
- Bags:25kg multi-wall paper sacks for mid-tier feed compounders lacking pneumatic unloading systems. French and Spanish distributors favor this format for humidity-sensitive logistics corridors.
- Totes:Intermediate bulk containers serving aquaculture nutrition programs with seasonal demand fluctuations. Norwegian salmonid producers leverage this flexibility for just-in-time formulation.
- Drums:Steel or plastic containment for pharmaceutical-grade and food-grade specifications requiring contamination control. EMA-certified facilities mandate dedicated drum handling protocols.
Bulk leads on scale; totes lead on momentum.
End User:
Downstream regulatory jurisdiction shapes supplier qualification depth and contract duration preferences.
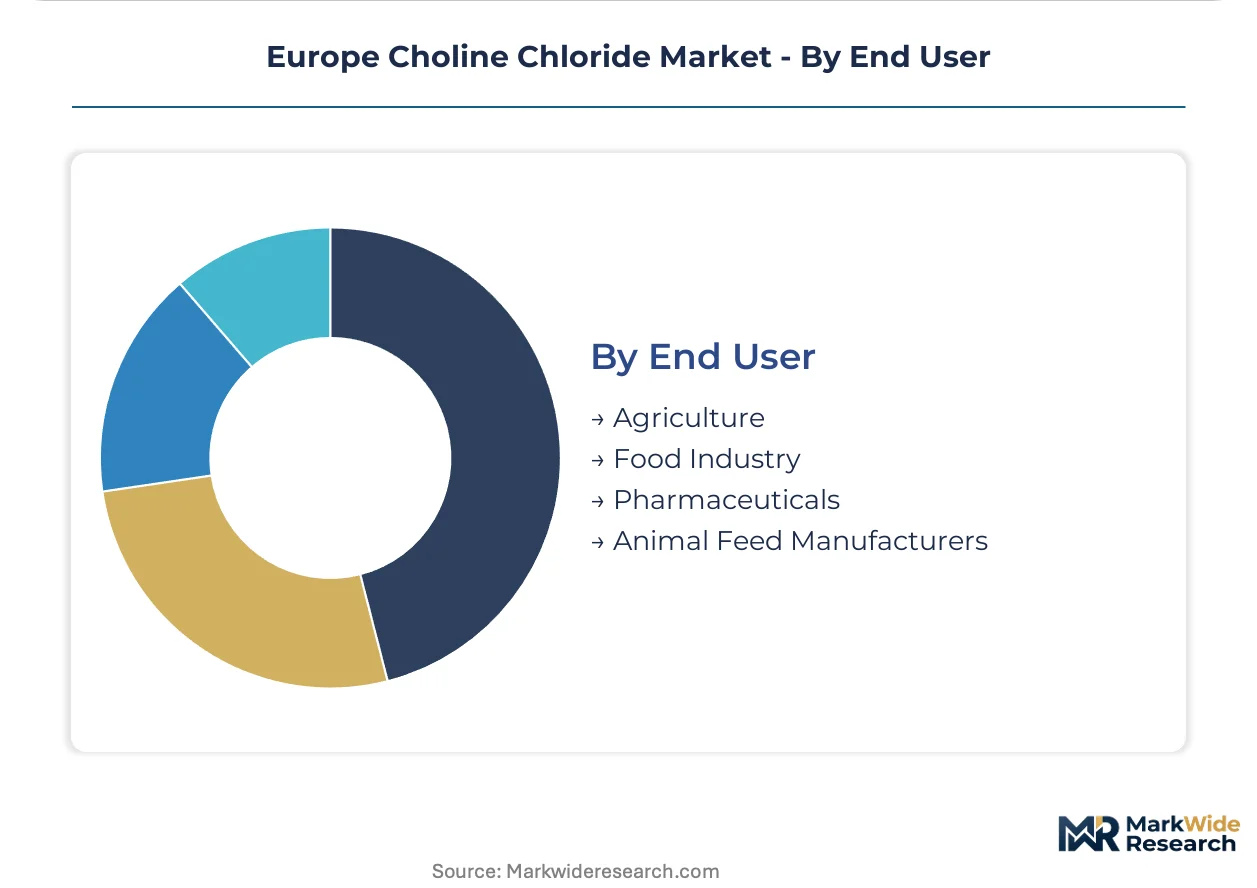
- Animal Feed Manufacturers:German, French, and Dutch compounders consolidate procurement through multi-year framework agreements. Purity-tiered pricing structures dominate relationship terms.
- Agriculture:Integrated poultry and swine operations in Poland and Spain source directly for on-farm premix preparation. REACH downstream-use communication obligations flow through these channels.
- Pharmaceuticals:EMA-registered drug manufacturers enforce impurity threshold documentation across batch records. Supplier audit cycles extend 18-24 months for qualification.
- Food Industry:Nutritional fortification applications in bakery and dairy segments. FSSAI-aligned importers in Southern Europe drive spot-market liquidity for this category.
Animal feed manufacturers lead on scale; pharmaceuticals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized compound feed formulation talent concentrates in the Benelux corridor and northern Germany, anchoring technical service capabilities for precision nutrition markets across the continent.
Germany
Poultry and swine operations in Lower Saxony and North Rhine-Westphalia drive bulk choline chloride procurement through FEFAC-aligned specifications. The EU F-Gas Regulation forces capital retooling at Ludwigshafen-area chemical complexes producing refrigerant-adjacent industrial grades. BASF SE leverages captive trimethylamine supply at its Ludwigshafen integrated site to sustain choline synthesis operations.
Netherlands
Large-scale compound feed manufacturing clusters in the Randstad region consolidate multi-year framework agreements with purity-tiered pricing structures. REACH downstream-use communication obligations flow through Rotterdam-Antwerp logistics corridors serving aquaculture nutrition programs. Kemin Industries anchors European distribution through Antwerp-region hubs serving Benelux feed compounders.
France
Broiler and layer operations across Brittany and Pays de la Loire standardize choline premix inclusion under EFSA feed-additive re-evaluations. Microencapsulation technology adoption accelerates among French feed compounders seeking lipid-coated variants for humidity-sensitive logistics. Premium companion animal nutrition in the Paris Basin incorporates choline for cognitive function positioning.
Norway
Salmonid producers in coastal fjord regions exceed terrestrial livestock choline thresholds, driving the steepest expansion trajectory within European animal feed applications. EFSA safety evaluations for food-producing species trigger reformulation investment cycles fastest here due to higher baseline inclusion rates. Just-in-time formulation patterns favor tote packaging for seasonal demand fluctuations.
Poland
Integrated poultry operations in Greater Poland and Lower Silesia source directly for on-farm premix preparation, bypassing compounder intermediaries. EU Green Deal farm-to-fork targets compress synthetic additive tolerance levels across national feed regulations. Spot-market liquidity persists for mid-tier operations lacking pneumatic unloading systems for bulk delivery.
Europe Choline Chloride Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive feedstock supply. Three tiers separate the vendor base: multinational diversified chemical groups controlling upstream trimethylamine synthesis, regional feed-additive specialists with formulation technical service capabilities, and industrial-grade suppliers facing margin compression from F-Gas compliance costs. Dominant competitive moves include backward integration into critical amine feedstocks and geographic expansion through Benelux distribution hub consolidation.
Among diversified chemical conglomerates, BASF SE exemplifies the integrated archetype through its Ludwigshafen complex operations. Kemin Industries, Inc. represents the regional specialist tier with its Antwerp-region distribution infrastructure. Balchem Corporation occupies a position bridging industrial and feed-grade specifications. Merck KGAA anchors the pharmaceutical-grade certification tier with EMA-registered facilities requiring dedicated handling protocols.
| Leading Market Players |
|---|
| Kemin Industries, Inc. |
| Nuproxa Switzerland Ltd. |
| BASF SE |
| Pestell Nutrition Inc. |
| Nouryon |
| Merck KGAA |
| Balchem Corporation |
| Algry Quimica S.L. |
| Eastman Chemical Company |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap feed additive specialists anchor supply discipline across the Benelux corridor, translating captive distribution relationships into pricing power that resists spot-market volatility. Their ownership structure prioritizes long-term contract stability over quarterly margin extraction, compressing working capital cycles for downstream compound feed manufacturers.
Pricing Analysis
Bundled technical service contracts separate premium-tier suppliers from unbundled commodity traders in European choline chloride procurement. Three-tier pricing structure across pharmaceutical, feed, and industrial grades reflects EMA certification burden, FEFAC alignment depth, and F-Gas compliance cost pass-through respectively. Pricing pressure stems from betaine substitution in swine nutrition, tightening margins for standard feed-grade specifications. Mid-tier poultry compounders exhibit highest price sensitivity due to volume volatility and limited pneumatic unloading infrastructure.
Supply Chain Analysis
Freight cost differentials between bulk tanker and bagged delivery formats concentrate procurement decisions around Rotterdam-Antwerp logistics hubs. Manufacturing draws from Germany, the Netherlands, and Belgium for trimethylamine feedstock and final synthesis. Raw material dependencies include ethylene oxide, hydrochloric acid, and methylamine intermediates. Single-source vulnerability at Ludwigshafen-area chemical complexes elevates supply risk for refrigerant-adjacent industrial grades. Distribution runs through compound feed manufacturing clusters with multi-year framework agreements displacing spot-market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe choline chloride functions as a stable compounder anchored by EFSA-mandated reformulation cycles that perpetuate demand for purity-optimized grades. Regulatory compression of synthetic additive tolerance levels under EU Green Deal targets sustains steady investment flows across the value chain.
For Market Incumbents: Deepen backward integration into trimethylamine supply to neutralize feedstock concentration risk at Ludwigshafen and Antwerp chemical complexes. Expand microencapsulation capacity in humidity-sensitive logistics corridors to defend margin position against lipid-coated variant substitution. Prioritize EMA pharmaceutical-grade certification investment to capture concentrated margin pools above feed-grade specifications. For New Entrants and Emerging Players: E-commerce platform procurement channels offer low-friction entry points for mid-tier aquaculture nutrition programs in Norway and Scotland. Target tote-packaged seasonal demand from salmonid producers lacking bulk unloading infrastructure. Pursue white-label formulation partnerships with French and Spanish feed compounders seeking humidity-stable premix variants. For Investors and Strategic Acquirers: Valuations sit cheapest among industrial-grade suppliers facing F-Gas Regulation capital burden and margin compression. Long-term viability favors integrated chemical conglomerates with captive amine synthesis and Benelux distribution infrastructure. Watch ECHA substance evaluation timeline announcements as inflection indicators for specification volatility cascading through contract structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trimethylamine | BASF SE's Ludwigshafen complex demonstrates captive feedstock security against third-party supply constraints. |
| Microencapsulation Capacity Expansion | French feed compounders adopt lipid-coated variants to reduce hygroscopic degradation in Atlantic coastal humidity corridors. |
| EMA Pharmaceutical-Grade Certification | Merck KGAA's EMA-registered facilities command batch certification premiums above standard feed-grade specifications. |
| Benelux Distribution Hub Consolidation | Kemin Industries' Antwerp-region infrastructure captures compound feed procurement concentration in the Randstad cluster. |
| Green Synthesis Pathway Investment | EU Green Deal farm-to-fork alignment redirects capital toward bio-based methyl donor production methods. |
Research Methodology
Direct dialogue with feed formulation technologists, compound feed procurement directors, EFSA regulatory affairs specialists, and aquaculture nutrition program managers grounded qualitative insights in operational reality. Secondary validation drew from customs/trade databases, FEFAC annual compound feed statistics, ECHA substance evaluation timelines, and SEC filings of listed chemical conglomerates. Bottom-up volume estimates from individual production facilities triangulated against top-down demand modeling across poultry, swine, and aquaculture species.
Bottom-up facility-level production capacity aggregated across German, Dutch, and Belgian chemical complexes, while top-down demand modeling applied species-specific metabolizable energy coefficients to livestock population forecasts. Segmentation dimensions included purity certification tier, end-use application, packaging format, and regional regulatory cluster. CAGRs derived from elasticity-adjusted price projections and volume growth assumptions across the projection horizon. Industry-specific inputs incorporated EFSA feed-additive re-evaluation schedules and salmonid nutrition program expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for continuous flow reactor automation or bio-based synthesis would alter the outlook for yield efficiency and cost structure. Forecasts reflect documented assumptions about regulatory timeline adherence and species-specific inclusion rate stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Viscosity Index Improvers Market
Additives
South America Concrete Admixtures Market
Additives
Europe UV Stabilizers Market
Additives
Grease Additives Market
Additives
Gelatin Peptones Market
Additives
Sodium Stearyl Fumarate Market
Additives
Calcium Stearate Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Oxygen Scavengers Market
Additives
Rheological Additives Market
Additives
Packaging Coating Additives Market
Additives
Shortstop Inhibitor Market
Additives
Europe Fuel Additives Market
Additives
Chitosan Powder Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Carboxymethylcellulose (CMC) Market