
 North America Surface Treatment Chemicals Market | 2026-2036
North America Surface Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surface Treatment Chemicals Market Analytics
Mexico's industrial corridor expansion is reconfiguring regional supply dynamics for conversion coating systems. DuPont sustains technology leadership in chromium-free pretreatment formulations across automotive assembly plants. Henkel AG & Co. KGaA anchors its position through direct technical service partnerships with Tier-1 metal stampers in the Midwest. PPG Industries competes on specification control with major aerospace primes requiring Nadcap-accredited chemical processing.
North America surface treatment chemicals encompass formulated solutions including acids, bases, solvents, and proprietary additives applied to metal, plastic, or composite substrates to modify surface properties for adhesion, corrosion resistance, or electrical conductivity; these formulations typically operate within controlled pH ranges and temperature parameters during immersion or spray application processes. Plating chemicals occupy the largest value share due to ongoing demand for decorative and functional electrodeposits in automotive trim and electronic connectors. Coating chemicals represent the fastest-expanding category as waterborne and powder-based alternatives displace solvent-borne systems under volatile organic compound constraints. Cleaning chemicals maintain stable demand across metal fabrication job shops where surface preparation quality directly determines subsequent coating adhesion performance.
EPA NESHAP standards for metal finishing operations mandate maximum achievable control technology for chromium and nickel emissions, forcing capital investment in closed-loop process systems and alternative chemistry formulations. OSHA permissible exposure limits for hexavalent chromium compel facility engineering controls and personal protective equipment protocols that elevate operating costs for traditional conversion coating lines. Canada's Chemicals Management Plan under Environment and Climate Change Canada requires substance screening for new surface treatment chemistries entering the market. Stakeholders must monitor evolving state-level green chemistry procurement policies that increasingly favor bio-based passivation treatments in public infrastructure projects.
Market Dynamics
EPA NESHAP standards for hexavalent chromium emissions are compressing the operational envelope for traditional conversion coating lines across US metal finishing facilities. Tier-1 automotive stampers now face capital allocation decisions between closed-loop retrofit investments and chemistry substitution programs.
Growth Catalysts
- Lightweight aluminum adoption:Automotive OEMs in Mexico are expanding pre-treatment capacity for aluminum body panels, pulling demand for zirconium-based conversion coatings that replace phosphate systems.
- REACH-aligned chemistry migration:Formulators are accelerating chromium-free pretreatment development to preempt regulatory alignment pressures across integrated North American supply chains.
- US Gulf Coast manufacturing clustering:Petrochemical corridor expansion is concentrating demand for corrosion-resistant coatings in downstream processing equipment fabrication.
Market Restraints
- Hexavalent chromium compliance costs:OSHA permissible exposure limits mandate engineering controls and personal protective equipment protocols that elevate operating costs for traditional conversion coating operations.
- Specialty chemical feedstock concentration:Fluorozirconate and fluorotitanate precursor supply concentrates among limited domestic producers, creating input cost volatility for pretreatment formulators.
- Waterborne system performance gaps:Solvent-borne coating alternatives retain adhesion superiority on certain alloy substrates, slowing displacement timelines in aerospace specification-controlled applications.
Strategic Opportunities
- Canadian infrastructure green procurement:Environment and Climate Change Canada procurement policies increasingly favor bio-based passivation treatments for public bridge and highway projects.
- Powder coating convergence:Hybrid chemistries combining powder deposition with in-line pretreatment are opening specification entry points at mid-tier metal fabrication job shops.
- Midwest technical service density:Direct formulation support partnerships with Tier-1 stampers create switching costs against commodity chemical distributors.
Industry Challenges
- Nadcap accreditation timelines:Aerospace chemical processing certification cycles extend 18-24 months, compressing revenue recognition for new facility investments.
- Legacy phosphate line stranded assets:Integrated steel and aluminum pretreatment on shared equipment creates chemistry incompatibility and wastewater treatment complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surface Treatment Chemicals Market |
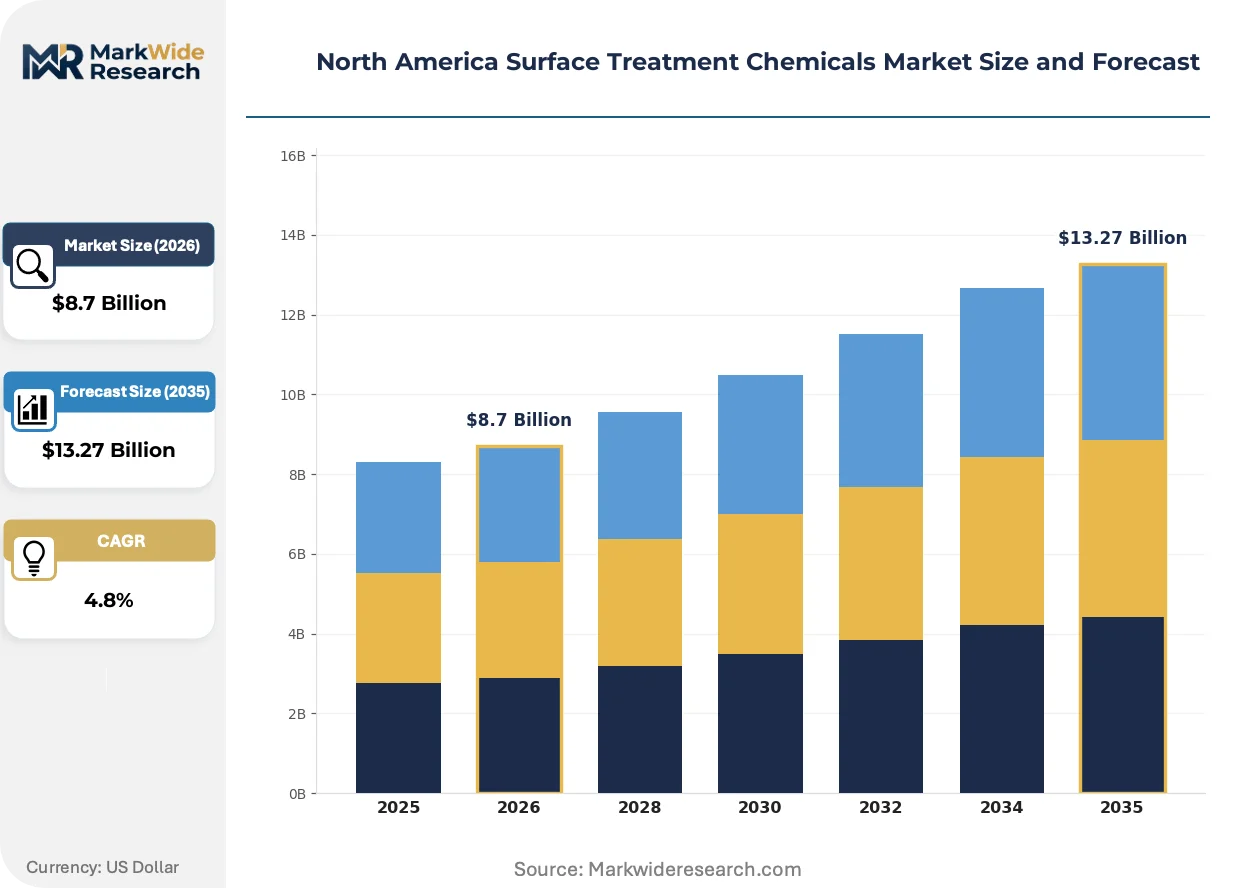
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plating Chemicals, Coating Chemicals, Cleaning Chemicals, Conversion Coatings Application: Aerospace, Automotive, Electronics, Metal Fabrication End User: OEMs, Service Providers, Tier-1 Suppliers, Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | DuPont, BASF SE, Henkel AG & Co. KGaA, PPG Industries Inc., Atotech, Akzo Nobel N.V., The Sherwin-Williams Company, Axalta Coating Systems, Element Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surface Treatment Chemicals Market Evolving Landscape
Process control architectures are digitizing surface treatment operations, replacing manual titration and bath monitoring with sensor-fed automation. This shift compresses chemistry consumption variability and enables predictive maintenance models for continuous processing lines.
Closed-loop rinse water recovery technology is digitizing resource efficiency metrics for metal finishing operations. Tier-1 automotive assembly plants are adopting these systems at accelerated pace to meet corporate sustainability targets. The technology is digitizing total cost of ownership calculations, repositioning capital-intensive water treatment as operational savings rather than compliance burden.
EPA NESHAP maximum achievable control technology mandates are forcing emission capture system retrofits across chromium plating facilities. Metal finishers in the US Midwest and Southeast are prioritizing fume suppressant chemistry substitutions over full enclosure investments. The regulation is compressing the viable supplier base to formulators with proven alternative conversion coating track records.
Specification bundling by major aerospace primes is consolidating approved chemical processing sources. Tier-2 and Tier-3 suppliers face escalating documentation and audit burdens to maintain Nadcap accreditation. This concentration is most visible in the US Southwest and Mexico aerospace manufacturing corridors where prime contractor consolidation has accelerated.
North America Surface Treatment Chemicals Market Segmentation
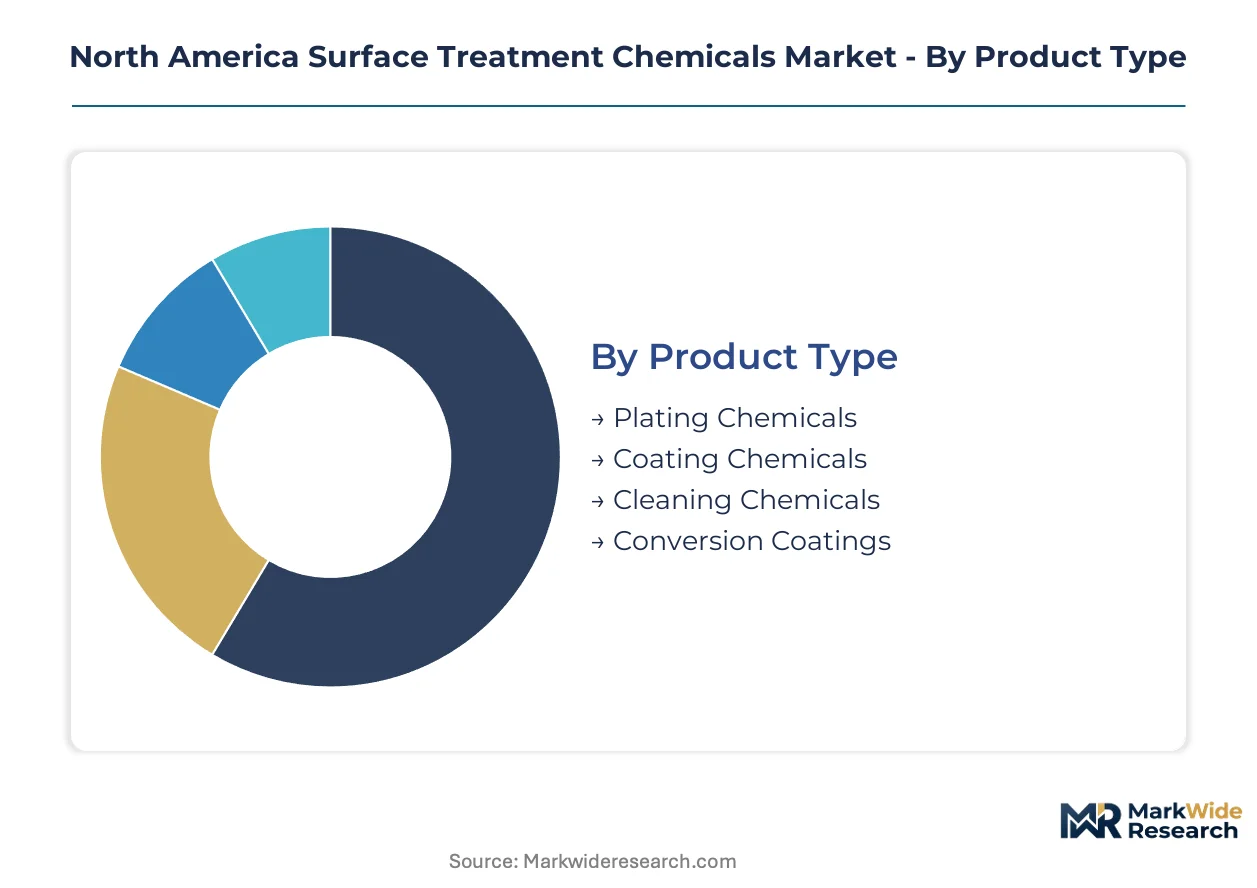
Segmentation in surface treatment chemicals reveals distinct procurement rhythms and specification requirements across product categories and customer tiers. Understanding these patterns enables formulators to align inventory positioning and technical service deployment with actual consumption velocity rather than aggregate demand assumptions.
Product Type:
Plating chemicals turn inventory fastest due to continuous bath replenishment cycles in high-volume decorative and functional electrodeposition lines. Conversion coatings move slowest as process control protocols and EPA NESHAP compliance documentation extend qualification timelines for new chemistry substitutions.
- Plating Chemicals:Formulated acid and alkaline electrolytes containing metal salts, brighteners, and grain refiners for electrodeposited nickel, chromium, copper, and zinc layers. Demand concentrates in US Midwest automotive trim suppliers and Mexican electronics connector manufacturers where decorative finishes and corrosion protection specifications remain non-negotiable.
- Coating Chemicals:Waterborne, solvent-borne, and powder-based resin systems including primers, topcoats, and specialty functional layers. The US Gulf Coast petrochemical corridor anchors demand as downstream equipment fabricators specify fluoropolymer and epoxy formulations for extreme chemical resistance.
- Cleaning Chemicals:Alkaline, acidic, and solvent-based degreasers and etchants for substrate preparation. Metal fabrication job shops across Ohio, Michigan, and Ontario represent the core consumption base.
- Conversion Coatings:Chromate, phosphate, and zirconium-based pretreatment films that enhance paint adhesion and corrosion resistance. Aerospace primes in California and Washington state drive qualification-intensive procurement through Nadcap-accredited processing specifications.
Plating chemicals dominate installed base. Coating chemicals are where expansion concentrates.
Application:
Cost tier segmentation separates specification-controlled aerospace applications from price-sensitive metal fabrication, with automotive and electronics occupying intermediate positions where performance premiums must justify measurable process efficiency gains.
- Aerospace:Nadcap-accredited chemical processing for airframe, engine, and landing gear components requiring fatigue-resistant coatings and corrosion protection. Washington state and California manufacturing clusters enforce the industry's most stringent chemistry qualification protocols.
- Automotive:Pre-treatment and coating systems for body-in-white, powertrain, and trim applications across aluminum, steel, and mixed-metal substrates. Mexican OEM assembly plants are pulling zirconium-based conversion coating demand as aluminum body panel adoption accelerates.
- Electronics:Precision plating and cleaning chemistries for printed circuit boards, connectors, and semiconductor packaging. Texas and California fabrication facilities concentrate consumption of high-purity formulations.
- Metal Fabrication:General-purpose cleaning, conversion coating, and protective finishing for architectural, industrial, and consumer products. Midwest job shops prioritize chemistry cost per square foot over specification complexity.
Automotive commands the largest absolute volume. Aerospace generates the highest margin per kilogram.
End User:
Customer type determines technical service intensity, with OEMs demanding embedded formulation support while service providers and Tier-1 suppliers prioritize supply security and price competitiveness.
- OEMs:Original equipment manufacturers with captive surface treatment operations or direct chemistry specification authority. Detroit-area automotive OEMs and Seattle-area aerospace primes dictate approved supplier lists that lock out commodity distributors.
- Service Providers:Independent metal finishing job shops serving multiple industries under contract processing arrangements. These operators in Ohio, Pennsylvania, and Illinois face acute pressure from EPA NESHAP compliance costs.
- Tier-1 Suppliers:Direct component suppliers to OEMs with specification delegation but limited chemistry autonomy. Mexican automotive stampers represent the fastest-expanding tier in this category.
- Manufacturers:Discrete manufacturers with in-house finishing for proprietary products rather than supply chain components. Canadian infrastructure fabricators are increasingly visible as green procurement policies reshape sourcing.
Tier-1 suppliers represent the deepest account concentration. Service providers are where switching costs erode fastest.
Distribution Channel:
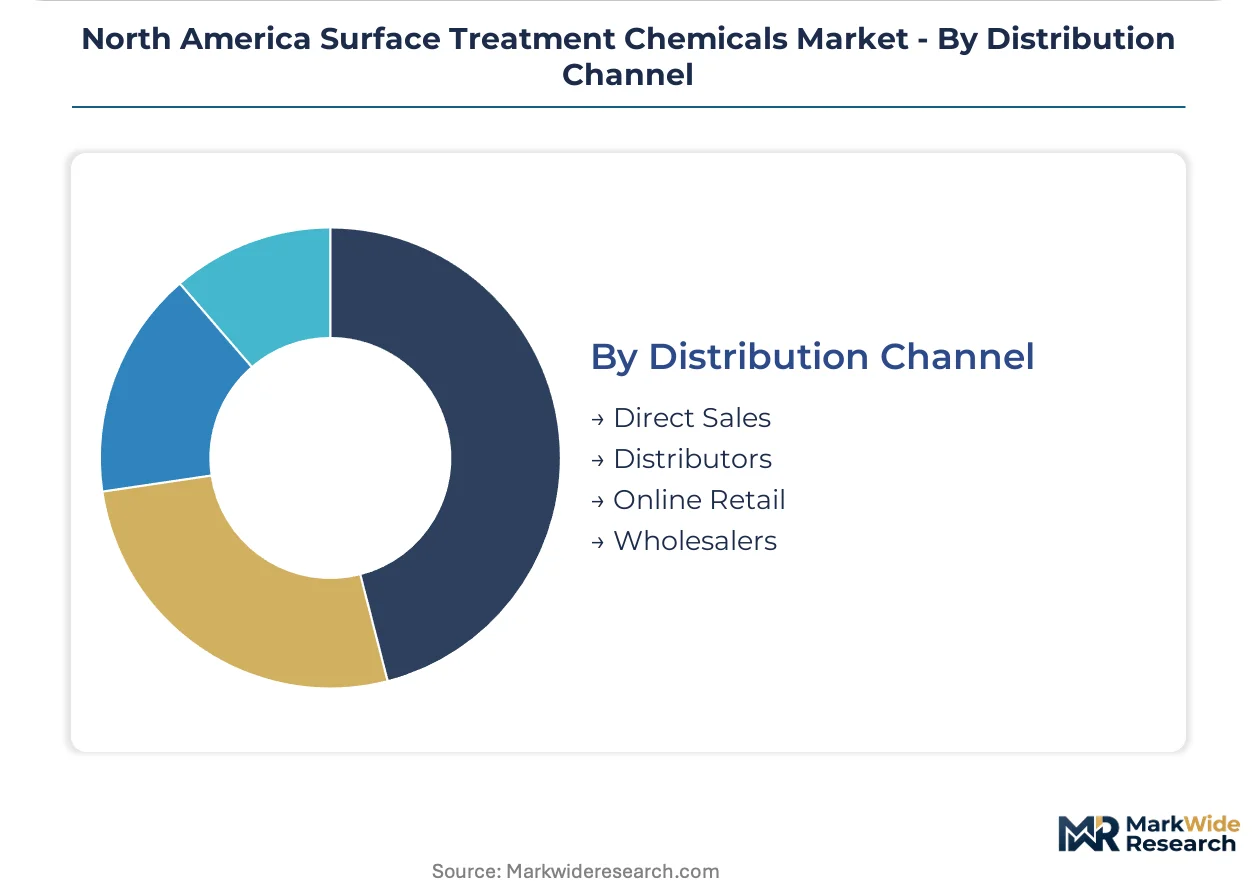
Supply concentration varies dramatically by channel, with direct sales relationships consolidating around formulation-intensive segments while distributors fragment across commodity cleaning and basic plating chemistries.
- Direct Sales:Manufacturer-to-customer relationships for proprietary formulations requiring technical service integration. Conversion coatings and aerospace-qualified plating systems move almost exclusively through this channel.
- Distributors:Regional chemical distributors with inventory positioning and local delivery capabilities. Standard cleaning chemicals and commodity plating salts flow through this channel across the US Midwest and Southeast.
- Online Retail:E-commerce platforms for standardized, documentation-light products. Small metal fabrication shops in secondary markets access basic formulations through this emerging channel.
- Wholesalers:Volume aggregators serving distributors rather than end users. This channel concentrates in petrochemical corridor logistics hubs.
Direct sales captures the highest value per transaction. Distributors handle the largest shipment volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America, with the United States driving specification-intensive aerospace and automotive demand, Mexico anchoring volume expansion through OEM assembly localization, and Canada prioritizing green procurement corridors for infrastructure applications.
United States
EPA NESHAP standards for hexavalent chromium emissions are forcing capital-intensive retrofits across Midwest metal finishing clusters. OSHA permissible exposure limits compound compliance burdens through mandated engineering controls and personal protective equipment protocols. Washington state and California aerospace manufacturing corridors enforce the continent's most stringent Nadcap accreditation requirements for chemical processing suppliers.
Mexico
Automotive OEM assembly plants in Nuevo León and the Bajío Region are expanding zirconium-based pretreatment capacity for lightweight aluminum body panels. Mexican environmental regulators are aligning emission standards with US EPA frameworks to maintain integrated supply chain access. Tier-1 metal stampers across Querétaro and Guanajuato represent the fastest-expanding customer tier for conversion coating formulators.
Canada
Environment and Climate Change Canada's Chemicals Management Plan requires substance screening for new surface treatment chemistries entering provincial markets. Federal infrastructure procurement policies increasingly specify bio-based passivation treatments for public bridge and highway projects. Ontario manufacturing clusters around Toronto and Hamilton concentrate demand from metal fabrication job shops serving US supply chains.
Texas Gulf Coast
Petrochemical corridor expansion is concentrating demand for corrosion-resistant fluoropolymer and epoxy coatings in downstream processing equipment fabrication. Texas Commission on Environmental Quality regulations govern volatile organic compound emissions from coating operations across Houston-area fabrication yards. The region's logistics infrastructure positions it as a distribution hub for formulated chemicals serving Southwestern US and Northern Mexican markets.
US Midwest
Detroit-area automotive OEMs dictate approved supplier lists that lock out commodity distributors from specification-controlled pretreatment programs. Ohio, Michigan, and Illinois metal fabrication job shops face acute pressure from EPA NESHAP compliance costs for legacy conversion coating lines. Direct technical service partnerships with Tier-1 stampers create switching costs against price-competitive chemical distributors.
North America Surface Treatment Chemicals Market Competitive Landscape
Capability concentration sits with specialty formulators holding aerospace and automotive qualifications; scale advantage sits with diversified chemical conglomerates serving commodity segments. The market structures around three tiers: Nadcap-accredited specialists serving aerospace primes, embedded technical service providers aligned with automotive OEMs, and regional distributors handling standard cleaning and plating chemistries. Dominant competitive moves include chemistry substitution programs to preempt regulatory alignment pressures and direct formulation support partnerships that create account stickiness.
Within the specialty formulator tier, DuPont and Henkel AG & Co. KGaA exemplify players with embedded technical service density across automotive assembly corridors. PPG Industries occupies a position tied to specification control with aerospace primes requiring accredited chemical processing. Among diversified chemical conglomerates, BASF SE represents the scale-driven archetype with broad formulation portfolios spanning multiple industrial verticals.
| Leading Market Players |
|---|
| DuPont |
| BASF SE |
| Henkel AG & Co. KGaA |
| PPG Industries Inc. |
| Atotech |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| Element Solutions Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in US fluorozirconate precursor production is tightening input cost control for pretreatment formulators while simultaneously elevating spot market premiums for automotive conversion coating contracts. This utilization squeeze propagates through to Tier-1 stampers facing binary choices between long-term chemistry lock-ins and exposure to volatile spot pricing for specialty feedstocks.
Pricing Analysis
Long-term offtake agreements dominate procurement for aerospace-qualified conversion coatings where Nadcap accreditation creates specification stickiness. Price differentiation rests on certification tier and volume scale, with prime-contractor-approved formulations commanding substantial premiums over commodity plating chemistries. Pricing pressure stems from EPA NESHAP compliance cost absorption demands cascading downstream from metal finishing job shops. Tier-1 automotive stampers exhibit highest price sensitivity due to OEM cost-down mandates, while aerospace primes prioritize supply security over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China concentrates risk for fluorinated precursor imports essential to zirconium-based pretreatment formulations. Domestic production draws from limited Texas and Louisiana chemical manufacturing clusters, while specialty additive sourcing rests on German and Japanese suppliers. Single-source vulnerability pervades fluorotitanate feedstock channels. Distribution runs through direct technical service relationships for specification-controlled segments, with regional distributors handling commodity cleaning and basic plating salts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as regulatory chemistry substitution programs splinter demand across multiple qualified suppliers rather than consolidating around legacy incumbents. EPA NESHAP alignment pressures and aluminum pretreatment conversion timelines are creating niche entry points for formulators with proven chromium-free track records.
For Market Incumbents: Build regulatory compliance moats through preemptive EPA NESHAP-aligned formulation portfolios that strand competitors with legacy chrome chemistry dependencies. Deepen embedded technical service density across Mexican automotive corridors to capture OEM aluminum pretreatment expansion. Prioritize backward integration into fluorozirconate precursor production to insulate margin structures from feedstock volatility. For New Entrants and Emerging Players: Pursue Canadian infrastructure green procurement corridors where bio-based passivation specifications remain undersupplied relative to evolving Environment and Climate Change Canada mandates. Target Midwest metal fabrication job shops facing acute EPA compliance cost pressure with closed-loop chemistry substitution programs. Lead with waterborne system performance guarantees backed by application engineering support to displace solvent-borne incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Nadcap-accredited specialists serving aerospace prime approved supplier lists. Long-term viability favors formulators with demonstrated chemistry substitution execution across regulatory windows. Acquisition focus should center on embedded technical service providers with automotive OEM specification control. Monitor EPA enforcement intensity signals as inflection indicator for accelerated chrome chemistry displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive fluorozirconate supply secures margin insulation against Texas Gulf Coast feedstock volatility. |
| Nadcap Accreditation Investment | Washington and California aerospace corridor access requires 18-24 month certification cycle completion. |
| Green Chemistry Formulation Development | Environment and Climate Change Canada procurement policies favor bio-based passivation for infrastructure. |
| Mexican Technical Service Expansion | Nuevo León and Bajío Region OEM aluminum pretreatment pull demands localized application support. |
| Closed-Loop Water Recovery Partnership | Tier-1 automotive sustainability targets compress total cost of ownership for integrated treatment systems. |
Research Methodology
Operator-level perspectives from plant managers at Midwest metal finishing facilities, procurement leads at Tier-1 automotive stampers, technical R&D directors at pretreatment formulators, and distribution channel partners anchored the qualitative base. Primary fieldwork combined with secondary validation drawing from EPA NESHAP regulatory filings, SEC 10-K disclosures by listed chemical conglomerates, American Chemistry Council sector reports, and customs trade data for fluorinated precursor imports. Bottom-up consumption modeling and top-down value chain sizing were triangulated to establish market boundaries.
Scenario-bracketing framed the analytical approach across the analysis window, with volume and value outputs reflecting segmented modeling by chemistry type, end-use industry, customer tier, and regional production cluster. CAGRs were derived from installed base turnover rates and substitution elasticity parameters. Forecast inputs incorporated EPA enforcement trajectory assumptions, Mexican automotive capacity expansion schedules, and aluminum body panel adoption curves.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, petrochemical feedstock pricing, or cross-border trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory alignment timelines and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Global Bleach Wipes Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Chemical Dust Suppressants Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Multifunctional Cleaner Market
Cleaning Chemicals
Low-VOC Cleaning Chemicals for Enclosed Workspaces Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market