
 Global Conveyor Oven Market | 2026-2036
Global Conveyor Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Global Conveyor Oven Market Intelligence
The EU F-Gas Regulation is decoupling European demand from gas-heated conveyor systems. Middleby Corporation leverages its vertical integration into thermal component manufacturing to sustain pricing power across belt-based product lines. Illinois Tool Works (ITW) anchors its position through R&D intensity in electric infrared modules. RATIONAL AG competes on precision temperature control for pharmaceutical drying applications.
A conveyor oven is a continuous thermal processing system that moves materials through heated zones via mechanized belt or chain transport, typically operating between 150°C and 300°C for curing, drying, or baking operations. Wire mesh conveyor systems dominate food processing installations due to airflow optimization and cleaning accessibility. Electric heating technology is displacing gas-fired units in electronics manufacturing as ISO 14001-certified facilities prioritize emissions reduction. Chain conveyor configurations occupy the highest margin pools in automotive component drying where load-bearing capacity commands premium pricing.
EPA emissions standards in the United States, REACH chemical compliance in Europe, and China's GB standards for industrial equipment safety collectively shape product design requirements and market access protocols. FDA food-contact surface regulations constrain belt material selection for North American food processing buyers. Stakeholders must monitor evolving carbon border adjustment mechanisms to anticipate retrofit demand cycles and heating technology substitution patterns.
Market Dynamics
Electric infrared heating modules are automating temperature control across pharmaceutical drying lines while EU F-Gas Regulation enforcement tightens compliance windows for gas-heated legacy installations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown schedule for hydrofluorocarbon refrigerants is forcing industrial bakeries toward electric heating retrofits, expanding replacement demand for belt-based thermal systems.
- Wire mesh conveyor systems:Food processing facilities prioritize airflow-optimized belt configurations that reduce cleaning downtime and extend operational cycles between maintenance.
- Quick-service restaurant chains:Automated baking infrastructure expansion across standardized franchise networks is driving volume procurement of continuous thermal processing equipment.
Market Restraints
- Nickel-chromium heating element costs:Volatility in specialty alloy feedstock prices compresses margin stability for electric infrared module manufacturers.
- German industrial baking corridor concentration:Supply-side clustering of precision engineering capability creates geographic vulnerability to regional energy price shocks.
- Gas-fired unit residual value:Secondary market liquidity for pre-2020 combustion-heated systems is collapsing under carbon accounting scrutiny, trapping capital in stranded assets.
Strategic Opportunities
- India:PLI scheme incentives for food processing infrastructure are opening tender windows for continuous baking systems in emerging cold chain hubs.
- Pharmaceutical contract manufacturing:Precision temperature control requirements for active pharmaceutical ingredient drying are creating specification premiums above food-grade equipment.
- ISO 14001-certified electronics facilities:Emissions reduction mandates are accelerating electric heating substitution in printed circuit board curing applications.
Industry Challenges
- Thermal systems integration:Retrofitting electric infrared modules into legacy gas-fired conveyor frames requires specialized mechanical engineering capacity that remains scarce.
- REACH chemical compliance documentation:Extended certification timelines for belt material substitutions are delaying product launches for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Conveyor Oven Market |
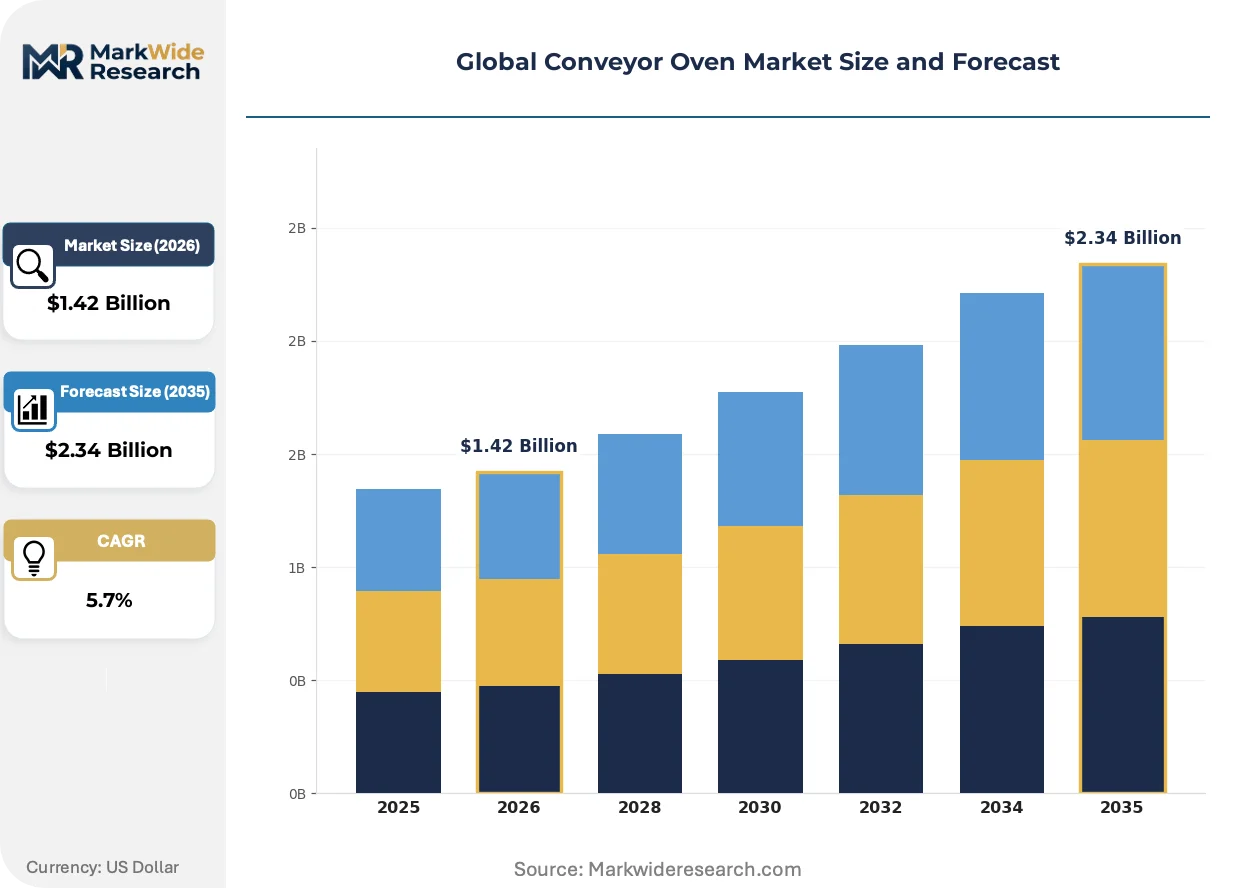
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.34 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Belt Conveyor, Chain Conveyor, Modular Belt Conveyor, Wire Mesh Conveyor, Roller Conveyor Heating Technology: Electric Heating, Gas Heating, Infrared Heating, Induction Heating, Steam Heating Application: Food Processing, Electronics Manufacturing, Automotive Component Drying, Pharmaceutical Drying, Textile Treatment End User Industry: Beverage Production, Aerospace Fabrication, Metalworking Plants, Chemical Processing Units, Packaging Facilities |
| Companies Covered | Middleby Corporation, Illinois Tool Works (ITW), Alto-Shaam, Welbilt, RATIONAL AG, Lincoln Foodservice Products, XLT Ovens, Moretti Forni, Davron Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Conveyor Oven Market Strategic Shifts & Innovations
Continuous thermal processing equipment is undergoing hardware-software convergence as sensor-embedded heating zones enable real-time temperature profiling. Three developments are compressing competitive differentiation timelines.
Infrared radiant heating arrays with embedded thermocouple feedback loops are automating zone-by-zone temperature calibration in pharmaceutical drying tunnels. Contract manufacturers of generic active ingredients are adopting these systems to reduce batch rejection rates. The technology is automating quality assurance labor out of high-value curing operations.
EPA emissions standards for industrial combustion equipment are tightening stack monitoring requirements for gas-fired conveyor ovens. Facility operators face accelerated depreciation schedules as compliance retrofit costs approach replacement thresholds. Food processing plants in California and Texas are prioritizing electric alternatives to avoid continuous emissions monitoring obligations.
Service contract unbundling is fragmenting buyer-supplier relationships in the quick-service restaurant segment. Chains are separating equipment procurement from maintenance agreements, compressing vendor switching costs. This pattern is most visible in standardized franchise networks across Florida and Illinois where multi-site operators aggregate purchasing leverage.
Global Conveyor Oven Market Segmentation
Conveyor oven procurement decisions pivot on thermal precision requirements, load-bearing specifications, and regulatory compliance burdens that vary sharply across end-use environments. Segmentation reveals where margin pools concentrate and which technology substitutions are compressing competitive differentiation timelines.
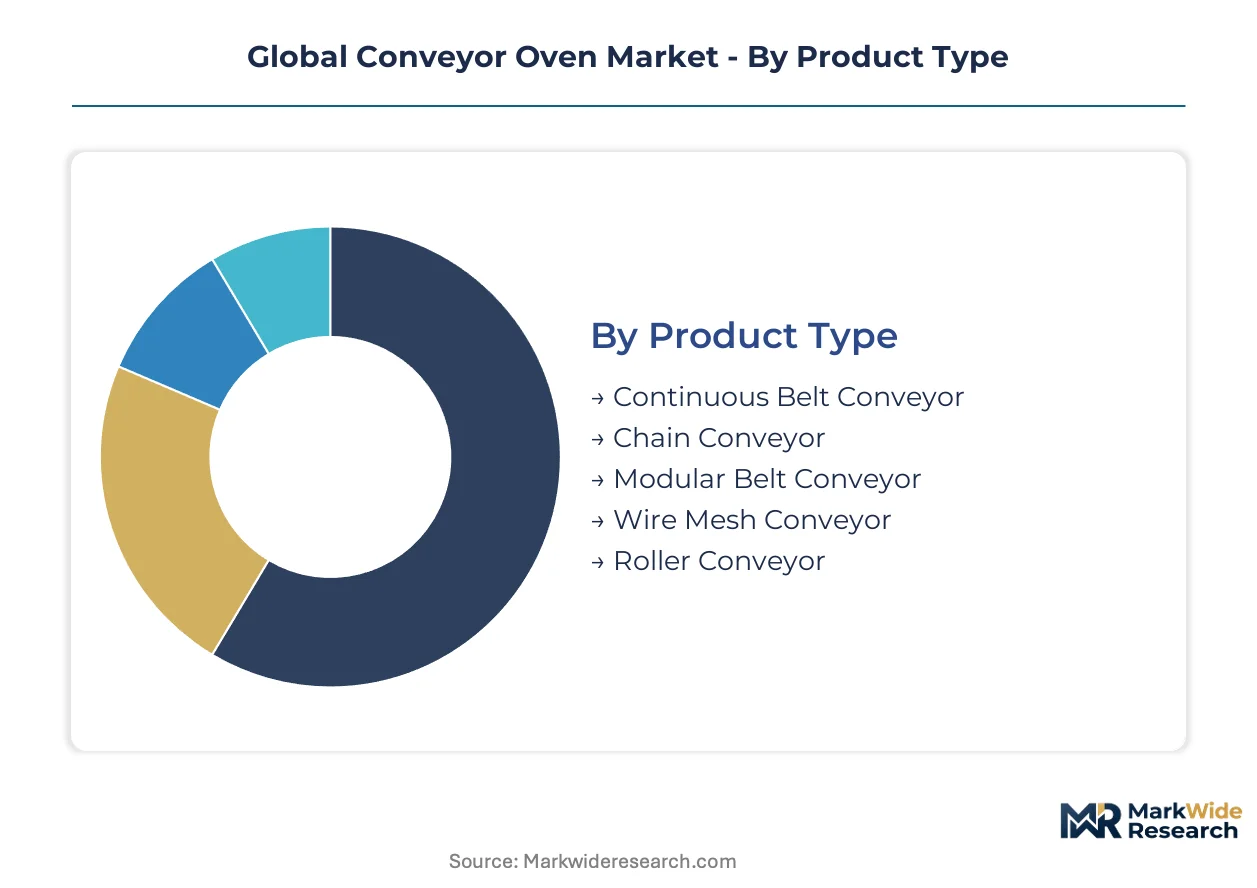
Product Type:
Belt configuration selection depends on airflow optimization needs, cleaning accessibility, and the mechanical load profiles of target applications.
- Wire Mesh Conveyor:Perforated metal belt construction maximizes thermal uniformity and simplifies sanitation protocols in food processing tunnels. Quick-service restaurant chains in Florida and Illinois specify these configurations to minimize downtime between baking cycles.
- Chain Conveyor:Heavy-duty link systems handle substantial mechanical loads in automotive component drying where part weight and thermal mass demand robust transport mechanisms. Germany's industrial baking corridor sources these for high-throughput precision operations.
- Continuous Belt Conveyor:Seamless loop designs suit electronics manufacturing where particulate contamination risks constrain belt joint configurations.
- Modular Belt Conveyor:Interlocking plastic or metal segments enable rapid section replacement without full belt removal, reducing maintenance windows in chemical processing environments.
- Roller Conveyor:Cylindrical bearing systems accommodate discrete palletized loads in packaging facilities where continuous belt contact would damage finished goods.
Wire mesh configurations lead on scale across food processing installations; chain conveyors lead on momentum as automotive electrification expands component drying demand.
Heating Technology:
Energy source selection now tracks carbon accounting obligations and the EU F-Gas Regulation's phasedown enforcement windows more than fuel cost arbitrage.
- Electric Heating:Resistive element systems deliver precise zone control for pharmaceutical drying where batch consistency determines regulatory approval. ISO 14001-certified electronics facilities in California and Texas are prioritizing these to sidestep EPA stack monitoring mandates.
- Infrared Heating:Radiant arrays with embedded thermocouple feedback automate temperature profiling in active pharmaceutical ingredient tunnels. Contract manufacturers adopt these systems to compress quality assurance labor and reduce rejection rates.
- Gas Heating:Combustion-based systems face collapsing secondary market liquidity as carbon border adjustments trap capital in stranded assets.
- Induction Heating:Electromagnetic field generation enables rapid thermal response for metalworking applications where ferrous substrate heating efficiency outweighs capital cost premiums.
- Steam Heating:Saturated vapor systems serve textile treatment facilities with existing boiler infrastructure, though efficiency constraints limit expansion.
Electric heating leads on scale through retrofit cycles; infrared modules are climbing the fastest as pharmaceutical specification premiums widen.
Application:
End-use thermal requirements determine belt speed ranges, zone count, and the sensor density needed for compliance documentation.
- Food Processing:Continuous baking and drying operations dominate volume demand, with FDA food-contact surface regulations constraining belt material selection for North American buyers.
- Pharmaceutical Drying:Precision temperature control for active pharmaceutical ingredients commands specification premiums above food-grade equipment, with EMA validation protocols driving hardware-software convergence.
- Electronics Manufacturing:Printed circuit board curing applications prioritize emissions reduction, accelerating electric heating substitution in ISO-certified facilities.
- Automotive Component Drying:Load-bearing capacity and thermal mass handling support premium pricing for chain conveyor configurations.
- Textile Treatment:Continuous dye fixation and finishing operations utilize lower-temperature steam systems with established regional supply chains.
Food processing leads on scale through quick-service restaurant automation; pharmaceutical drying is gaining share fastest as contract manufacturing expands.
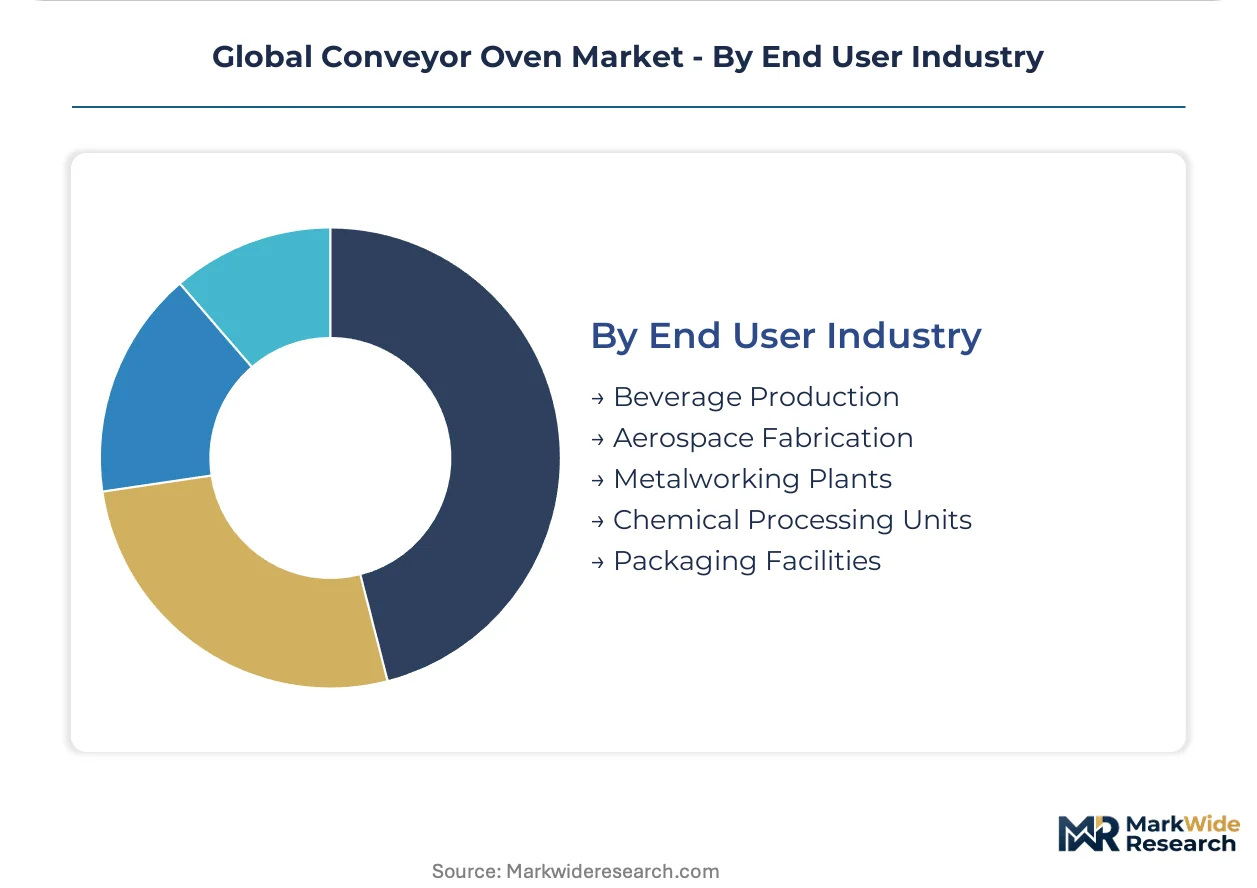
End User Industry:
Facility certification requirements and production scale determine procurement aggregation patterns and vendor relationship structures.
- Beverage Production:Pasteurization tunnel demand concentrates in emerging cold chain hubs where India's PLI scheme incentives are opening tender windows.
- Metalworking Plants:Heat treatment and surface finishing operations require robust thermal systems with extended duty cycles.
- Chemical Processing Units:Corrosive environment specifications drive modular belt adoption for rapid component replacement.
- Aerospace Fabrication:Composite curing applications demand precise thermal profiling with extensive documentation for airworthiness certification.
- Packaging Facilities:End-of-line sterilization and shrink-wrapping operations prioritize throughput over thermal precision.
Beverage production leads on momentum through infrastructure incentives; metalworking maintains scale through established replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters anchor European conveyor oven manufacturing capability. India's food processing infrastructure incentives are drawing capital toward emerging cold chain hubs. Chinese industrial equipment safety standards are reshaping import compliance protocols for thermal processing systems.
United States
Quick-service restaurant automation drives belt-based thermal system procurement across Florida and Illinois franchise networks. EPA stack monitoring mandates for industrial combustion equipment tighten compliance windows for gas-fired legacy installations. California electronics manufacturers prioritize electric heating retrofits to sidestep continuous emissions monitoring obligations.
Germany
Industrial baking corridor concentration supports high-throughput precision operations for automotive component drying applications. EU F-Gas Regulation enforcement accelerates electric heating technology transitions away from hydrofluorocarbon-dependent systems. Bavaria and Baden-Württemberg host precision engineering clusters supplying chain conveyor configurations for load-bearing thermal mass handling.
China
Electronics manufacturing scale drives demand for continuous belt configurations minimizing particulate contamination risks. GB standards for industrial equipment safety constrain product design requirements for market access. Yangtze River Delta and Pearl River Delta facilities prioritize electric heating substitution to align with dual carbon goals and ISO 14001 certification trends.
India
PLI scheme incentives for food processing infrastructure open tender windows for continuous baking systems in emerging cold chain hubs. FSSAI regulations constrain belt material selection for domestic food-contact applications. Maharashtra and Gujarat industrial zones concentrate beverage production pasteurization tunnel demand.
Japan
Pharmaceutical contract manufacturing expansion creates specification premiums for precision temperature control equipment. METI industrial policy supports hardware-software convergence in sensor-embedded heating zone development. Kanto and Kansai regions host active pharmaceutical ingredient drying operations adopting infrared radiant arrays with thermocouple feedback automation.
Global Conveyor Oven Market Key Industry Players
Capital-heavy producers compete with asset-light designers across conveyor oven manufacturing. The vendor base clusters around three strategic tiers: integrated thermal component manufacturers, specialized precision engineering houses, and regional fabrication specialists. Competitive differentiation hinges on backward integration into heating element supply, captive control over belt material sourcing, and in-house software development for temperature profiling systems. M&A activity concentrates on electric infrared module capabilities and pharmaceutical validation documentation assets.
Within the integrated manufacturing tier, Middleby Corporation and Illinois Tool Works occupy positions exemplifying upstream control over thermal component supply chains. RATIONAL AG anchors the precision engineering segment focused on pharmaceutical drying applications. Zhengzhou Shuli Machinery Co., Ltd. and Davron Technologies represent regional fabrication specialists serving geographic markets with customized belt configurations. These three archetypes—integrated conglomerates, precision specialists, and regional fabricators—capture distinct margin pools based on certification depth and vertical scope.
| Leading Market Players |
|---|
| Middleby Corporation |
| Illinois Tool Works (ITW) |
| Alto-Shaam |
| Welbilt |
| RATIONAL AG |
| Lincoln Foodservice Products |
| XLT Ovens |
| Moretti Forni |
| Davron Technologies |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation compliance deadlines are gating qualified supply for electric infrared modules and reserving premium-tier pricing access for vendors with EMA-validated pharmaceutical documentation. Carbon border adjustment mechanisms are simultaneously compressing residual value for gas-heated legacy systems and elevating procurement premiums for ISO 14001-certified configurations.
Pricing Analysis
Service contract unbundling now splits equipment procurement from maintenance agreements across quick-service restaurant chains, fragmenting vendor relationships and compressing switching costs. Pricing stratifies across pharmaceutical-grade precision systems, food-processing standardized units, and economy-tier regional fabrications based on certification depth and thermal control granularity. Cost compression in mid-tier electric heating modules is intensifying because nickel-chromium alloy feedstock volatility erodes margin stability. Quick-service restaurant franchise aggregators in Florida and Illinois exhibit highest price sensitivity; pharmaceutical contract manufacturers accept specification premiums for EMA-validated temperature profiling systems.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for food processing belt configurations in emerging cold chain hubs. Manufacturing gravity centers on Germany's precision engineering clusters for chain conveyor systems, China's Yangtze River Delta for continuous belt electronics configurations, and India's Maharashtra-Gujarat industrial zones for beverage pasteurization tunnels. Nickel-chromium heating elements, wire mesh belting alloys, and infrared radiant arrays constitute critical input dependencies. Single-source vulnerability concentrates in German specialty alloy suppliers serving pharmaceutical-grade thermal component demand. Distribution runs through OEM-direct channels for large-scale industrial buyers and regional fabrication specialists serving geographic aftermarket service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in electric heating retrofits where EU F-Gas Regulation enforcement eliminates gas-fired competition and pharmaceutical specification premiums widen on EMA validation requirements.
For Market Incumbents: Anticipate stranded asset risk in pre-2020 gas-heated installed bases by accelerating electric infrared module R&D intensity and capturing pharmaceutical validation documentation assets through targeted certification investment. Backward integration into nickel-chromium heating element supply hedges feedstock volatility exposure. Channel control through captive aftermarket service agreements defends against unbundling pressure from quick-service restaurant procurement aggregators. For New Entrants and Emerging Players: The premium-economy price-point gap in India's PLI scheme tender windows offers white-space entry for modular belt configurations serving beverage pasteurization tunnels in Maharashtra and Gujarat cold chain hubs. Pharmaceutical drying applications in Japan's Kanto region present penetrable specification premium capture for infrared radiant array specialists with thermocouple feedback automation capabilities. Go-to-market leverage rests on FSSAI-compliant belt material sourcing partnerships with domestic Indian fabricators. For Investors and Strategic Acquirers: Roll-up economics work for precision engineering specialists with EMA validation assets because pharmaceutical contract manufacturing expansion concentrates procurement leverage among specification-premium vendors. Five-to-ten-year viability favors electric heating technology portfolios over gas-fired legacy exposure. Target acquisition archetype: mid-cap regional fabricators with ISO 14001 certification pathways and installed base conversion potential. The signal to watch is carbon border adjustment mechanism implementation timing triggering accelerated depreciation cycles for combustion-heated systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heating Elements | Middleby Corporation's captive thermal component supply insulates margin stability from nickel-chromium alloy volatility. |
| Pharmaceutical Validation Documentation Investment | EMA-compliant temperature profiling systems command specification premiums above food-grade equipment in contract manufacturing. |
| Electric Infrared Module R&D Expansion | ITW's intensified development of zone-control arrays automates quality assurance labor from pharmaceutical drying tunnels. |
| Regional Fabrication Partnership in India | PLI scheme incentives for food processing infrastructure open tender windows for FSSAI-compliant belt configurations. |
| Aftermarket Service Agreement Bundling | Captive maintenance contracts defend vendor positioning against quick-service restaurant procurement unbundling trends. |
Research Approach
Direct dialogue with plant engineers at quick-service restaurant chains, pharmaceutical contract manufacturing operations directors, thermal systems procurement leads, and aftermarket service heads grounded qualitative assessment in operational reality. Secondary validation drew from EPA emissions compliance filings, EMA pharmaceutical equipment validation databases, EU F-Gas Regulation implementation schedules, and SEC 10-K disclosures from listed industrial equipment manufacturers. Bottom-up demand aggregation across belt configuration types and heating technology substitutions triangulated against top-down market sizing from trade flow analysis.
Segmented outputs across wire mesh, chain, continuous belt, modular belt, and roller conveyor configurations combined with electric, infrared, gas, induction, and steam heating technology splits. Food processing, pharmaceutical drying, electronics manufacturing, automotive component drying, and textile treatment end-use applications structured the demand model. CAGRs derived from replacement cycle analysis of gas-to-electric retrofit windows and infrastructure incentive program timelines. Nickel-chromium alloy price indices and carbon border adjustment mechanism implementation schedules fed industry-specific forecast sensitivity.
Caveats apply where EU F-Gas Regulation enforcement delays, nickel-chromium supply disruptions, or pharmaceutical contract manufacturing demand shifts could materially shift the outlook. Forecasts embed assumptions about retrofit cost thresholds and specification premium sustainability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Food Waste Disposers Market