
 Dry Ice Market | 2026-2036
Dry Ice Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Ice Market Analysis
EPA regulations under the AIM Act is consolidating the competitive landscape by raising compliance costs for synthetic refrigerant alternatives and elevating dry ice's cost competitiveness in temperature-controlled logistics. Linde plc leverages its integrated CO2 capture and liquefaction infrastructure to sustain margin advantages across North American distribution corridors. Airgas competes through dense branch networks that control last-mile delivery density for foodservice and healthcare accounts. Cold Jet specializes in precision pellet production systems that differentiate its output for blast cleaning and surface preparation applications.
Dry ice consists of solid carbon dioxide sublimating at minus 78.5 degrees Celsius, produced by compressing and cooling gaseous CO2 into liquid form before rapid expansion into snow that is hydraulically pressed into blocks, pellets, or custom shapes. Its primary commercial purpose centers on maintaining ultra-low temperatures without residual liquid during transit of perishables, pharmaceuticals, and biological specimens. Pellet formats lead volume in blast cleaning and medical shipping due to surface-area efficiency and dosing precision, while block configurations anchor food preservation and long-haul cold chain logistics where thermal mass governs performance. The custom shapes segment occupies niche positions in theatrical special effects and precision industrial fitting where geometry-specific sublimation rates matter.
FDA cold chain guidelines for biologics and the EPA's HFC phasedown framework jointly tighten product standards and expand addressable demand for pharmaceutical-grade and food-safe dry ice. OSHA workplace exposure limits for CO2 concentrations further shape handling protocols and ventilation requirements in production facilities and end-use environments. Stakeholders must monitor regulatory alignment between refrigerant transition timelines and cold chain infrastructure investments to capture shifting procurement patterns.
Market Dynamics
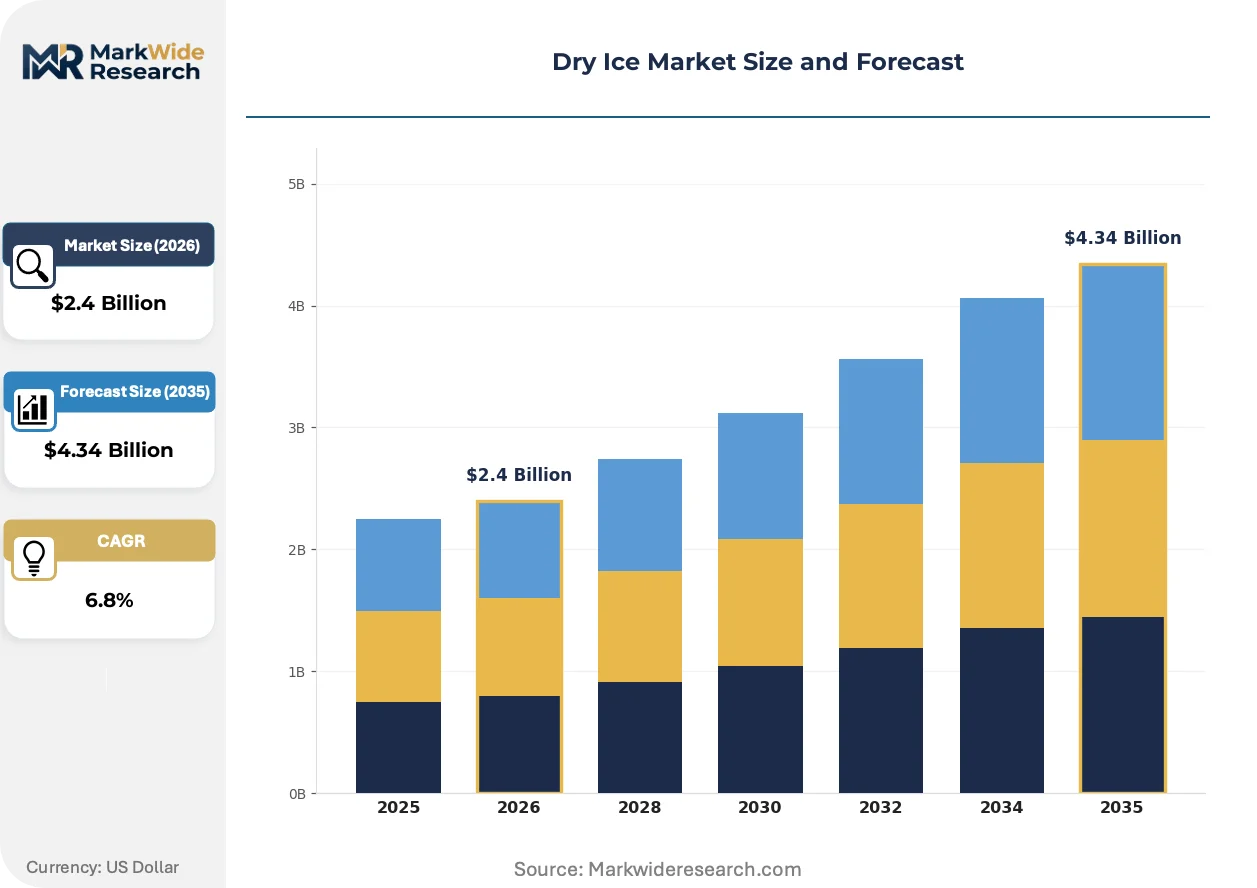
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is redirecting cold chain infrastructure investments toward CO2-based cooling systems and elevating dry ice's position in temperature-controlled logistics.
Growth Catalysts
- AIM Act Compliance:The EPA's hydrofluorocarbon refrigerant phasedown mandates industrial cold chain operators to adopt CO2-based alternatives, expanding dry ice procurement for food processing and pharmaceutical storage facilities.
- Biologics Cold Chain:FDA guidelines for vaccine and cell therapy transport mandate ultra-low temperature maintenance without residual liquids, driving pharmaceutical-grade dry ice consumption through specialized logistics networks.
- Pellet Production Scale-Up:Automated hydraulic pressing systems for high-density pellet manufacturing are reducing unit production costs and enabling blast cleaning contractors to substitute dry ice for solvent-based surface preparation methods.
Market Restraints
- Feedstock Concentration:Industrial CO2 supply concentrates near ammonia fertilizer plants and ethanol refineries in the US Gulf Coast, creating geographic supply vulnerability for Northeast and West Coast dry ice producers.
- Liquid Nitrogen Substitution:Cryogenic nitrogen systems achieve comparable ultra-low temperatures for certain pharmaceutical applications, pressuring dry ice pricing power in biologics transport segments.
- OSHA Exposure Limits:Workplace CO2 concentration thresholds mandate ventilation infrastructure investments that raise handling costs for small-scale foodservice and theatrical effects end-users.
Strategic Opportunities
- Cell and Gene Therapy Expansion:Personalized medicine manufacturing clusters in Massachusetts and North Carolina are creating demand for precision-dosed pellet formats tailored to small-batch biologics shipment protocols.
- Carbon Capture Integration:Direct air capture facilities producing food-grade CO2 streams offer dry ice producers backward integration into captive feedstock supply, decoupling from ammonia and ethanol market cycles.
- Last-Mile Cold Chain:Meal kit delivery networks and specialty pharmaceutical couriers are adopting portable dry ice containers as alternatives to mechanical refrigeration for same-day temperature-sensitive distribution.
Industry Challenges
- Cryogenic Handling Certification:OSHA and DOT training requirements for hazardous materials transport limit the available labor pool for pharmaceutical and biologics logistics operations, extending onboarding timelines.
- Production Asset Intensity:Hydraulic pellet presses and block extrusion systems require substantial capital deployment, constraining capacity expansion for regional dry ice suppliers serving fragmented foodservice accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Ice Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block, Pellets, Custom Shapes, Chips Application: Food Preservation, Shipping, Medical, Special Effects End User: Retail, Healthcare, Events, Industrial Packaging Type: Reusable Containers, Disposable Containers, Bulk Bags, Bag-in-Box |
| Companies Covered | Airgas, Cold Jet, Linde plc, Aquila Triventek, CryoCarb, Air Liquide, Continental Carbonic Products, Tripti Dry Ice Co, Air Products and Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Ice Market Emerging Trajectories
Automation and regulatory chemistry are compressing production economics and reshaping competitive positioning across the dry ice value chain. Three developments are actively restructuring how CO2 is captured, converted, and consumed.
Automated pellet classification systems using optical sorting and density sensors are unifying quality standards across pharmaceutical and food-grade output streams. Large-scale producers deploy these systems to certify sublimation rate consistency for FDA-regulated biologics shipments while repurposing off-spec material for industrial blast cleaning applications. This quality-tier unification is compressing price spreads between premium pharmaceutical and standard industrial grades.
The EPA's refrigerant management regulations and the EU F-Gas Regulation are synchronizing transatlantic pressure on synthetic refrigerant-dependent cold chain infrastructure. Food processors in California and Germany face parallel compliance deadlines that accelerate CO2-based system retrofits and expand addressable demand for dry ice as transitional and permanent cooling media. Pharmaceutical manufacturers with dual-continent operations are standardizing on dry ice protocols to simplify regulatory alignment.
Consolidated buying by national cold chain logistics providers is fragmenting regional distributor relationships that historically dominated foodservice and healthcare procurement. Large third-party logistics operators now contract directly with integrated CO2 producers for dedicated capacity, displacing independent dry ice distributors from high-volume pharmaceutical and frozen food accounts. This channel restructuring is most visible in the US Southeast, where vaccine distribution hubs and poultry processing clusters concentrate procurement leverage.
Dry Ice Market Segmentation
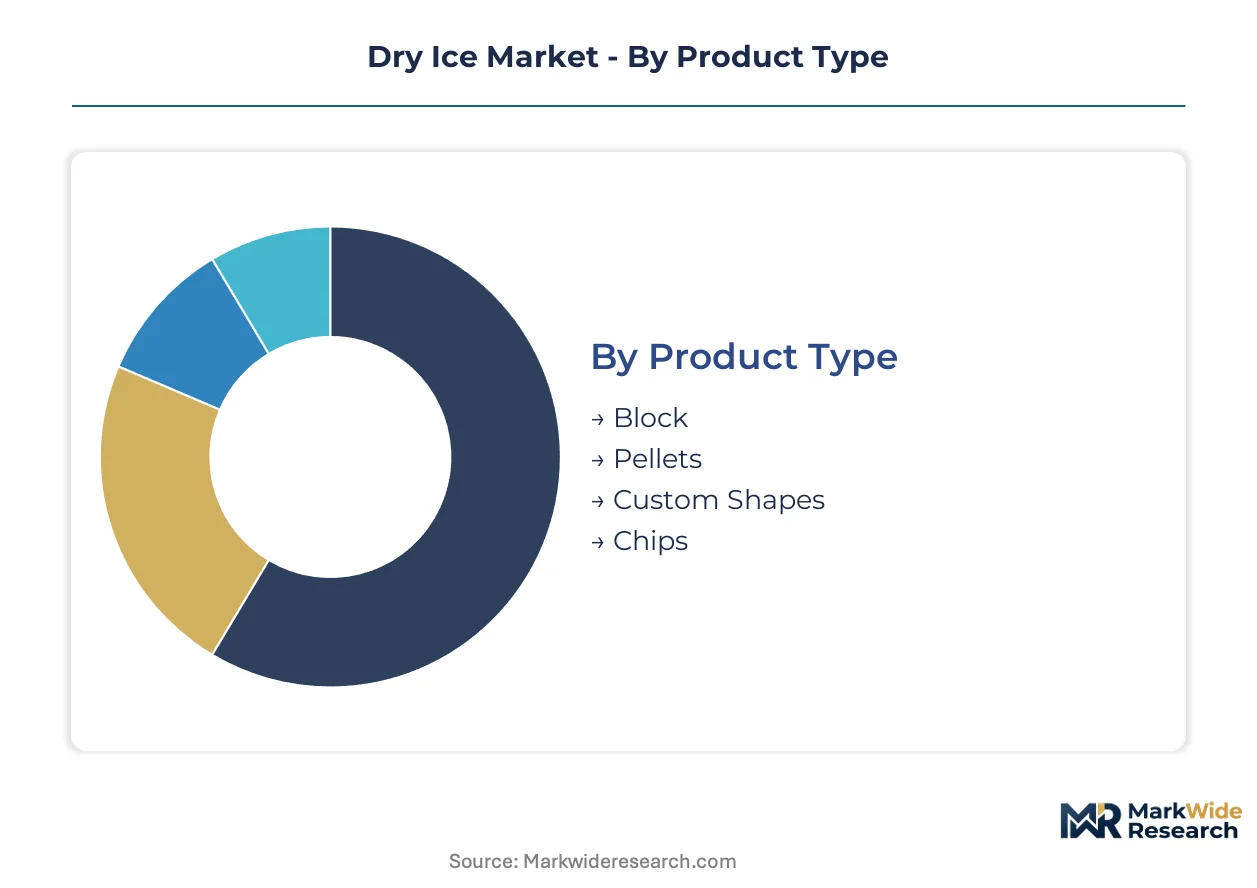
Product format specifications dictate thermal performance and handling economics across dry ice procurement decisions. Pharmaceutical cold chain operators, food processors, and industrial contractors each prioritize distinct physical configurations that align with temperature maintenance requirements, dosing precision, and sublimation rate control.
Product Type:
Physical form factor determines sublimation kinetics and end-use compatibility across temperature-controlled logistics.
- Pellets:High surface-area-to-mass ratio enables rapid cooling and precise dosing for blast cleaning operations and small-batch pharmaceutical shipments. FDA-regulated biologics transport in Massachusetts and North Carolina manufacturing clusters consumes pharmaceutical-grade pellet output for cell therapy distribution protocols.
- Block:Dense hydraulic pressing yields extended thermal mass for long-haul frozen food logistics and large-scale cold storage backup. Poultry processing facilities in the US Southeast and frozen food distribution hubs anchor procurement volume for block configurations.
- Custom Shapes:Geometry-specific pressing serves theatrical special effects and precision industrial fitting where controlled sublimation rates matter.
- Chips:Fragmented form factor supports rapid cooling applications and temporary surface chilling in foodservice environments.
Mature deployment sits with Block. Newer deployment is concentrated in Pellets.
Application:
Regulatory stringency and temperature requirements segment demand across commercial use cases.
- Shipping:Ultra-low temperature maintenance without residual liquid drives pharmaceutical-grade consumption for vaccine and biologic transport. EPA AIM Act compliance timelines accelerate CO2-based cooling adoption in temperature-controlled logistics networks.
- Food Preservation:Mechanical refrigeration backup and flash-freezing operations sustain volume in poultry processing and frozen food manufacturing clusters.
- Medical:Cell and gene therapy manufacturing protocols mandate precision-dosed formats for personalized medicine distribution.
- Special Effects:Theatrical fog generation and entertainment applications occupy niche demand positions with seasonal procurement patterns.
Food Preservation commands established volume. Shipping gains share fastest.
End User:
Customer scale and technical sophistication determine service requirements and contract structures.
- Healthcare:Hospital systems, specialty pharmacies, and biologics manufacturers require certified pharmaceutical-grade output with chain-of-custody documentation. OSHA cryogenic handling mandates and FDA cold chain guidelines shape procurement specifications and vendor qualification protocols.
- Industrial:Blast cleaning contractors and manufacturing facilities consume high-volume pellet output for surface preparation and in-process cooling.
- Retail:Grocery chains and foodservice operators procure block and chip formats for temporary refrigeration and display cooling.
- Events:Catering companies and entertainment producers generate intermittent demand for custom shapes and theatrical effects.
Industrial users anchor baseline capacity utilization. Healthcare drives premium pricing expansion.
Packaging Type:
Container economics and reuse cycles influence total cost of ownership for high-frequency versus intermittent users.
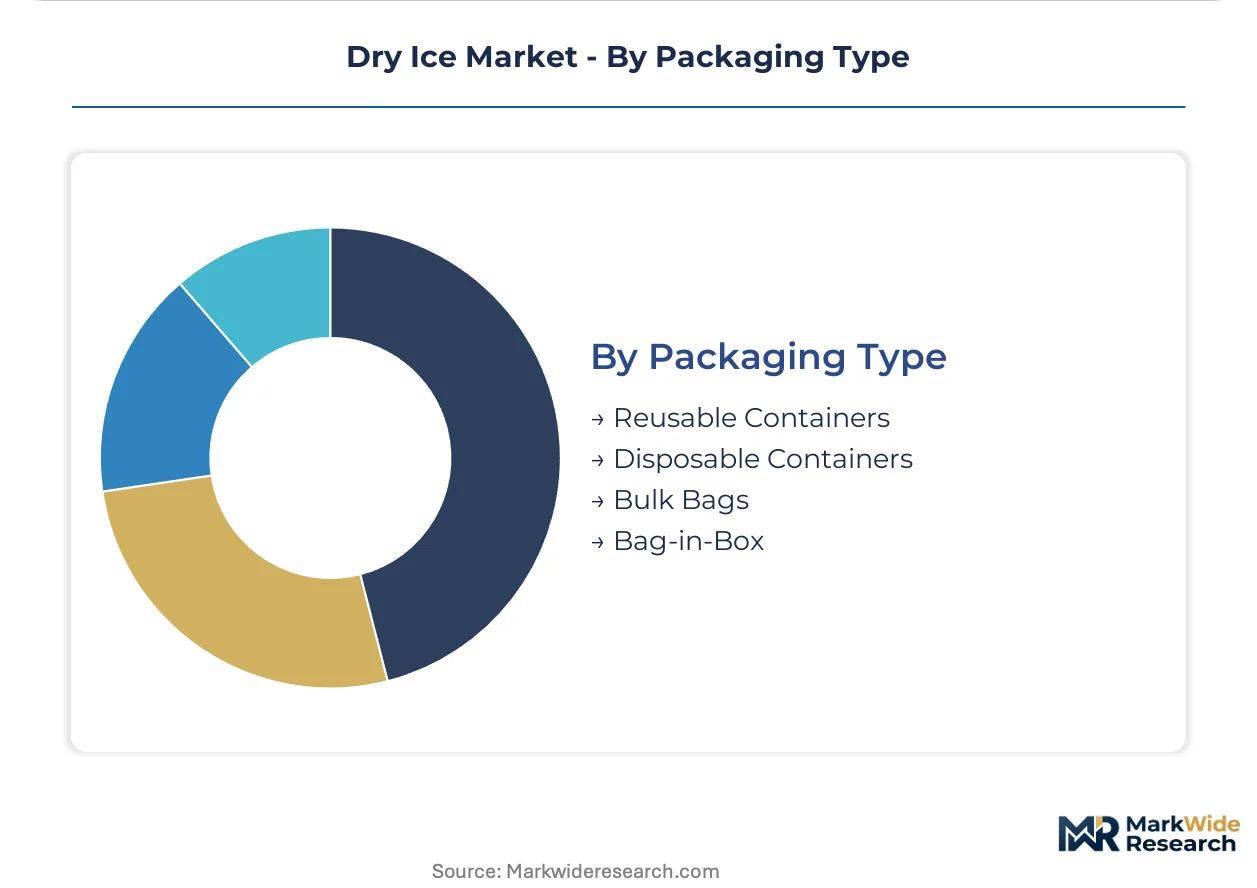
- Reusable Containers:Insulated dewar systems and returnable totes support closed-loop logistics for pharmaceutical distributors and large food processors with reverse logistics infrastructure.
- Disposable Containers:Single-use insulated cartons serve meal kit delivery networks and specialty pharmaceutical couriers without return logistics capabilities.
- Bulk Bags:Large-format flexible packaging accommodates industrial blast cleaning contractors and high-volume food manufacturing inputs.
- Bag-in-Box:Intermediate containment systems bridge foodservice and small-scale industrial applications with moderate volume requirements.
Reusable Containers dominate contracted pharmaceutical accounts. Disposable Containers expand with last-mile delivery networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical manufacturing zones in Massachusetts and North Carolina concentrate cell therapy production, anchoring North American demand for precision-dosed dry ice formats. These clusters attract integrated CO2 suppliers seeking captive feedstock arrangements with biologics manufacturers.
United States
Vaccine distribution networks and frozen food processing clusters sustain high-volume procurement across the Southeast and Midwest. The EPA's AIM Act phasedown of hydrofluorocarbon refrigerants redirects food processors toward CO2-based cooling alternatives. Poultry processing facilities in Georgia and Alabama anchor block-format consumption for mechanical refrigeration backup.
Germany
Automotive component cleaning operations and pharmaceutical manufacturing drive pellet demand for precision surface preparation and biologics transport. The EU F-Gas Regulation synchronizes pressure on synthetic refrigerant-dependent infrastructure with US compliance timelines. Industrial clusters in Baden-Württemberg and Bavaria standardize on dry ice protocols for cross-continental regulatory alignment.
China
Expanding cold chain logistics networks for fresh e-commerce delivery and vaccine distribution expand addressable demand for disposable container formats. The country's dual carbon goals incentivize carbon capture integration into industrial CO2 supply chains. Yangtze River Delta pharmaceutical manufacturing zones adopt pharmaceutical-grade pellet systems for export-oriented biologics production.
India
Vaccine cold chain infrastructure investments and expanding food processing capacity elevate dry ice consumption for temperature-sensitive distribution. The PLI scheme for pharmaceutical manufacturing attracts biologics producers requiring certified cold chain protocols. Maharashtra and Gujarat pharmaceutical clusters develop dedicated dry ice supply arrangements for export compliance.
United Kingdom
Specialty pharmaceutical couriers and meal kit delivery networks adopt portable dry ice containers for last-mile temperature control. Health Canada-aligned cold chain guidelines for biologics shipments shape procurement specifications for transatlantic logistics operators. The Southeast England logistics corridor concentrates distribution infrastructure serving European pharmaceutical markets.
Dry Ice Market Vendor Landscape
North American producers anchor one tier of supply consolidation through integrated CO2 capture infrastructure; European specialists hold differentiated positions in pharmaceutical-grade certification systems. The competitive structure stratifies across three archetypes: integrated industrial gas majors with captive feedstock, regional distributors controlling last-mile density, and equipment-integrated producers supplying precision pellet systems. Capacity expansion and backward integration into carbon capture assets represent the dominant competitive moves reshaping supply security.
Among the integrated industrial gas tier, Linde plc and Air Liquide exemplify producers with multinational CO2 liquefaction networks. Airgas occupies a position within the regional distribution archetype, while Cold Jet represents the equipment-integrated specialization segment. These three anchors illustrate how competitive positioning diverges across feedstock control, geographic density, and format precision vectors.
| Leading Market Players |
|---|
| Airgas |
| Cold Jet |
| Linde plc |
| Aquila Triventek |
| CryoCarb |
| Air Liquide |
| Continental Carbonic Products |
| Tripti Dry Ice Co |
| Air Products and Chemicals |
| Others |
Supply Flow & Price Mechanics
CO2 feedstock costs cascade through three pricing tiers from ammonia fertilizer plants and ethanol refineries into pharmaceutical-grade premiums, industrial spot rates, and foodservice contract discounts. Geographic distance from Gulf Coast supply centers dictates landed cost spreads that separate long-term offtake agreements from volatile spot procurement.
Pricing Analysis
Short lead-time premiums command substantial markups over contract volumes scheduled weeks ahead. Pharmaceutical-grade certification and FDA-compliant chain-of-custody documentation anchor the premium tier, while industrial blast cleaning contractors absorb standard-grade pricing with minimal service bundling. Pricing pressure stems from liquid nitrogen substitution in biologics transport segments. Small-scale foodservice operators exhibit highest price sensitivity due to OSHA-mandated ventilation infrastructure costs.
Supply Chain Analysis
Reverse logistics for reusable dewar containers and returnable totes create closed-loop economics that favor large pharmaceutical distributors with dedicated fleet capacity. Industrial CO2 supply concentrates in the United States Gulf Coast, with secondary nodes in Germany and China. Production draws from ammonia fertilizer plants, ethanol refineries, and emerging direct air capture facilities. Single-source vulnerability around Gulf Coast petrochemical complexes threatens supply security during hurricane disruptions. Distribution runs through integrated industrial gas majors, regional branch networks, and equipment-integrated specialists serving precision pellet demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
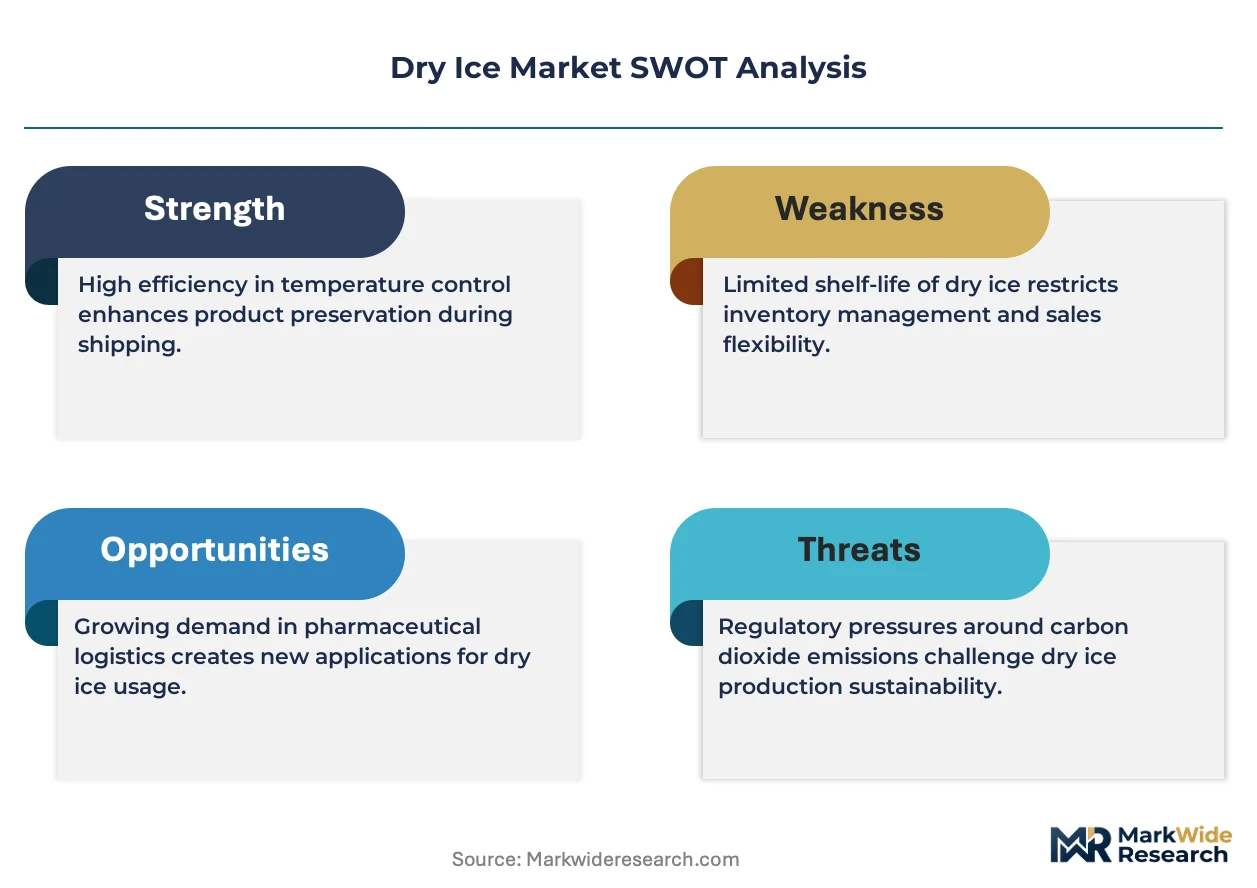
The dry ice market has become a vertical-integration race where captive CO2 feedstock control separates margin leaders from price-takers. Players are pursuing backward integration into carbon capture assets and liquefaction infrastructure to decouple from commodity chemical cycles.
For Market Incumbents: Cement feedstock security through long-term offtake agreements with ammonia and ethanol producers before direct air capture scales. Add pellet production capacity in Massachusetts and North Carolina biologics clusters to defend against liquid nitrogen substitution. EPA AIM Act compliance timelines create window to lock in pharmaceutical-grade certification investments ahead of competitor capacity additions. For New Entrants and Emerging Players: E-commerce platforms for portable dry ice containers offer low-capital entry into last-mile cold chain networks. Target meal kit delivery couriers and specialty pharmaceutical distributors in Southeast England and Yangtze River Delta zones underserved by integrated majors. Lead with disposable container subscriptions to bypass reverse logistics infrastructure requirements that favor incumbents. For Investors and Strategic Acquirers: Consolidated buying by national third-party logistics operators is the leading indicator that regional distributor valuations will compress. Long-term viability favors producers with carbon capture integration pathways and pharmaceutical-grade certification systems. Target regional distributors with dense last-mile networks in vaccine distribution corridors as acquisition candidates before channel restructuring completes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Capture | Direct air capture facilities decouple dry ice producers from ammonia and ethanol market volatility. |
| Pharmaceutical-Grade Certification Investment | FDA-compliant pellet systems capture premium pricing from Massachusetts cell therapy manufacturers. |
| Pellet Production Capacity Expansion | Automated hydraulic pressing reduces unit costs for blast cleaning contractor substitution demand. |
| Last-Mile Container Subscription Models | Disposable container networks bypass reverse logistics requirements for meal kit delivery growth. |
| Long-Term Feedstock Offtake Agreements | Gulf Coast petrochemical contracts secure CO2 supply ahead of direct air capture competition. |
Methodological Framework
Independent corroboration across dry ice production facility managers, pharmaceutical logistics procurement leads, and blast cleaning contractor operations heads underwrites the qualitative findings. Secondary validation draws from EPA AIM Act regulatory filings, FDA cold chain guidance documents, EU F-Gas Regulation implementation reports, and industrial gas producer SEC disclosures. Bottom-up capacity assessments triangulate against top-down demand modeling across application segments.
Rate-of-change decomposition separates volume growth from price trajectory shifts across the projection horizon. The analytical framework models product format, application, end user, and packaging type dimensions alongside regional regulatory cluster differentiation. CAGRs derive from production capacity expansion schedules, feedstock cost projections, and substitution elasticity estimates for liquid nitrogen in biologics transport.
The model holds under stable EPA phasedown timelines and continued pharmaceutical cold chain investment; deviation in carbon capture cost curves or OSHA exposure limit tightening would shift supply economics. Practitioners should monitor direct air capture project announcements and biologics manufacturing cluster development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Global Nutating Mixers Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Pet Food Processing Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Shawarma Grill Machine Market