
 Cereal Rolling Machine Market | 2026-2036
Cereal Rolling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Cereal Rolling Machine Market Analysis
Breakfast cereal manufacturing is realigning toward high-throughput automated flaking as private-label brands gain shelf space. Buhler Group leverages its Swiss process engineering heritage to dominate premium industrial roller installations across European milling corridors. Satake Corporation anchors its position in Asian rice-to-cereal conversion lines with precision gap-control technology. Jinan Huixin Machinery competes on cost-optimized electric rolling machines for mid-scale Chinese cereal producers expanding domestic oat processing.
A cereal rolling machine employs hardened alloy rollers with calibrated gap settings, typically operating at controlled temperatures and differential speeds to flatten grain kernels into uniform flakes for ready-to-eat cereals and snack bases. Electric rolling machines lead volume shipments due to consistent torque delivery and programmable thickness control, while laboratory rollers capture disproportionate margin pools from R&D-intensive food manufacturers validating new grain formulations. Cereal processing applications sustain the largest installed base, though snack production lines represent the fastest-growing demand segment as extruded and flaked savory products expand in retail channels.
FDA food safety modernization rules and EU hygiene design standards under EFSA guidance compel equipment upgrades with clean-in-place capabilities and sanitary bearing housings. China's SAMR enforces GB standards on food-contact machinery that constrain imports lacking domestic certification. Stakeholders must monitor regulatory divergence between North American and European sanitation protocols when configuring global equipment portfolios.
Market Dynamics
Automated flaking lines are displacing semi-manual roller systems as breakfast cereal manufacturers face FDA food safety modernization mandates requiring clean-in-place capabilities and sanitary bearing housings.
Growth Catalysts
- EU hygiene design standards:EFSA guidance under Regulation (EC) 852/2004 compels European industrial bakeries to upgrade legacy roller systems with certified sanitary designs.
- Electric torque control:Programmable thickness settings enable mid-scale oat processors to achieve flake uniformity previously requiring premium mechanical systems.
- Private-label shelf expansion:Contract manufacturers in Germany are installing precision-controlled roller systems to serve retailer-owned cereal brands.
Market Restraints
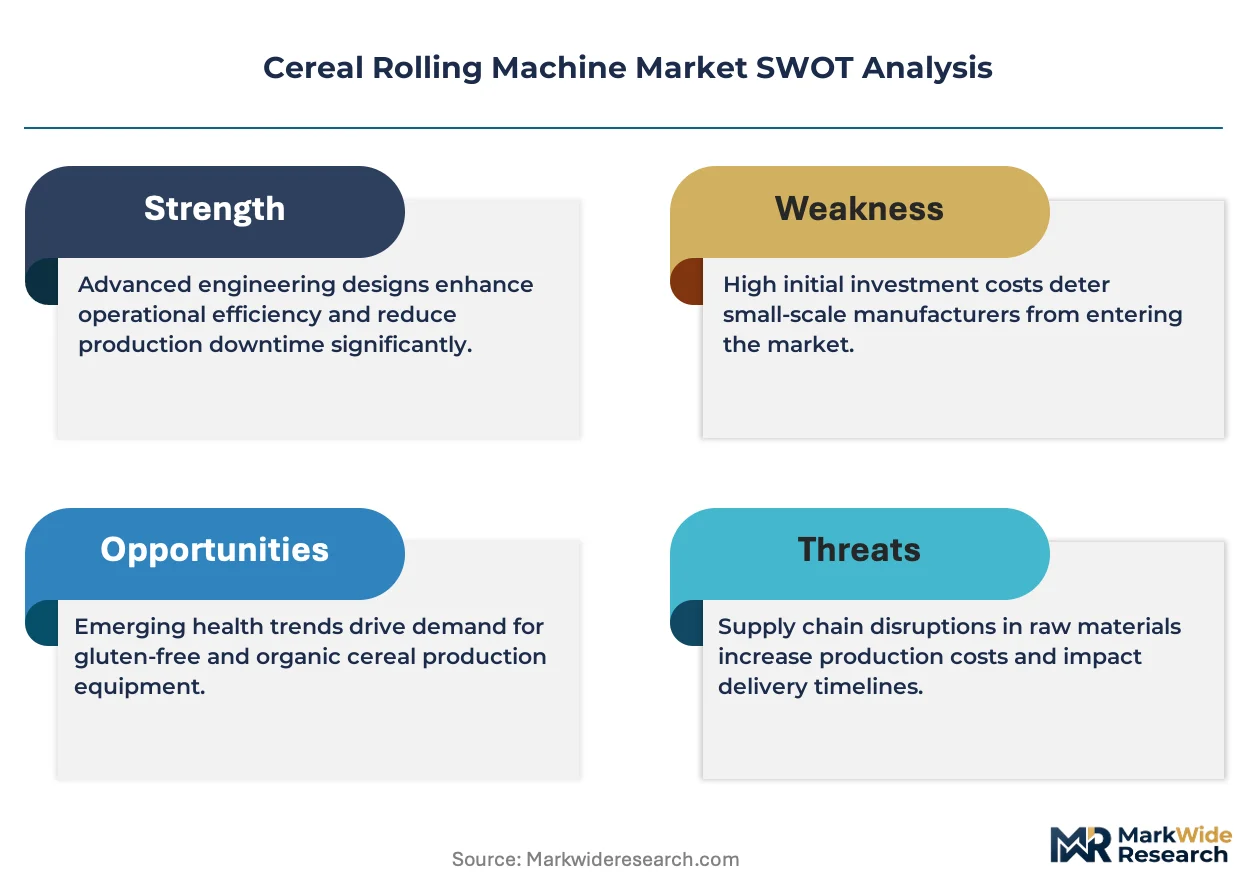
- Alloy roller supply concentration:Hardened steel roller fabrication clusters in select European and East Asian forging centers create procurement vulnerability for North American equipment assemblers.
- GB standards certification friction:China's SAMR food-contact machinery requirements constrain import velocity for European and North American equipment lacking domestic testing documentation.
- Extrusion substitution:Hot extrusion systems for direct-expanded cereals bypass flaking entirely in certain RTE breakfast applications.
Strategic Opportunities
- Savory snack flaking:Extruded and flaked savory products in retail channels are creating parallel demand for roller systems outside traditional cereal processing.
- Laboratory-scale validation:R&D-intensive food manufacturers require precision gap-control rollers for new grain formulation testing before production-scale commitment.
- US energy efficiency incentives:IRA manufacturing provisions subsidize electric rolling machine upgrades for domestic cereal producers reducing thermal processing footprints.
Industry Challenges
- Sanitary welding certification:FDA-compliant clean-in-place roller assemblies require specialized orbital welding qualifications that constrain qualified technician pools.
- Legacy mechanical integration:Existing pneumatic gap-control systems resist seamless interface with modern programmable logic controllers without substantial line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cereal Rolling Machine Market |
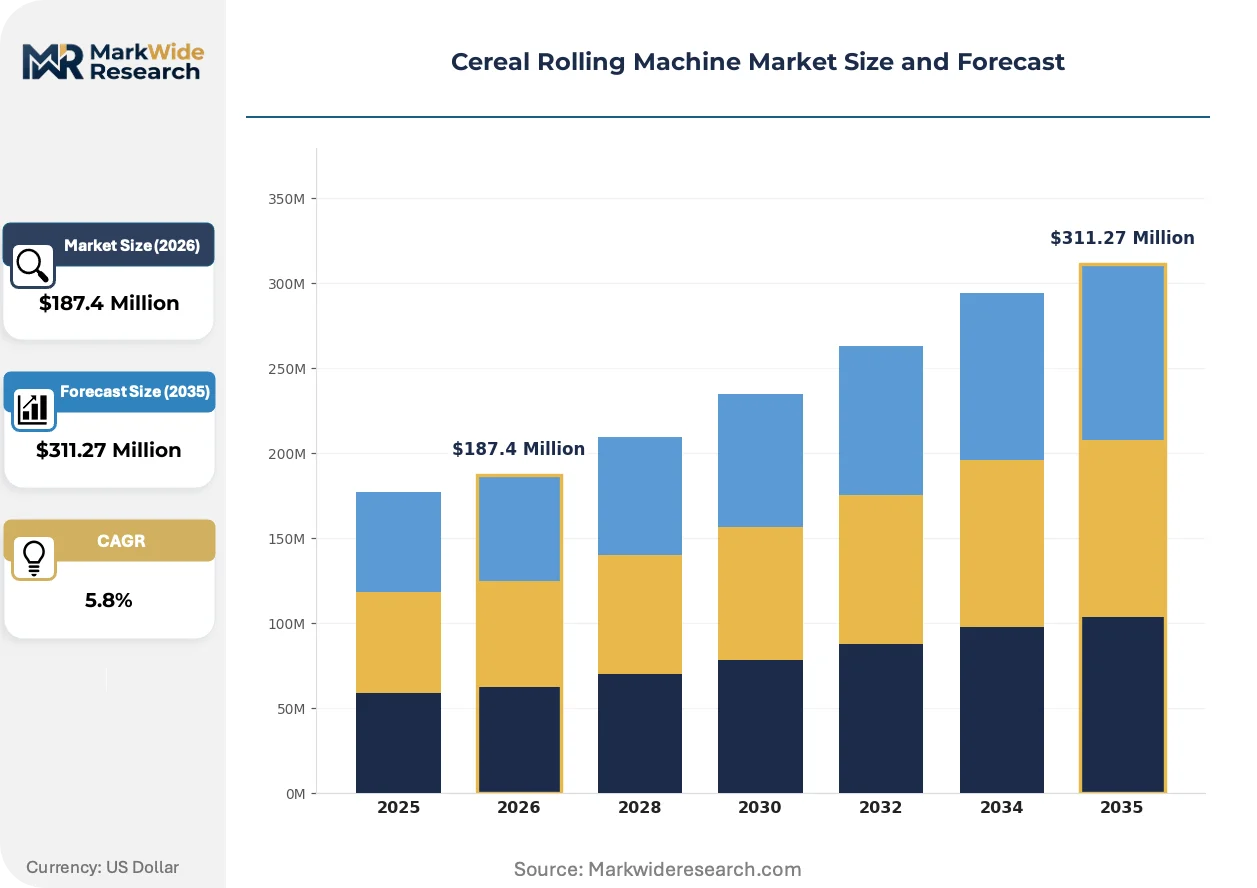
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Rolling Machines, Manual Rolling Machines, Industrial Rollers, Laboratory Rollers End User: Food Manufacturers, Bakeries, Cereal Producers, Research Institutions Size: Small Scale, Medium Scale, Large Scale, Custom Size Application: Cereal Processing, Snack Production, Flour Milling, Animal Feed Production |
| Companies Covered | Buhler Group, Satake Corporation, Jinan Huixin Machinery Co., Ltd., Henan Pingyuan Machinery Co., Ltd., Laxmi Engineering Works, Zhengzhou Longer Machinery Co., Ltd., Zhengzhou Leabon Machinery Equipment Co., Ltd., Idugel Group, Krüger & Salecker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cereal Rolling Machine Market Emerging Trajectories
Precision gap-control automation is compressing the performance advantage gap between premium European and cost-optimized Asian equipment tiers, reshaping buyer evaluation criteria across mid-scale processing facilities.
Electromechanical roller gap actuation is overtaking pneumatic positioning systems in new installations. Food-grade servo motors with closed-loop feedback enable 10-micron positioning repeatability across temperature swings. Mid-scale oat and rice processors in China and Southeast Asia are specifying electromechanical systems for new lines, compressing the historical premium attached to Swiss and German pneumatic designs.
REACH Annex XIV authorization requirements for chromium plating processes are elevating surface treatment costs for hardened alloy rollers. European roller fabricators are shifting toward plasma-transferred wire arc coatings as compliant alternatives. German and Italian equipment OEMs absorb the steepest cost adjustments, passing selective premiums to buyers specifying EU-origin components.
Buyer consolidation among North American contract manufacturers is compressing equipment procurement cycles. Large co-manufacturing groups now centralize capital equipment decisions across multiple production sites, replacing distributed plant-level purchasing. This concentration is most visible in the US Great Lakes cereal production corridor, where three integrated co-manufacturing networks now control a substantial share of new roller system specifications.
Cereal Rolling Machine Market Segmentation
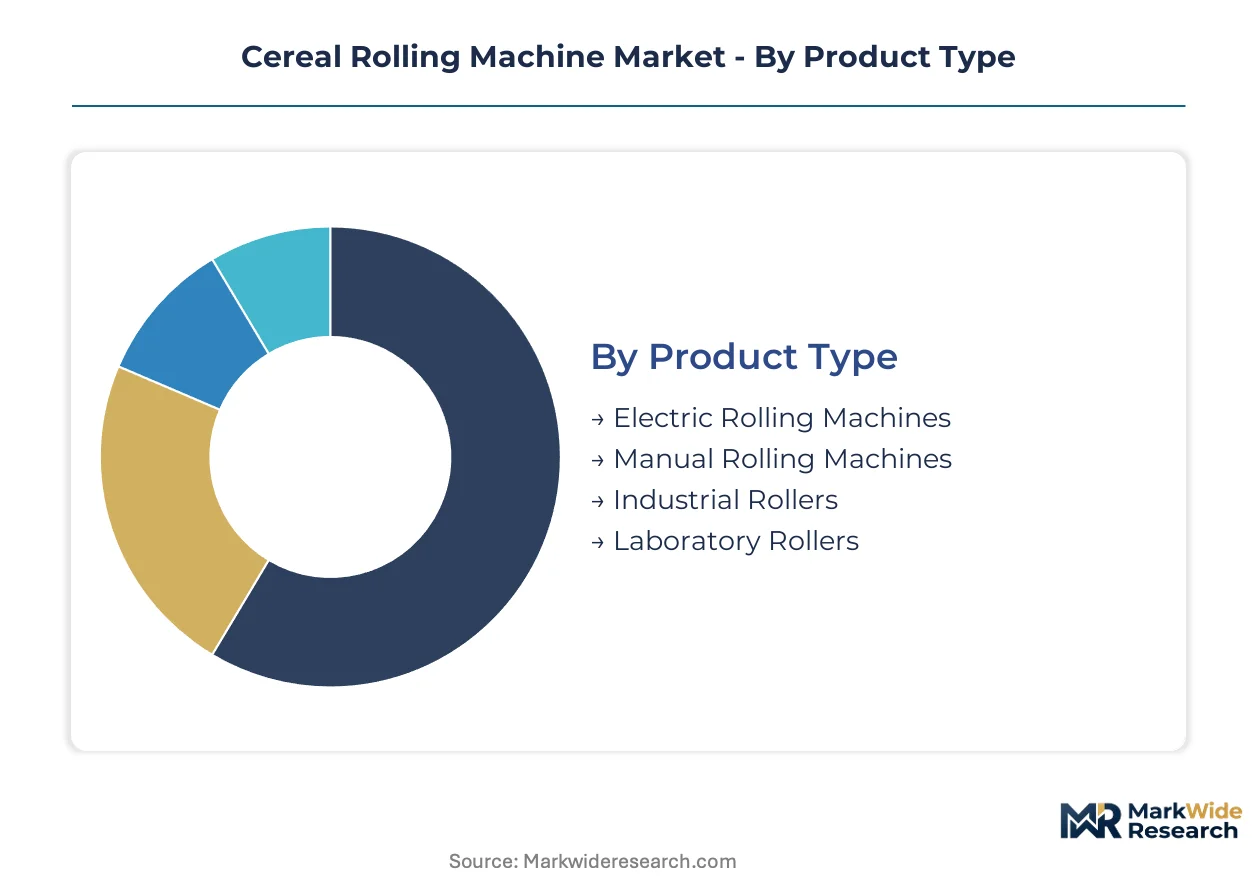
Cereal rolling machine procurement decisions pivot on throughput requirements, regulatory compliance tiers, and integration complexity with existing processing lines. Equipment specification directly determines flake uniformity, energy consumption profiles, and clean-in-place protocol compatibility across breakfast cereal and adjacent food processing verticals.
Product Type:
Electromechanical precision and torque delivery architectures define performance differentiation across equipment tiers.
- Electric Rolling Machines:Servo-driven systems with closed-loop feedback enable programmable thickness control across temperature fluctuations. Food manufacturers in Germany and the United States specify these for high-throughput oat flaking lines under tightened FDA and EFSA sanitation mandates.
- Industrial Rollers:Hardened alloy roller assemblies with differential speed configurations process multiple grain varieties on shared production lines. Cereal producers in China's Shandong and Henan provinces deploy these for domestic oat processing expansion.
- Manual Rolling Machines:Mechanical gap-adjustment systems serve artisan bakeries and small-batch muesli producers with limited automation requirements.
- Laboratory Rollers:Precision gap-control units enable R&D validation of new grain formulations before production-scale commitment.
Electric rolling machines lead on scale; laboratory rollers lead on momentum.
End User:
Customer procurement authority concentrates differently across integrated multinationals, contract manufacturers, and research-intensive institutions.
- Food Manufacturers:Integrated breakfast cereal producers with centralized capital equipment committees specify sanitary-design roller systems for multi-site standardization. Co-manufacturing networks in the US Great Lakes corridor drive consolidated purchasing volume.
- Cereal Producers:Dedicated RTE cereal specialists require precision-controlled flaking lines for private-label contract production. German industrial bakeries and muesli specialists anchor European replacement demand.
- Bakeries:Industrial and artisan baking operations utilize roller systems for grain preprocessing and specialty flake incorporation.
- Research Institutions:Food science laboratories and university extension programs acquire small-scale validation equipment for grain innovation pipelines.
Food manufacturers dominate installed base; cereal producers show steepest expansion trajectory.
Size:
Production scale alignment determines equipment footprint, utility infrastructure requirements, and automation integration depth.
- Large Scale:Continuous-duty roller systems with automated gap control and clean-in-place architecture serve high-volume breakfast cereal production. These installations concentrate in integrated processing facilities across the United States and Germany.
- Medium Scale:Semi-automated systems with programmable logic controllers enable mid-tier oat and rice processors to achieve flake uniformity without premium mechanical investments. Southeast Asian processors specify these for expanding domestic cereal markets.
- Small Scale:Compact roller units serve regional bakeries and specialty cereal startups with limited capital budgets.
- Custom Size:Engineered-to-order systems address non-standard grain varieties or constrained facility footprints.
Large scale commands capital allocation; medium scale gains share fastest.
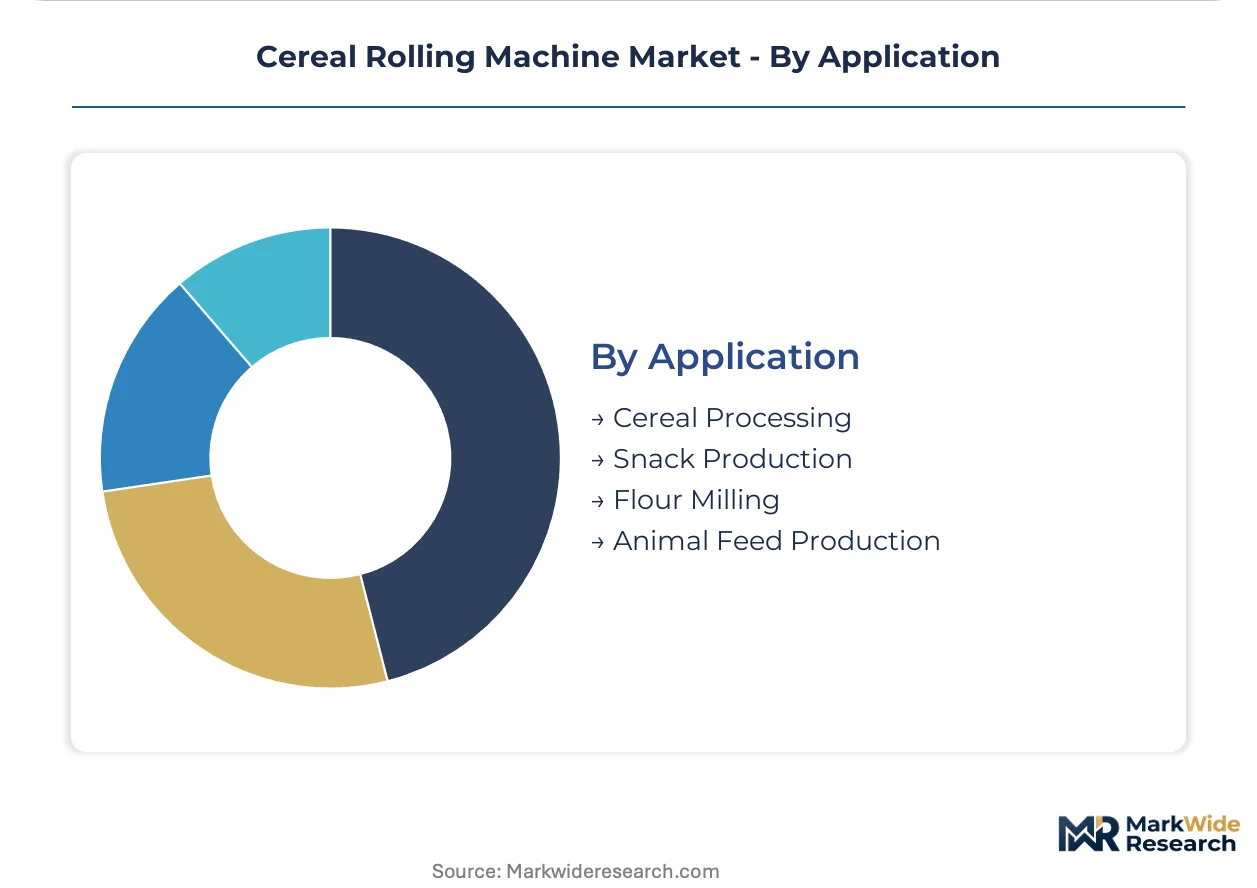
Application:
End-use diversification beyond traditional breakfast cereal creates parallel demand channels with distinct specification requirements.
- Cereal Processing:Flake production for ready-to-eat breakfast cereals sustains the largest installed base of roller systems. FDA food safety modernization rules and EU hygiene design standards compel equipment upgrades with sanitary bearing housings and clean-in-place capabilities.
- Snack Production:Extruded and flaked savory products in retail channels generate demand for roller systems outside traditional cereal processing. Asian and North American snack manufacturers specify precision gap-control equipment for expanded savory flake portfolios.
- Flour Milling:Grain flattening operations for specialty flour applications utilize modified roller configurations with adjusted gap tolerances.
- Animal Feed Production:Rolled grain processing for livestock feed applications employs simplified roller systems with reduced sanitation certification requirements.
Cereal processing anchors revenue; snack production climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns diverge sharply where regulatory compliance costs outpace automation savings, pushing mid-scale producers toward jurisdictions with streamlined certification pathways.
United States
Integrated co-manufacturing networks in the Great Lakes cereal corridor drive consolidated capital equipment decisions across multiple production sites. FDA food safety modernization rules mandate clean-in-place capabilities and sanitary bearing housings for all new installations. Chicago and Minneapolis-St. Paul anchor the densest cluster of automated flaking line deployments.
Germany
Industrial bakeries and muesli specialists in Bavaria and North Rhine-Westphalia sustain replacement cycles for precision-controlled roller systems. EFSA guidance under EU hygiene design standards compels upgrades to certified sanitary designs. Munich-based equipment fabricators supply adjacent European milling corridors with premium electromechanical systems.
China
Domestic oat processing expansion in Shandong and Henan provinces drives demand for cost-optimized electric rolling machines. SAMR food-contact machinery requirements constrain import velocity for equipment lacking GB standards certification. Jinan and Zhengzhou house the fastest-growing clusters of mid-scale cereal machinery manufacturing.
Japan
Rice-to-cereal conversion specialists specify precision gap-control technology for specialty flake production. METI energy efficiency guidelines favor servo-driven systems with closed-loop feedback over legacy pneumatic designs. Osaka-Nagoya industrial belt concentrates the highest density of laboratory-scale validation equipment for grain innovation.
India
Contract manufacturers serving private-label brands install semi-automated systems with programmable logic controllers for flake uniformity. FSSAI food safety regulations tighten equipment sanitation standards for ready-to-eat cereal production. Maharashtra and Gujarat host expanding clusters of mid-tier oat and millet processing facilities.
Cereal Rolling Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding premium installations while regional fabricators capture cost-sensitive mid-scale demand. The vendor base organizes around three strategic archetypes: Swiss and German precision engineering houses, East Asian scale-oriented manufacturers, and Indian and Chinese cost-optimized specialists. Competitive moves concentrate on geographic expansion through distribution partnerships and backward integration into hardened alloy roller fabrication.
Among Swiss precision engineering houses, Buhler Group occupies a position exemplifying premium-tier process heritage across European milling corridors. Satake Corporation anchors the Japanese archetype for rice-to-cereal conversion technology. Jinan Huixin Machinery Co., Ltd. represents the Chinese cost-optimized tier serving domestic oat processing expansion.
| Leading Market Players |
|---|
| Buhler Group |
| Satake Corporation |
| Jinan Huixin Machinery Co., Ltd. |
| Henan Pingyuan Machinery Co., Ltd. |
| Laxmi Engineering Works |
| Zhengzhou Longer Machinery Co., Ltd. |
| Zhengzhou Leabon Machinery Equipment Co., Ltd. |
| Idugel Group |
| Krüger & Salecker |
| Others |
Supply Flow & Price Mechanics
Integrated co-manufacturing networks in the US Great Lakes corridor and German industrial bakery groups now command sufficient procurement volume to enforce contract-based long-term offtake pricing with tiered performance guarantees. This buyer concentration compresses margin buffers for equipment assemblers while elevating the premium attached to certified sanitary designs.
Pricing Analysis
Distributor margins for European-origin equipment typically absorb 12-18 points before OEM delivery, while direct-to-factory sales from Chinese fabricators bypass this layer entirely. Pricing stratifies across premium electromechanical systems with closed-loop feedback, standard pneumatic configurations, and economy-tier manual units. Cost compression in the economy tier intensifies as Jinan and Zhengzhou manufacturers expand servo-driven offerings at mid-market price points. Contract manufacturers show the sharpest price sensitivity; integrated multinationals prioritize certification tier over unit cost.
Supply Chain Analysis
Freight cost volatility from European forging centers to North American assembly plants has prompted inventory pre-positioning at Port of Rotterdam hubs. Hardened alloy roller fabrication clusters in Germany, Italy, and Japan feed global equipment assembly, with Chinese steel mills capturing share in cost-optimized tiers. Supply chain risk centers on single-source vulnerability for precision-ground roller bearings sourced from German and Japanese specialty producers. Distribution runs through authorized equipment dealers for premium tiers and direct factory relationships for mid-scale Asian procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cereal rolling machine market represents a late-cycle quality story as FDA and EFSA sanitation mandates force replacement of legacy pneumatic systems with certified clean-in-place architectures. This regulatory-driven specification upgrade favors vendors with pre-validated sanitary designs.
For Market Incumbents:Lock in backward integration into hardened alloy roller fabrication to secure supply continuity against forging-center concentration risk. Expand certified technician training programs for orbital welding qualifications; qualified installer scarcity now constrains deployment velocity for clean-in-place retrofits. Defend margin position by bundling aftermarket service contracts with initial equipment sales.
For New Entrants and Emerging Players:Precision gap-control automation technology offers entry leverage against established pneumatic-system incumbents. Target medium-scale oat processors in Southeast Asia and domestic Chinese markets where electromechanical specifications are displacing legacy mechanical designs. Pursue laboratory-scale validation equipment as the most penetrable segment; R&D-intensive food manufacturers prioritize performance demonstration over brand heritage.
For Investors and Strategic Acquirers:Food manufacturing conglomerates with private-label cereal portfolios are the most active acquirer in this space, seeking captive equipment supply for co-manufacturing networks. The long-term viability window favors vendors with demonstrated FDA and EFSA certification pathways. Monitor SAMR GB standards certification velocity as the critical inflection signal; domestic Chinese certification unlocks import substitution opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Roller Fabrication | Mitigates supply vulnerability from European and East Asian forging-center concentration. |
| Sanitary Welding Certification Investment | Addresses FDA-compliant clean-in-place assembly constraints from qualified technician scarcity. |
| Laboratory-Scale Equipment Launch | Captures R&D-intensive food manufacturer demand for formulation validation before production commitment. |
| Direct Distribution Expansion in Southeast Asia | Bypasses distributor margin layers for mid-scale oat processors in expanding domestic markets. |
| Servomotor Platform Standardization | Enables 10-micron positioning repeatability across temperature swings for precision gap-control automation. |
Methodological Framework
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs records and SEC filings, and technical specification audits — were reconciled to construct market estimates. Conversations with maintenance directors at integrated cereal producers, aftermarket service heads at equipment distributors, and regulatory affairs leads at food manufacturers informed demand-side dynamics. Bottom-up equipment shipment tallies were cross-referenced against top-down processed grain volume projections.
Historical capacity deployment patterns were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation across product type, end user, production scale, and application vertical, with regional regulatory clusters as an overlay dimension. CAGRs were derived from slope analysis of replacement cycle timing and expansion capital commitment trajectories, incorporating SAMR certification friction and IRA energy efficiency incentive uptake as industry-specific forecast inputs.
The model holds under continued regulatory enforcement of FDA food safety modernization and EFSA hygiene design standards; deviation in enforcement intensity or tariff exposure on alloy roller imports would shift replacement timing and geographic sourcing patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Recycler Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Countertop Convection Oven Market