
 Global Commercial Food Dehydrators Market | 2026-2036
Global Commercial Food Dehydrators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Food Dehydrators Market Intelligence
Global initiatives to reduce food waste, such as the objectives outlined in the UN's Sustainable Development Goal 12.3, is expanding the addressable market for commercial food preservation equipment. Excalibur Dehydrator leverages its long-standing brand recognition in the tray dehydrator segment for professional kitchens. Harvest Right specializes in the high-margin freeze dehydrator category, targeting both commercial and prosumer markets. National Presto Industries competes on the basis of its wide distribution network across North American retail channels.
Commercial food dehydrators are industrial-grade appliances designed to remove moisture from food products through controlled heat and airflow, extending shelf life. Key operational parameters include precise temperature control, typically ranging from 35°C to 75°C, and air circulation velocity to ensure uniform drying. Within product types, freeze dehydrators command a premium price point while conventional tray dehydrators represent the largest installed base. Food processing companies constitute the largest end-user segment, followed by restaurants and catering services seeking to create unique menu items.
Equipment design and material safety are governed by standards from bodies like the FDA in the United States and through CE marking requirements in Europe. Food contact material regulations, such as those under the EU's EFSA, dictate the types of plastics and metals permissible in construction. Vendor selection will increasingly hinge on demonstrating compliance with global food safety certifications and energy efficiency benchmarks.
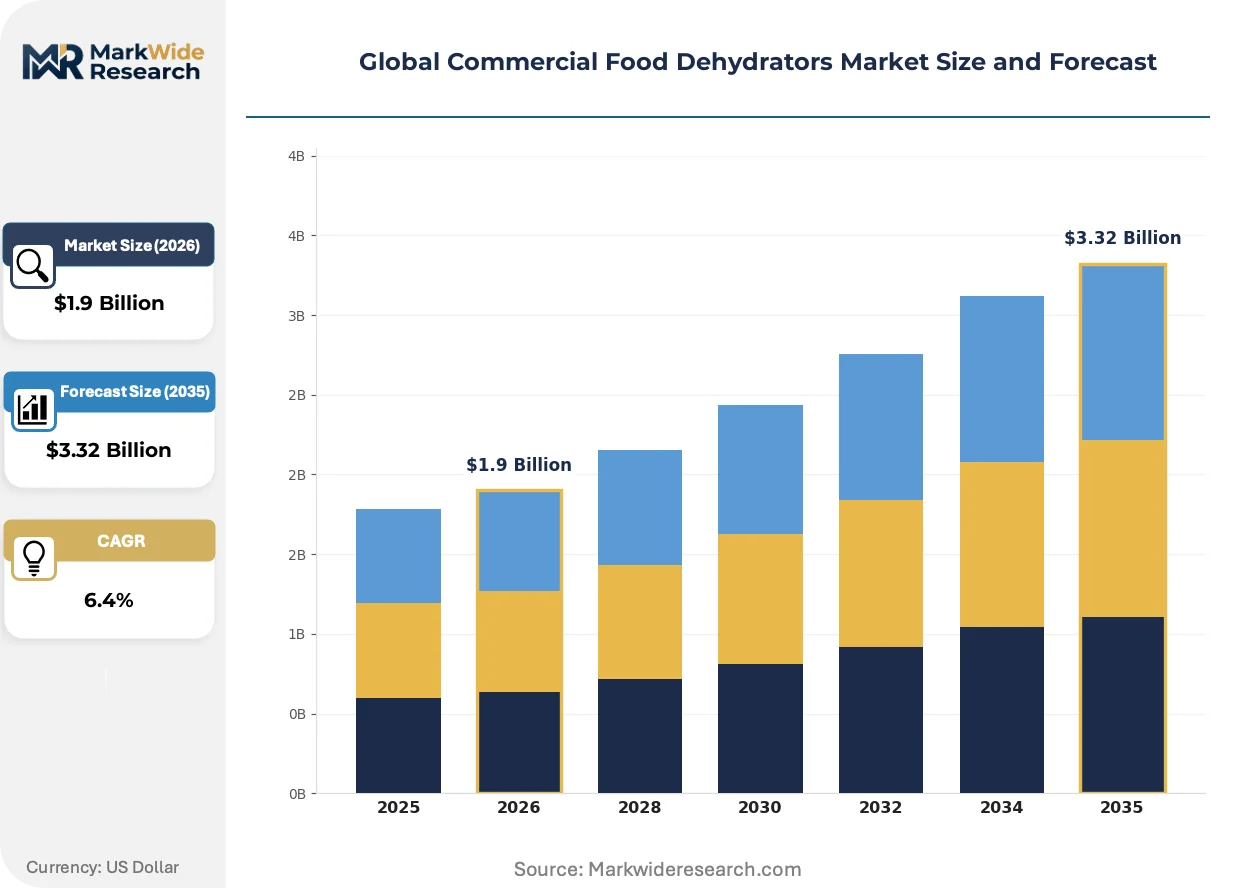
Market Dynamics
The central dynamic shaping the commercial food dehydrator market is the convergence of global food waste reduction mandates and consumer demand for clean-label foods. This dual pressure compels food processors to invest in advanced preservation technologies that extend shelf life while maintaining nutritional integrity, directly expanding the addressable market for industrial-grade drying equipment.
Growth Catalysts
- Food Waste Reduction Policies:Global frameworks, including the UN's Sustainable Development Goal 12.3, encourage food producers and processors to adopt technologies like dehydration to minimize post-harvest losses and convert surplus produce into shelf-stable products.
- Advanced Preservation Technology:The increasing accessibility of freeze-drying technology allows for superior retention of nutrients, color, and texture. This enables food manufacturers to create premium, value-added ingredients for health-focused consumer goods.
- Demand in Food Manufacturing:China's expansive food processing industry exhibits strong demand for dehydrated ingredients used in instant soups, snacks, and ready-to-eat meals, requiring large-scale, efficient dehydration capacity.
Market Restraints
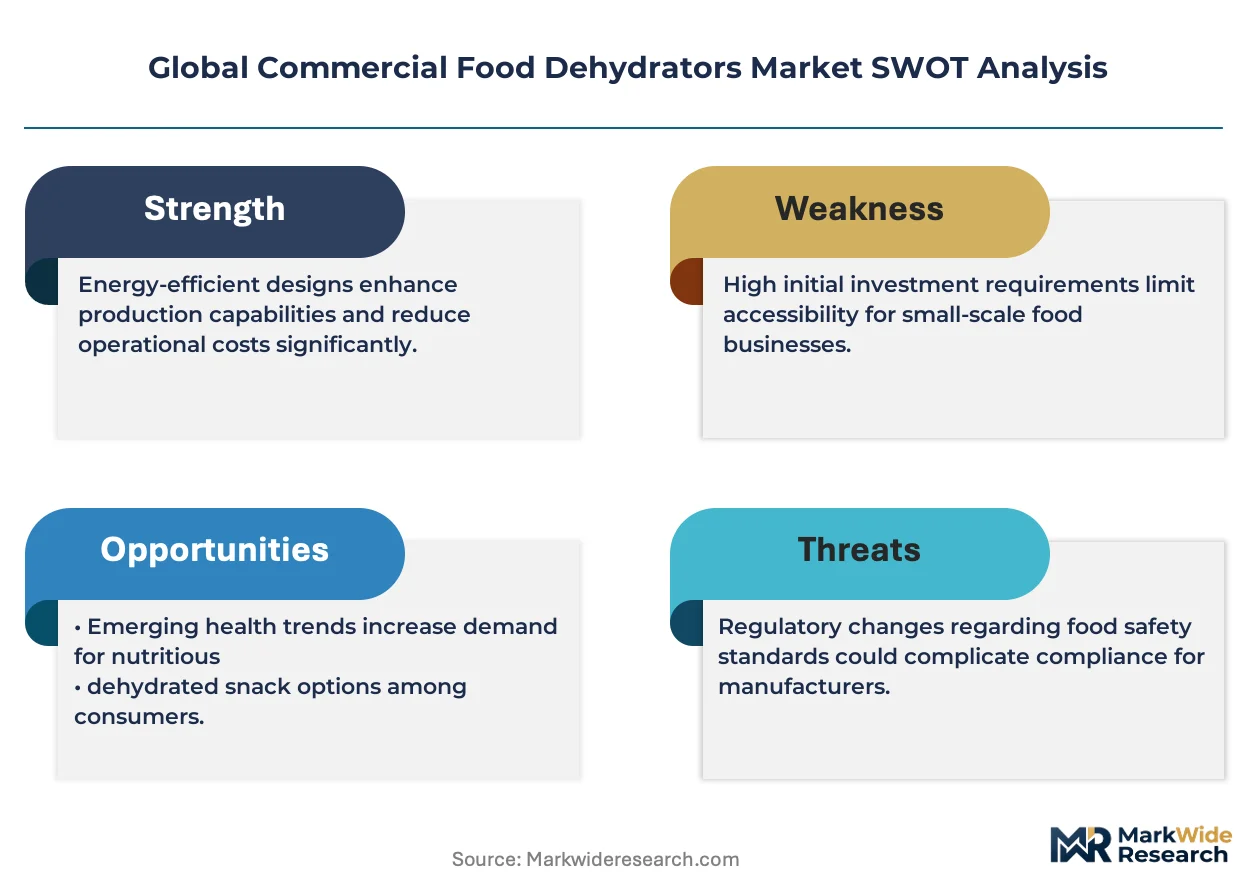
- High Capital Investment:The significant upfront cost of industrial-scale equipment, particularly high-margin freeze dehydrators, presents a substantial barrier to entry for small and medium-sized enterprises.
- Energy Consumption:Conventional tray and conveyor dehydrators are energy-intensive, leading to high operational costs that can erode profit margins, especially in regions with volatile electricity prices.
- Regulatory Compliance Costs:Adhering to stringent food contact material regulations, such as those mandated by the FDA in the US and EFSA in Europe, increases equipment design and manufacturing costs for vendors.
Strategic Opportunities
- Emerging Market Penetration:Brazil's large agricultural sector presents an opportunity for deploying dehydration technology to process tropical fruits and vegetables for export, creating new value chains.
- Nutraceutical and Pet Food Ingredients:Expanding into niche applications like creating high-value active ingredients for dietary supplements or single-ingredient protein snacks for the premium pet food market offers new revenue streams.
- Integration of Smart Technology:Incorporating IoT sensors and AI-driven software for process automation allows for optimized drying cycles, predictive maintenance, and energy savings, creating a strong value proposition for end-users.
Industry Challenges
- Navigating Global Certifications:Securing and maintaining a complex web of food safety and electrical certifications, including CE marking for Europe and specific USDA requirements, is an ongoing operational challenge for manufacturers.
- Technician Skill Gaps:A shortage of trained personnel capable of operating, servicing, and optimizing advanced freeze-drying systems can limit the adoption and efficient use of this high-end technology.
- Energy Efficiency Mandates:Evolving energy performance standards across multiple jurisdictions require continuous R&D investment to redesign equipment, potentially making older models non-compliant and obsolete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Food Dehydrators Market |
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.32 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Dehydrators, Belt Dehydrators, Tray Dehydrators, Freeze Dehydrators Application: Meat Preservation, Fruit Drying, Vegetable Dehydration, Herb Drying End User: Restaurants, Food Processing Companies, Catering Services, Supermarkets Deployment: On-premise, Off-site, Mobile, Centralized |
| Companies Covered | Excalibur Dehydrator, Tribest Corporation, National Presto Industries, LEM Products Holding LLC, Hamilton Beach Brands, Koolatron Corporation, Aroma Housewares Company, Harvest Right, STX International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Food Dehydrators Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward intelligent, modular, and highly efficient dehydration systems. This movement is a direct response to the food industry's need for greater product development agility, verifiable food safety, and lower operational expenditures in creating shelf-stable ingredients.
Modular freeze-drying systems offer scalable capacity that can be adjusted based on production volume. Small-scale food processors, professional kitchens, and R&D labs are the primary adopters of this technology. This equipment innovation is decentralizing advanced preservation capabilities, previously confined to large industrial facilities, to a wider range of commercial users.
European Union regulations under its Green Deal initiative are establishing stricter energy efficiency benchmarks for industrial machinery. This is compelling equipment manufacturers to integrate heat recovery systems, improved insulation, and more efficient fan technologies into their designs. The conventional tray dehydrator segment is most impacted, creating a replacement cycle toward models that meet these new performance standards.
A behavioral shift is occurring in how food companies source dehydrated goods, moving away from simple commodity procurement. Manufacturers of natural and organic products are forming strategic partnerships with specialized dehydration service providers that can offer certified ingredients with guaranteed nutritional values. This trend is most visible within the clean-label food and beverage sectors of North America and Europe.
Global Commercial Food Dehydrators Market Segmentation
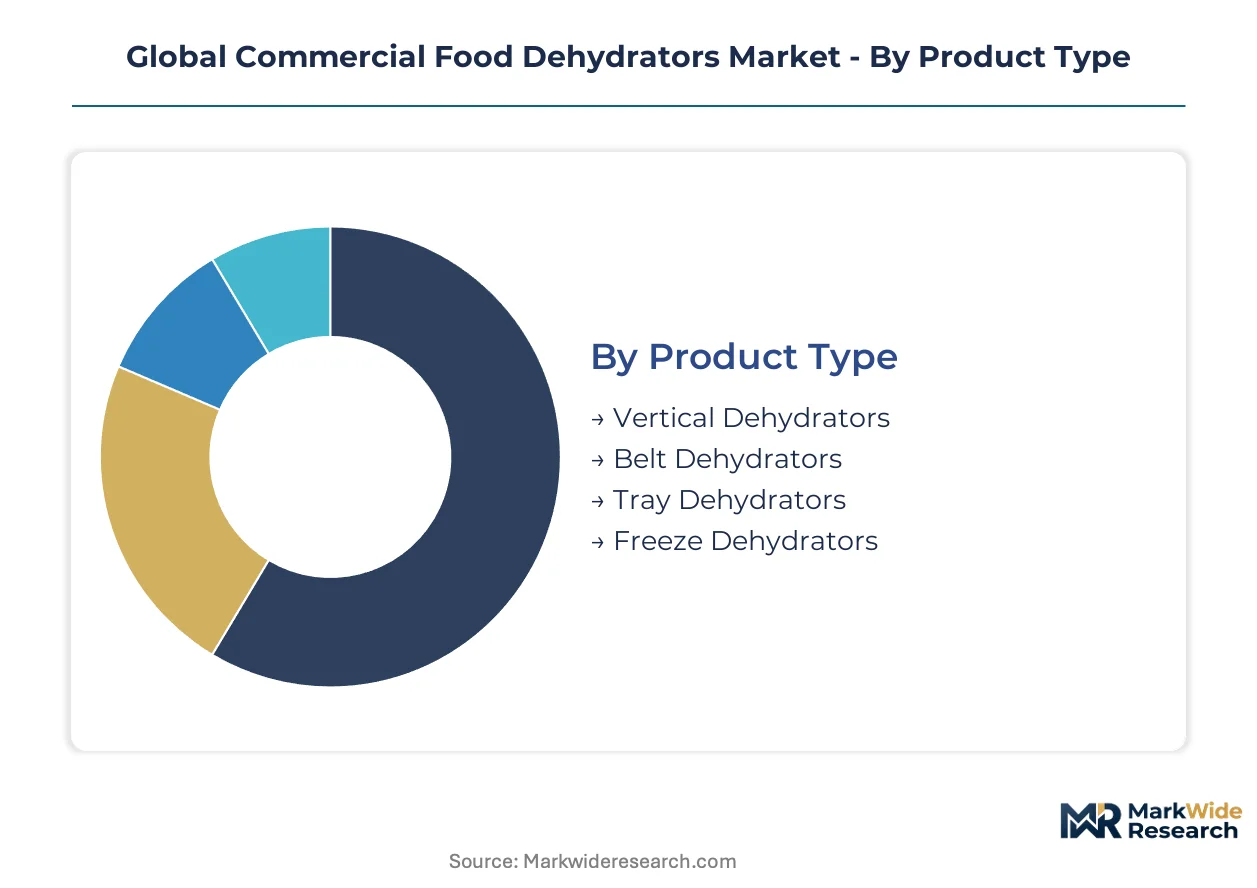
The commercial food dehydrators market is segmented to reflect the diverse needs of food processors, restaurants, and other commercial entities. Understanding these distinctions allows vendors to tailor equipment features and services to specific operational requirements and production scales. Each segment highlights different drivers influencing purchasing decisions across the global landscape.
Product Type:
Buyers in this category differentiate based on the required preservation quality, processing capacity, and initial investment. Advanced technology often correlates with higher nutritional retention and premium product outcomes.
- Freeze Dehydrators:These systems remove moisture through sublimation, preserving up to 97% of nutritional content and original texture. Demand concentrates in North America and Europe for high-value nutraceutical ingredients and premium pet food products.
- Tray Dehydrators:These conventional units utilize controlled heat and airflow across multiple trays, representing the largest installed base in food processing. Food processing companies in China extensively use these for high-volume production of dried fruits and vegetables.
- Vertical Dehydrators:These compact dehydrators circulate air from top to bottom or bottom to top, offering an economical solution for smaller batch processing. Restaurants and catering services often adopt these for in-house ingredient preparation.
- Belt Dehydrators:Continuous belt systems are designed for high-throughput industrial operations, handling large volumes of food products efficiently. Large-scale agricultural processors in Brazil leverage these for fruit and vegetable drying.
Tray Dehydrators lead volumes today; Freeze Dehydrators are gaining share fastest.
Application:
The specific food item being processed dictates the optimal dehydration method, influencing equipment design and operational parameters for moisture removal.
- Fruit Drying:This application involves removing water content from various fruits to extend shelf life and create snack products or ingredients for baked goods. Demand from consumer-packaged goods companies for healthy snack alternatives is robust.
- Vegetable Dehydration:Vegetables are dried for use in instant soups, ready-to-eat meals, and as ingredients for clean-label products. Processors in Europe require efficient vegetable dehydration to meet stringent food safety standards.
- Meat Preservation:Dehydrators are employed to create jerky, biltong, and other dried meat products, reducing water activity to prevent spoilage. Specialty meat processors in the United States utilize this for niche protein snacks.
- Herb Drying:This involves gently removing moisture from herbs to retain their aromatic compounds and extend their usability for culinary and medicinal purposes. Small-batch producers and pharmaceutical companies use this technique.
Demand for Fruit Drying is robust, while Vegetable Dehydration shows significant expansion.
End User:
End-user segments are differentiated by their operational scale, product diversity, and regulatory compliance requirements for food preservation equipment.
- Food Processing Companies:This segment comprises large-scale manufacturers converting raw produce into shelf-stable ingredients and finished products. These companies demand high-capacity, energy-efficient systems compliant with FDA and EFSA regulations.
- Restaurants:Commercial kitchens use dehydrators to create unique menu components, garnish, and reduce food waste from surplus ingredients. Fine dining establishments in France implement these for culinary innovation.
- Catering Services:Catering businesses utilize dehydrators to prepare bulk quantities of dried ingredients, reducing weight and extending the shelf life of prepared components. Event caterers find value in portable and modular units.
- Supermarkets:Some supermarket chains employ dehydrators for in-store production of dried fruits, vegetables, and jerky, offering fresh, locally processed options. Retailers aim to reduce spoilage and enhance product offerings.
Food Processing Companies remain the largest consumer, with Restaurants exhibiting strong growth potential.
Deployment:
The deployment model reflects the physical location and operational strategy for commercial food dehydrators, impacting logistics and infrastructure requirements.
- On-premise:Equipment is installed directly at the food production facility or restaurant, allowing for immediate processing and quality control. This model offers flexibility for companies maintaining strict control over their production processes.
- Centralized:Large-scale dehydration facilities process raw materials from multiple sources, achieving economies of scale. Major agricultural regions, such as those in Brazil, benefit from centralized processing hubs.
- Off-site:Dehydration services are provided by third-party contractors, offering specialized equipment and expertise without the need for capital investment by the food producer. Small and medium-sized enterprises often leverage off-site services.
- Mobile:Portable dehydration units can be transported to different locations, particularly useful for processing seasonal crops directly at the harvest site. Agricultural cooperatives find these valuable for reducing post-harvest losses.
The shift towards On-premise deployment reflects evolving operational needs and scale requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial food dehydrators market has scaled significantly, driven by the historical imperative to preserve food and reduce spoilage. Early methods of drying food have evolved into sophisticated industrial processes, now critical for global food supply chains. This evolution supports an expanding market for advanced preservation equipment across diverse geographies.
China
China's expansive food manufacturing sector demonstrates strong demand for dehydrated ingredients, particularly for instant soups, snacks, and ready-to-eat meals. Adherence to national GB standards ensures food safety and quality across all processed food products. Major food processing hubs in the Yangtze River Delta actively invest in large-scale, efficient dehydration capacity to meet domestic and export needs.
Brazil
Brazil's large agricultural sector presents a significant opportunity for deploying dehydration technology to process tropical fruits and vegetables for export. ANVISA regulations govern food processing and product safety for both domestic consumption and international trade. São Paulo state, with its robust food processing and export operations, increasingly leverages belt dehydrators for high-volume fruit and vegetable drying.
Germany
Germany's food industry prioritizes stringent European food safety standards and the development of clean-label products and nutraceutical ingredients. The EU Green Deal initiatives compel equipment manufacturers to meet stricter energy efficiency benchmarks for industrial machinery, including CE marking requirements. Industrial clusters in North Rhine-Westphalia integrate advanced heat recovery systems into their food processing equipment, enhancing sustainability.
United States
The United States market exhibits robust demand from specialty meat processors for products like jerky, alongside a growing premium pet food segment. FDA regulations dictate equipment design and material safety for all food contact surfaces, complemented by specific USDA requirements for meat products. California's specialty food production sector increasingly adopts advanced freeze-drying systems for high-value ingredients and snacks.
Global Commercial Food Dehydrators Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and end-user focus in the commercial food dehydrators market. The market exhibits a tiered structure, with specialized manufacturers offering advanced freeze-drying solutions at one end and high-volume conventional dehydrator producers at the other. Strategic archetypes include technology innovators, established brand leaders, and mass-market distributors. Companies frequently engage in strategic partnerships to expand their product portfolios and pursue geographic expansion into emerging agricultural regions.
On the premium-tier vector, Harvest Right exemplifies advanced technology specialization in freeze dehydrators, targeting commercial and prosumer markets. Excalibur Dehydrator represents established brand recognition within the conventional tray dehydrator segment, catering to professional kitchens. National Presto Industries occupies a position focused on wide distribution networks, particularly across North American retail channels, serving a broader consumer and light commercial base.
| Leading Market Players |
|---|
| Excalibur Dehydrator |
| Tribest Corporation |
| National Presto Industries |
| LEM Products Holding LLC |
| Hamilton Beach Brands |
| Koolatron Corporation |
| Aroma Housewares Company |
| Harvest Right |
| STX International |
| Others |
Cost & Logistics Intelligence
Energy consumption costs, particularly for conventional tray dehydrators, directly influence operational expenditures for food processors, eventually translating into higher prices for dehydrated ingredients in the downstream supply chain. This cost component differentiates market segments and affects adoption rates across various end-users.
Pricing Analysis
A bifurcated pricing model characterizes the commercial food dehydrators market, with transactional per-unit pricing for conventional units and value-based pricing for advanced freeze-dehydrators. Price differentiation stems from superior nutritional retention capabilities of freeze-drying technology and stringent regulatory compliance like FDA or CE marking. Pricing pressure on conventional tray dehydrators intensifies due to evolving energy efficiency mandates, particularly from EU Green Deal initiatives. Small and medium-sized enterprises often exhibit higher price sensitivity, while nutraceutical and premium pet food manufacturers prioritize quality over cost for freeze-dehydrators.
Supply Chain Analysis
Refurbishment and spare parts logistics for industrial dehydrators represent a critical aspect of aftermarket services, ensuring equipment longevity. Supply concentration for conventional dehydrator manufacturing centers in China, while advanced components for freeze-drying systems often originate from Germany and the United States. The supply chain relies on specialized stainless steel grades, high-precision sensors, and efficient compressor technologies. A structural risk involves single-source vulnerability for high-performance vacuum pumps used in freeze dehydrators. Distribution runs through a combination of direct sales channels for large industrial clients and specialized equipment distributors for smaller commercial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial food dehydrators market presents a geographic-arbitrage opportunity, driven by varying energy costs and regulatory mandates between regions like Brazil and Germany.
For Market Incumbents: Hedge against rising energy costs by investing in heat recovery systems for conventional tray dehydrators. Integrate smart technology, such as IoT sensors, into existing product lines for process optimization, countering the threat from new entrants offering modular freeze-drying systems. Invest in robust certification processes, including CE marking and FDA compliance, to maintain global market access against evolving regulatory mandates.
For New Entrants and Emerging Players: A significant price-point gap exists between high-end freeze dehydrators and conventional tray units, creating white space. Target the development of modular freeze-drying systems specifically for small and medium-sized enterprises and prosumer markets. Focus on niche applications like nutraceutical ingredients and premium pet food products within North America and Europe. A go-to-market strategy should emphasize the superior nutritional retention and product quality achievable with advanced preservation technologies.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs and R&D for advanced technologies create barriers to entry. The long-term viability of this market is strong, driven by global food waste reduction mandates and consumer demand for clean-label products. Identify specialized freeze-drying technology providers or companies with strong intellectual property in energy-efficient designs as prime acquisition targets. Practitioners should monitor increased merger and acquisition activity among smaller, innovative equipment manufacturers for early signals.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D Investment in Energy Efficiency | This reduces operational costs for end-users, enhancing equipment competitiveness against evolving EU Green Deal standards. |
| Strategic Partnerships with Food Processors | These collaborations facilitate co-development of application-specific drying solutions and secure long-term demand for equipment. |
| Geographic Expansion into Emerging Markets | This captures new growth in agricultural regions like Brazil, leveraging demand for processing tropical fruits. |
| Product Line Diversification into Modular Systems | This addresses the needs of small-batch producers and professional kitchens, decentralizing advanced preservation capabilities. |
| Technology Licensing for Smart Automation | This integrates AI-driven process control, optimizing drying cycles and offering predictive maintenance to end-users. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Primary research involved discussions with food processing executives, restaurant owners, equipment engineers, and regulatory compliance officers. Secondary data sources included FDA publications, EFSA reports, UN Sustainable Development Goal reports, and national trade statistics. The analysis employed both bottom-up market sizing and top-down validation to ensure data accuracy.
The forecast window was anchored to historical reference periods, establishing a robust baseline for future projections. The analytical framework considered both demand-side drivers and supply-side constraints across the modeling period. Segmentation dimensions modeled included product type, application, end-user, and regional regulatory environment. Compound Annual Growth Rates were derived from a comprehensive growth model, factoring in market dynamics. Forecast inputs included global food waste reduction targets and the anticipated volume of clean-label product launches.
Caveats apply where unforeseen energy price spikes or rapid shifts in global trade policies could materially shift the outlook. Forecasts reflect assumptions regarding technological advancements and regulatory stability over the projection horizon. Practitioners should monitor technological breakthroughs in drying efficiency and evolving international trade agreements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Sword Feeders Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Sheet Metal Processing Equipment Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Water Cooled Cube Ice Machines Market
Food Processing Equipment
Pan Feeder Market