
 High-Pressure Processing Equipment Market | 2026-2036
High-Pressure Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
High-Pressure Processing Equipment Market Analysis
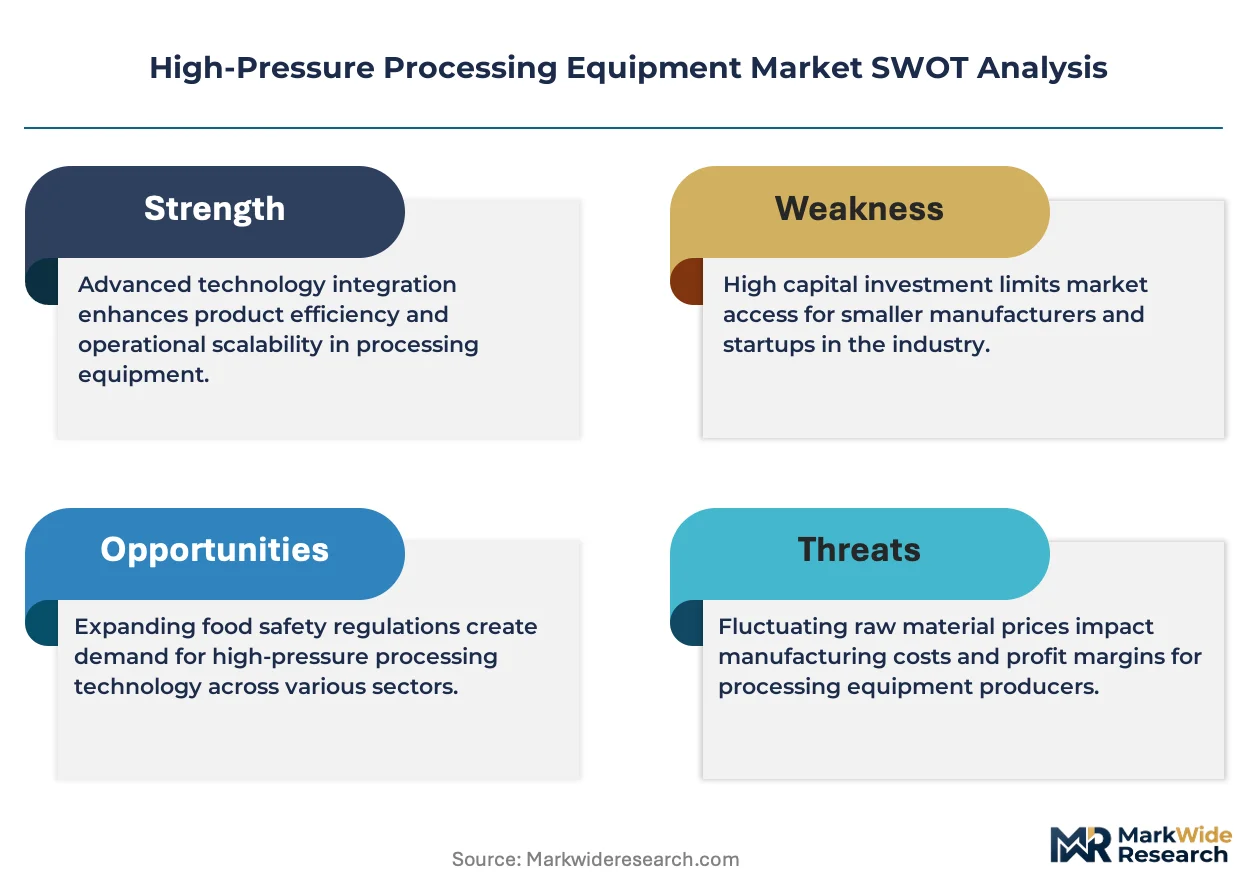
Foodservice distribution channels are reconfiguring as cold-chain logistics providers integrate HPP tolling into their service portfolios. Hiperbaric S.A. leverages its Spanish manufacturing base to anchor European fresh-protein processing lines. JBT Corporation sustains a dominant position in North American poultry and juice system installations. Thyssenkrupp AG competes through its precision-engineered pressure vessel expertise inherited from industrial forging operations.
High-pressure processing equipment subjects food, pharmaceutical, and biotech materials to isostatic pressures between 100 and 600 MPa at ambient or moderate temperatures to inactivate pathogens and spoilage organisms without thermal degradation. Batch processors dominate current revenue as meat and juice producers favor flexible, lower-capital configurations for multi-SKU operations. Continuous processors represent the fastest-growing product category as beverage bottlers pursue throughput above 10,000 liters per hour. Laboratory machines occupy a stable niche serving process development and regulatory validation workflows for pharmaceutical and nutraceutical clients.
The FDA's juice HACCP regulation and USDA-FSIS Listeria control guidelines shape equipment specifications for U.S. meat and juice installations. EFSA's scientific opinions on HPP efficacy against vegetative pathogens inform CE-marking requirements and commercial adoption thresholds across EU member states. ISO 9001 and 3-A Sanitary Standards compliance has become a baseline procurement filter for multinational food manufacturers. Stakeholders must monitor evolving pathogen-resistance research and energy-efficiency benchmarks as these criteria increasingly determine equipment replacement cycles and facility expansion decisions.
Market Dynamics
The clean-label imperative is forcing food and beverage processors to replace thermal pasteurization with non-thermal alternatives, creating a structural pull on high-pressure processing equipment capacity that outpaces current manufacturing throughput.
Growth Catalysts
- USDA-FSIS Listeria Control Guidelines:The USDA's mandatory post-processing lethality standards for ready-to-eat meats compel processors to install HPP systems as a validated kill step, directly expanding the installed base in North American protein facilities.
- Cold-chain logistics integration:Third-party cold storage operators in the United States are embedding HPP tolling services into their warehouse offerings, lowering capital barriers for mid-size juice and guacamole brands.
- Plant-based protein processing:Alternative meat manufacturers utilize HPP to extend shelf life without chemical preservatives, matching the clean-label positioning that drives their category differentiation.
Market Restraints
- Pressure vessel steel volatility:Specialized forged alloy requirements for 600 MPa containment systems tie equipment margins to aerospace and energy sector demand cycles for high-grade metallurgy.
- European supplier concentration:Precision-engineered intensifier pump manufacturing clusters in Germany and Spain create single-source dependencies for North American and Asian system integrators.
- Batch processing throughput ceilings:Current vessel-based architectures impose fundamental limits on economies of scale for high-volume beverage bottlers, constraining addressable market expansion.
Strategic Opportunities
- Pharmaceutical aseptic filling:Biologics manufacturers are piloting HPP for terminal sterilization of parenteral solutions, opening a compliance-driven segment with premium pricing tolerance.
- India FSSAI clean-label mandates:India's food safety regulator is tightening additive restrictions in processed foods, creating regulatory pull for HPP adoption in Mumbai and Delhi NCR manufacturing zones.
- Continuous processing R&D:Converging developments in ceramic valve engineering and real-time pressure telemetry are enabling semi-continuous architectures that bridge batch flexibility with line-speed economics.
Industry Challenges
- 3-A Sanitary Standards certification timelines:Multinational food manufacturers require third-party hygienic design validation that extends procurement cycles by six to twelve months for custom vessel configurations.
- High-pressure physics specialization:Equipment operators and maintenance technicians with expertise in isostatic compression dynamics remain scarce relative to thermal processing skill pools, inflating training costs.
- Legacy SCADA integration:Brownfield facilities face protocol translation complexity when connecting HPP control systems to existing MES and ERP architectures, delaying commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Pressure Processing Equipment Market |
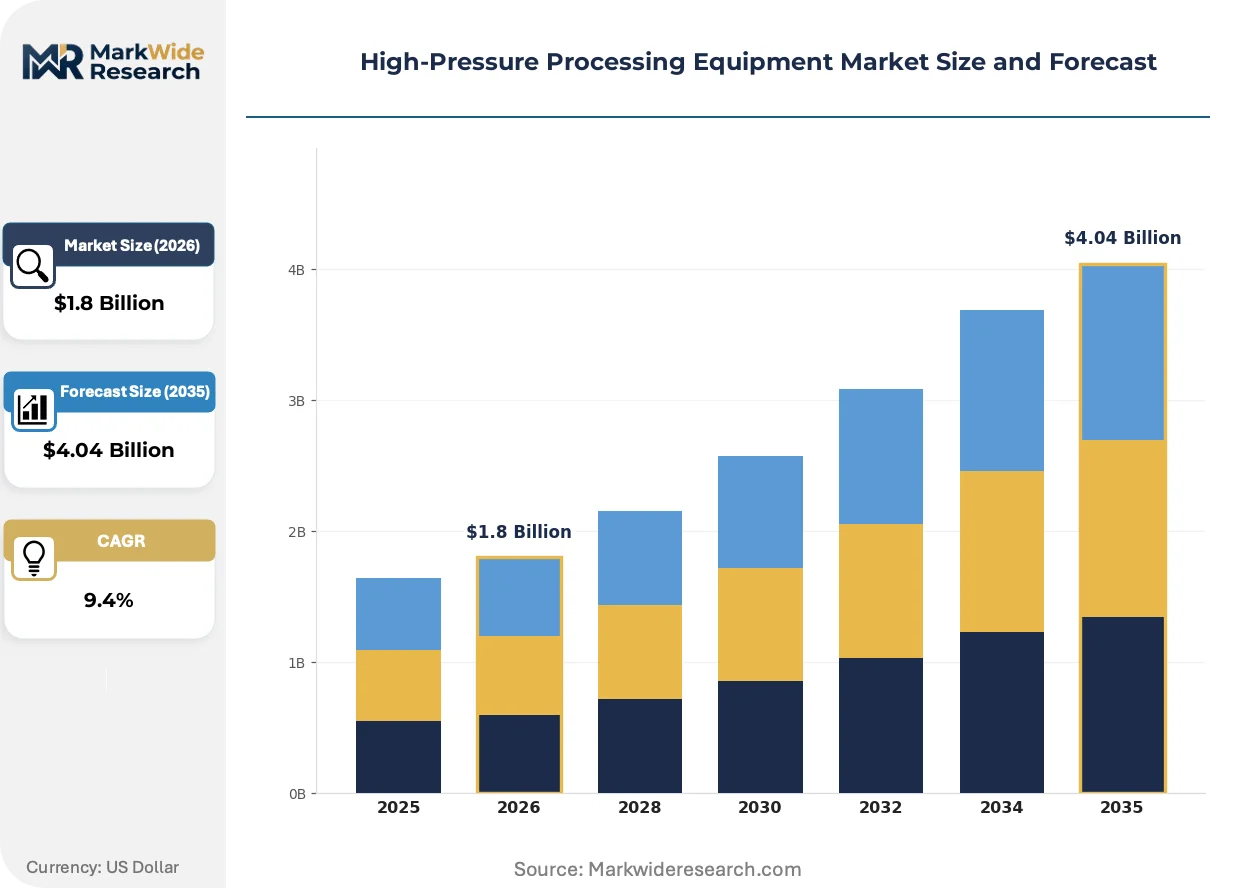
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Processors, Continuous Processors, Laboratory Machines, Industrial Systems End User: Food & Beverage, Biotechnology, Pharmaceuticals, Nutraceuticals Application: Pasteurization, Preservation, Extraction, Texturization Technology: Cold Water, Hot Water, Liquid CO2, Compressed Gas |
| Companies Covered | Hiperbaric S.A., JBT Corporation, Thyssenkrupp AG, Multivac Sepp Haggenmüller SE & Co. KG, Kobe Steel Ltd., Quintus Technologies AB, Bao Tou KeFa High Pressure Technology Co., Ltd., Chic FresherTech, Stansted Fluid Power Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Pressure Processing Equipment Market Emerging Trajectories
Digital twin technology is virtualizing equipment commissioning and process validation workflows, compressing time-to-market for new HPP installations while reducing physical prototyping requirements.
Digital twin platforms replicate pressure vessel fatigue cycles and seal degradation patterns before physical build, allowing equipment builders to optimize maintenance intervals. Food safety laboratories in the Netherlands and California are adopting these virtual environments for regulatory submission pre-validation. This capability is virtualizing the traditional pilot-plant phase, enabling faster scale-up from bench to production.
EFSA's updated scientific opinions on HPP efficacy against non-proteolytic Clostridium botulinum are tightening validation requirements for vacuum-packed seafood across EU member states. Equipment purchasers in Spain and Portugal must now demonstrate spore inactivation kinetics beyond prior vegetative-pathogen standards. CE-marking timelines have extended accordingly, favoring suppliers with established regulatory dossiers.
Refrigerated ready-to-eat brands are unbundling equipment ownership from processing service, contracting toll HPP at regional cold-chain hubs rather than captive installation. This asset-light model concentrates volume with logistics operators in the US Southeast and California Central Valley. Protein processors in these corridors now specify equipment compatibility with multi-tenant operational protocols during vendor selection.
High-Pressure Processing Equipment Market Segmentation
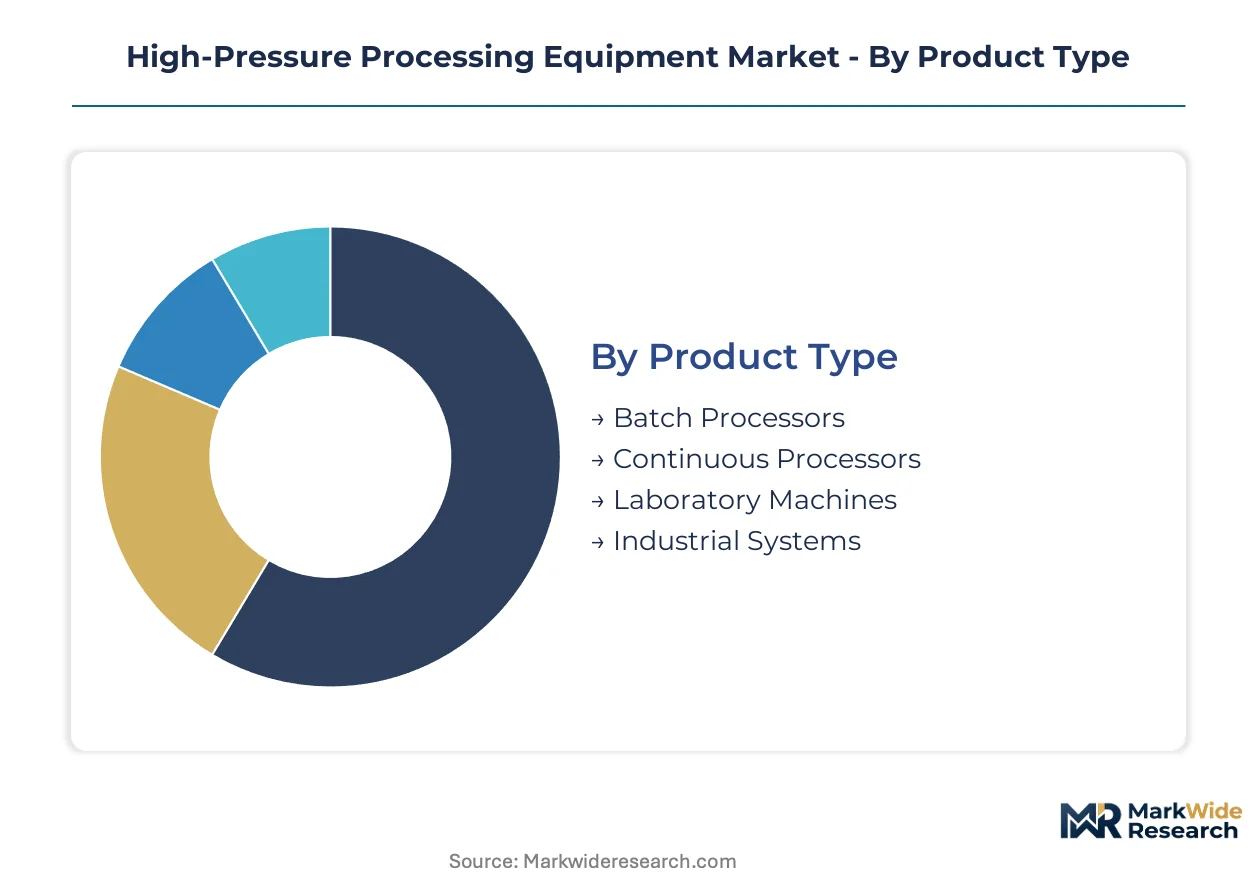
Equipment segmentation in high-pressure processing reflects divergent capital intensity, throughput requirements, and regulatory validation burdens across protein, beverage, and pharmaceutical verticals. Purchase decisions hinge on vessel capacity, pressure range, and integration complexity with existing production lines.
Product Type:
After-sales service intensity varies sharply across vessel architectures, with batch systems demanding frequent seal replacement and intensifier maintenance while continuous lines require specialized ceramic valve servicing.
- Batch Processors:Vessel-based systems accommodate flexible product loads between 100-600 MPa through discrete processing cycles. Meat and juice producers in the United States favor these configurations for multi-SKU operations where changeover frequency outweighs throughput optimization.
- Continuous Processors:Pump-driven architectures sustain isostatic pressure through sealed product flow paths, enabling beverage bottlers to exceed 10,000 liters per hour. Demand concentrates with large-scale juice brands in California and Florida seeking line-speed economics without thermal degradation.
- Laboratory Machines:Bench-scale units serve process development and regulatory validation workflows for pharmaceutical clients.
- Industrial Systems:Integrated production lines combine pressure generation, material handling, and automated controls for dedicated high-volume facilities.
Batch processors hold the largest share; momentum sits with continuous processors.
End User:
Cost tier stratification separates commodity food processors from premium-priced pharmaceutical installations, with biotechnology occupying an intermediate position on validation stringency and equipment specification.
- Food & Beverage:Protein processors and juice bottlers deploy HPP for pathogen inactivation and shelf-life extension without chemical preservatives. USDA-FSIS Listeria control guidelines compel ready-to-eat meat facilities to install validated kill-step systems.
- Pharmaceuticals:Biologics manufacturers pilot terminal sterilization for parenteral solutions, requiring aseptic filling integration and FDA compliance documentation that extends procurement cycles.
- Biotechnology:Cell lysate preparation and enzyme activation applications drive demand from research-scale through commercial bioprocessing.
- Nutraceuticals:Botanical extract processors utilize HPP for bioactive compound preservation without solvent residues.
Food and beverage dominates installed base value; pharmaceuticals show the steepest expansion trajectory on premium pricing tolerance.
Application:
Volume concentration aligns with pasteurization demand from refrigerated ready-to-eat brands, while extraction applications gain share in botanical and alternative protein processing.
- Pasteurization:Non-thermal pathogen inactivation for meat, juice, and dairy products represents the core commercial application, with EFSA efficacy opinions shaping EU validation requirements.
- Preservation:Spoilage organism suppression enables clean-label shelf-life extension for guacamole, dips, and wet salads distributed through US cold-chain networks.
- Extraction:Pressure-assisted recovery of bioactive compounds from plant matrices serves nutraceutical and functional food formulators.
- Texturization:Protein structure modification creates alternative meat textures without thermal denaturation.
Pasteurization commands the majority of unit placements; extraction is climbing the fastest on plant-based protein investment.
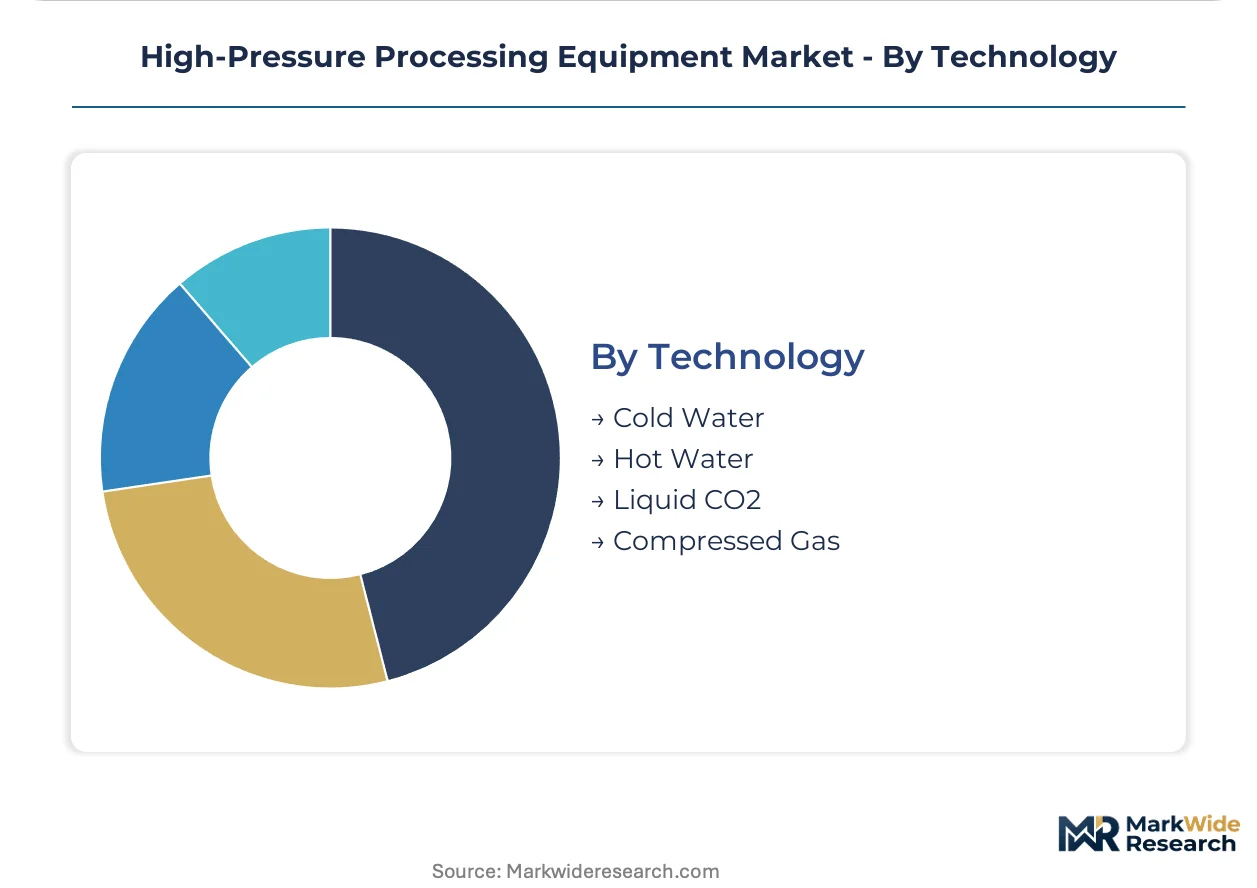
Technology:
Supply concentration for precision intensifier pumps in Germany and Spain creates geographic dependencies that influence technology selection and maintenance access.
- Cold Water:Ambient-temperature isostatic compression dominates commercial installations, preserving heat-sensitive nutrients and flavors in premium juice and meat products.
- Hot Water:Elevated-temperature pressure treatment addresses spore-forming organisms in vacuum-packed seafood, with EFSA tightening validation standards for non-proteolytic Clostridium botulinum.
- Liquid CO2:Supercritical fluid extraction systems serve specialized pharmaceutical and nutraceutical applications requiring solvent-free processing.
- Compressed Gas:Nitrogen or inert gas pressure media enable specific texturization and preservation effects in niche food applications.
Cold water systems anchor current revenue; hot water configurations are gaining share fastest on seafood safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Spanish manufacturing clusters where precision forging and intensifier pump engineering command premium positioning, while North American demand growth outpaces domestic fabrication capacity and drives import dependency.
United States
Refrigerated ready-to-eat meat brands and cold-pressed juice bottlers anchor equipment demand across California's Central Valley and the Southeast poultry corridor. USDA-FSIS Listeria control guidelines mandate validated kill-step installations for post-processing lethality compliance. Cold-chain logistics operators in Georgia and Florida now embed HPP tolling into warehouse service portfolios, lowering capital barriers for mid-size processors.
Germany
Precision-engineered pressure vessel manufacturing and intensifier pump production concentrate in industrial forging centers with aerospace metallurgy heritage. EFSA scientific opinions on HPP efficacy against vegetative pathogens inform CE-marking thresholds that German fabricators design toward. The Baden-Württemberg engineering cluster supplies critical high-pressure components to system integrators across EU member states.
Spain
Fresh-protein processing lines and vacuum-packed seafood installations drive demand along the Mediterranean coast where EFSA's tightened non-proteolytic Clostridium botulinum standards extend validation timelines. Basque Country manufacturing facilities anchor European HPP equipment supply for protein processors. Barcelona and Valencia serve as regulatory submission hubs for CE-marking dossiers.
India
Mumbai and Delhi NCR manufacturing zones face tightening FSSAI clean-label mandates that restrict chemical preservatives in processed foods. Alternative protein startups and traditional dairy processors pilot HPP installations for shelf-life extension without additive dependency. Maharashtra's food processing parks attract equipment vendors establishing regional service capabilities.
China
Yangtze River Delta beverage bottlers and Pearl River Delta seafood processors evaluate HPP adoption as SAMR tightens food safety enforcement. Domestic forging capacity for 600 MPa containment vessels remains limited, creating procurement bottlenecks for local system builders. Shandong Peninsula seafood exporters seek HPP validation for EU market access compliance.
High-Pressure Processing Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in forging and intensifier pump engineering. Market structure shows moderate consolidation with three to five dominant system builders capturing majority installed base value while precision component supply concentrates in German and Spanish industrial clusters. Two strategic archetypes define competitive positioning: vertically integrated vessel fabricators with metallurgical heritage, and modular system assemblers sourcing pressure generation subsystems. Capacity expansion and regulatory dossier accumulation represent the dominant competitive moves as CE-marking and FDA validation timelines extend procurement cycles.
Within the European manufacturing tier, Hiperbaric S.A. and Thyssenkrupp AG exemplify contrasting archetypes—Spanish platform integration versus German precision-engineered component heritage. JBT Corporation anchors North American market presence through poultry and juice system installations. These three occupy positions spanning vessel fabrication, intensifier pump supply, and integrated system delivery across the value chain.
| Leading Market Players |
|---|
| Hiperbaric S.A. |
| JBT Corporation |
| Thyssenkrupp AG |
| Multivac Sepp Haggenmüller SE & Co. KG |
| Kobe Steel Ltd. |
| Quintus Technologies AB |
| Bao Tou KeFa High Pressure Technology Co., Ltd. |
| Chic FresherTech |
| Stansted Fluid Power Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in precision-forged pressure vessel fabrication across the Baden-Württemberg and Basque Country clusters is compressing lead times and amplifying pricing power for German and Spanish component suppliers serving North American system integrators.
Pricing Analysis
The customization-premium spread separates standard 100-300 MPa batch configurations from 600 MPa continuous systems engineered to USDA-FSIS lethality validation standards. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade intensity, with FDA-compliant systems commanding substantial premiums over CE-marked equivalents. Cost compression in mid-capacity batch vessels is intensifying because Chinese fabricators are entering the 300 MPa segment. Protein processors in the US Southeast show highest price sensitivity due to tolling-model adoption, while pharmaceutical biologics manufacturers demonstrate least sensitivity given aseptic filling integration requirements.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for North American equipment assemblers sourcing precision intensifier pumps. Manufacturing gravity centers on Germany, Spain, and Japan for critical subsystems. Forged alloy pressure vessels draw from aerospace-qualified metallurgy suppliers, ceramic valve components rest on Japanese precision ceramics networks, and control systems feed from German automation engineering clusters. Single-source vulnerability concentrates in 600 MPa intensifier pump assemblies where two Baden-Württemberg specialists control proprietary architectures. Distribution runs through direct OEM sales for large protein processors and third-party cold-chain logistics operators for mid-size juice and guacamole brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for seal replacement and intensifier maintenance are expanding faster than hardware shipments as tolling-model adoption concentrates operational expertise with logistics operators rather than captive food processors.
For Market Incumbents: Insulate installed base value by embedding predictive maintenance telemetry into legacy vessel fleets before modular system assemblers capture retrofit opportunities. Deepen backward integration into 600 MPa forged alloy supply through exclusive offtake agreements with aerospace metallurgy suppliers, neutralizing price volatility in pressure vessel steel. For New Entrants and Emerging Players: Establish a beachhead in Indian FSSAI-mandated clean-label processing zones where domestic fabrication capacity lags regulatory enforcement timelines. Target Maharashtra food processing parks with compact batch systems designed for dairy and alternative protein startups lacking capital for continuous line investment. Lead with regulatory submission support bundled into equipment procurement to differentiate against established vendors with extended CE-marking queues. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among system integrators with captive aftermarket service networks serving tolling operators in the US Southeast and California Central Valley. Long-term viability favors precision component specialists with regulatory dossier depth over pure-play vessel fabricators vulnerable to Chinese capacity expansion. Watch EFSA scientific opinion updates on spore-forming organism validation as the signal indicating premium pricing endurance for hot-water system architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Accumulation | CE-marking and FDA validation timelines extend procurement cycles, favoring suppliers with established submission histories. |
| Aftermarket Service Network Expansion | Predictive maintenance contracts capture recurring revenue from tolling-model operators concentrating fleet ownership. |
| Continuous Processing R&D Investment | Ceramic valve engineering advances enable semi-continuous architectures bridging batch flexibility with line-speed economics. |
| Backward Integration into Metallurgy | Exclusive forged alloy supply agreements neutralize aerospace sector demand-cycle volatility for pressure vessel margins. |
| Digital Twin Platform Deployment | Virtual commissioning compresses time-to-market for new installations while reducing physical prototyping requirements. |
Methodological Framework
A standing panel of equipment maintenance directors, cold-chain logistics operators, protein processing plant engineers, and regulatory affairs specialists provided ongoing calibration against operating reality. Primary interviews with these stakeholders combined with secondary validation from USDA-FSIS guidance documents, EFSA scientific opinions, FDA juice HACCP regulations, and ISO 9001 certification databases. Bottom-up vessel shipment tallies triangulated against top-down food and beverage capital expenditure disclosures.
Scenario-bracketing framed demand projections across the analysis window, modeling base, optimistic, and constrained cases for clean-label adoption rates and regulatory enforcement intensity. Segmentation dimensions included product architecture, pressure range tier, end-use vertical, and geographic regulatory cluster. CAGRs were derived from equipment shipment trajectories weighted by average selling price evolution. Forecast inputs incorporated cold-chain logistics integration rates and pharmaceutical aseptic filling pilot program expansion.
Stress conditions across pressure vessel steel price volatility, EFSA validation timeline extension, and Indian FSSAI enforcement pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory adoption curves and metallurgy supply elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
North America Multi Cooker Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Hygienic Easy to Clean Food Processing Equipment Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Fish Cutting Machine Market