
 Potato Processing Market | 2026-2036
Potato Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Processing Market Analysis
Modified starch formulations is recalibrating cost structures across dehydrated potato products. McCain Foods Limited leverages its vertically integrated supply chain from seed potato to frozen fry distribution. Lamb Weston Holdings, Inc. anchors North American food service channels through dedicated quick-service restaurant partnerships. J.R. Simplot Company differentiates via proprietary potato varieties bred for specific frying performance and solids content.
Potato processing transforms raw tubers into shelf-stable or ready-to-cook products through washing, peeling, cutting, thermal treatment, and packaging operations, with moisture content, reducing sugar levels, and oil uptake serving as critical quality parameters governing final texture and shelf life. Frozen fries dominates value generation due to per-unit premiums and food service contract volumes, while starch extraction captures industrial margin pools through supply to paper, textile, and pharmaceutical binders. Dehydrated flakes competes on cost efficiency in institutional and ingredient channels where reconstitution speed matters.
USDA grading standards and FDA food safety rules govern allowable defect levels and pathogen controls across interstate commerce, while EU F-Gas Regulation mandates refrigerant transitions that raise capital costs for frozen product cold chains. Stakeholders must monitor how refrigerant phase-down timelines intersect with processing capacity expansion decisions.
Market Dynamics
EU F-Gas Regulation mandates refrigerant phase-down timelines that intersect directly with frozen fry capacity expansion decisions, forcing processors to synchronize capex cycles with compliance deadlines rather than pure demand signals.
Growth Catalysts
- Quick-service restaurant procurement:Chain operators are consolidating frozen fry contracts into multi-year supply agreements that lock in volume commitments and prioritize suppliers with certified cold-chain integrity.
- REACH-compliant modified starch:Paper and pharmaceutical binder applications are absorbing potato-derived starch as EU chemical safety standards displace synthetic alternatives in industrial formulations.
- German processing clusters:Industrial concentration around Lower Saxony and Bavaria generates network economies that reduce per-unit logistics costs for central European distribution.
Market Restraints
- Input cost volatility:Natural gas prices govern thermal processing economics for dehydration and frying operations, exposing margin structures to energy market fluctuations.
- Seed potato supply concentration:Elite germplasm for frying-grade varieties remains controlled by a narrow band of breeders in the Netherlands and Germany, creating varietal access bottlenecks.
- Reducing sugar management:Cold-induced sugar accumulation in stored tubers limits fry color consistency, requiring controlled-atmosphere storage investments that raise working capital intensity.
Strategic Opportunities
- Plant-based protein extraction:Potato protein isolate production from processing waste streams is attracting ingredient channel investment as food formulators seek allergen-free emulsifiers.
- India cold-chain buildout:Quick-service restaurant penetration in tier-2 cities is creating demand for frozen fry distribution infrastructure that local processors can anchor.
- EU Green Deal bioeconomy incentives:Starch valorization into biodegradable packaging films qualifies for circular economy funding that improves project IRRs.
Industry Challenges
- Refrigeration technician scarcity:F-Gas-certified service capacity is contracting as phase-down complexity rises, extending equipment downtime risks during peak harvest windows.
- Legacy ERP integration:Traceability mandates from FDA Food Safety Modernization Act rules require retrofitting batch-tracking modules into decades-old process control architectures.
- Water stewardship compliance:Starch extraction effluent treatment must meet tightening EPA discharge permits that demand membrane filtration capex at Midwestern US facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Processing Market |
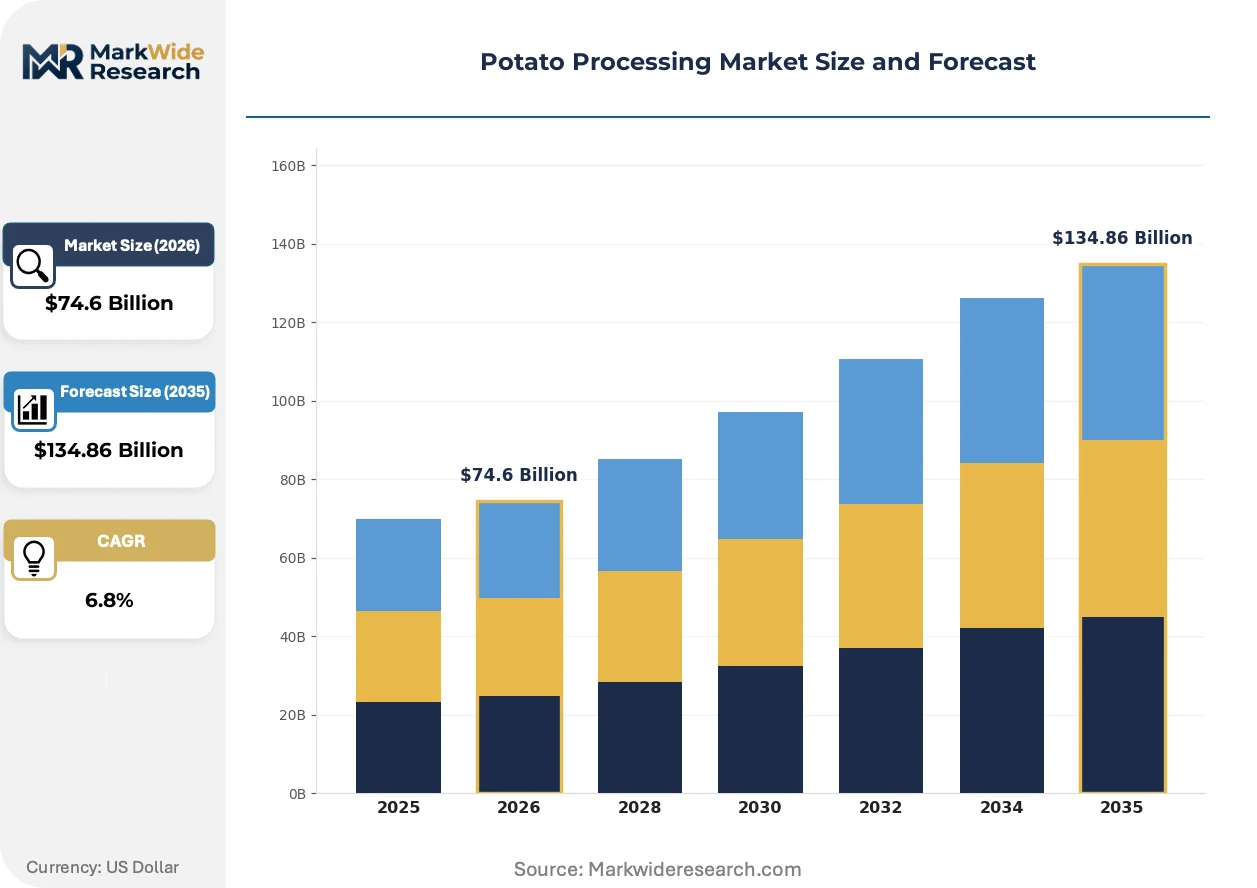
| Market Size in 2026 | $74.6 Billion |
| Market Size in 2035 | $134.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fries, Chips, Flakes, Starch Technique: Frying, Dehydration, Boiling, Baking Packaging Type: Bags, Boxes, Cartons, Pouches End User: Food Service, Retail, Food Processing, Catering |
| Companies Covered | Aviko B.V., The Kraft Heinz Company, McCain Foods Limited, Farm Frites International, Idahoan Foods, Lamb Weston Holdings, Inc., Cavendish Farms Corporation, Agristo, J.R. Simplot Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Processing Market Emerging Trajectories
Processing equipment architectures and ingredient specifications are converging around resource efficiency mandates that reward closed-loop water systems and waste-to-value configurations.
Advanced sorting vision systems is modularizing quality control workflows across washing and cutting lines. Mid-scale processors in Poland and Belgium are retrofitting hyperspectral cameras that detect internal defects without destructive sampling. The technology is modularizing capital deployment by allowing staged upgrades rather than full line replacements.
EU F-Gas Regulation is compressing the installed base of hydrofluorocarbon refrigeration systems through mandated service bans and recharge restrictions. Frozen storage operators face accelerated depreciation schedules as natural refrigerant retrofits become economically unavoidable. German cold-chain infrastructure is responding fastest through ammonia-CO2 cascade system adoption.
Contract structures are shortening procurement cycles for dehydrated potato ingredients as food manufacturers reduce inventory exposure to agricultural commodity volatility. Instant mashed potato brands are shifting from annual tenders to quarterly price negotiations indexed to futures markets. This pattern is most pronounced in UK retail channels where private-label concentration amplifies buyer leverage.
Potato Processing Market Segmentation
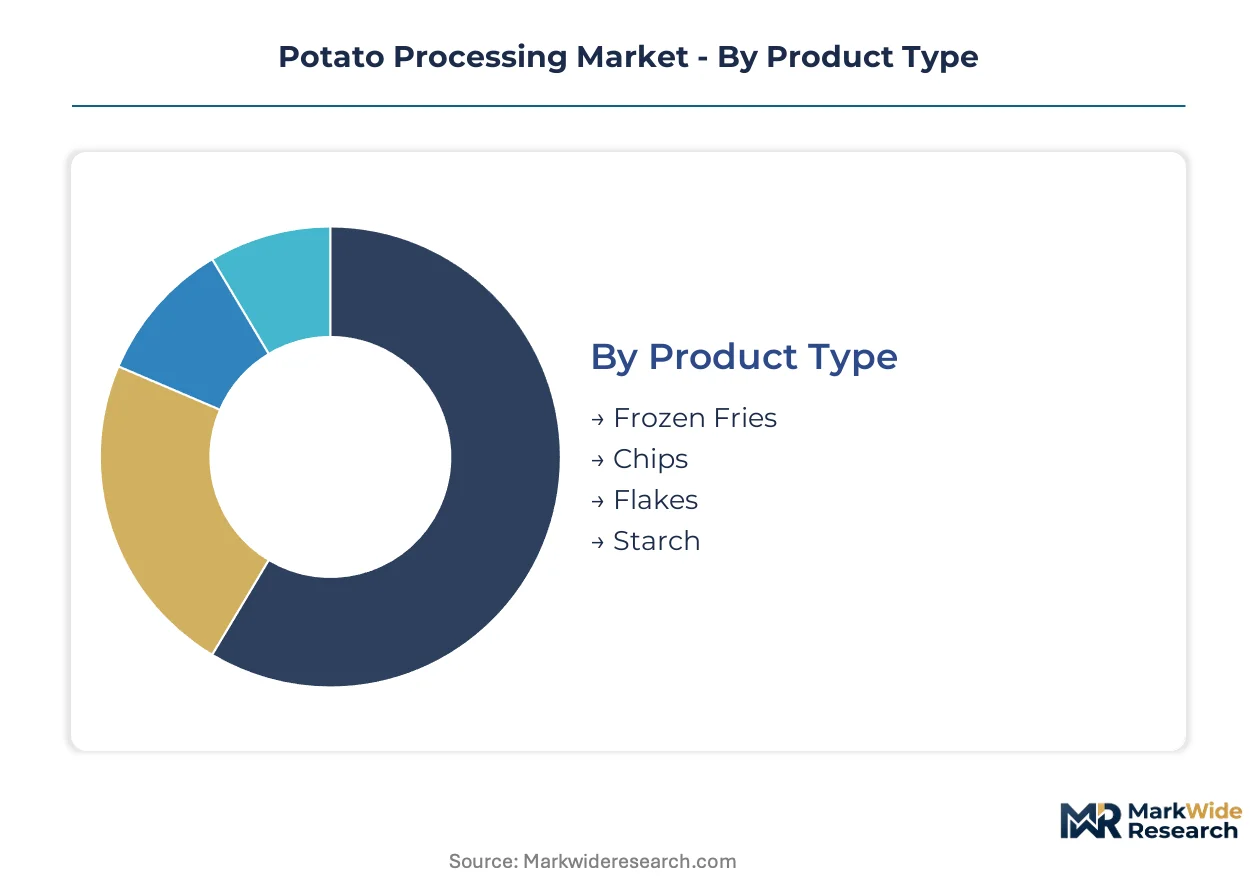
Segmentation in potato processing reveals how regulatory compliance burdens and capital intensity vary sharply across product formats and customer channels. Processors must align certification investments with segment-specific margin profiles to optimize resource allocation.
Product Type:
Frozen fries and starch extraction face divergent regulatory pathways—frozen products trigger FDA cold-chain rules and EU F-Gas refrigeration mandates, while starch enters industrial chemical compliance under REACH and food-grade purity standards.
- Frozen Fries:Par-fried potato strips blast-frozen at minus 18 degrees Celsius retain texture through reconstitution. Quick-service restaurant chains in Germany and the Netherlands dominate procurement volumes, with multi-year supply agreements locking in cold-chain integrity certifications.
- Chips:Thin-sliced tubers fried or baked to specific moisture content thresholds for shelf stability. Retail private-label concentration in UK and French supermarkets drives formulation standardization and packaging format flexibility requirements.
- Flakes:Drum-dried or extruded dehydrated potato with rapid reconstitution properties. Institutional food manufacturers in North American and Scandinavian markets absorb output for instant mashed potato applications where labor cost reduction matters.
- Starch:Extracted amylose and amylopectin fractions serving paper, textile, and pharmaceutical binder channels. EU Green Deal bioeconomy incentives are redirecting investment toward biodegradable packaging film applications.
Frozen fries sits at the top of the volume ranking, with starch climbing the fastest as industrial formulation substitution accelerates.
Technique:
Processing technique selection determines energy intensity profiles and equipment depreciation schedules, with thermal methods exposed to natural gas price volatility while non-thermal alternatives carry higher upfront capital requirements.
- Frying:Oil-immersion cooking at 175-185 degrees Celsius creates Maillard reaction products for flavor development. Continuous fryer lines in Belgian and Dutch processing clusters achieve economies through shared oil filtration and waste heat recovery systems.
- Dehydration:Moisture reduction via drum drying, spray drying, or air drying to sub-ten-percent water content. Energy costs govern location decisions, with processors migrating toward geothermal-powered facilities in Iceland and Kenya where available.
- Boiling:Pre-cooking for mashed potato and salad applications requiring precise texture control. Ready-meal manufacturers in France and Japan specify boil intensity parameters that dictate varietal selection and harvest timing.
- Baking:Dry-heat processing for reduced-fat chip alternatives and whole-tuber convenience formats. Health-positioned retail channels in California and Australian metro markets absorb premium-priced output despite longer cycle times.
Frying commands the largest installed capacity base, though dehydration is expanding most quickly as ingredient channel demand concentrates.
Packaging Type:
Packaging format selection intersects with distribution channel requirements and shelf-life specifications, with food service bulk formats minimizing unit costs while retail configurations prioritize shelf impact and resealability.
- Bags:Flexible polymer or paper laminate structures for retail chip and flake distribution. Modified atmosphere gas flushing extends shelf life, with nitrogen injection systems now standard in German and Polish packaging lines.
- Boxes:Corrugated fiberboard containers for frozen fry bulk shipments to quick-service restaurant distribution centers. Stack height and compression strength specifications vary by chain operator, requiring format customization.
- Cartons:Rigid paperboard for premium retail positioning and institutional portion control. Scandinavian retail channels favor recyclable carton formats under extended producer responsibility frameworks.
- Pouches:Stand-up and flat flexible formats for dehydrated ingredients and single-serve convenience. Retort-capable pouch structures are penetrating Indian and Southeast Asian ambient distribution channels.
Boxes dominate food service throughput, with pouches gaining share fastest in emerging market retail expansion.
End User:
End-user channel concentration shapes pricing power and contract structure, with food service consolidation enabling volume commitments while retail fragmentation demands SKU proliferation and promotional flexibility.
- Food Service:Quick-service restaurant chains, casual dining operators, and institutional cafeterias. McDonald's, Burger King, and KFC procurement offices in Chicago, Munich, and Singapore centralize frozen fry specification setting.
- Retail:Supermarket chains, convenience stores, and e-commerce grocery platforms. Private-label concentration in Tesco, Carrefour, and Ahold Delhaize systems compresses branded margin structures.
- Food Processing:Ingredient buyers for ready meals, soups, sauces, and bakery applications. Japanese and German food manufacturers specify flake particle size distributions that determine supplier qualification.
- Catering:Event service providers, airline meal suppliers, and correctional or military feeding operations. Cost-per-serving targets dominate procurement criteria with limited brand loyalty.
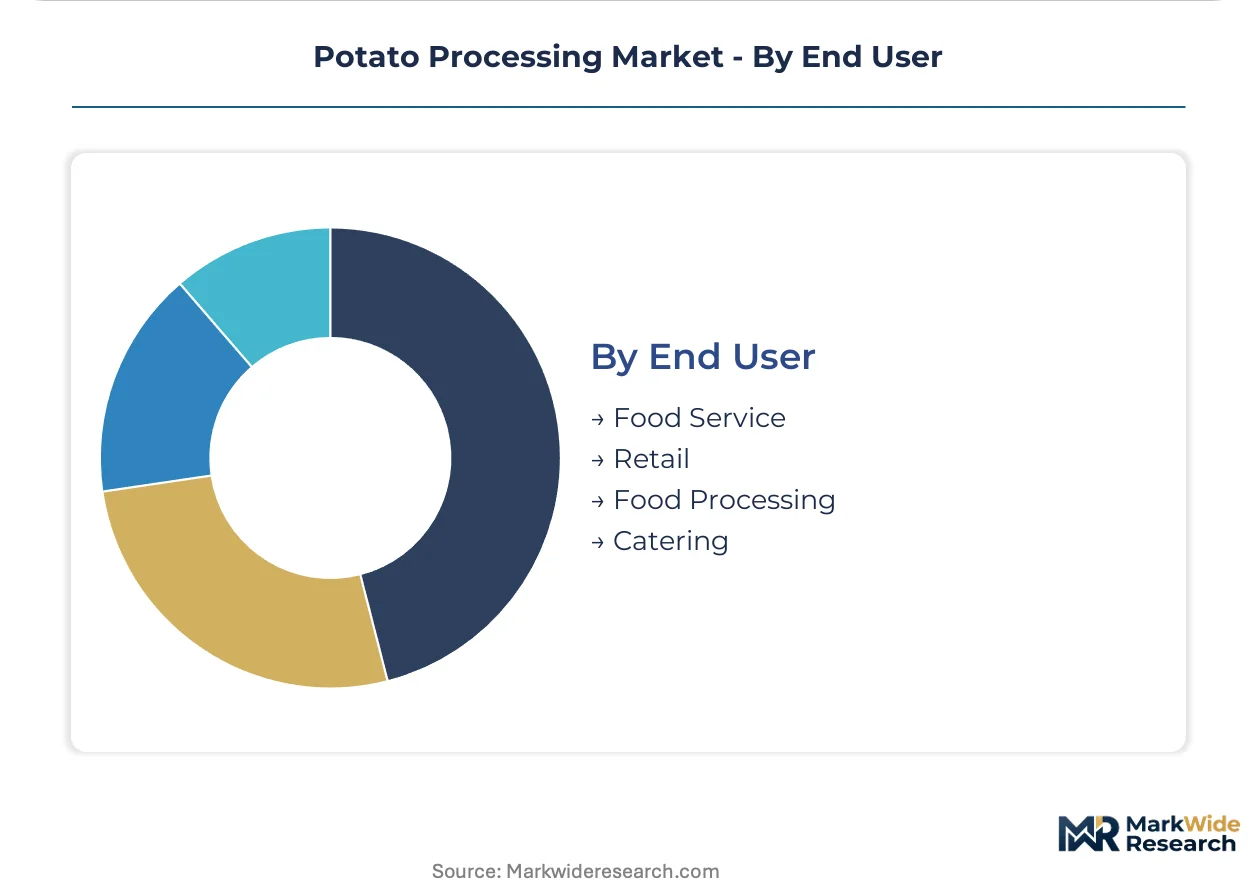
Food Service anchors volume demand, with Food Processing expanding most steeply as clean-label ingredient substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lower Saxony anchors European potato processing capacity through dense clustering of fry production facilities and starch extraction plants serving central European distribution networks.
Germany
Quick-service restaurant chains in Munich and Berlin drive frozen fry procurement volumes through multi-year supply contracts. The EU F-Gas Regulation mandates ammonia-CO2 cascade refrigeration retrofits across Bavarian cold-storage facilities. Processing concentration around Lower Saxony generates network economies that reduce per-unit logistics costs for Benelux and Polish distribution.
United States
Idaho and Washington state potato growers supply frying-grade varieties to industrial processors under varietal development agreements. FDA Food Safety Modernization Act traceability rules require batch-tracking module upgrades at Midwestern facilities. The Columbia River Basin supports dehydration operations with low-cost hydroelectric power for thermal processing.
Netherlands
Farm Frites and Aviko procurement offices in Rotterdam coordinate frozen fry exports to Asian food service channels. REACH compliance requirements govern modified starch formulations entering paper and pharmaceutical binder markets. Zeeland and Noord-Brabant host continuous fryer line clusters achieving economies through shared oil filtration infrastructure.
Belgium
Flemish processors supply par-fried strips to quick-service restaurant distribution centers under cold-chain integrity certifications. EU Green Deal bioeconomy incentives redirect starch valorization investments toward biodegradable packaging film applications. Antwerp and Ghent processing corridors specialize in retail chip formats for French and UK supermarket private-label programs.
India
Quick-service restaurant penetration in Bangalore and Hyderabad tier-2 corridors creates demand for frozen fry distribution infrastructure. FSSAI food safety standards govern allowable defect levels and pathogen controls across interstate processing operations. Gujarat and Maharashtra cold-chain buildout projects attract anchor investments from international processors seeking regional manufacturing footholds.
Potato Processing Market Vendor Landscape
Global majors compete with regional champions across frozen fry and dehydrated product lines, creating a tiered structure where scale-driven volume players coexist with specialty-focused mid-cap operators. The vendor base separates into three strategic archetypes: vertically integrated seed-to-fry conglomerates, regional processing specialists with captive raw material sourcing, and ingredient-channel pure-plays serving industrial starch applications. Competitive moves concentrate on backward integration into elite germplasm control and ammonia refrigeration retrofit partnerships that secure F-Gas compliance ahead of regulatory deadlines.
Within the scale-driven tier, McCain Foods Limited and Lamb Weston Holdings, Inc. exemplify global volume positioning through extensive quick-service restaurant contract portfolios. J.R. Simplot Company occupies a specialist position emphasizing proprietary varietal development for frying performance optimization. These three anchors represent divergent strategic paths: multi-continental manufacturing footprint, North American food service channel dominance, and upstream breeding program investment respectively.
| Leading Market Players |
|---|
| Aviko B.V. |
| The Kraft Heinz Company |
| McCain Foods Limited |
| Farm Frites International |
| Idahoan Foods |
| Lamb Weston Holdings, Inc. |
| Cavendish Farms Corporation |
| Agristo |
| J.R. Simplot Company |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates qualified supply and premium-tier pricing access for frozen fry processors, as ammonia-CO2 cascade refrigeration certification becomes a threshold condition for quick-service restaurant contract eligibility while non-compliant operators face spot-market relegation.
Pricing Analysis
Input-cost pass-through dynamics govern contract structures across frozen fry and dehydrated product lines, with natural gas and seed potato varietal premiums flowing directly into multi-year supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates F-Gas-certified cold-chain operators from conventional refrigeration facilities and uncertified spot-market suppliers. Pricing pressure stems from energy market volatility and refrigerant retrofit capex amortization. Quick-service restaurant chains exhibit lowest price sensitivity due to brand consistency requirements, while catering operators and private-label retail channels absorb margin compression most acutely.
Supply Chain Analysis
Dual-sourcing requirements from McDonald's, Burger King, and KFC procurement offices mandate multi-supplier qualification for frozen fry contracts, forcing processors to maintain parallel certification tracks across separate cold-storage facilities. Geographic supply concentrates in Germany, the Netherlands, and Belgium, where Lower Saxony and Zeeland processing clusters feed central European distribution networks. Raw material dependencies center on frying-grade seed potatoes from Dutch and German breeders, edible oils for thermal processing, and natural gas for dehydration operations. Single-source vulnerability persists in elite germplasm access controlled by narrow breeding programs. Distribution runs through quick-service restaurant distribution centers and retail consolidation platforms serving Benelux, French, and UK supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with quick-service restaurant procurement consolidation driving steady volume commitments and multi-year contract visibility across frozen fry channels.
For Market Incumbents: Lock in ammonia-CO2 cascade refrigeration partnerships ahead of EU F-Gas phase-down deadlines to secure quick-service restaurant contract renewals and foreclose competitor access to premium-tier pricing tiers. Deepen backward integration into seed potato breeding programs to reduce varietal access bottlenecks and control frying-performance specifications. Capacity addition in Gujarat and Maharashtra cold-chain infrastructure positions processors to anchor India quick-service restaurant expansion. For New Entrants and Emerging Players: Begin with biodegradable packaging film applications under EU Green Deal bioeconomy incentives, where starch valorization qualifies for circular economy funding with lower capital barriers than frozen fry manufacturing. Target tier-2 Indian cities for frozen fry distribution infrastructure partnerships, leveraging FSSAI compliance as a qualification wedge. Go-to-market angle centers on allergen-free potato protein isolate production from processing waste streams for ingredient channel buyers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional processors with captive raw material sourcing because quick-service restaurant procurement consolidation favors suppliers with certified cold-chain integrity and multi-facility redundancy. Long-term viability frames around steady institutional demand for dehydrated flakes and industrial starch applications. Acquisition target archetype: Flemish or Polish processors with established quick-service restaurant relationships and uncompleted F-Gas retrofit pipelines. Signal to watch: refrigerant technician scarcity extending equipment downtime during peak harvest windows, compressing effective capacity and accelerating distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-CO2 Cascade Refrigeration Retrofit | EU F-Gas Regulation mandates phase-down timelines that intersect with capacity expansion decisions. |
| Backward Integration into Seed Potato Breeding | Proprietary varietal development controls frying performance and solids content specifications. |
| India Cold-Chain Infrastructure Buildout | Quick-service restaurant penetration in tier-2 cities creates anchor investment opportunities. |
| Starch Valorization into Biodegradable Films | EU Green Deal bioeconomy incentives improve project returns for circular economy applications. |
| Potato Protein Isolate Production | Food formulators seek allergen-free emulsifiers from processing waste streams. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with frozen fry procurement managers at quick-service restaurant chains, plant managers at German and Dutch processing facilities, cold-chain logistics operators, and starch application specialists in paper and pharmaceutical binder channels with secondary validation. Secondary sources included EU F-Gas Regulation implementation timelines, FDA Food Safety Modernization Act traceability rules, REACH compliance documentation for modified starch formulations, customs and trade data for frozen potato product flows, and SEC filings from publicly traded processors. Bottom-up capacity and demand modeling triangulated against top-down market sizing from trade association data.
Segment-weighting approaches distributed value and volume across product type, processing technique, packaging format, and end-user channel dimensions, with frozen fry, chip, flake, and starch extraction categories receiving distinct growth trajectory assumptions. CAGRs derived from historical shipment data, capacity expansion announcements, and quick-service restaurant procurement contract visibility. Industry-specific forecast inputs incorporated natural gas price sensitivity for thermal processing economics and refrigerant retrofit capex schedules tied to EU regulatory deadlines across the projection horizon.
Several conditions sit outside the modeled scope, including abrupt seed potato disease outbreaks, trade restriction impositions on frozen fry flows, and technological disruption from alternative root vegetable formulations. Forecasts reflect documented assumptions about quick-service restaurant expansion rates and EU regulatory compliance timelines. Deviation in natural gas price volatility or F-Gas technician availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Optical Sorter Market