
 Food Waste Disposers Market | 2026-2036
Food Waste Disposers Market Size, Share, and Industry Trends Forecast 2026-2036
Food Waste Disposers Market Intelligence
EPA landfill diversion targets are repositioning municipal procurement criteria across North America. Emerson Electric leverages in-house motor manufacturing to sustain cost advantages in continuous-feed systems. Franke Holding anchors European distribution through specialized kitchen fitting networks. InSinkErator dominates North American residential channels with established plumber training programs that lock in specification preferences.
Food waste disposers are electrically powered grinding units installed beneath sinks, typically operating at 1725-3600 RPM with stainless steel impellers to pulverize organic refuse into particles small enough for wastewater transport. Their primary commercial purpose is reducing landfill-bound organic mass while lowering waste hauling frequency for foodservice operations. Continuous feed models command the largest installed base due to lower unit costs and simpler operation protocols, though batch feed variants attract safety-conscious household segments with interlocked lid mechanisms. Commercial foodservice applications generate the strongest margin pools because health code compliance demands drive replacement cycles and premium specification.
FDA food code provisions on waste handling influence commercial kitchen design standards, while EPA landfill methane regulations push municipalities toward grinder-friendly sewer infrastructure. OSHA kitchen safety guidelines affect worker exposure protocols for commercial installations. Stakeholders must monitor how building electrification codes and decarbonization mandates reshape the cost calculus between disposer-based and composting-centric waste strategies.
Market Dynamics
EPA landfill diversion mandates are restructuring municipal procurement criteria across the United States, forcing waste management authorities to prioritize grinder-compatible sewer infrastructure over traditional hauling contracts. This regulatory pressure cascades through commercial kitchen specifications and residential renovation cycles.
Growth Catalysts
- EU F-Gas Regulation:Tightening disposal standards across European member states are accelerating replacement of refrigerant-dependent waste handling equipment with electrically powered grinding systems in commercial foodservice operations.
- Restaurant chains:Centralized procurement by multi-unit operators is standardizing disposer specifications across franchise networks, creating specification lock-in that drives volume commitments to preferred suppliers.
- Stainless steel impellers:Corrosion-resistant grinding components are extending service intervals in high-volume commercial installations, reducing total cost of ownership and justifying premium pricing.
Market Restraints
- Copper motor windings:Volatility in conductive metal pricing compresses margins for manufacturers lacking backward integration into motor production.
- Batch feed safety interlocks:Complex lid-locking mechanisms add component cost and failure points, limiting adoption in price-sensitive residential segments despite superior injury prevention.
- Composting infrastructure:Municipal investments in centralized organic waste processing create substitution pressure in jurisdictions with collection logistics.
Strategic Opportunities
- India commercial kitchens:Underpenetrated foodservice equipment markets in urban centers present first-mover advantages for disposer manufacturers establishing local distribution.
- Building electrification codes:Gas-phase-out mandates in California and New York are eliminating competing thermal waste processing options, expanding addressable market for electric grinding solutions.
- Plumber training networks:Certification programs that embed specification preferences during apprenticeship create durable channel control and reduce price competition.
Industry Challenges
- OSHA kitchen safety compliance:Worker exposure protocols for commercial installation and maintenance require specialized training that strains field service capacity.
- Legacy sewer infrastructure:Aging municipal wastewater systems in older US cities restrict disposer permissibility, fragmenting addressable markets by zip code.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Waste Disposers Market |
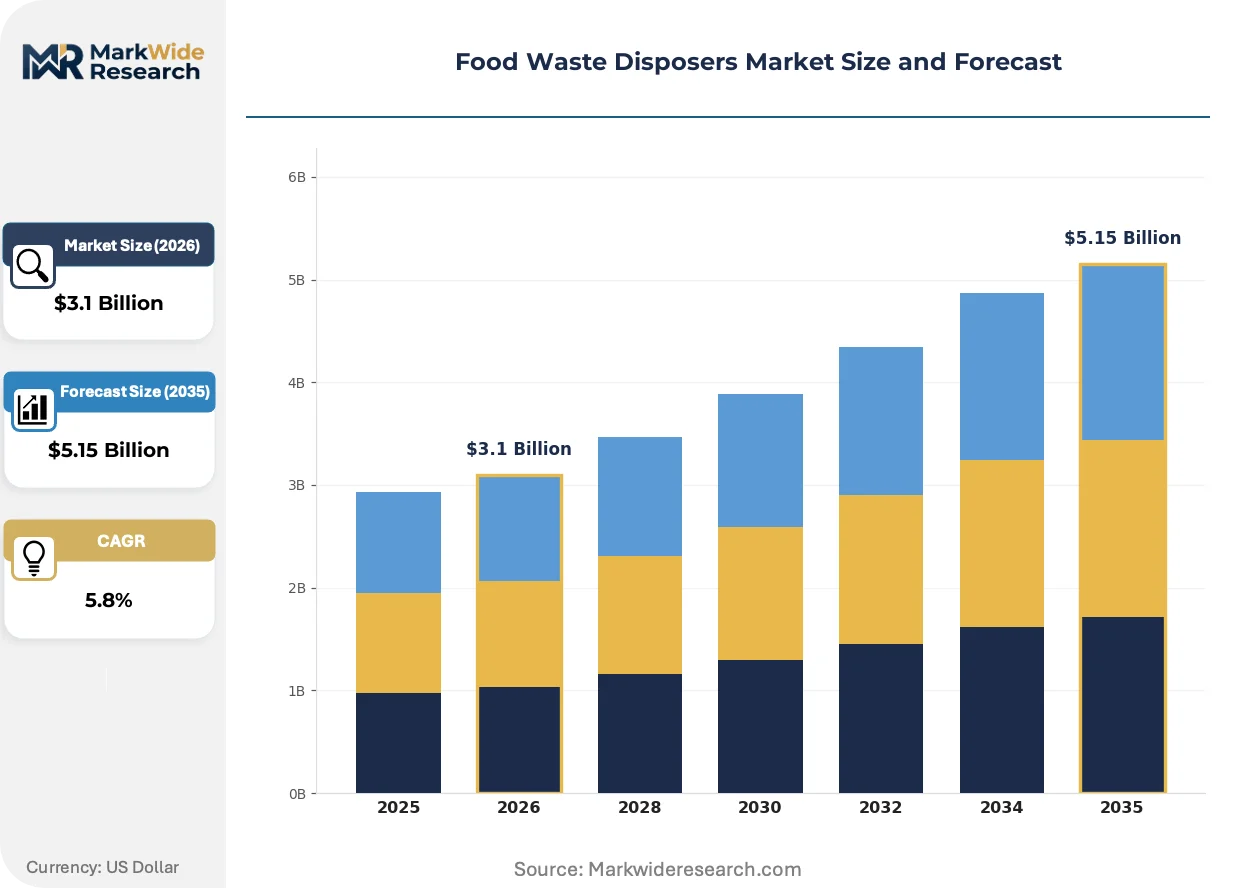
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Feed, Continuous Feed, In-Sink Models, Drain-Integrated Units Installation Type: Under-Sink Mount, Wall Mount, Countertop, Portable Application: Household Kitchens, Commercial Foodservice, Institutional Dining, Catering Operations End User: Consumers, Restaurant Chains, Educational Facilities, Corporate Cafeterias |
| Companies Covered | Moen Incorporated, Franke Holding, Emerson Electric, Hobart Corporation, Electrolux, Whirlpool, Waste King, GE Appliances, InSinkErator, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Waste Disposers Market Strategic Shifts & Innovations
Electrification mandates and connected equipment architectures are converging to redefine how food waste disposers integrate with broader building management systems. Manufacturers are responding with sensor-enabled units that communicate operational status.
Permanent magnet motor technology is absorbing market share from traditional induction designs in premium residential and commercial segments. High-torque density enables compact form factors that fit constrained cabinet spaces beneath commercial prep sinks. This shift is absorbing specification preferences among kitchen designers specifying for renovation projects where space optimization dominates.
EPA landfill methane regulations are compelling municipalities to evaluate grinder-friendly sewer infrastructure as a compliance pathway. The industrial consequence is revised procurement criteria that prioritize disposer compatibility in new construction and major renovation permits. Commercial foodservice operations in jurisdictions with active EPA enforcement are responding by accelerating equipment replacement cycles.
Specification influence is migrating from general contractors to specialized kitchen equipment distributors. Restaurant chains now route disposer purchases through authorized dealer networks that bundle installation with maintenance contracts. This channel consolidation is most visible in the United States, where consolidated foodservice equipment distributors have captured specification authority from traditional plumbing wholesalers.
Food Waste Disposers Market Segmentation
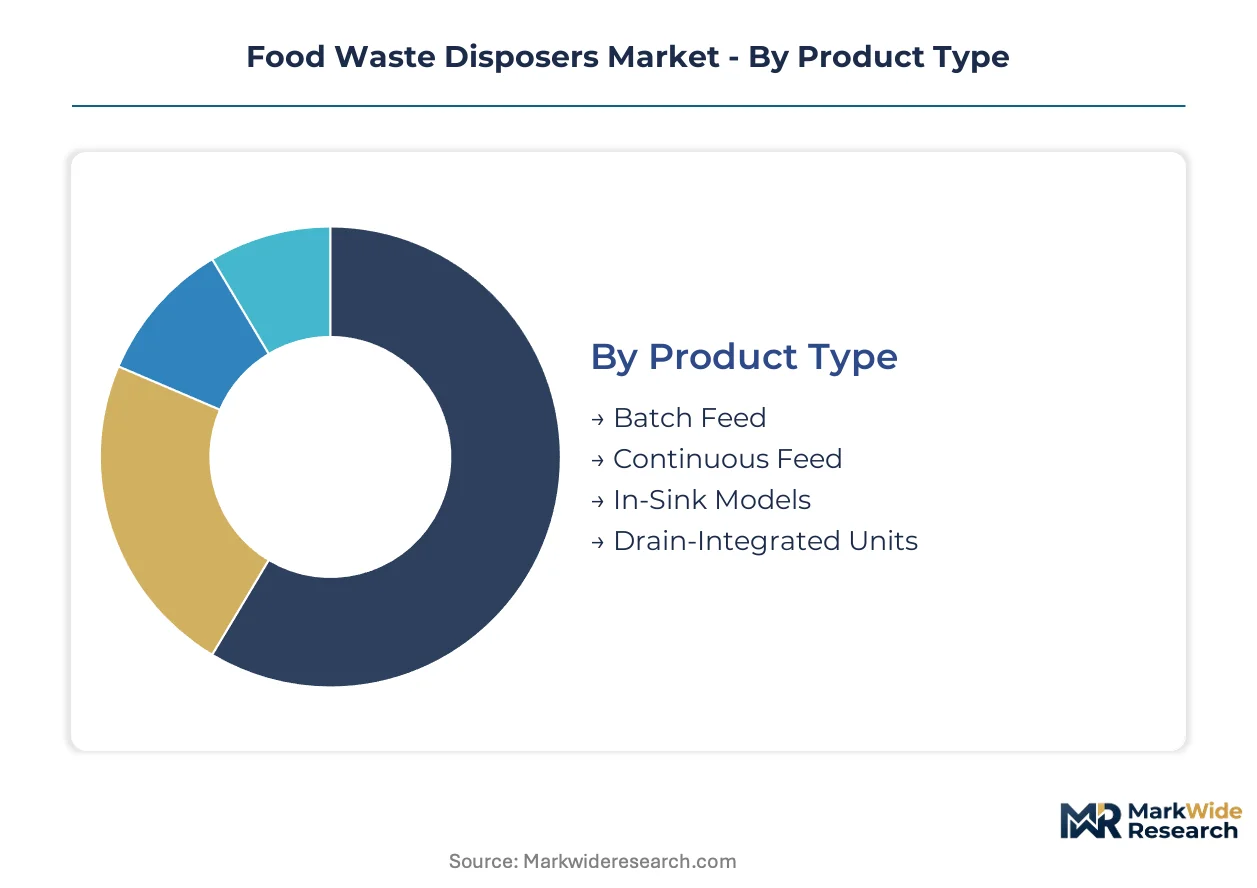
Food waste disposers segment across four functional dimensions that determine specification requirements and procurement channels. Product architecture dictates installation protocols, while end-use intensity shapes motor sizing and grinding chamber specifications. Certification burdens vary sharply across these boundaries.
Product Type:
Continuous feed models carry UL 430 electrical safety certification and NSF/ANSI 61 material contact approvals for commercial foodservice. Batch feed variants require additional interlock mechanism validation under CSA C22.2 standards.
- Continuous Feed:Open-throat designs allow waste introduction during operation through rubber splash guards. Restaurant chains in the United States specify these for high-volume prep sinks where throughput speed governs labor efficiency.
- Batch Feed:Interlocked lid mechanisms prevent operation until sealed, satisfying OSHA kitchen safety guidelines for worker exposure reduction. Educational facilities favor these despite premium pricing for liability mitigation.
- In-Sink Models:Compact grinding units integrated directly into basin structures, common in European residential renovations where cabinet space constraints dominate.
- Drain-Integrated Units:Modular assemblies factory-fitted to sink drains, gaining traction in multi-unit residential construction for standardized installation.
Continuous feed sits at the top of the volume ranking, with batch feed climbing the fastest on safety regulation tailwinds.
Installation Type:
Mounting configuration determines plumbing integration complexity and field service requirements. Under-sink variants demand certified plumber installation per IAPMO Uniform Plumbing Code.
- Under-Sink Mount:Standard three-bolt flange systems attach to sink drain openings. Commercial foodservice operations generate replacement demand as health code inspections drive upgrade cycles.
- Wall Mount:Remote grinding units connected to sinks via dedicated waste lines, specified for centralized kitchen layouts in institutional dining facilities.
- Countertop:Freestanding units with independent feed hoppers, niche positioning for catering operations requiring mobility.
- Portable:Self-contained units with temporary drain connections, limited adoption outside event catering and temporary kitchen installations.
Under-sink mount commands the largest installed base, while wall mount configurations gain share fastest in new institutional construction.
Application:
Application intensity drives motor specification divergence. Commercial installations require higher horsepower ratings and stainless steel grinding components to satisfy FDA food code durability standards.
- Household Kitchens:Single-phase induction motors at ½ to ¾ horsepower dominate. Mature replacement cycles in the United States sustain steady demand through home improvement retail channels.
- Commercial Foodservice:Three-phase permanent magnet motors at 1-3 horsepower with cast stainless steel impellers. EPA landfill diversion mandates in California and New York accelerate equipment replacement.
- Institutional Dining:Heavy-duty continuous feed systems for university and hospital cafeterias, procured through foodservice equipment distributors with bundled maintenance contracts.
- Catering Operations:Mobile and temporary installations with rapid-connect plumbing, price-sensitive procurement through rental equipment channels.
Household kitchens anchor volume, with commercial foodservice expanding most quickly on regulatory compliance spending.
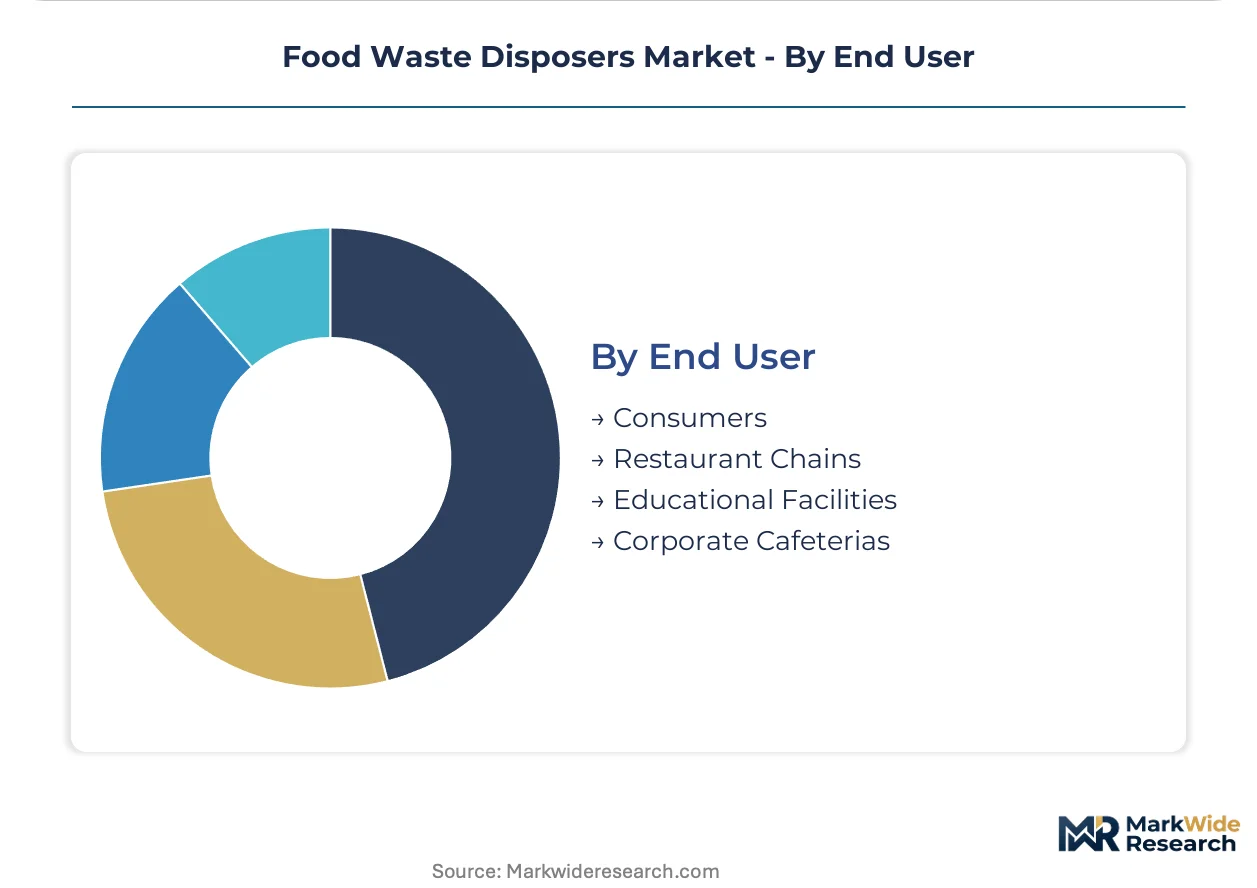
End User:
Procurement authority concentrates differently across end user types. Restaurant chains centralize specification through corporate facilities teams, while educational facilities delegate to local maintenance departments.
- Consumers:Individual purchasers influenced by plumber recommendations and retail availability. Big-box home improvement chains capture specification through point-of-sale placement.
- Restaurant Chains:Centralized procurement standardizes equipment across franchise networks. Multi-unit operators negotiate volume commitments with preferred suppliers for national account pricing.
- Educational Facilities:K-12 and university foodservice directors prioritize batch feed safety features. Procurement flows through cooperative purchasing agreements to satisfy public sector bidding requirements.
- Corporate Cafeterias:Facilities management teams specify for employee dining operations, often outsourcing foodservice to contract management companies that bring equipment preferences.
Restaurant chains lead volume concentration, with corporate cafeterias gaining share fastest as workplace dining investment recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The food waste disposer industry traces its commercial origins to 1920s Racine, Wisconsin, where the first electrically powered grinding unit received municipal approval for residential installation. Kitchen renovation cycles and plumbing infrastructure norms established in that era continue shaping procurement patterns across mature markets today.
United States
Mature replacement cycles sustain steady demand through home improvement retail channels. EPA landfill diversion mandates force waste management authorities to prioritize grinder-compatible sewer infrastructure over traditional hauling contracts. California and New York building electrification codes are eliminating competing thermal waste processing options, expanding addressable markets in coastal metropolitan corridors.
Germany
Specialized kitchen fitting networks anchor European distribution for premium residential installations. EU F-Gas Regulation tightening disposal standards accelerates replacement of refrigerant-dependent waste handling equipment with electrically powered grinding systems. The Ruhr industrial cluster hosts component suppliers serving commercial foodservice equipment fabricators.
China
Urban residential construction in tier-one cities drives specification of compact grinding units for high-rise kitchen installations. National standards under GB framework establish electrical safety and material contact requirements for domestic manufacturers. The Yangtze River Delta manufacturing belt concentrates motor winding and stainless steel impeller production for regional supply chains.
Japan
Space-constrained residential kitchens favor in-sink integrated models with minimal cabinet footprint. METI energy efficiency guidelines influence motor specification preferences toward permanent magnet designs. The Kansai region around Osaka maintains specialized plumbing fixture distribution networks serving renovation contractors.
India
Underpenetrated commercial foodservice equipment markets in urban centers present first-mover advantages for manufacturers establishing local distribution. BIS certification requirements create compliance barriers that favor established multinational suppliers with testing infrastructure. Maharashtra and Karnataka foodservice hubs show accelerating specification of grinding systems for hotel and restaurant chains.
Food Waste Disposers Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive motor manufacturing capabilities. Consolidation around plumbing fixture and foodservice equipment specialists has created tiered positioning across residential and commercial channels. Three archetypes dominate: vertically integrated electrical component manufacturers, specialized kitchen equipment distributors with specification authority, and diversified appliance conglomerates leveraging brand recognition. Capacity expansion in permanent magnet motor production and strategic partnerships with foodservice equipment rental channels represent the dominant competitive moves.
Among North American industrial conglomerates, Emerson Electric and Whirlpool occupy positions anchored by in-house electrical component manufacturing. Electrolux exemplifies the diversified appliance archetype with transatlantic distribution infrastructure. Franke Holding represents the specialized kitchen fitting network model with European specification authority. InSinkErator and Moen Incorporated sit within the plumbing-channel-dependent tier where installer training programs create durable preference lock-in.
| Leading Market Players |
|---|
| Moen Incorporated |
| Franke Holding |
| Emerson Electric |
| Hobart Corporation |
| Electrolux |
| Whirlpool |
| Waste King |
| GE Appliances |
| InSinkErator |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between UL 430/NSF-listed commercial units and unlisted residential economy models creates divergent margin structures that propagate backward into motor sourcing strategies and forward into installer compensation schemes. Premium continuous-feed systems command bundled installation-maintenance contracts through authorized dealer networks, while economy batch-feed variants compete on landed cost through big-box retail channels with minimal field service attachment.
Pricing Analysis
Bundled service contracts versus unbundled equipment-only transactions split the market into two pricing architectures. Three-tier pricing structure across premium permanent-magnet commercial systems, standard induction-motor residential units, and economy aluminum-wound entry models differentiates on horsepower rating and impeller material grade. Cost compression in the economy tier intensifies because copper winding volatility erodes manufacturer margins without captive motor production. Restaurant chains exhibit lowest price sensitivity due to replacement-cycle urgency from health code enforcement, while individual household purchasers through retail channels demonstrate highest elasticity.
Supply Chain Analysis
Freight cost exposure from stainless steel impeller sourcing concentrates manufacturing decisions near Yangtze River Delta foundries and Ruhr industrial cluster component suppliers. Motor winding operations draw from Chinese copper processing and German electrical steel laminations. Single-source vulnerability in permanent magnet rare earth sourcing from China creates procurement risk for premium product tiers. Distribution runs through consolidated foodservice equipment distributors in the United States and specialized kitchen fitting networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food waste disposer market functions as a stable compounder anchored by EPA landfill diversion mandates that perpetuate municipal infrastructure investment and commercial replacement cycles.
For Market Incumbents: Cement specification lock-in by expanding plumber certification programs that embed brand preference during apprenticeship training. Deepen backward integration into permanent magnet motor production to offset copper volatility and defend margin structure against emerging Asian manufacturers. Prioritize channel control through exclusive maintenance contract bundling with institutional dining procurement.
For New Entrants and Emerging Players: Permanent magnet motor efficiency gains offer a technology-first wedge into renovation segments where space constraints favor compact high-torque designs. Target underpenetrated commercial foodservice equipment markets in Indian urban centers where BIS certification barriers favor established testing infrastructure. Pursue white-label partnerships with consolidated foodservice distributors to bypass direct specification battles with entrenched brands.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional plumbing wholesalers lose specification authority to national foodservice equipment distributors. The market supports long-term viability framing around electrification tailwinds and landfill diversion regulatory momentum. Acquisition target archetypes include specialized kitchen fitting networks with European specification authority and permanent magnet motor producers with automotive sector crossover capability. Monitor EPA enforcement intensity in coastal metropolitan corridors as inflection indicator for commercial replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Manufacturing Scale-Up | Captures efficiency premiums from California and New York electrification codes. |
| Plumber Certification Program Expansion | Locks in specification preference through IAPMO-aligned training networks. |
| Foodservice Equipment Distributor Partnership | Bundles installation-maintenance contracts with restaurant chain procurement. |
| Stainless Steel Impeller Backward Integration | Reduces rare earth supply chain exposure for premium commercial tiers. |
| India Distribution Infrastructure Buildout | Establishes first-mover position in Maharashtra and Karnataka foodservice hubs. |
Research Approach
Direct dialogue with commercial kitchen equipment procurement directors, plumbing contractor association training officers, municipal wastewater authority planners, and foodservice distributor category managers grounded qualitative insights. Secondary validation drew from EPA enforcement databases, FDA food code revision dockets, IAPMO Uniform Plumbing Code amendments, and customs records for stainless steel grinding component trade flows. Bottom-up unit shipment estimates triangulated against top-down replacement cycle modeling across the analysis window.
Segmented outputs across product architecture, installation configuration, application intensity, and end-user procurement authority informed volume and value projections. CAGRs derived from regulatory compliance spending trajectories and renovation cycle elasticity parameters. Industry-specific inputs included health code inspection frequency by jurisdiction and building electrification code adoption timelines.
The model holds under steady EPA landfill diversion enforcement and stable copper pricing; deviation in rare earth export restrictions or accelerated composting infrastructure rollout would shift commercial segment growth trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Automatic Deboner Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
North America Beverage Filling and Capping Machine Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Small Continuous Fryer Market
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market