
 North Africa Fruits and Vegetables Processing Market | 2026-2036
North Africa Fruits and Vegetables Processing Market Size, Share, and Industry Trends Forecast 2026-2036
North Africa Fruits and Vegetables Processing Market Intelligence
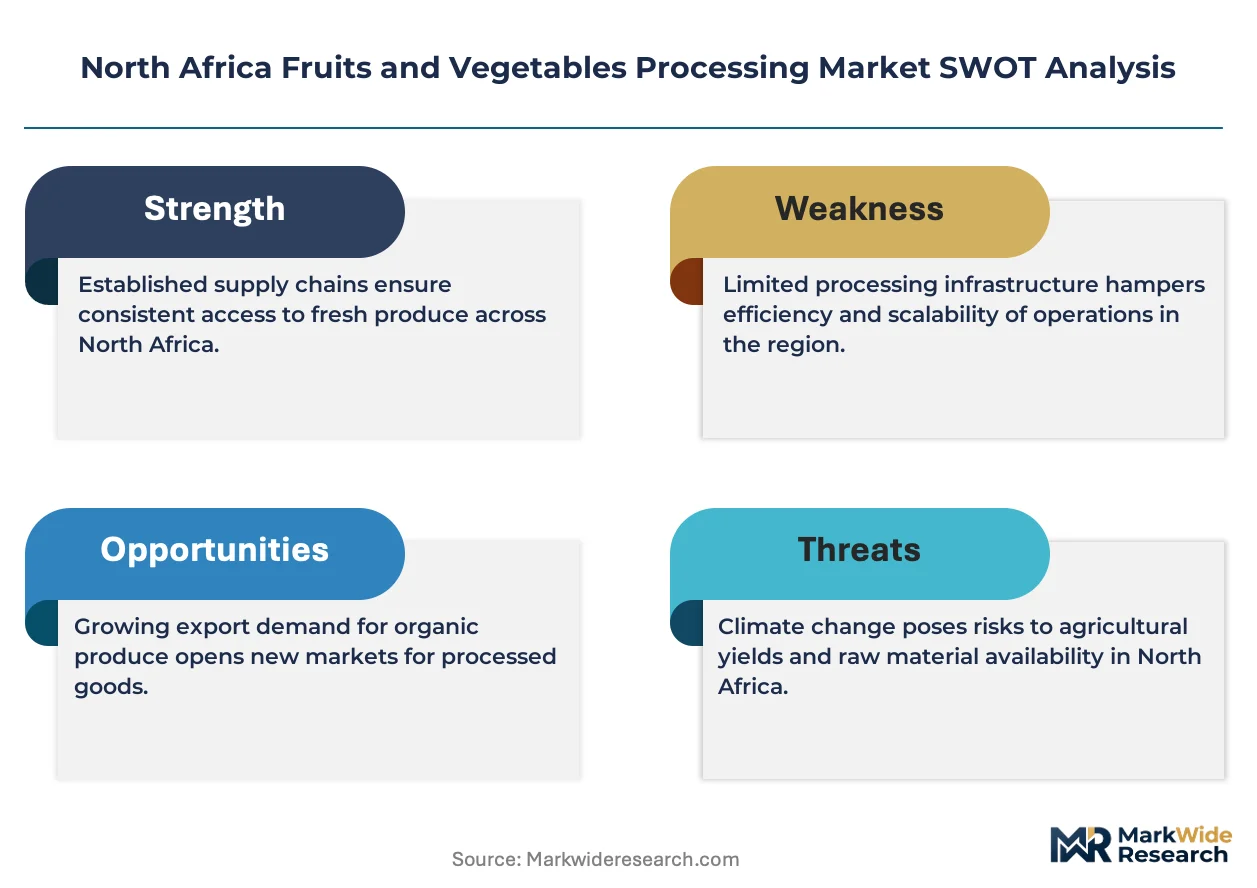
Egyptian tomato paste processors is pivoting toward higher-capacity extraction lines to serve Gulf export contracts. Al Kabeer Group leverages its cold-chain infrastructure to dominate frozen vegetable distribution across Saudi and UAE retail channels. Sunbulah Group anchors its position in date processing through backward integration into Saudi Arabian palm orchards. Dole plc competes in premium packaged fruit segments where European supermarket specifications demand BRC certification.
North Africa fruits and vegetables processing encompasses the mechanical and thermal transformation of harvested produce into shelf-stable or convenience formats through blanching, pasteurization, dehydration, or freezing, typically reducing water activity below thresholds that support microbial proliferation while preserving organoleptic properties. The sector serves retail grocery, food service, and export markets requiring standardized quality, traceable origin documentation, and extended distribution reach. Canned goods and frozen vegetables represent the dominant product categories by volume, with freeze-dried fruit segments capturing disproportionate margin pools due to premium positioning in European health-conscious retail. Vacuum packing technology is expanding fastest among processing methods as processors target reduced preservative formulations for EU import compliance.
Morocco's national food safety authority applies Codex Alimentarius-derived standards alongside EU equivalence protocols for tomato and citrus exports. Egypt's food processing oversight framework mandates facility registration and periodic microbiological testing for products destined for Gulf Cooperation Council markets. Tunisia's technical regulations align with CE marking requirements for packaged goods entering French and Italian retail distribution. Stakeholders must monitor evolving phytosanitary certificate reciprocity between Maghreb nations and European border inspection posts.
Market Dynamics
EU phytosanitary certificate reciprocity negotiations are forcing North African processors to restructure traceability systems ahead of 2027 compliance deadlines, compressing investment timelines across Egypt and Morocco.
Growth Catalysts
- Gulf Cooperation Council import protocols:Egypt's facility registration mandates for microbiological testing create compliant supply corridors into Saudi and UAE retail channels.
- Vacuum packing technology:Reduced preservative formulations unlock EU import eligibility for Tunisian date processors targeting French supermarket contracts.
- Nile Delta irrigation infrastructure:Water-intensive vegetable processing clusters concentrate extraction capacity to serve European frozen produce demand.
Market Restraints
- Input cost volatility:Tomato paste processors face concentrated exposure to Nile Delta irrigation energy tariffs and seasonal water allocation restrictions.
- Supply concentration risk:Cold-chain infrastructure ownership clusters among three integrated groups controlling Saudi and UAE frozen vegetable distribution.
- Regulatory friction:CE marking alignment costs for Tunisian packaged goods entering Italian retail impose capital burdens on mid-scale operators.
Strategic Opportunities
- Underpenetrated geography:Libya's post-conflict food service reconstruction offers first-mover positioning for Moroccan citrus concentrate exporters.
- Regulatory tailwind:Morocco's Hazard Analysis Critical Control Point enforcement creates certification arbitrage for compliant processors serving EU equivalence protocols.
- Technology convergence:Blanching-line automation combined with blockchain traceability addresses French supermarket origin-documentation requirements.
Industry Challenges
- Specialized technician scarcity:High-pressure pasteurization equipment maintenance requires skills concentrated in Casablanca and Cairo technical institutes.
- BRC certification timelines:European supermarket specifications demand 18-month compliance windows that strain Egyptian SME working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Africa Fruits and Vegetables Processing Market |
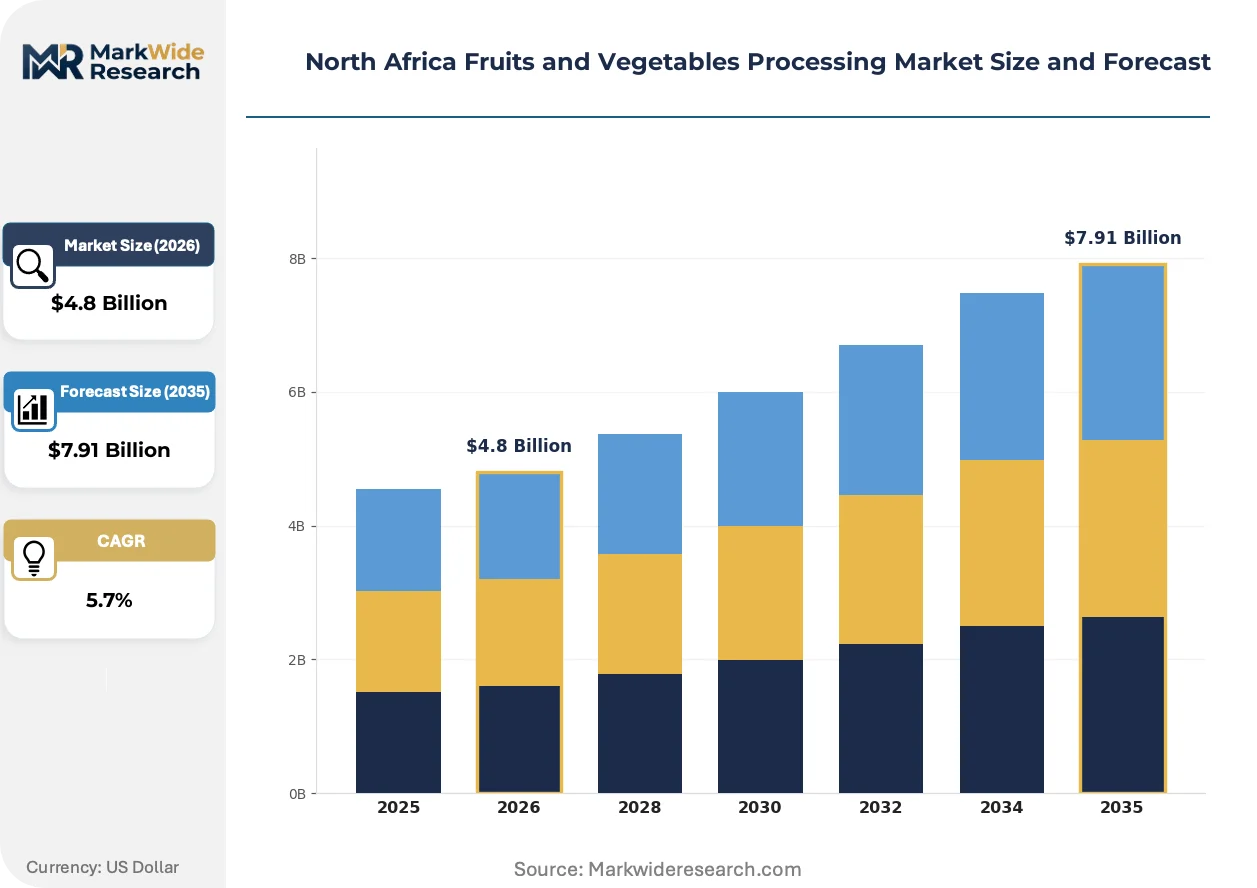
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Produce, Canned Goods, Frozen Vegetables, Dried Fruits Processing Technology: Blanching, Pasteurization, Freeze-Drying, Vacuum Packing End User: Food Service, Retail, Exporters, Community Markets Distribution Channel: Supermarkets, Wholesalers, Direct Sales, Online Platforms |
| Companies Covered | Nestlé S.A., General Mills Inc., Kraft Heinz Company, Al Kabeer Group, Sunbulah Group, Dole plc, Del Monte Pacific Ltd., Archer Daniels Midland Co., Conagra Brands Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Africa Fruits and Vegetables Processing Market Strategic Shifts & Innovations
Processing technology is fragmenting into configurable subsystems that allow North African operators to stage capital deployment against volatile export contract flows.
High-pressure processing equipment is modularizing across Moroccan tomato paste facilities, enabling processors to add capacity increments rather than committing to full greenfield lines. Mid-scale Egyptian operators are adopting leased modular units to serve spot Gulf export contracts without fixed asset exposure. This architecture is compressing the minimum viable scale for EU-compliant production, allowing regional players to challenge integrated incumbents.
Morocco's national food safety authority is enforcing Codex Alimentarius-derived standards alongside EU equivalence protocols for citrus exports. Facility audit frequency has doubled since 2023, accelerating HACCP system investments among date and tomato processors. Small-scale Tunisian operators are consolidating to share compliance costs for French retail entry.
Food service procurement in Egypt is consolidating toward direct processor relationships that bypass traditional wholesale layers. Hotel and restaurant chains in Cairo and Alexandria are mandating farm-level traceability documentation that informal traders cannot supply. This channel shift is most visible in Nile Delta vegetable processing clusters serving European contract catering.
North Africa Fruits and Vegetables Processing Market Segmentation
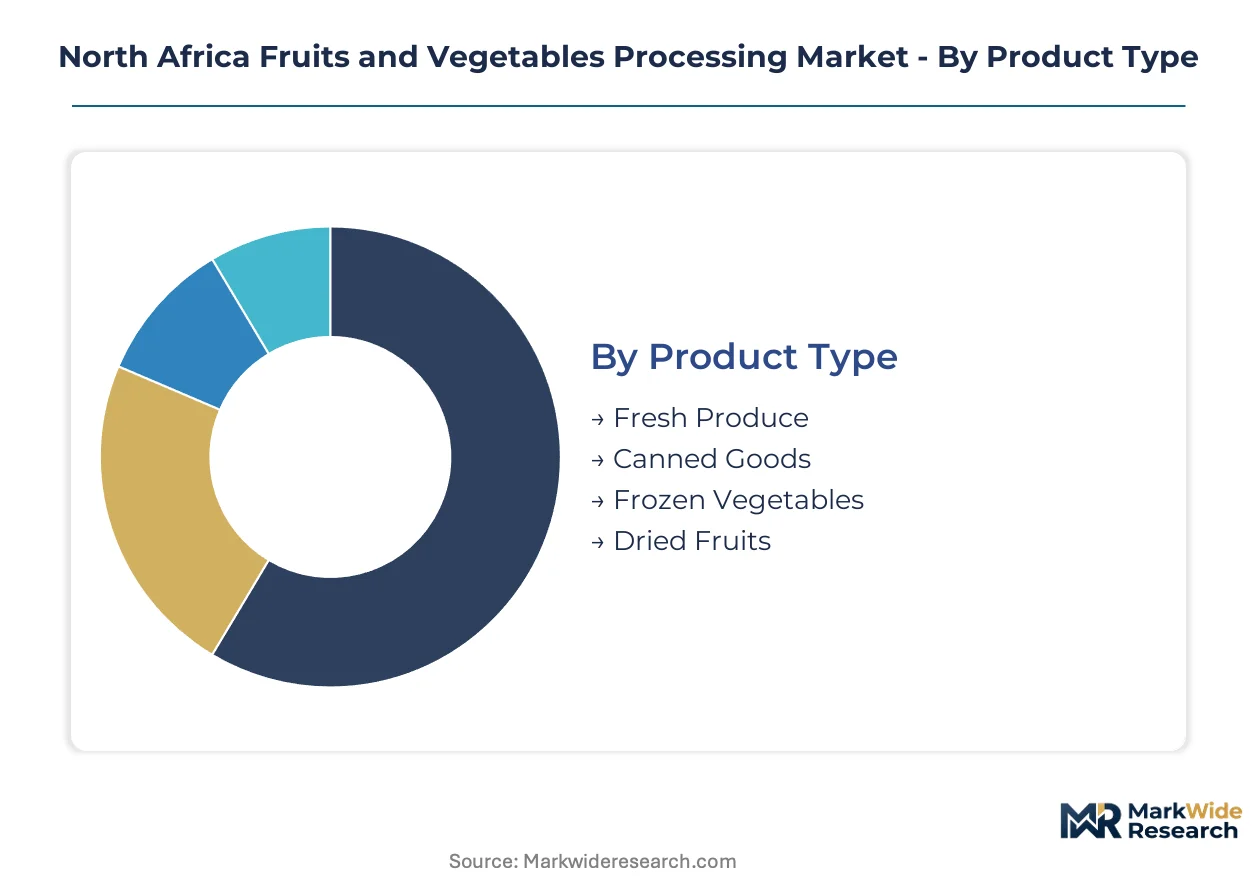
Segmentation in North Africa fruits and vegetables processing reveals how technology choices, channel structures, and end-user specifications create distinct operational requirements. Processors must align capital deployment with the technical and regulatory demands of each segment to capture margin pools.
Product Type:
Equipment replacement cycles vary sharply across product categories, with thermal-intensive formats demanding more frequent line upgrades than ambient-stable alternatives.
- Canned Goods:Metal-container sterilization lines dominate Egyptian and Moroccan installed capacity, serving Gulf Cooperation Council shelf-stable procurement contracts. Tomato paste concentration facilities in the Nile Delta corridor run continuous retort systems calibrated for 18-month shelf life specifications.
- Frozen Vegetables:Individual quick freezing tunnels require the most capital-intensive maintenance cycles among all product types. Cold-chain dependency limits viable production to clusters with reliable electricity infrastructure, concentrating capacity in Egypt's Sharqia and Morocco's Souss-Massa regions.
- Fresh Produce:Minimal processing preserves enzymatic activity through controlled-atmosphere packaging for European supermarket pre-cut salad programs.
- Dried Fruits:Solar and mechanical dehydration serves Tunisian date processors targeting French organic retail channels with reduced moisture specifications.
Volume placements concentrate in Canned Goods; the faster expansion belongs to Frozen Vegetables.
Processing Technology:
Technology selection maps directly to export destination requirements, with European-bound shipments demanding more stringent thermal intervention than regional trade.
- Vacuum Packing:Modified atmosphere systems enable reduced-sulfur formulations that satisfy EU maximum residue limits for Tunisian date exports. French supermarket buyers mandate oxygen transmission rates below specific thresholds that only multi-layer barrier films achieve.
- Freeze-Drying:Sublimation equipment commands premium positioning in European health-conscious retail through preserved cellular structure and rehydration performance. Egyptian operators lease modular units to serve spot contracts without fixed asset exposure.
- Blanching:Steam and water immersion systems inactivate enzymes prior to freezing or dehydration, with automation investments concentrated in Nile Delta vegetable clusters.
- Pasteurization:High-pressure processing modules in Moroccan tomato facilities enable cold-pathogen reduction for clean-label positioning in German retail.
Capital deployment concentrates in Vacuum Packing; the steepest expansion trajectory belongs to Freeze-Drying.
End User:
Customer-type segmentation determines traceability depth, with institutional buyers imposing farm-level documentation that informal channels cannot supply.
- Food Service:Hotel and restaurant chains in Cairo and Alexandria mandate lot-level origin documentation for contract catering procurement. Direct processor relationships are displacing traditional wholesale layers across Egypt's hospitality sector.
- Exporters:European supermarket specifications demand BRC certification and phytosanitary reciprocity compliance that compresses investment timelines for Egyptian and Moroccan operators.
- Retail:Domestic supermarket chains in Morocco and Tunisia prioritize price positioning over certification depth for mass-market canned goods.
- Community Markets:Traditional bazaar channels in Algeria and Libya absorb surplus production without formal quality documentation.
Procurement volume concentrates in Food Service; the certification-driven expansion belongs to Exporters.
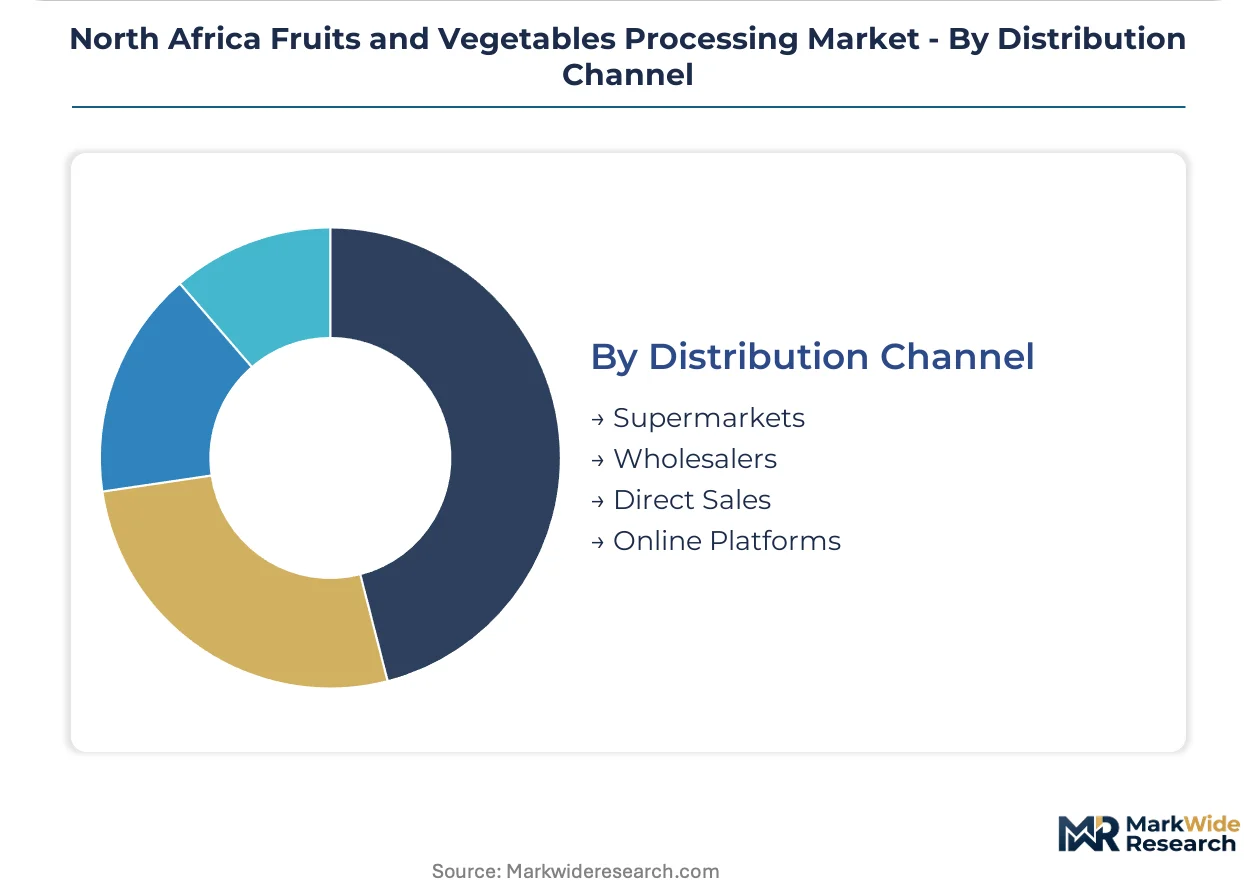
Distribution Channel:
Channel structure determines working capital intensity, with direct relationships reducing margin leakage but requiring dedicated sales infrastructure.
- Supermarkets:Modern retail penetration in Morocco's Casablanca-Rabat corridor demands palletized logistics and electronic data interchange compatibility. Carrefour and Marjane specifications drive standardization across supplier bases.
- Wholesalers:Traditional aggregation in Egypt's Al-Obour market and Tunisia's Central Market remains the default path for mid-scale processors lacking cold-chain assets.
- Direct Sales:Large-format food service contracts bypass intermediary margins but require dedicated account management in Saudi and UAE procurement offices.
- Online Platforms:E-commerce penetration for processed produce remains limited to premium gift-box dates in Gulf markets with established last-mile cold delivery.
Shipment volume concentrates in Wholesalers; the margin-preservation shift belongs to Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nile Delta's irrigation-intensive vegetable belts anchor processing capacity across Egypt's Sharqia and Dakahlia governorates, where tomato paste concentration facilities cluster to serve Gulf export corridors.
Egypt
Food service procurement in Cairo and Alexandria mandates farm-level traceability documentation that informal traders cannot supply. The country's food processing oversight framework requires facility registration and periodic microbiological testing for products destined for Gulf Cooperation Council markets. Nile Delta vegetable processing clusters concentrate extraction capacity to serve European frozen produce demand through Alexandria port corridors.
Morocco
Citrus concentrate exporters target Libya's post-conflict food service reconstruction with first-mover positioning strategies. Morocco's national food safety authority enforces Hazard Analysis Critical Control Point standards across processing facilities alongside Codex Alimentarius-derived protocols. Souss-Massa region hosts cold-chain-dependent frozen vegetable capacity serving domestic supermarket chains and French retail contracts.
Tunisia
Date processors pursue reduced-sulfur formulations to satisfy EU maximum residue limits for French organic retail channels. Technical regulations align with CE marking requirements for packaged goods entering Italian distribution networks. Mid-scale operators consolidate to share compliance costs for European supermarket entry.
Algeria
Traditional bazaar channels absorb surplus canned production without formal quality documentation requirements. The country's national food safety regulator applies import substitution policies favoring domestic tomato paste capacity over foreign suppliers. Processing clusters concentrate in northern coastal zones with Mediterranean port access for equipment imports.
North Africa Fruits and Vegetables Processing Market Key Industry Players
Global majors compete with regional champions across certification depth and cold-chain infrastructure ownership. The vendor base stratifies into three tiers: multinational packaged food conglomerates with BRC-certified global supply systems, Gulf-based integrated groups controlling Saudi and UAE distribution networks, and mid-scale North African operators consolidating for shared compliance costs. Dominant competitive moves include backward integration into palm orchards for date supply security and modular high-pressure processing equipment leasing to reduce fixed asset exposure.
Among Gulf-based integrated processors, Al Kabeer Group and Sunbulah Group exemplify the cold-chain infrastructure archetype controlling Saudi and UAE frozen vegetable distribution channels. Dole plc occupies a position representing premium packaged fruit specialists where European supermarket specifications demand certification depth. These three anchors illustrate how geographic origin and vertical control over supply assets determine competitive positioning against multinational conglomerates.
| Leading Market Players |
|---|
| Nestlé S.A. |
| General Mills Inc. |
| Kraft Heinz Company |
| Al Kabeer Group |
| Sunbulah Group |
| Dole plc |
| Del Monte Pacific Ltd. |
| Archer Daniels Midland Co. |
| Conagra Brands Inc. |
| Others |
Cost & Logistics Intelligence
Gulf Cooperation Council procurement mandates for BRC-certified frozen vegetables are compressing supplier margins and forcing Egyptian processors to absorb certification costs or cede shelf space to Moroccan competitors with established compliance infrastructure. This buyer-side pressure cascades into supply chain restructuring as mid-scale operators consolidate to share cold-chain assets and reduce per-unit compliance burdens.
Pricing Analysis
Service bundling separates Egyptian tomato paste exporters offering HACCP documentation and Gulf port logistics from unbundled spot-market sellers serving Algerian bazaar channels. Three-tier pricing structure across premium certified, standard registered, and economy unregistered levels tracks certification depth and cold-chain completeness. Cost compression in the standard tier is intensifying because Nile Delta irrigation energy tariffs are rising without corresponding tomato price recovery. Food service buyers in Cairo and Alexandria exhibit lowest price sensitivity due to contract catering premiums, while Algerian traditional channel distributors demand maximum volume discounts.
Supply Chain Analysis
Skilled technician availability constrains capacity expansion in Egypt's Sharqia governorate and Morocco's Souss-Massa region where high-pressure pasteurization maintenance expertise concentrates in Casablanca and Cairo technical institutes. Manufacturing gravity centers on Egypt, Morocco, and Tunisia with Algeria serving as surplus absorption market. Raw material flows draw from Nile Delta tomato belts, Moroccan citrus orchards, and Tunisian date palm regions. Single-source vulnerability runs through Alexandria and Casablanca cold-chain hubs exposed to electricity infrastructure instability. Distribution runs through Saudi and UAE retail procurement offices for premium segments and Al-Obour wholesale aggregation for domestic Egyptian volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU phytosanitary reciprocity deadlines are accelerating consolidation as BRC certification timelines and working capital requirements force smaller Egyptian processors into distressed sales or joint venture structures.
For Market Incumbents: Anchor market position through backward integration into Nile Delta irrigation infrastructure and captive date palm supply in Tunisian oases to insulate against input cost volatility. Prioritize modular high-pressure processing equipment leasing to reduce fixed asset exposure while maintaining clean-label positioning for German retail contracts. Defend against Moroccan citrus concentrate exporters by locking long-term food service procurement relationships in Cairo and Alexandria with farm-level traceability documentation that informal traders cannot replicate. For New Entrants and Emerging Players: Direct-to-food-service digital platforms offer lowest competitive friction for Egyptian processors seeking to bypass Al-Obour wholesale margin extraction. Target Libya's post-conflict reconstruction procurement where Moroccan citrus concentrate exporters hold temporary first-mover advantage but lack established distribution infrastructure. Pursue white-space positioning in vacuum-packed reduced-sulfur date segments for French organic retail where Tunisian mid-scale operators are consolidating compliance costs rather than expanding capacity. For Investors and Strategic Acquirers: The window for entry favors cold-chain infrastructure owners with Gulf retail network control and backward integration into palm orchards. Five-to-ten year viability hinges on capturing certification-arbitrage returns before EU equivalence protocols commoditize compliance premiums. Monitor phytosanitary certificate reciprocity implementation between Maghreb nations and European border inspection posts as inflection indicator for Egyptian export corridor viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigation Assets | Nile Delta water rights secure tomato paste supply against seasonal allocation restrictions. |
| Modular HPP Equipment Leasing | Moroccan processors reduce capital commitment while serving spot German retail contracts. |
| BRC Certification Acceleration | Egyptian SMEs compress 18-month compliance windows to meet Gulf procurement mandates. |
| Direct Food Service Procurement Platforms | Cairo hotel chains bypass traditional wholesale layers with farm-level traceability demands. |
| Consolidation for Shared Compliance Costs | Tunisian date processors pool CE marking investments for French supermarket entry. |
Research Approach
Document review covered customs records from Egyptian and Moroccan port authorities, EU phytosanitary certificate reciprocity negotiation filings, and Gulf Cooperation Council import protocol documentation, complemented by interviews with plant managers at Nile Delta processing facilities, procurement directors at Saudi retail chains, regulatory affairs specialists at Moroccan food safety authority, and cold-chain logistics operators serving Alexandria port corridors. Secondary validation drew from trade data published by national statistics offices, industry association capacity surveys, and facility registration databases maintained by Egyptian food processing oversight framework. Bottom-up capacity installation counts and top-down trade flow estimates were triangulated against reported production volumes.
Segment-level value and volume trajectories across the projection horizon reflect calibrated assumptions on technology adoption rates, export contract renewal patterns, and regulatory enforcement intensity. The analytical framework modeled product type, processing technology, end user category, and distribution channel dimensions alongside country-specific regulatory cluster alignment. CAGRs were derived from installed capacity expansion timelines, equipment replacement cycles, and historical trade growth patterns. Forecast inputs incorporated Nile Delta irrigation infrastructure investment pipelines and Moroccan HACCP audit frequency acceleration.
The model holds under stable EU-Maghreb trade reciprocity and continued Gulf import protocol enforcement; deviation in phytosanitary certificate recognition timelines or Nile Delta water allocation policy would shift capacity location decisions and margin projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Dehydrated Beets Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Global Garcinia Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Noni Fruit Powder Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Europe Olive Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
United States Guacamole Market