
 Global Integrated Food Ingredient Market | 2026-2036
Global Integrated Food Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Global Integrated Food Ingredient Market Intelligence
The shift toward clean-label and non-GMO formulations is reorganizing the competitive landscape for integrated food ingredients. This trend elevates the value of transparent sourcing and simplified ingredient lists. Cargill leverages its extensive global supply chain to secure consistent non-GMO raw materials. Kerry Group specializes in developing complex, customized ingredient systems for specific end-use applications like bakery and beverages. Archer Daniels Midland sustains its market position through large-scale processing of plant-based proteins and sweeteners.
Integrated food ingredients are pre-blended systems that combine multiple functional components, such as emulsifiers, stabilizers, and flavor enhancers, into a single product. These systems are engineered to deliver synergistic effects that are not achievable with individual components. Their primary purpose is to streamline the food manufacturing process, ensure product consistency, and optimize texture, shelf life, or taste. While stabilizers and emulsifiers represent a foundational and mature product segment, integrated protein blends for beverages and dairy alternatives are showing the most significant expansion.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) set stringent standards for ingredient safety, labeling, and health claims. In parallel, China's national GB standards govern market access and product compliance within its large consumer market. These regulations directly influence formulation strategies and R&D priorities for new ingredient systems. Navigating the divergent international requirements for novel ingredients and clean-label substantiation remains a critical strategic consideration for all market participants.
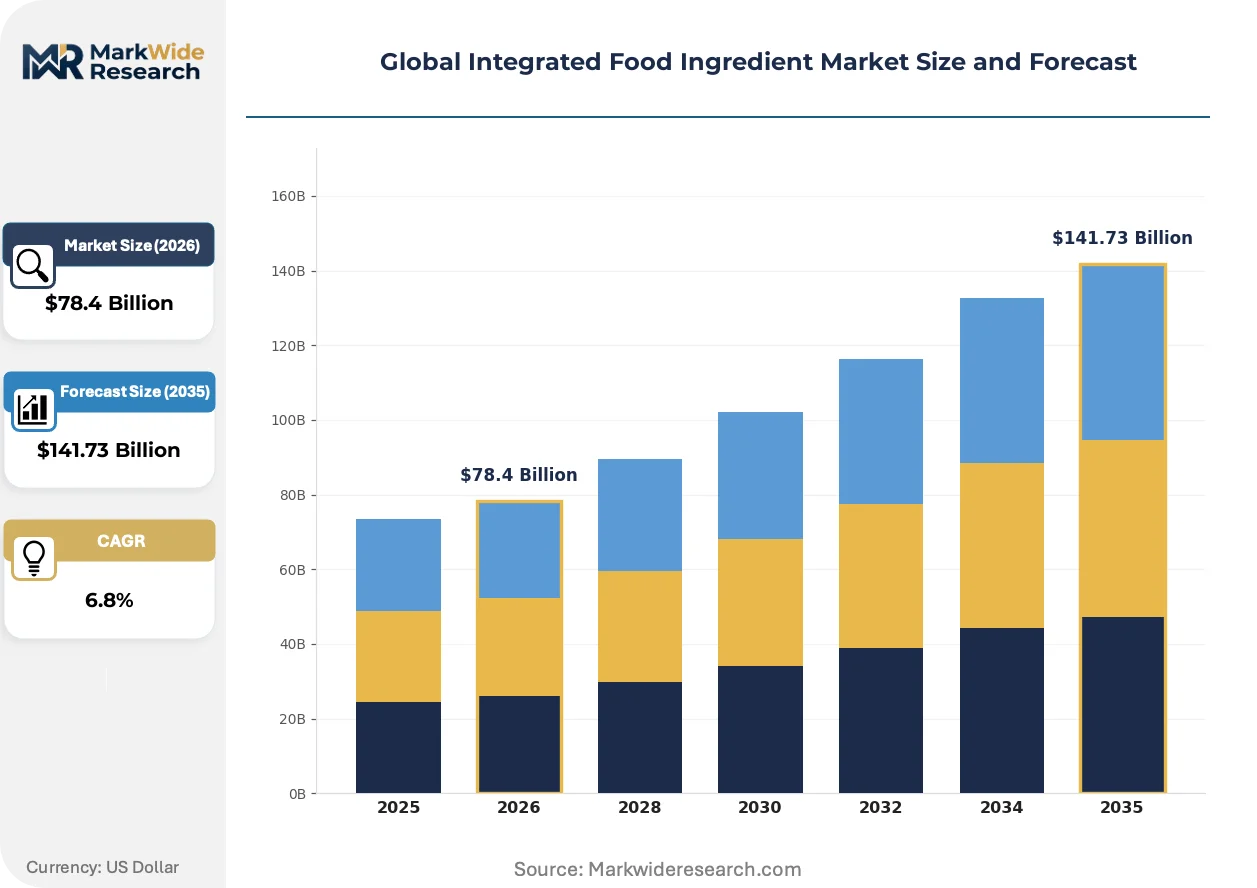
Market Dynamics
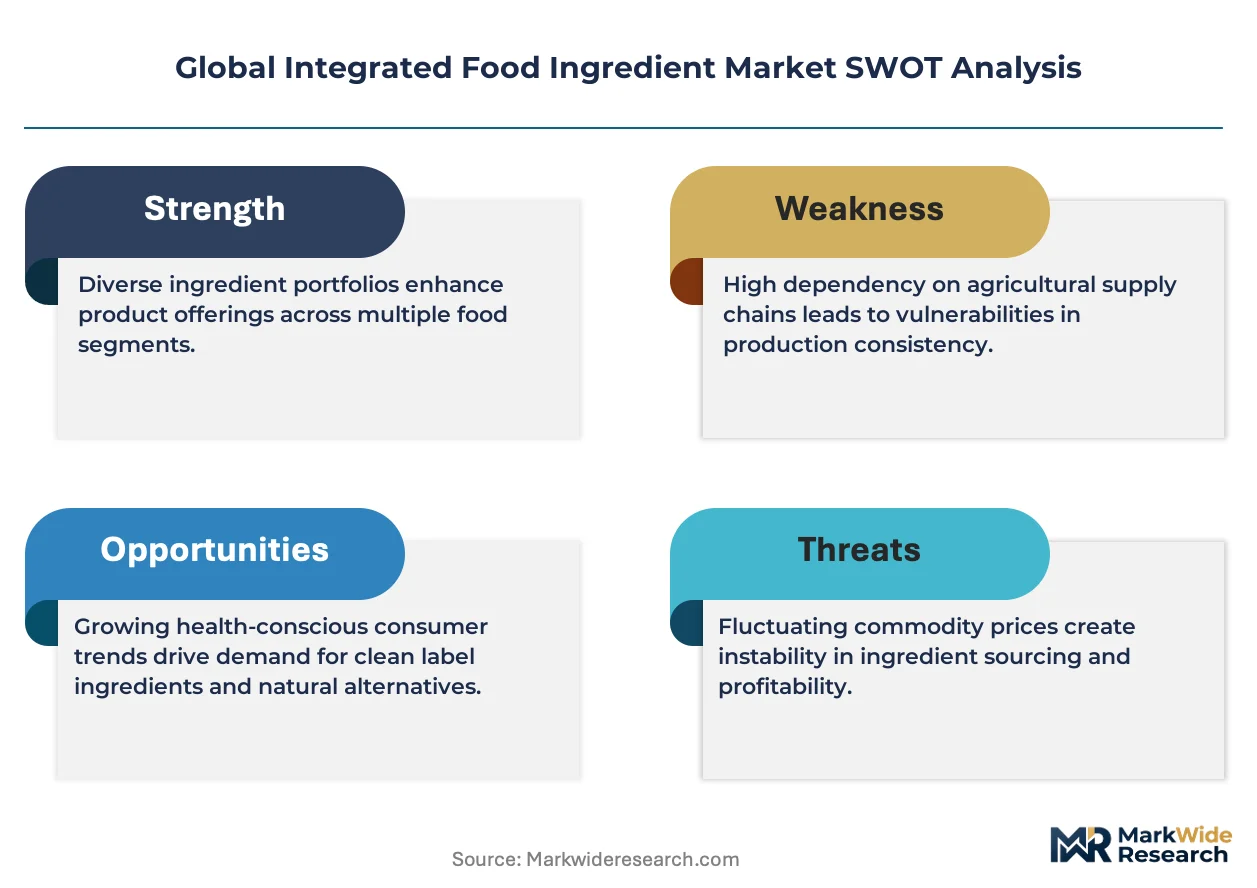
The central structural force shaping the integrated food ingredient market is the tension between consumer demand for simplified, clean-label products and the technical complexity required to achieve multifunctionality. This dynamic elevates the strategic importance of formulation expertise and transparent sourcing.
Growth Catalysts
- Clean-Label Regulation:Stricter guidelines from bodies like the European Food Safety Authority (EFSA) on additives and labeling are compelling manufacturers to adopt natural, recognizable integrated systems, particularly within the European bakery and dairy sectors.
- Plant-Based Food Expansion:The rapid growth of the plant-based meat and dairy alternative categories necessitates sophisticated ingredient blends to replicate the texture, mouthfeel, and nutritional profile of conventional animal products.
- Manufacturing Efficiency in China:China's expanding processed food industry drives demand for pre-blended, standardized ingredient systems that improve production line efficiency, reduce batch variability, and ensure compliance with national GB standards.
Market Restraints
- Input Cost Volatility:Price fluctuations for key raw materials, such as hydrocolloids sourced predominantly from India and Pakistan, create margin pressure and supply chain instability for formulators of stabilizer and texturizer systems.
- Regulatory Divergence:Navigating disparate approval pathways for novel ingredients between major markets, like the US FDA's GRAS notification system and China's more stringent registration process, complicates global product launches.
- Technical Functionality Gaps:Creating clean-label integrated systems that perfectly match the performance, shelf stability, and sensory characteristics of established synthetic ingredients remains a significant research and development challenge.
Strategic Opportunities
- Southeast Asian Beverage Market:The growing beverage industry in countries like Vietnam and Indonesia presents an opportunity for customized fortification blends that address local nutritional needs and flavor preferences.
- Cellular Agriculture Ingredients:Developing integrated systems for the nascent cellular agriculture sector, providing scaffolding, nutrient media, and texturizing agents for cultivated meat, represents a new frontier for innovation.
- AI-Powered Formulation:The convergence of artificial intelligence with high-throughput screening allows for the rapid discovery and optimization of synergistic ingredient combinations, accelerating development of novel functional blends.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of food scientists and chemical engineers with expertise in both the chemistry of individual components and the physics of complex food matrices hinders innovation.
- Complex Certification Pathways:Obtaining and maintaining multiple certifications, such as Non-GMO Project Verified or USDA Organic, for multi-component blends is a costly and time-consuming process that can delay market access.
- Supply Chain Traceability:Ensuring complete, verifiable traceability for every raw material within a complex ingredient blend is a significant operational hurdle, yet it is critical for substantiating clean-label claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Integrated Food Ingredient Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteins, Emulsifiers, Stabilizers, Flavor Enhancers, Sweeteners, Colorants Application: Bakery & Confectionery, Beverages, Meat & Seafood, Dairy Alternatives, Sauces & Dressings, Snacks End User: Food Manufacturers, Foodservice Operators, Private Label Producers, Nutraceutical Companies Distribution Channel: Direct Sales, Distributors, E-Commerce Platforms, Wholesale Suppliers, Food Ingredient Brokers |
| Companies Covered | Cargill, Archer Daniels Midland, Associated British Foods, Tate & Lyle, BASF, Kerry Group, DSM, International Flavors & Fragrances, Dohler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Integrated Food Ingredient Market Strategic Shifts & Innovations
Synergistic functionality is displacing the use of single-function additives. The market is shifting toward intelligent systems engineered for specific outcomes, such as sugar reduction or texture modification, driven by advanced formulation science and consumer demand for healthier, simpler products.
Precision fermentation is a production technology used to create highly specific functional molecules like proteins or enzymes without traditional agriculture. Food manufacturers, especially in the alternative dairy and protein sectors, are adopting these ingredients for their purity and consistent performance. This technology is decomposing the reliance on agricultural raw material supply chains, creating new value streams centered on biomanufacturing.
The US Food and Drug Administration's updated nutrition labeling rules, which mandate clearer declaration of added sugars, are forcing widespread product reformulation. This policy directly increases demand for integrated sweetener systems that reduce sugar content while preserving taste and texture. The beverage and confectionery segments are most affected, spurring investment in blends utilizing natural high-intensity sweeteners.
A notable shift in purchasing behavior involves buyers demanding co-developed, application-specific ingredient solutions instead of generic, off-the-shelf products. This alters the traditional supplier-customer relationship into a more collaborative partnership, embedding ingredient specialists within a client's R&D process. This model is most prominent within Europe's specialized nutrition and premium bakery sectors, where custom functionality is a key differentiator.
Global Integrated Food Ingredient Market Segmentation
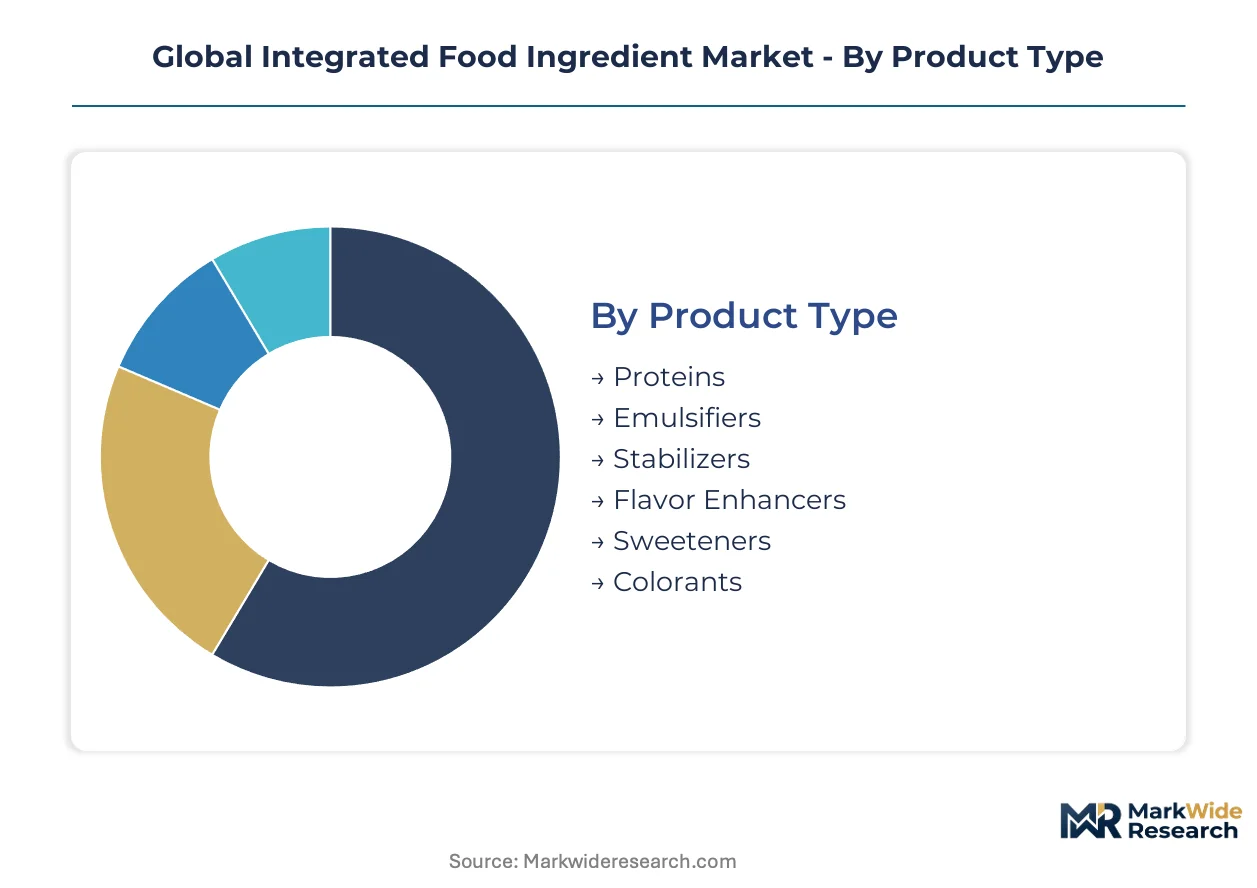
The integrated food ingredient market demonstrates diverse requirements across product types, applications, and end-user profiles. Understanding these distinct segments is critical for manufacturers to tailor solutions that meet specific functional needs and regulatory compliance. Each category reflects unique demand drivers and technical complexities, influencing strategic investment and product development priorities.
Product Type:
Regulatory frameworks from the US FDA and EFSA heavily influence the classification and permissible usage of integrated food ingredients.
- Proteins:Proteins represent complex blends designed to enhance nutritional value and textural properties in food products. Demand is particularly high in the European plant-based dairy and meat alternative sectors, driven by consumer health trends.
- Emulsifiers:These ingredients stabilize immiscible liquids, preventing separation and improving product consistency. The global bakery and confectionery industries rely on emulsifiers for optimal texture and shelf life.
- Stabilizers:Stabilizers maintain physical properties, preventing ingredient separation and degradation over time. They are crucial for dairy products and beverages to ensure product integrity.
- Flavor Enhancers:Flavor enhancers intensify existing tastes, often reducing the need for higher concentrations of primary flavorings. Asian markets, especially China, show strong demand for these components in savory snacks.
- Sweeteners:Sweeteners comprise integrated systems formulated for sugar reduction while maintaining sensory profiles. The US beverage and confectionery segments are driving adoption, responding to updated FDA nutrition labeling rules.
- Colorants:Colorants provide visual appeal and consistency, often derived from natural sources to meet clean-label demands. The European dairy and beverage sectors are increasingly adopting natural color blends.
Established volume favors Stabilizers; emerging adoption favors Proteins.
Application:
Volume considerations dictate the prioritization of integrated ingredient applications across diverse food sectors.
- Bakery & Confectionery:This segment utilizes integrated ingredients for texture modification, shelf life extension, and moisture retention in products like breads and cakes. European premium bakery sectors frequently demand customized ingredient systems.
- Beverages:Beverages employ multifunctional blends to improve mouthfeel, stability, and nutritional fortification. The Southeast Asian market shows significant demand for customized blends addressing regional dietary needs.
- Meat & Seafood:Integrated ingredients enhance binding, moisture retention, and texture in processed meat and seafood products. China's expanding processed food industry drives considerable demand in this category.
- Dairy Alternatives:Dairy Alternatives require sophisticated ingredient systems to mimic the texture and functional properties of traditional dairy. Growth in China's processed food sector fuels demand for these specialized blends.
- Sauces & Dressings:These applications leverage integrated ingredients for emulsification, stabilization, and viscosity control, ensuring product consistency. The US market prioritizes clean-label formulations in this segment.
- Snacks:Integrated ingredients in snacks contribute to texture, flavor, and shelf stability, particularly in savory and extruded products. Global consumer preferences for healthier snack options influence ingredient choices.
Bakery & Confectionery applications maintain consistent demand, while Dairy Alternatives are expanding most quickly.
End User:
Customer type significantly influences the scale and customization required for integrated food ingredient solutions.
- Food Manufacturers:Food Manufacturers procure large volumes of integrated ingredient systems to streamline production and ensure consistent product quality. China's expanding manufacturing base represents a major demand center.
- Foodservice Operators:This segment uses integrated ingredients to simplify preparation, extend holding times, and standardize menu items across multiple locations. European foodservice chains seek easy-to-use, stable ingredient blends.
- Private Label Producers:Private Label Producers require cost-effective, high-performing integrated ingredients to compete with national brands. North American retailers drive demand for versatile, multi-functional blends.
- Nutraceutical Companies:Nutraceutical Companies seek highly functional and clean-label integrated ingredients for health-focused product development. European markets show strong demand for certified organic and non-GMO formulations.
Food Manufacturers constitute the largest purchasing segment; Nutraceutical Companies are rapidly increasing their ingredient procurement.
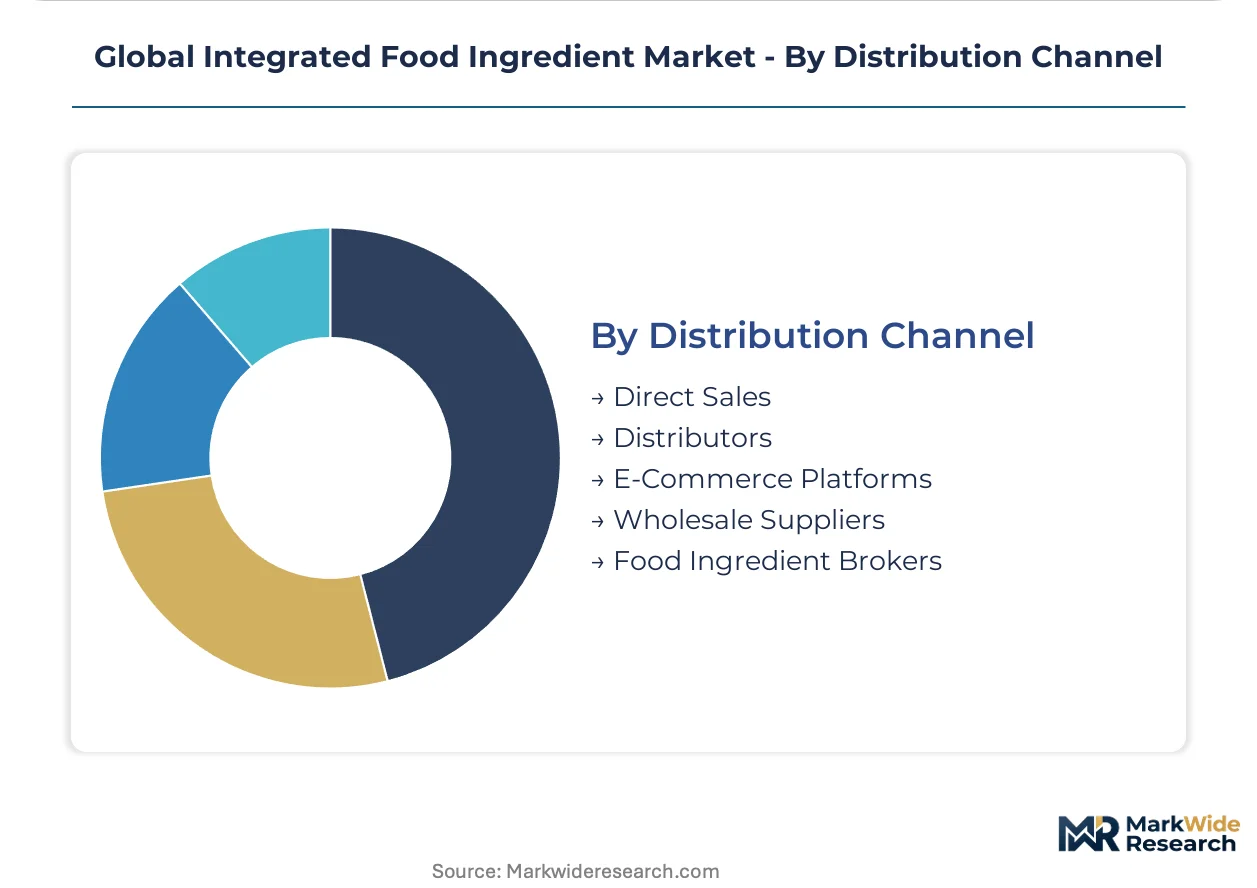
Distribution Channel:
Supply chain concentration patterns shape the efficiency and reach of integrated food ingredient distribution.
- Direct Sales:Direct Sales channels facilitate deep technical collaboration between ingredient suppliers and food manufacturers for co-developed solutions. This model is prominent within Europe's specialized nutrition sector.
- Distributors:Distributors provide broad market access, especially for smaller manufacturers and specialized regional needs, by stocking a wide range of integrated ingredients. This channel is crucial across diverse geographies.
- E-Commerce Platforms:E-Commerce Platforms offer efficient procurement and broader access to standardized integrated ingredient products for smaller manufacturers. The US market is seeing a shift towards online purchasing for common ingredients.
- Wholesale Suppliers:Wholesale suppliers cater to bulk purchasers, offering competitive pricing for high-volume integrated ingredient orders. Asian markets frequently utilize wholesale for staple food ingredient procurement.
- Food Ingredient Brokers:Brokers connect buyers and sellers, often facilitating transactions for niche or hard-to-source integrated ingredients. Their role is particularly important in fragmented global supply chains.
Direct Sales channels are essential for strategic partnerships, while E-Commerce Platforms are gaining traction for transactional purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The integrated food ingredient market's operational footprint is defined by specific regional concentrations. China's expanding processed food industry represents a major demand center, while European markets drive innovation in clean-label formulations. North America also contributes significantly through regulatory shifts and advanced ingredient development.
China
China's expanding processed food industry drives demand for standardized ingredient systems and flavor enhancers. National GB standards mandate strict compliance for all integrated food products entering its vast consumer market. Food manufacturers in the Yangtze River Delta utilize these blends to improve production line efficiency and consistency.
United States
The United States market exhibits high demand for integrated sweetener systems due to sugar reduction initiatives. US FDA's updated nutrition labeling rules directly influence product reformulation in beverage and confectionery segments. Food innovation hubs across California focus on developing novel functional blends for health-conscious consumers.
Germany
Germany drives demand for natural, recognizable integrated systems within its sophisticated bakery and dairy sectors. Stricter European Food Safety Authority (EFSA) guidelines on additives compel manufacturers to adopt transparent sourcing and simplified ingredient lists. Research and development centers in Bavaria lead efforts in creating custom ingredient systems for specialized nutrition applications.
India
India serves as a crucial sourcing hub for key raw materials like hydrocolloids, impacting global supply chains. The Food Safety and Standards Authority of India (FSSAI) sets national standards for ingredient safety and labeling, influencing local formulation strategies. Emerging food processing clusters in Maharashtra are increasing their adoption of integrated ingredients for efficiency and quality.
Global Integrated Food Ingredient Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the integrated food ingredient market. The market exhibits a tiered structure, with large multinational corporations alongside specialized innovators. These archetypes include global ingredient powerhouses, niche solution providers, and regional commodity processors. Dominant competitive moves involve strategic partnerships for co-development and portfolio diversification into plant-based solutions.
Global ingredient powerhouses like Cargill and Archer Daniels Midland exemplify scale-driven market participation. Cargill leverages its extensive global supply chain for consistent non-GMO raw materials. Archer Daniels Midland sustains its market position through large-scale processing of plant-based proteins and sweeteners. Kerry Group, a specialized innovator, focuses on developing complex, customized ingredient systems for specific end-use applications like bakery and beverages. These companies continuously adapt their offerings to meet evolving clean-label and functional demands.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Associated British Foods |
| Tate & Lyle |
| BASF |
| Kerry Group |
| DSM |
| International Flavors & Fragrances |
| Dohler |
Cost & Logistics Intelligence
Plant-based protein blends substituting for traditional animal-derived ingredients are reshaping the integrated food ingredient supply geography and pricing economics. This dynamic shifts sourcing towards novel agricultural inputs and biomanufacturing processes.
Pricing Analysis
EFSA guidelines dictate the pricing tier structure for integrated food ingredients, particularly for clean-label formulations in Europe. Contract-based long-term offtake agreements dominate, driven by customization level and specific certification grades like Non-GMO Project Verified. Input cost volatility for raw materials, such as hydrocolloids, generates margin pressure across the value chain. Private Label Producers exhibit high price sensitivity, while Nutraceutical Companies prioritize functional performance over cost.
Supply Chain Analysis
Strategic stockpiles are critical for novel integrated ingredients, mitigating risks from regulatory approval lead times and specialized sourcing. Supply concentrates in China for manufacturing, with India serving as a crucial hub for hydrocolloids. The industry relies on plant-based proteins and natural high-intensity sweeteners as key inputs. Regulatory divergence between the US FDA and China's GB standards presents a structural supply chain risk, impacting both direct sales for co-developed solutions and broad-reach distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The integrated food ingredient market is at a platform-economics inflection point, driven by the emergence of AI-powered formulation ecosystems. These systems enable rapid discovery and optimization of synergistic ingredient combinations.
For Market Incumbents:Secure transparent sourcing for all clean-label raw materials, mitigating risks from input cost volatility and ensuring regulatory compliance. Invest in precision fermentation technologies to overcome the technical functionality gaps of established synthetic ingredients. Expand R&D into cellular agriculture to address future protein demand and diversify portfolio. Prioritize Non-GMO Project Verified certification for multi-component blends.
For New Entrants and Emerging Players:Certification fast-tracks, such as rapid organic approval processes, enable quicker market entry for novel clean-label ingredients. Target the Southeast Asian beverage market with customized fortification blends that address local nutritional needs. Offer co-developed, application-specific ingredient solutions to establish strong client partnerships. Focus on niche integrated systems for the nascent cellular agriculture sector.
For Investors and Strategic Acquirers:US FDA's updated nutrition labeling rules reshape the acquisition landscape, favoring companies with advanced sugar reduction technologies. Long-term viability remains strong for functional, clean-label ingredient providers over the next decade. Target specialized innovators in plant-based proteins or precision fermentation with proven application-specific expertise. The signal to watch is increased patent filings for AI-optimized ingredient blends.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Investment | Secures novel protein and enzyme sources, reducing reliance on traditional agricultural supply chains. |
| AI-Powered Formulation Platform Development | Accelerates discovery of synergistic ingredient combinations, optimizing product development for manufacturers. |
| Clean-Label Certification Expansion | Substantiates transparency claims, meeting stringent regulatory requirements from EFSA and FDA. |
| Southeast Asia Market Entry | Taps into beverage sector growth, addressing regional nutritional needs and flavor preferences. |
| Cellular Agriculture Partnership | Establishes early mover advantage in cultivated meat and dairy alternative ingredient systems. |
Research Approach
Cross-validation between primary interviews and extensive secondary validation anchors the qualitative findings of this study. Researchers engaged food scientists, R&D directors, procurement leads, and regulatory affairs specialists across key regions. Secondary data encompassed regulatory filings from the US FDA, EFSA, and China's GB standards, alongside company annual reports and trade association publications. A rigorous bottom-up and top-down triangulation process ensured data accuracy.
Sensitivity analysis informed the quantitative modeling framework used to project market trajectories across the analysis window. The model segmented data by product type, application, end-user, and specific ingredient functionality like sugar reduction. Compound annual growth rates were derived from historical trends, validated against projected market dynamics. Key forecast inputs included raw material price indices and anticipated regulatory policy changes.
Decision-makers should treat outputs as directional under current regulatory frameworks and prevailing consumer demand patterns; material deviation would warrant model refresh. Unforeseen technological breakthroughs or significant shifts in global trade policies represent key risk factors. Revision becomes warranted when major regulatory bodies introduce entirely new ingredient approval pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
North America Feed Additives Market