
 Tea Processing Equipment Market | 2026-2036
Tea Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Processing Equipment Market Analytics
Aftermarket service revenue is tilting from spare parts supply toward predictive maintenance contracts and remote calibration services. GEA Group AG leverages its refrigeration and heat exchange expertise to anchor premium retrofit programs across South Asian tea estates. Bühler Group sustains competitive positioning through integrated process control platforms that span withering through final sorting. Marshall Fowler Engineers specializes in compact, modular drying systems designed for East African cooperative scale.
Tea processing equipment encompasses mechanical and thermal systems engineered to transform fresh Camellia sinensis leaves into finished tea through controlled moisture reduction, cell rupture, enzymatic oxidation, and final desiccation to 3-6% moisture content. These systems perform the sequential operations of withering, rolling, fermenting, drying, and grading that determine liquor color, aroma intensity, and leaf appearance for commercial sale. Drying ovens and fermentation chambers command the dominant share of capital expenditure due to their thermal energy intensity and direct impact on cup quality consistency. Mechanical processing technology leads installed capacity globally, though solar drying installations are gaining traction among small scale producers seeking to reduce grid dependency and fuel costs in remote growing regions.
Food safety regulators including the FDA, EFSA, and FSSAI enforce maximum residue limits and hygienic design standards that directly shape equipment material specifications and clean-in-place system requirements for export-oriented tea manufacturers. The EU F-Gas Regulation and REACH chemical restrictions are accelerating replacement of conventional refrigerant-based withering systems with ammonia and CO2 heat pump alternatives in European-serving supply chains. Stakeholders must monitor evolving carbon border adjustment mechanisms and energy labeling schemes that will increasingly determine market access for processed tea and the equipment that produces it.
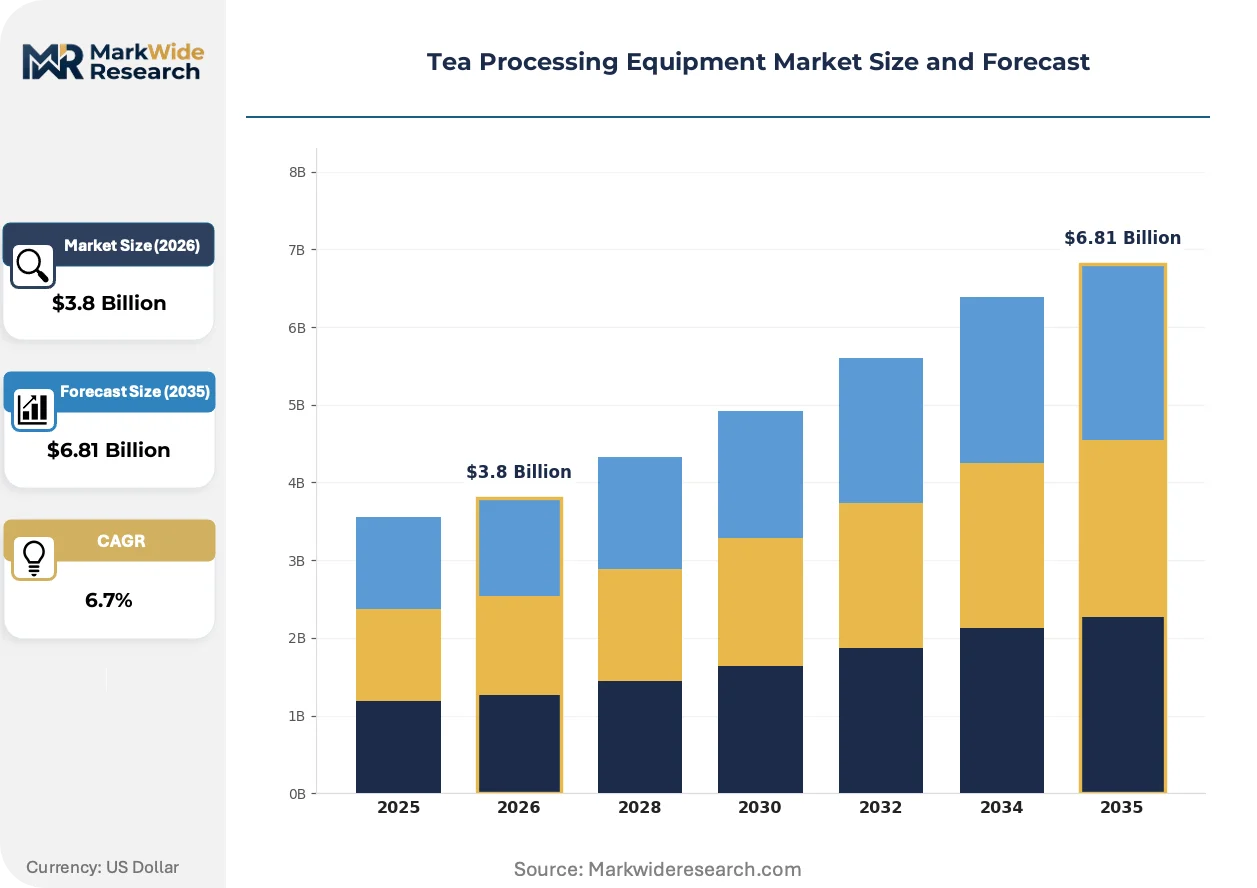
Market Dynamics
EU F-Gas Regulation compliance deadlines are forcing specialty tea manufacturers in Japan and Kenya to retire conventional refrigerant-based withering systems and install ammonia heat pump alternatives, compressing replacement cycles and reshaping vendor selection criteria toward thermal engineering expertise.
Growth Catalysts
- EU Ecodesign energy efficiency mandates:Export-oriented processors in Kenya and Sri Lanka must upgrade drying ovens to meet thermal performance thresholds, pulling demand for precision-controlled fermentation chambers.
- Solar drying adoption:Small-scale producers in remote Indian growing regions deploy photovoltaic thermal arrays to eliminate grid dependency and diesel generator costs.
- East African cooperative mechanization:Manual withering operations in Uganda and Tanzania transition to mechanical systems to achieve cup quality consistency required by European importers.
Market Restraints
- Stainless steel price volatility:Fermentation chamber and drying oven fabrication depends on grade 304 and 316 alloy inputs, exposing capital budgets to commodity swings.
- Specialized thermal engineering talent scarcity:Ammonia heat pump and CO2 transcritical system design requires skills concentrated in European and Japanese equipment vendors.
- Legacy refrigerant phase-out timelines:The EU F-Gas Regulation mandates staged reductions in HFC refrigerant availability, stranding existing withering system investments before full depreciation.
Strategic Opportunities
- Remote calibration service contracts:Precision fermentation control systems enable vendors to monetize ongoing sensor optimization rather than one-time hardware sales.
- Modular drying system deployment:Compact, containerized units address capital constraints of Rwandan and Burundian cooperatives unable to finance centralized processing infrastructure.
- India PLI scheme alignment:Domestic equipment manufacturers qualify for production-linked incentives by achieving specified local value addition in thermal processing components.
Industry Challenges
- Clean-in-place system integration:FDA and FSSAI residue limit enforcement requires retrofitting existing fermentation chambers with automated CIP circuits, disrupting production schedules.
- Cross-border carbon border adjustment readiness:European CBAM pilot phases demand documented energy intensity data that legacy mechanical processing lines cannot generate without sensor upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Processing Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Withering Trough, Rolling Machine, Fermentation Chamber, Drying Oven End User: Tea Manufacturers, Small Scale Producers, Cooperative Societies, Exporters Technology: Mechanical Processing, Electrical Processing, Solar Drying, Manual Processing Service Type: Installation, Maintenance, Training, Consulting |
| Companies Covered | Steelsworth Limited, Hongda Machinery, GEA Group AG, Keya Tea Processing Machines, Hunan Sunshine Machinery, Bühler Group, Fasco Industries, Marshall Fowler Engineers, thyssenkrupp Industrial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Processing Equipment Market Evolving Landscape
Predictive maintenance platforms and precision fermentation control systems are compressing the traditional equipment replacement cycle while unbundling aftermarket revenue from spare parts toward continuous optimization services.
Machine learning-based moisture prediction algorithms integrated into rolling and withering control systems are rendering obsolete manual sampling protocols that introduced batch-to-batch variation. Specialty orthodox tea manufacturers in Darjeeling and Uva districts deploy these sensors to achieve the tight moisture bands required for premium grade certification. The technology is rendering obsolete the role of experienced floor supervisors who previously relied on tactile assessment.
The EU F-Gas Regulation and REACH chemical restrictions are accelerating refrigerant transition timelines across European-serving supply chains. Conventional HFC-based withering systems face accelerated obsolescence as ammonia and CO2 heat pump alternatives achieve cost parity at scale. Kenyan and Japanese processors serving EU markets are prioritizing vendors with demonstrated transcritical CO2 project execution.
Aftermarket service unbundling is separating hardware procurement from ongoing optimization contracts. Large South Asian tea estates now specify remote calibration and predictive maintenance clauses in initial equipment tenders, displacing traditional break-fix service relationships. This shift is most visible in Assam and Kerala operations where estate managers prioritize uptime guarantees over capital expenditure minimization.
Tea Processing Equipment Market Segmentation
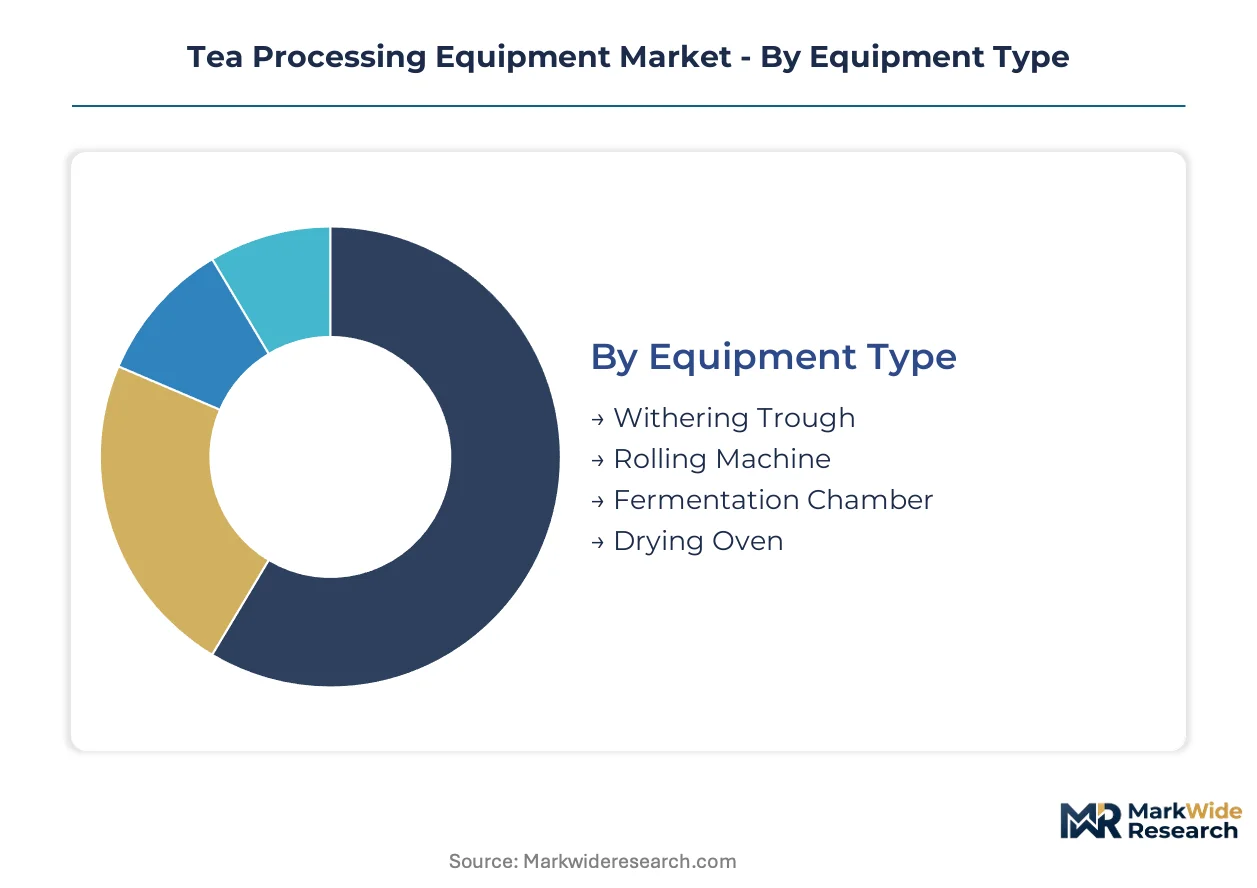
Equipment replacement cycles in tea processing vary dramatically by thermal intensity and regulatory exposure, creating distinct investment rhythms across segment categories. Procurement patterns diverge between export-oriented estates facing EU F-Gas deadlines and domestic-market cooperatives prioritizing capital efficiency over compliance speed.
Equipment Type:
Cycle times compress sharply for thermally intensive systems facing refrigerant phase-outs, while mechanical equipment enjoys longer depreciation schedules. Drying ovens and fermentation chambers turn over fastest due to energy efficiency mandates, whereas rolling machines and withering troughs persist through multiple technology generations.
- Drying Oven:Thermal energy intensity drives 40-60% of capital expenditure in new plant construction, with precision moisture control systems commanding premium positioning. Kenyan and Sri Lankan export processors dominate replacement demand as EU Ecodesign thresholds force retirement of conventional gas-fired units before full depreciation.
- Fermentation Chamber:Controlled enzymatic oxidation environments require hygienic design compliance with FDA and FSSAI residue limits, elevating stainless steel specification grades and clean-in-place integration costs. Japanese specialty orthodox manufacturers anchor demand for ammonia heat pump alternatives to meet F-Gas Regulation timelines.
- Withering Trough:Moisture reduction systems range from ambient-air natural convection to forced-air mechanical configurations, with East African cooperatives upgrading from manual spreading beds to accelerate throughput consistency.
- Rolling Machine:Cell rupture equipment varies from orthodox rotary styles to CTC (crush-tear-curl) configurations optimized for bagged tea volume production, with Indian estates representing the largest installed base globally.
Drying ovens dominate installed base by capital value. Fermentation chambers are where expansion concentrates as precision control becomes a competitive differentiator for premium grade certification.
End User:
Procurement authority clusters differently across customer types, with export-facing entities prioritizing compliance speed over capital minimization. Volume concentration sits with large manufacturers, though cooperative societies represent the steepest expansion trajectory as mechanization spreads through East African smallholder supply chains.
- Tea Manufacturers:Integrated processing estates in Assam and Kerala deploy full-line automation spanning withering through final sorting, specifying predictive maintenance contracts upfront to guarantee uptime for just-in-time export schedules.
- Cooperative Societies:Capital constraints in Rwanda and Burundi drive preference for containerized modular systems that eliminate centralized infrastructure requirements, with GEA Group and Marshall Fowler Engineers competing on deployment speed and local service reach.
- Small Scale Producers:Remote Indian growing regions deploy photovoltaic thermal arrays to eliminate grid dependency, with solar drying installations gaining traction where diesel generator costs erode margin sustainability.
- Exporters:EU-serving supply chains in Kenya and Japan face compressed replacement cycles as carbon border adjustment mechanisms demand documented energy intensity data that legacy equipment cannot generate.
Tea manufacturers dominate installed base by throughput volume. Cooperative societies are expanding most quickly as donor financing and development agency programs accelerate mechanization timelines.
Technology:
Technology selection hinges on grid reliability, fuel access, and regulatory exposure rather than pure efficiency optimization. Mechanical processing retains volume leadership while solar alternatives capture remote deployment opportunities where infrastructure gaps persist.
- Mechanical Processing:Motor-driven rolling, withering, and sorting systems constitute the dominant installed capacity globally, with Assam and Dooars estates representing concentrated demand for integrated process control platforms that span sequential operations.
- Solar Drying:Photovoltaic thermal arrays eliminate diesel generator dependency for small-scale producers in remote Nilgiri and Kangra growing regions, though throughput constraints limit applicability to specialty orthodox production where batch times are less critical.
- Electrical Processing:Precision-controlled fermentation chambers and infrared drying systems serve premium grade manufacturers in Darjeeling and Uva districts requiring tight moisture bands for certification compliance.
- Manual Processing:Labor-intensive spreading and rolling persists in heritage orthodox operations and some East African smallholder contexts, though quality inconsistency drives gradual mechanization wherever capital access permits.
Mechanical processing dominates installed base. Solar drying is where expansion concentrates as photovoltaic cost curves improve rural deployment economics.
Service Type:
Revenue unbundling is separating hardware procurement from ongoing optimization, with estates prioritizing uptime guarantees over break-fix relationships. Service mix varies by customer sophistication, with large manufacturers specifying remote calibration clauses in initial tenders while cooperatives rely on installation and basic maintenance packages.
- Maintenance:Predictive maintenance contracts and remote sensor optimization are displacing traditional spare parts revenue, with South Asian estates specifying continuous calibration services to achieve batch-to-batch consistency for premium grade certification.
- Installation:Modular system deployment in East African cooperatives requires rapid commissioning capabilities to minimize harvest season disruption, with vendor selection criteria weighting local technician availability.
- Training:Machine learning-based moisture prediction algorithms are rendering obsolete manual sampling protocols, creating demand for operator retraining on sensor-driven control interfaces that displace experienced floor supervisors.
- Consulting:Carbon border adjustment readiness and F-Gas Regulation compliance planning drive advisory demand among EU-serving exporters in Kenya and Japan seeking to document energy intensity and refrigerant transition timelines.
Maintenance dominates service revenue by contract value. Training is where expansion concentrates as technology turnover accelerates skill obsolescence across the operator workforce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Export-facing estates absorb premium equipment costs for compliance, while domestic-market cooperatives prioritize capital efficiency over feature depth.
Kenya
Specialty orthodox manufacturers anchor East African demand for ammonia heat pump withering systems. The EU F-Gas Regulation compresses replacement cycles for processors serving European importers. Nandi Hills and Kericho estates deploy precision fermentation chambers to document energy intensity data required by emerging carbon border adjustment mechanisms.
India
Integrated Assam and Kerala estates specify full-line automation with predictive maintenance contracts upfront. The FSSAI enforces hygienic design standards that elevate stainless steel specifications for fermentation chamber fabrication. Dooars and Nilgiri clusters accelerate solar drying adoption among small-scale producers seeking to eliminate diesel generator dependency.
Japan
Specialty tea manufacturers prioritize transcritical CO2 heat pump alternatives to meet EU Ecodesign and REACH chemical restrictions. METI efficiency guidelines reinforce thermal performance thresholds for export-oriented processors. Shizuoka prefecture estates anchor demand for precision-controlled fermentation systems achieving tight moisture bands for premium grade certification.
Sri Lanka
Uva and Dimbula district processors upgrade drying ovens to satisfy EU Ecodesign thermal performance mandates. The national export development authority channels financing toward mechanization programs for cooperative societies. Colombo-based equipment distributors compete on local service reach and rapid commissioning capabilities during harvest windows.
Rwanda
Cooperative societies drive demand for containerized modular drying systems that eliminate centralized infrastructure requirements. Development agency programs accelerate mechanization timelines for smallholder supply chains. Kigali corridor processors prioritize deployment speed and capital efficiency over advanced automation features.
Tea Processing Equipment Market Competitive Landscape
Capability concentration sits with thermal engineering specialists; scale advantage sits with diversified process equipment conglomerates. The vendor base separates into three tiers: refrigeration and heat exchange experts, integrated process control platform providers, and compact modular system fabricators. Strategic moves center on aftermarket service unbundling and rapid deployment capabilities for cooperative-scale customers.
Within the thermal engineering tier, GEA Group AG and thyssenkrupp Industrial Solutions occupy positions anchored by refrigeration expertise applied to withering and drying applications. Bühler Group exemplifies the integrated platform archetype spanning sequential operations from withering through final sorting. Marshall Fowler Engineers and Keya Tea Processing Machines represent the compact modular specialization, targeting East African cooperative capital constraints with containerized deployment models.
| Leading Market Players |
|---|
| Steelsworth Limited |
| Hongda Machinery |
| GEA Group AG |
| Keya Tea Processing Machines |
| Hunan Sunshine Machinery |
| Bühler Group |
| Fasco Industries |
| Marshall Fowler Engineers |
| thyssenkrupp Industrial Solutions |
| Others |
Value Network & Pricing Analysis
Assam and Kerala processing clusters anchor thermal equipment fabrication capacity, concentrating stainless steel procurement leverage among integrated estates serving EU export channels. Their scale advantages compress per-unit capital costs for precision fermentation chambers while elevating barriers for cooperative-scale buyers in East African markets.
Pricing Analysis
Predictive maintenance contracts and remote calibration services drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates ammonia heat pump systems from conventional gas-fired units from basic mechanical configurations. Pricing pressure stems from stainless steel alloy volatility and specialized thermal engineering talent scarcity. Cooperative societies in Rwanda and Burundi exhibit highest price sensitivity, while Japanese specialty orthodox manufacturers absorb premiums for F-Gas Regulation compliance.
Supply Chain Analysis
Tariff exposure between India and European Union markets dominates supply chain risk planning for export-oriented equipment vendors. Fabrication capacity concentrates in India, China, and Germany, with grade 304 and 316 stainless steel, precision sensors, and refrigeration compressors as critical inputs. Single-source vulnerability persists for transcritical CO2 heat pump components. Distribution runs through Colombo-based distributors for Sri Lankan estates and direct vendor relationships for large South Asian integrated processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in cooperative-scale modular systems as donor financing accelerates East African mechanization timelines beyond consolidated vendor service reach.
For Market Incumbents: Insulate service revenue through predictive maintenance contract anchoring in initial tenders, displacing break-fix relationships. Deepen backward integration into precision sensor calibration capabilities to capture remote optimization value. Counter emerging modular specialists by accelerating containerized deployment speed for Rwandan and Burundian cooperatives. For New Entrants and Emerging Players: Rwandan cooperative societies offer the most penetrable white-space as development agency financing outpaces established vendor local service reach. Target solar-thermal hybrid configurations for remote Indian growing regions where grid unreliability creates specification gaps. Lead with rapid commissioning capabilities during narrow harvest windows as primary go-to-market wedge. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because carbon border adjustment mechanisms and refrigerant phase-out timelines compress replacement cycles independent of pure efficiency economics. Acquisition target archetype: compact modular system fabricators with demonstrated East African deployment track records. Watch EU F-Gas Regulation enforcement intensity as inflection indicator for ammonia heat pump demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Anchoring | GEA Group and Bühler Group monetize ongoing sensor optimization rather than one-time hardware sales. |
| Modular System Deployment Acceleration | Marshall Fowler Engineers addresses capital constraints of Rwandan cooperatives unable to finance centralized infrastructure. |
| Refrigerant Transition Engineering Investment | thyssenkrupp Industrial Solutions captures F-Gas Regulation-driven replacement demand in Kenya and Japan. |
| Solar-Thermal Hybrid Development | Remote Nilgiri and Kangra producers eliminate diesel generator dependency through photovoltaic thermal arrays. |
| Clean-in-Place System Integration | FDA and FSSAI residue limit enforcement requires retrofitting fermentation chambers with automated CIP circuits. |
Research Methodology
Operator-level perspectives from estate managers, cooperative procurement officers, thermal engineering specialists, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, SEC equipment vendor filings, FAO tea production statistics, and EU regulatory implementation notices. Bottom-up installation tracking across Assam, Kerala, Kericho, and Shizuoka clusters triangulated against top-down capital expenditure estimates from national export development authorities.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific milestones. Segmentation dimensions modeled include equipment type thermal intensity, end-user procurement authority concentration, technology grid dependency, and service type revenue unbundling maturity. CAGRs derived from equipment replacement cycle compression rates and regulatory deadline acceleration effects. Forecast inputs incorporated EU F-Gas Regulation phase-out schedules and India PLI scheme local value addition thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese equipment fabricators or accelerated donor financing scale-up in East Africa would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Industrial Fryers Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Automatic Liquid Dispenser Machine Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Butcher Equipment Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Small Continuous Fryer Market
Food Processing Equipment
Brewing Boiler Market