
 Small Brewery Equipment Market | 2026-2036
Small Brewery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Small Brewery Equipment Market Analytics
A shortage of certified brewing technicians is unwinding capacity expansion plans across the craft beer sector. Krones AG leverages its German engineering heritage to dominate stainless steel fabrication for brewhouses. GEA Group sustains competitive positioning through captive supply of heat exchanger technology. Alfa Laval anchors its presence in North America with specialized centrifugal separation systems for small-batch clarification.
Small brewery equipment encompasses vessels, controls, and auxiliary systems engineered to produce beer in batches typically ranging from one to thirty barrels, with pressure-rated fermentation tanks operating at precise temperature bands to manage yeast metabolism and flavor compound development. Fermentation tanks command the deepest margin pools due to alloy thickness requirements and cooling jacket complexity, while automated systems are capturing share from traditional methods as labor costs escalate. Modular solutions are expanding fastest among urban taprooms where floor space constraints limit linear production layouts.
The FDA enforces Current Good Manufacturing Practice regulations that mandate clean-in-place protocols and material traceability for all food-contact surfaces in brewing equipment. OSHA inspects brewhouse steam systems and confined-space entry procedures, while the EPA regulates wastewater discharge from cleaning cycles under Clean Water Act permits. Stakeholders must weigh capital allocation between all-in-one system simplicity and component-level upgrade flexibility as distribution models shift toward direct-to-consumer canning lines.
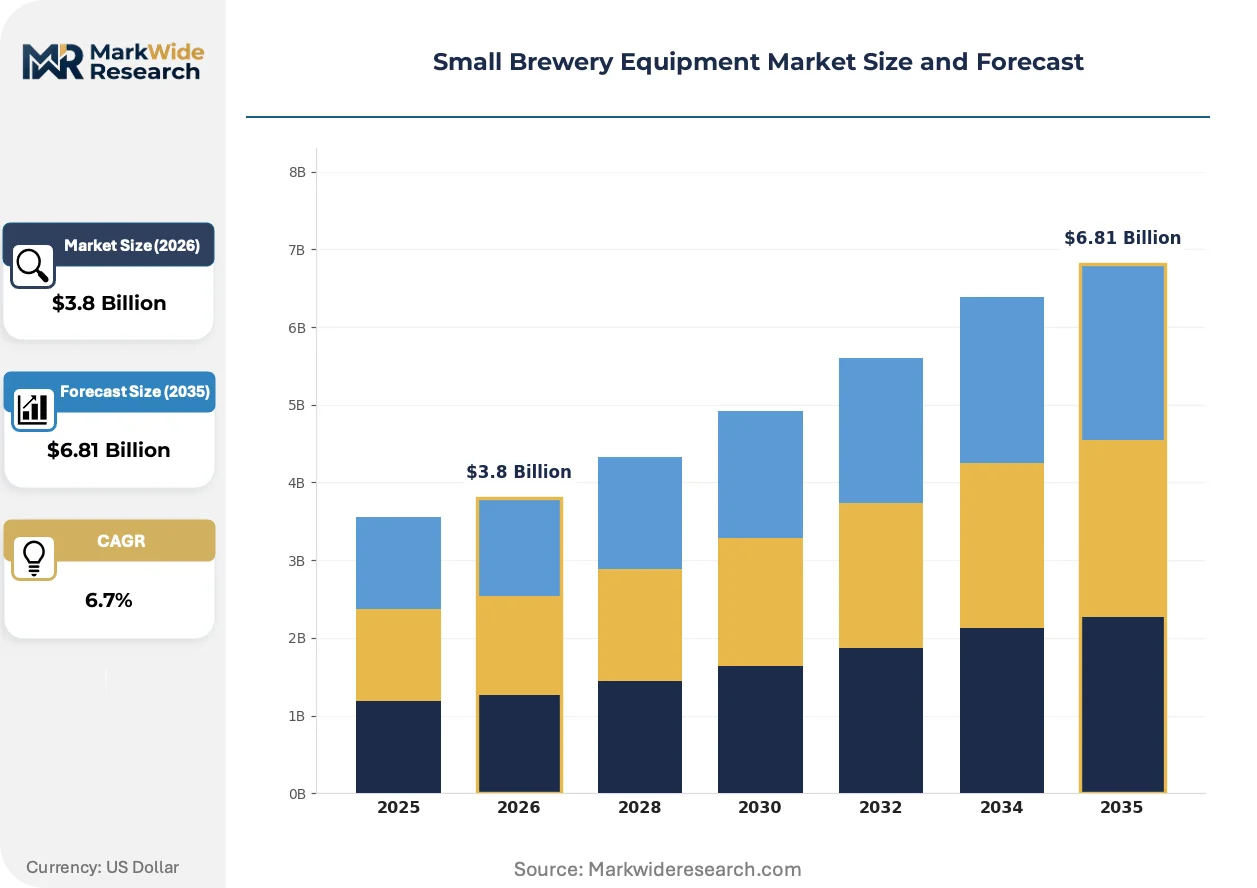
Market Dynamics
The Small Brewery Equipment Market pivots on the tension between taproom operators demanding rapid recipe rotation and the capital intensity of stainless steel fabrication. Modular fermentation systems are compressing brewhouse footprints while automated controls reduce dependency on scarce certified technicians.
Growth Catalysts
- Taproom Expansion in Urban Clusters:Microbreweries in Portland, Oregon and Denver, Colorado are scaling production capacity to meet direct-to-consumer demand. These operators prioritize equipment that supports seasonal portfolio rotation.
- Clean-in-Place Mandates:The FDA's Food Safety Modernization Act enforces Current Good Manufacturing Practice protocols. Brewers must upgrade to automated sanitation systems to maintain compliance.
- Alloy Fabrication Advances:Heat exchanger integration and cooling jacket complexity in fermentation tanks now enable precise temperature band control. This supports yeast metabolism management for flavor compound development.
Market Restraints
- Certified Technician Scarcity:A shortage of qualified brewing technicians is unwinding capacity expansion plans across the craft beer sector. Equipment utilization rates suffer when specialized labor is unavailable.
- Stainless Steel Input Concentration:German engineering heritage dominates premium brewhouse fabrication. Supply bottlenecks emerge when regional mill capacity tightens.
- Wastewater Discharge Permitting:The EPA regulates cleaning cycle effluent under Clean Water Act permits. Small operators face compliance costs that scale disproportionately with batch volume.
Strategic Opportunities
- Direct-to-Consumer Canning Lines:Distribution model shifts toward on-site packaging create demand for compact filling and seaming equipment. Taprooms in Colorado are retrofitting production floors to capture margin.
- Modular System Architecture:Urban floor space constraints favor non-linear production layouts. Vessel stacking and skid-mounted brewhouses open locations previously excluded by real estate costs.
- State-Level Alcohol Beverage Control Modernization:Relaxed self-distribution thresholds in select jurisdictions reduce barrier to entry. Equipment financing aligns with licensing timeline acceleration.
Industry Challenges
- Confined-Space Entry Certification:OSHA inspects brewhouse steam systems and tank entry procedures. Operators must maintain documented training protocols that extend equipment downtime.
- Material Traceability Documentation:FDA mandates lot tracking for all food-contact surfaces. Legacy record-keeping systems require expensive retrofit to meet audit standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Brewery Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Brew Kettles, Fermentation Tanks, Kegs, Bottling Machines Production Capacity: Micro Scale, Small Scale, Medium Scale, Large Scale Brewing Technology: All-In-One Systems, Traditional Methods, Automated Systems, Modular Solutions Application: Craft Beer, Specialty Ales, Lagers, Seasonal Brews |
| Companies Covered | Krones AG, GEA Group, Alfa Laval, Paul Mueller Company, Della Toffola, Meura, Praj Industries, PicoBrew, Criveller Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Brewery Equipment Market Evolving Landscape
Automation and modularity are restructuring how small breweries configure capital deployment. Equipment buyers now prioritize upgrade pathways over monolithic system purchases.
Automated brewing controls are displacing manual valve trees and gravity-fed operations in taprooms with limited staff. Urban operators in Portland are adopting touchscreen-driven mash schedules that reduce batch-to-batch variability. This compression of labor dependency is enabling smaller teams to manage expanded production schedules.
The FDA's Food Safety Modernization Act is tightening material traceability requirements for all food-contact surfaces. Brewers must now document alloy composition and welding certification for every fermentation vessel. Small-batch operators are responding by specifying equipment from fabricators with pre-validated quality systems.
Urban real estate economics are compressing equipment footprints as taprooms prioritize customer-facing square footage. Skid-mounted brewhouses and vertical tank configurations are replacing traditional linear production lines in Denver. This spatial optimization is visible in retrofit installations where brewing occupies basements or secondary structures.
Small Brewery Equipment Market Segmentation
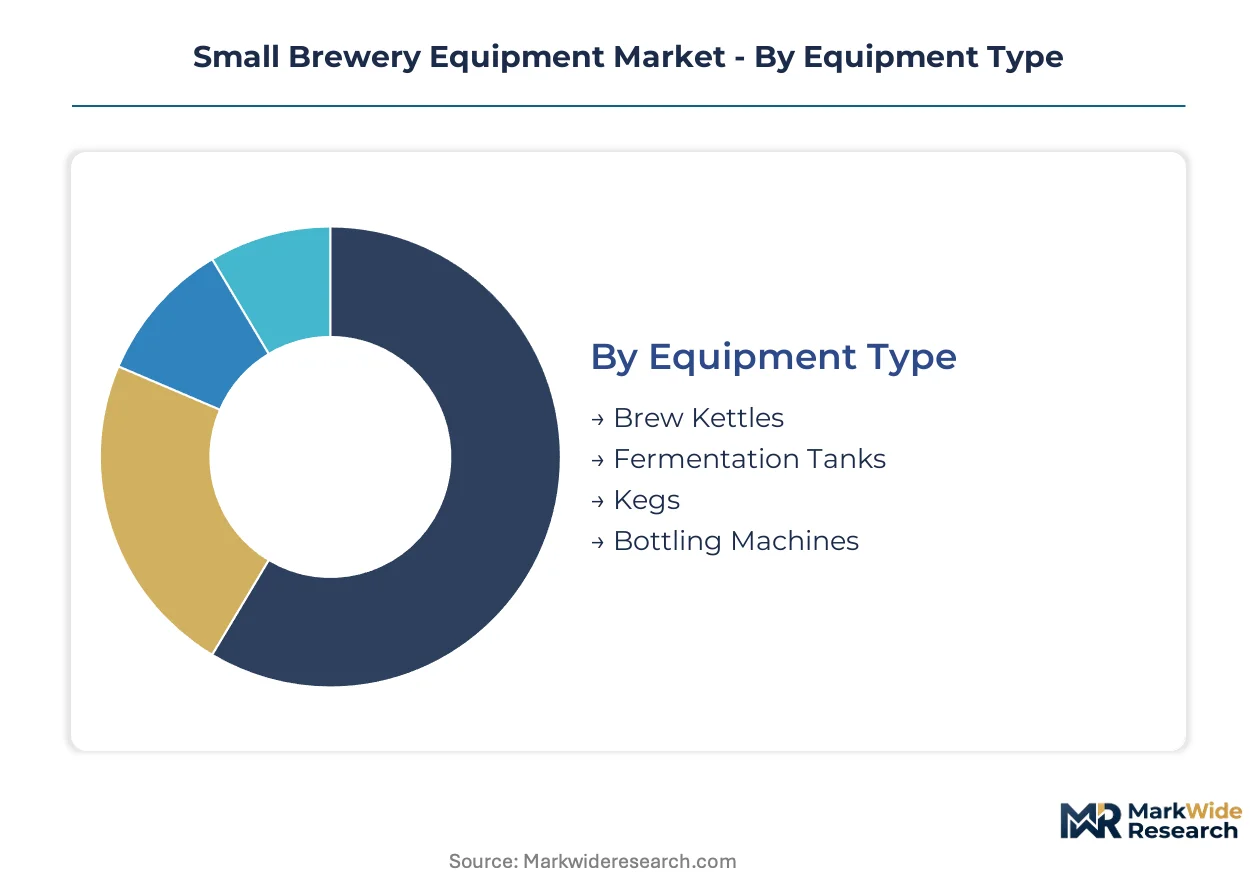
Equipment segmentation in the small brewery market determines capital deployment patterns, regulatory compliance pathways, and operational flexibility. Buyers prioritize segments that balance batch consistency with recipe rotation capability.
Equipment Type:
Domestic fabrication dominates brew kettles and kegs, while fermentation tanks and bottling machines draw significant import flows from German and Italian engineering centers.
- Brew Kettles:Vessels engineered for wort boiling with precise temperature ramp control and steam jacket integration. Taproom operators in Portland specify compact single-vessel designs to preserve customer-facing floor space amid real estate cost escalation.
- Fermentation Tanks:Pressure-rated vessels with cooling jacket complexity and alloy thickness specifications that manage yeast metabolism across precise temperature bands. Demand concentrates in Denver's expanding microbrewery cluster where seasonal recipe rotation requires rapid tank turnaround.
- Kegs:Stainless steel containers for draft distribution with standardized Sankey valve configurations. Direct-to-consumer taprooms drive stainless sourcing from domestic metal fabricators.
- Bottling Machines:Counter-pressure filling systems for small-batch packaging with seaming and labeling integration. Urban retrofit installations favor compact linear designs over rotary configurations.
Fermentation tanks hold the largest share; momentum sits with bottling machines as direct-to-consumer distribution accelerates.
Production Capacity:
Cost tier stratification separates entry-level micro operators from capital-intensive medium-scale facilities with integrated canning lines.
- Micro Scale:Systems producing under five barrels per batch, typically occupying taproom basements or secondary structures. OSHA confined-space entry requirements complicate tank maintenance in these footprint-constrained installations.
- Small Scale:Five-to-fifteen barrel configurations serving regional distribution with manual or semi-automated controls. FDA material traceability mandates drive specification of certified fabricators over generic metalwork suppliers.
- Medium Scale:Fifteen-to-thirty barrel systems with automated clean-in-place protocols and heat exchanger integration. These configurations anchor the deepest margin pools due to alloy specifications and cooling complexity.
- Large Scale:Thirty-plus barrel installations approaching regional production brewery thresholds with full automation and wastewater treatment integration. EPA Clean Water Act permitting costs scale disproportionately at this tier.
Small scale holds the largest share; medium scale is climbing the fastest as taproom operators expand into self-distribution.
Brewing Technology:
Application intensity varies by labor availability, with automated systems displacing traditional methods where certified technician scarcity bites hardest.
- All-In-One Systems:Integrated vessels combining mash, lauter, and boil functions in single footprints. Entry-level operators in Colorado favor these for licensing timeline acceleration and reduced installation complexity.
- Traditional Methods:Gravity-fed operations with manual valve trees requiring skilled labor for batch-to-batch consistency. Veteran brewers maintain these configurations for recipe development flexibility despite labor dependency.
- Automated Systems:Touchscreen-driven mash schedules with programmable temperature ramps and remote monitoring capability. Portland taprooms adopt these to compress staffing requirements across expanded production schedules.
- Modular Solutions:Skid-mounted vessels and vertical tank configurations enabling non-linear production layouts. Urban real estate economics in Denver drive specification of stackable fermentation systems.
Automated systems hold the largest share; modular solutions are gaining share fastest as floor space constraints intensify.
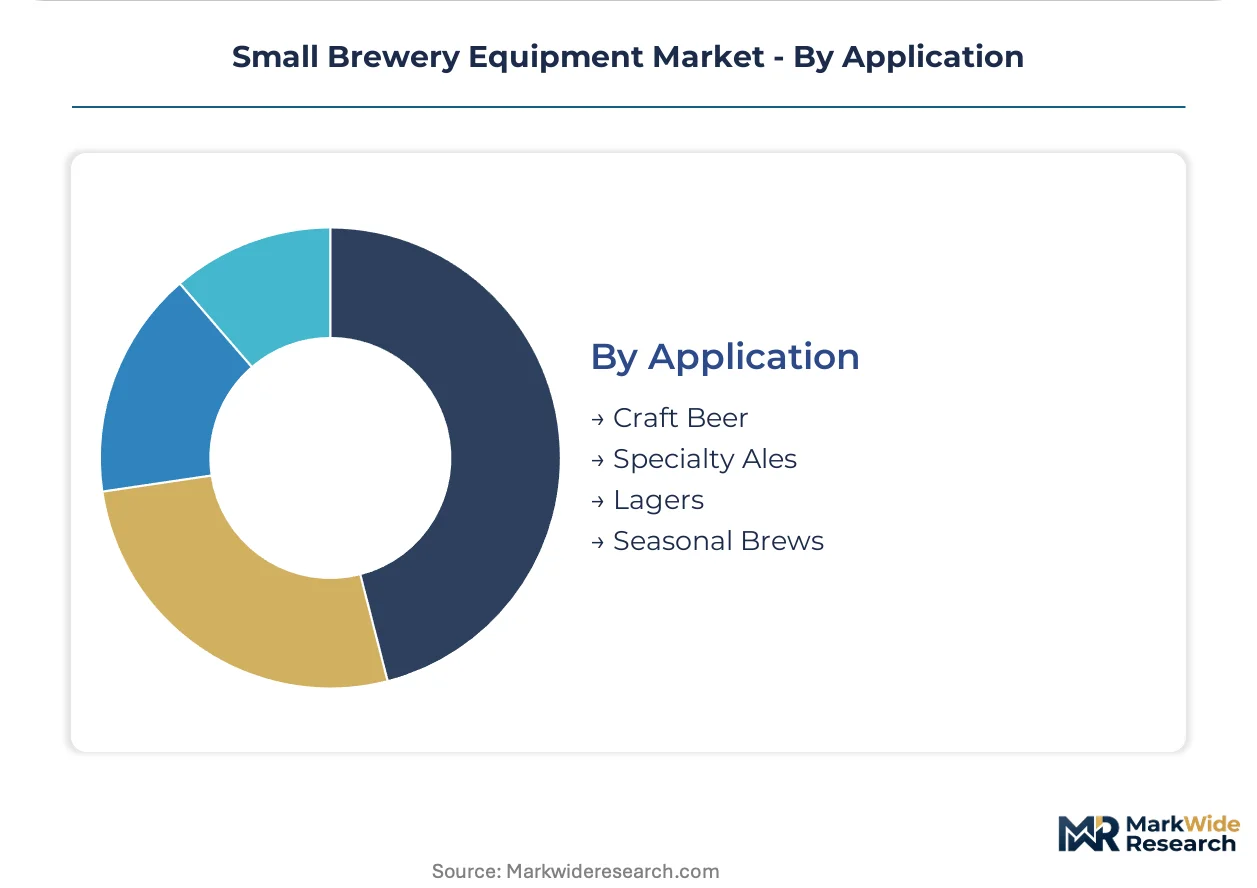
Application:
Customer type differentiation separates year-round portfolio staples from rotating seasonal releases that demand tank flexibility.
- Craft Beer:Broad category encompassing hop-forward ales and experimental recipes with variable fermentation profiles. This segment anchors equipment specification for temperature band precision.
- Specialty Ales:High-gravity and barrel-aged variants requiring extended fermentation timelines and oak adjunct handling. These applications drive demand for secondary conditioning vessels.
- Lagers:Cold-fermented styles demanding precise temperature control near freezing and extended maturation periods. Cooling jacket specification intensifies for these applications.
- Seasonal Brews:Limited-release recipes with compressed production windows and rapid tank turnaround requirements. Taproom operators prioritize modular fermentation capacity to support this portfolio strategy.
Craft beer holds the largest share; seasonal brews are expanding most quickly as taproom differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of Current Good Manufacturing Practice protocols anchors demand patterns in the United States, while German engineering heritage shapes supply-side concentration across European markets. Equipment specification varies sharply by local regulatory intensity and taproom licensing frameworks.
United States
Taproom operators in Portland and Denver are scaling fermentation capacity to capture direct-to-consumer margins. The FDA's Food Safety Modernization Act mandates automated clean-in-place documentation for all food-contact surfaces. Oregon's alcohol beverage control modernization accelerates equipment financing timelines for urban microbreweries.
Germany
Bavarian fabricators supply premium brewhouse vessels with pre-validated welding certification for export markets. REACH compliance requirements govern alloy composition disclosure for stainless steel fermentation tanks. Munich-area engineering clusters concentrate heat exchanger integration expertise for precise temperature band control.
Canada
Ontario craft brewers are retrofitting basement installations with skid-mounted brewhouses to maximize customer-facing floor space. Health Canada enforces material traceability for food-contact surfaces under Food and Drug Regulations. Toronto's urban core sees vertical tank stacking configurations displace traditional linear production layouts.
United Kingdom
London taprooms prioritize modular fermentation systems enabling rapid seasonal recipe rotation. CE marking requirements govern pressure vessel certification for brewing equipment import. The Midlands industrial corridor hosts stainless fabrication capacity serving domestic microbrewery expansion.
Australia
Victoria's craft sector is adopting touchscreen-driven mash schedules to compress staffing requirements across extended production windows. The TGA oversees material safety standards for food-contact equipment alongside state-level liquor licensing. Melbourne's inner suburbs concentrate urban retrofit installations in secondary structures and basements.
Small Brewery Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the small brewery equipment market. German engineering heritage dominates premium stainless fabrication with validated quality systems, while Asian fabricators compete on modular system cost structures. The vendor base stratifies into three archetypes: integrated process technology conglomerates, specialized brewing equipment fabricators, and automated control system developers. Competitive moves concentrate on backward integration into heat exchanger technology and geographic expansion through distributor partnerships.
Among German-based engineering conglomerates, Krones AG and GEA Group exemplify the integrated technology archetype with captive supply of critical subsystems. Alfa Laval occupies a distinct position among specialists in fluid handling and separation technology. These three anchors represent divergent strategic paths: conglomerate breadth versus component-level technical depth.
| Leading Market Players |
|---|
| Krones AG |
| GEA Group |
| Alfa Laval |
| Paul Mueller Company |
| Della Toffola |
| Meura |
| Praj Industries |
| PicoBrew |
| Criveller Group |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for German-engineered fermentation tanks compress pricing power for domestic fabricators while elevating premium tier margins. Stainless steel input volatility and certified welder scarcity tether equipment costs to mill capacity cycles, forcing buyers into longer procurement horizons.
Pricing Analysis
Domestic fabricators in the United States undercut Bavarian imports by fifteen to twenty percent on brew kettles, though fermentation tanks show narrower spreads due to cooling jacket complexity. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked German vessels from mid-tier Italian fabrications and Asian modular systems. Price differentiation centers on alloy certification grade and FDA pre-validation documentation. Cost compression in the economy tier is intensifying because Asian fabricators are scaling stainless fabrication capacity. Taproom operators with direct-to-consumer models prove least price-sensitive, prioritizing rapid installation timelines over per-unit equipment savings.
Supply Chain Analysis
Days-of-inventory for cooling jacket subassemblies stretch to sixty days when German mill capacity tightens, exposing lead-time vulnerability in peak brewing equipment procurement cycles. Supply concentrates in Germany for premium pressure vessels, Italy for bottling machinery, and China for modular skid systems. Raw material flows draw from Swedish stainless steel slab, Taiwanese control electronics, and domestic heat exchanger tubing. Single-source vulnerability concentrates in German heat exchanger integration expertise. Distribution runs through regional equipment distributors with installation service capabilities, though direct OEM relationships are displacing intermediary channels for medium-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Small brewery equipment sits in early-cycle expansion as taproom licensing accelerations in Colorado and Oregon outpace installed base saturation. Automated controls penetration remains below thirty percent among micro-scale operators, creating headroom for technology substitution.
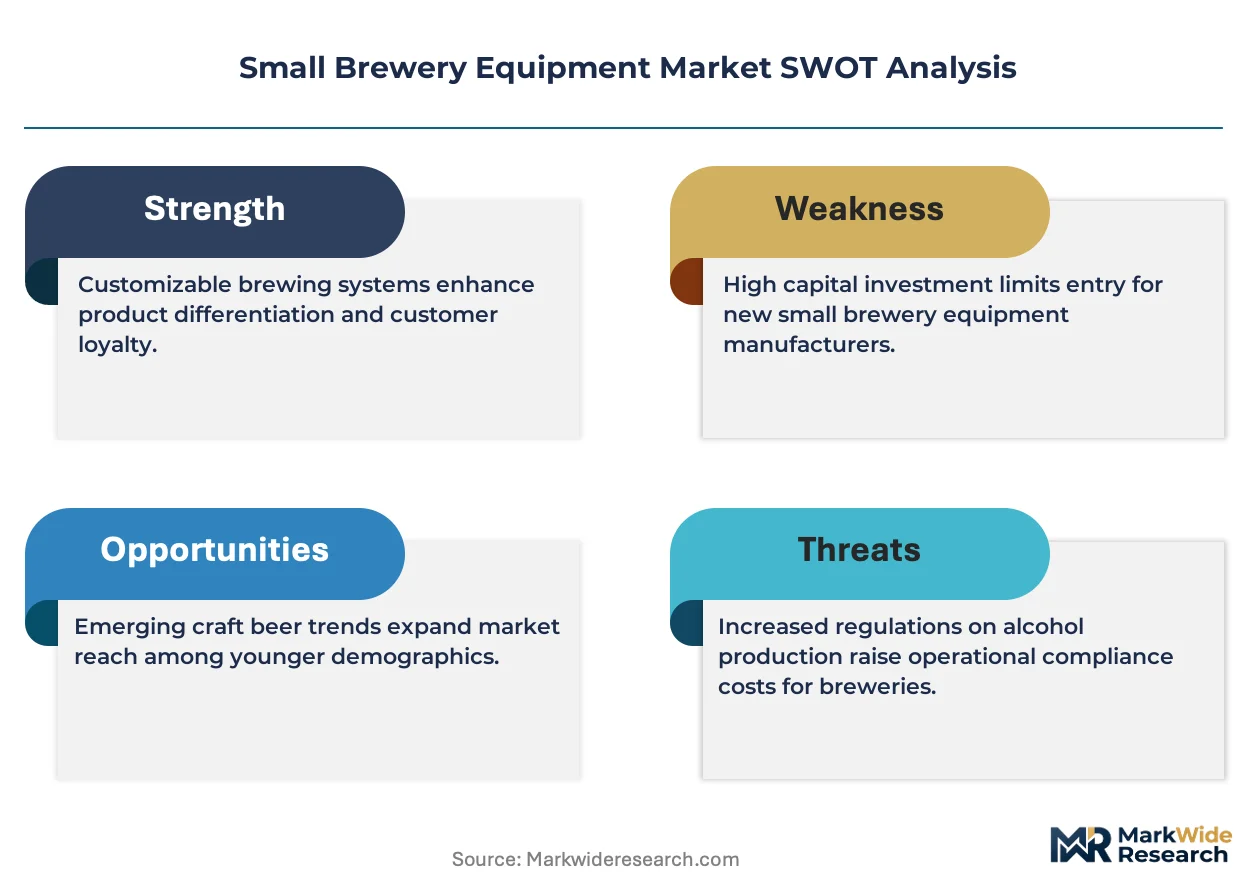
For Market Incumbents: Secure captive supply of heat exchanger technology to defend margin pools in fermentation tank fabrication. Krones AG and GEA Group already anchor this position; followers must acquire certified welding capacity or risk exclusion from FDA-pre-validated supply chains. Certification investment in FDA Food Safety Modernization Act documentation protocols represents the critical defensive lever against emerging Asian modular competitors.
For New Entrants and Emerging Players: Differentiate on rapid-deployment modular architecture targeting urban basement retrofit installations in Toronto and Melbourne. The most penetrable white-space sits in sub-five-barrel skid-mounted brewhouses with pre-integrated clean-in-place protocols. Go-to-market execution should prioritize equipment financing partnerships aligned with state-level alcohol beverage control licensing timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified process engineering conglomerates with under-monetized brewing equipment divisions. Long-term viability hinges on automation attach rates and aftermarket service contract penetration. The signal to watch is direct-to-consumer canning line retrofit velocity in Denver and Portland taprooms as an inflection indicator for capital deployment appetite.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Technology | Captive supply of cooling jacket subassemblies deepens margin pools in fermentation tank fabrication. |
| Skid-Mounted Modular System Development | Vertical tank configurations unlock urban basement installations previously excluded by footprint constraints. |
| FDA Pre-Validation Documentation Investment | Material traceability protocols align with Food Safety Modernization Act enforcement trajectories. |
| Direct-to-Consumer Canning Line Partnership | Compact filling equipment retrofits capture margin shift in Colorado self-distribution taprooms. |
| Certified Technician Training Program Launch | Addressed scarcity unwinds capacity expansion bottlenecks across craft brewery operator base. |
Research Methodology
The analysis maps fermentation tank fabrication, automated control systems, and modular brewhouse architecture, each validated through equipment procurement managers, taproom operations directors, and certified brewing technicians. Primary interviews with stainless steel fabricators, distributor sales engineers, and regulatory compliance officers combined with secondary validation from FDA enforcement records, EPA Clean Water Act permit databases, and state alcohol beverage control licensing filings. Bottom-up equipment shipment tracking and top-down taproom capacity expansion analysis provided cross-referenced triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled equipment type, production capacity tier, brewing technology intensity, and application segmentation dimensions. CAGRs were derived from installed base expansion rates and replacement cycle compression observed across the analysis window. Forecast inputs incorporated OSHA confined-space certification timelines and alloy price index movements.
Material uncertainties — tariff exposure on German vessel imports, stainless steel price volatility, and state-level licensing acceleration or retrenchment — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and taproom real estate economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ice-Cream Maker Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Deaeration Machine Market